
 Asia-Pacific Snack Bar Market | 2026-2036
Asia-Pacific Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Snack Bar Market Outlook
Premium protein specification tiers is collapsing the gap between sports nutrition and everyday snacking across the Asia-Pacific region. Nestlé S.A. leverages its dairy protein supply chain to dominate refrigerated bar distribution in Southeast Asian convenience channels. Mondelēz International, Inc. sustains mass-market penetration through its biscuit-to-bar manufacturing scale in India and Australia. Calbee, Inc. anchors Japanese consumer trust with soy-based formulations that compete directly with Western whey-dominant recipes.
A snack bar is a shelf-stable, individually wrapped baked or extruded food item typically weighing 30–60 grams, composed of cereals, proteins, sweeteners, and binders formed through cold-press or oven-bake processes, designed for portable consumption between meals. Protein bars command the highest margin pools due to ingredient complexity and sports-channel pricing power, while fruit and nut bars occupy the fastest-expanding shelf space in Chinese health food shops driven by clean-label preferences. Granola bars remain mature in Australian supermarkets where private-label competition compresses returns, though online retail across the region unlocks direct-to-consumer trials for emerging ingredient-type variants.
China's SAMR enforces GB standards on nutritional claims and additive limits, while India's FSSAI mandates quantitative ingredient declarations that raise reformulation costs for multinational entrants. Japan's Consumer Affairs Agency coordinates with METI on functional food labeling that permits specific protein and fiber claims, creating a regulatory moat for domestic manufacturers. Stakeholders must monitor how Australia's TGA and New Zealand's MPI align on novel protein approvals, as divergence would fragment R&D investment across the region.
Market Dynamics
Protein-fortification technology diffusion is collapsing the traditional boundary between sports nutrition and everyday snacking across Asia-Pacific, forcing manufacturers to reconfigure supply chains around cold-pressed extrusion capabilities and refrigerated distribution networks that were previously specialized segments.
Growth Catalysts
- FSSAI Clean-Label Mandates:India's quantitative ingredient declaration requirements accelerate reformulation toward recognizable whole-food bases, creating first-mover advantages for domestic brands with transparent sourcing.
- China's Tier-One Urbanization:Metropolitan corridors in Shanghai, Beijing, and Shenzhen concentrate purchasing power for portable nutrition formats that replace traditional breakfast or lunch occasions.
- Cold-Press Protein Stabilization:Enzyme-based binding systems now enable ambient storage of high-protein bars without whey denaturation, unlocking convenience-channel distribution previously reserved for lower-nutrition alternatives.
Market Restraints
- Palm Oil Price Volatility:Southeast Asian supply disruptions transmit directly to coating and binding cost structures, compressing margins for mid-tier manufacturers without forward-contract coverage.
- GB Standards Compliance Burden:China's SAMR enforcement of nutritional claim substantiation requires expensive clinical validation for protein-content marketing, disadvantaging smaller entrants against established players with in-house R&D facilities.
- Fresh Fruit Substitution Threat:Refrigerated fresh-cut fruit packs in Japanese and South Korean convenience chains compete directly for the same portable-nutrition occasion at lower per-unit cost.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Modern trade expansion in Ho Chi Minh City and Jakarta creates whitespace for premium-positioned entrants before local private-label consolidation.
- METI Functional Food Labeling:Japan's permitted protein and fiber claims pathway enables differentiated positioning against generic competitors, rewarding domestic manufacturing investment.
- Direct-to-Consumer Subscription Models:Online retail infrastructure across the region supports trial-sized assortment packs that bypass traditional slotting-fee barriers in brick-and-mortar retail.
Industry Challenges
- Extrusion Technician Scarcity:Cold-press and high-moisture extrusion operations require specialized food engineering skills that outpace vocational training output in India and Southeast Asia.
- Dual Certification Timelines:Simultaneous FSSAI registration and GB standard compliance for cross-border India-China launches extends time-to-market by 14-18 months.
- Legacy ERP Integration:Real-time ingredient traceability requirements for clean-label compliance force expensive middleware upgrades in established manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Snack Bar Market |
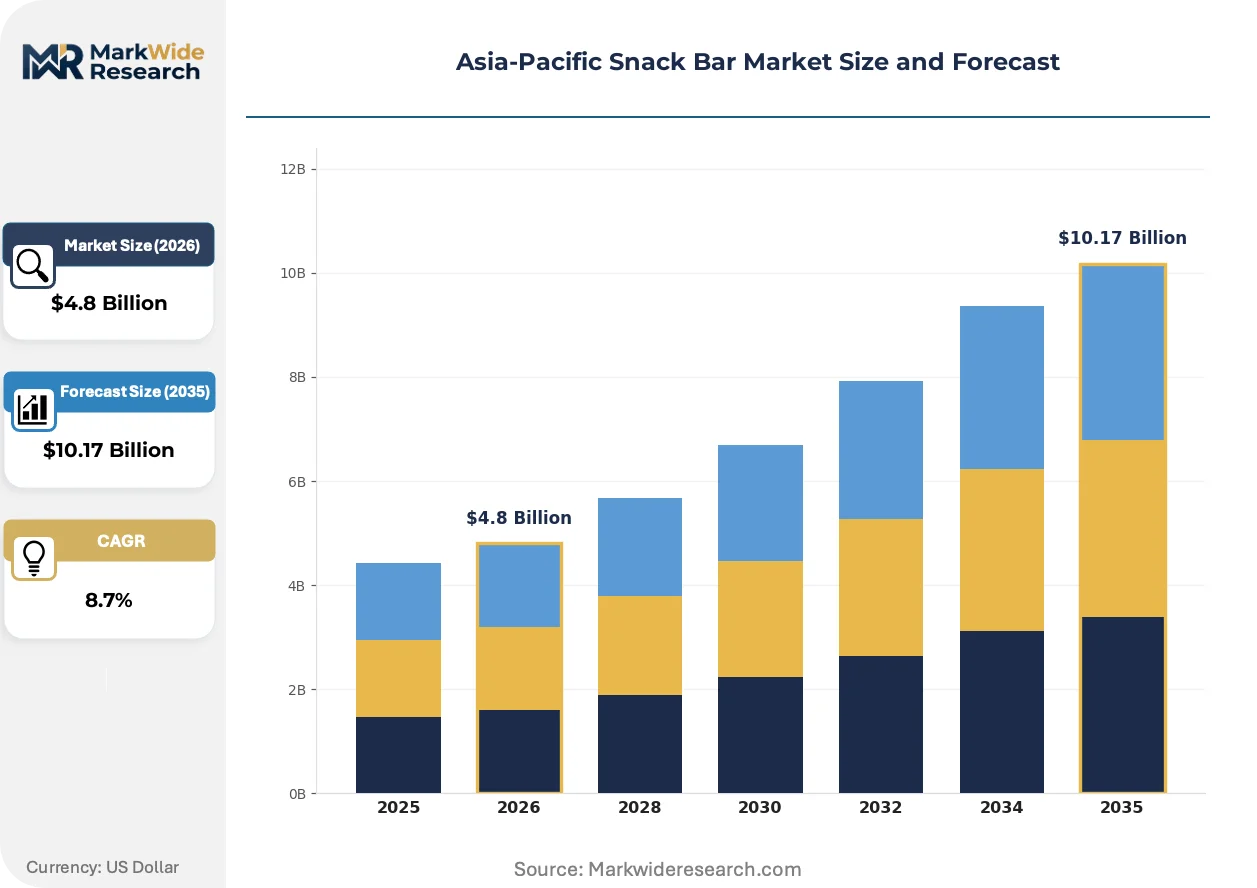
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutrition Bars, Granola Bars, Protein Bars, Fruit & Nut Bars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops End User: Athletes, Health-Conscious Consumers, Busy Professionals, Students Ingredient Type: Organic, Gluten-Free, Vegan, High-Protein |
| Companies Covered | General Mills Inc., Mondelēz International, Inc., Asahi Group Holdings Ltd, ITC Limited, Nestlé S.A., Calbee, Inc., Kellogg Company, Freedom Foods Group Limited, Bagrrys India Pvt Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Snack Bar Market Strategic Shifts
Refrigerated distribution infrastructure is expanding beyond dairy-centric categories into high-protein snacking, while regulatory frameworks increasingly reward verifiable nutritional claims over marketing positioning. Technology convergence between pharmaceutical-grade protein processing and food manufacturing is compressing development cycles.
High-pressure processing (HPP) is miniaturizing from beverage applications into bar manufacturing, enabling ambient-stable products with fresh-like taste profiles. Chinese and Australian contract manufacturers are adopting HPP lines at accelerating pace. This technology is miniaturizing the equipment footprint required for pathogen reduction without thermal degradation, enabling distributed production closer to urban demand centers rather than centralized mega-facilities.
Japan's Consumer Affairs Agency coordination with METI on functional food labeling creates a regulatory moat that domestic manufacturers exploit for protein and fiber claim differentiation. Industrial consequence includes accelerated R&D investment in clinically substantiated ingredient combinations. The sports-nutrition segment responds fastest, reformulating around permitted claim thresholds that command shelf-space premiums in Japanese health food channels.
Urban professional procurement of snack bars through corporate wellness programs is displacing individual convenience-store purchases in Shanghai, Bangalore, and Sydney. Employers negotiate direct supply contracts that bypass traditional retail markup structures. This channel rotation is most visible in China's technology sector, where campus commissaries and home-office stipends now represent substantial volume concentration.
Asia-Pacific Snack Bar Market Segmentation
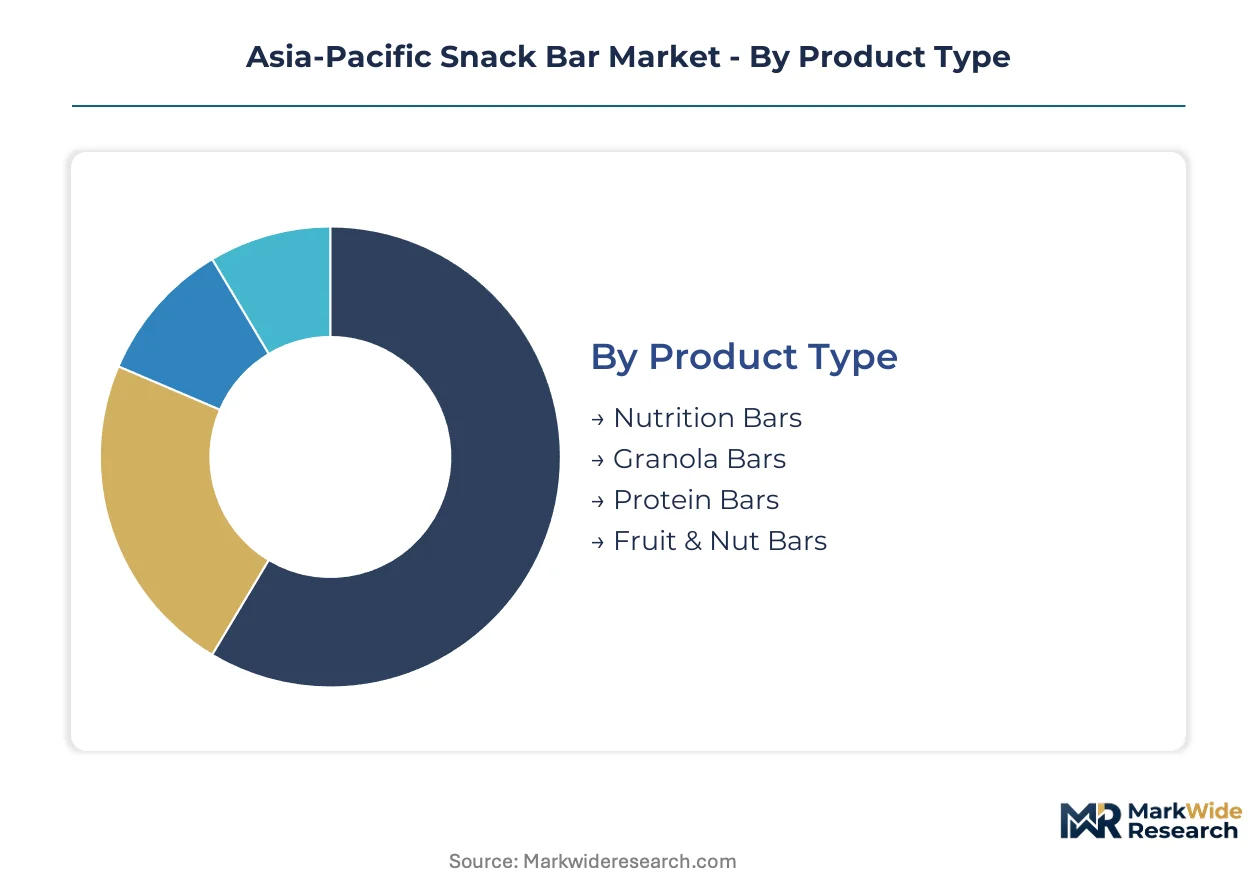
Segmentation in Asia-Pacific snack bars reveals distinct procurement patterns across metropolitan corridors and export manufacturing zones. Manufacturers configure production lines differently for domestic convenience-channel distribution versus cross-border premium positioning.
Product Type:
Geographic concentration varies sharply: protein and nutrition bars serve export-led demand from Australian and Japanese manufacturing hubs, while granola and fruit formulations cluster around domestic Southeast Asian consumption.
- Protein Bars:Cold-pressed extrusion with whey or plant isolates delivers 20-30g protein per 60g serving. Demand concentrates in China's tier-one cities where corporate wellness programs displace traditional retail procurement. SAMR GB standards on nutritional claim substantiation raise compliance costs for imported variants.
- Fruit & Nut Bars:Whole-food bases with visible ingredient pieces target clean-label preferences. India's FSSAI quantitative declaration mandates accelerate adoption in Bangalore and Mumbai health food channels. Binding technology limits remain the primary formulation constraint.
- Nutrition Bars:Fortified with vitamins and minerals for meal-replacement positioning. Australian contract manufacturers dominate export supply to Southeast Asian markets.
- Granola Bars:Baked oat-based formats with established shelf presence. Australian supermarkets exhibit mature private-label penetration compressing branded margins.
Protein bars hold the largest share; momentum sits with fruit and nut bars.
Distribution Channel:
Channel selection determines margin structure: refrigerated logistics for convenience stores command premium pricing, while online retail enables direct-to-consumer trial formats without slotting-fee burdens.
- Convenience Stores:7-Eleven and Lawson chains across Japan, South Korea, and Thailand prioritize grab-and-go formats with ambient stability. Cold-chain infrastructure expansion in Vietnam and Indonesia creates whitespace for premium-positioned entrants.
- Online Retail:Subscription models and trial-sized assortment packs bypass traditional retail markup. Tmall and Lazada infrastructure supports cross-border launches from Australian manufacturers into Chinese tier-two cities.
- Supermarkets:Coles and Woolworths in Australia, along with Aeon in Japan, maintain category captain arrangements that disadvantage smaller entrants.
- Health Food Shops:Specialized channels in Shanghai, Beijing, and Sydney reward clean-label certification and permitted functional claims.
Supermarkets retain volume leadership; online retail is climbing the fastest.
End User:
User segmentation reflects occasion-based procurement: institutional bulk purchasing by employers versus individual convenience-driven selection.
- Busy Professionals:Corporate wellness programs in China's technology sector negotiate direct supply contracts for campus commissaries and home-office stipends. This channel rotation displaces individual convenience-store purchases in Shanghai and Shenzhen.
- Health-Conscious Consumers:Clean-label and organic certification drives premium willingness-to-pay in Japanese and Australian urban centers. METI functional food labeling creates claim differentiation for fiber and protein positioning.
- Athletes:Sports-channel distribution through gyms and specialty retailers commands highest per-unit pricing. Cold-press protein stabilization enables ambient storage without whey denaturation.
- Students:Price-sensitive segment with volume concentration in India's metropolitan corridors. Mid-tier manufacturers compete on per-gram protein cost efficiency.
Busy professionals represent the dominant revenue pool; health-conscious consumers show the steepest expansion trajectory.
Ingredient Type:
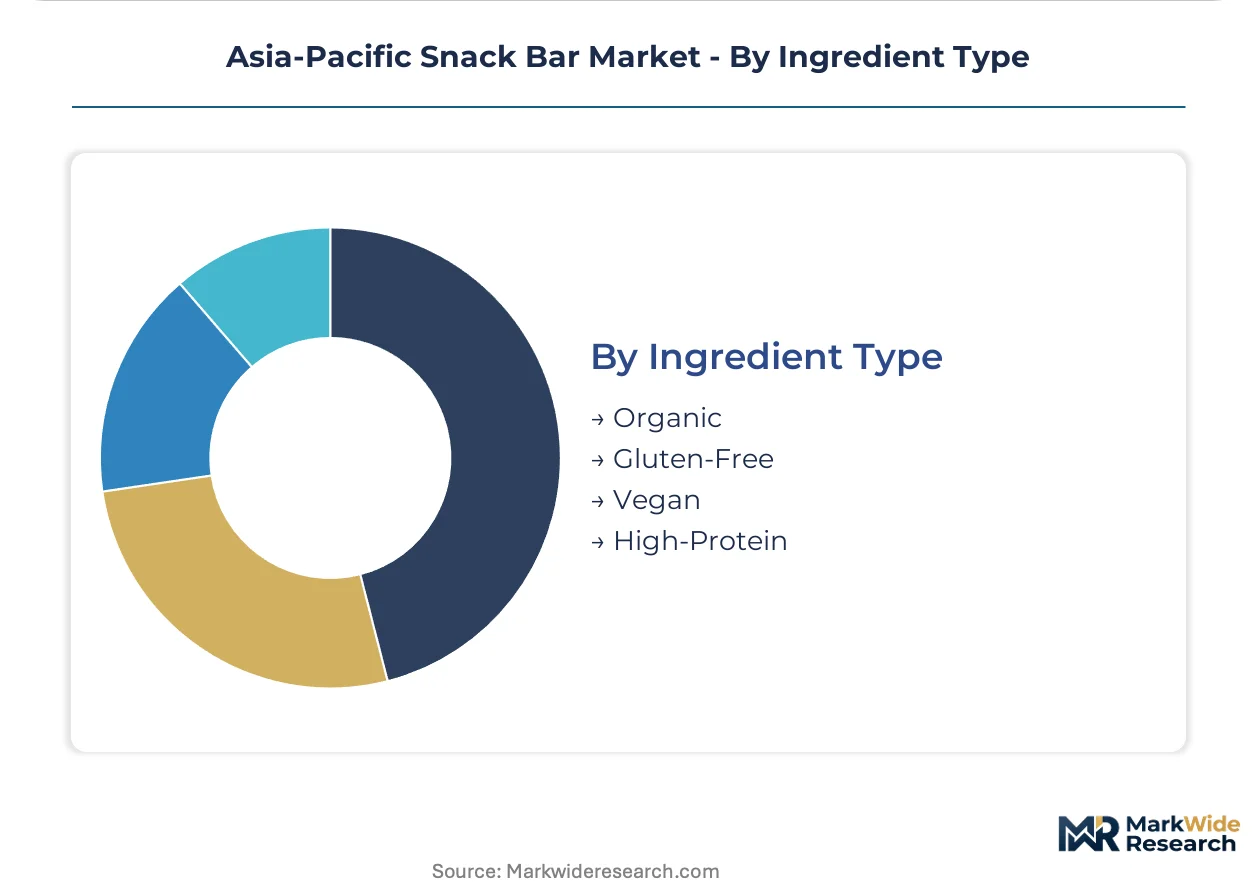
Ingredient certification tiers separate premium export positioning from domestic mass-market supply, with regulatory divergence between FSSAI, SAMR, and METI frameworks complicating cross-border formulation.
- High-Protein:Enzyme-based binding systems and HPP pathogen reduction enable ambient-stable products with pharmaceutical-grade protein processing. Chinese and Australian contract manufacturers adopt HPP lines at accelerating pace.
- Organic:Certification requirements vary across APAC jurisdictions, with Australian NASAA and Japanese JAS standards commanding retail premium. Traceability middleware upgrades strain legacy ERP systems in established facilities.
- Gluten-Free:Oat purity protocols and dedicated production lines required for celiac-safe positioning. Demand clusters in Australian and Japanese markets with established gluten-free retail infrastructure.
- Vegan:Plant protein isolates from pea, rice, and soy compete with whey-dominant formulations. Calbee's soy-based recipes anchor Japanese consumer trust against Western alternatives.
High-protein formulations command margin leadership; vegan certification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia-Pacific snack bar market. Price-sensitive procurement dominates India's metropolitan corridors and Indonesia's emerging urban centers, while premium willingness-to-pay concentrates in Japan's Kanto region and Australia's eastern seaboard.
China
Corporate wellness programs in Shanghai and Shenzhen technology campuses negotiate direct supply contracts that displace traditional convenience-store procurement. SAMR enforces GB standards on nutritional claim substantiation, raising compliance costs for protein-content marketing. Cold-press protein stabilization capabilities cluster in Guangdong manufacturing zones serving tier-one urban demand.
Japan
Health-conscious consumers in Tokyo and Osaka demonstrate sustained premium willingness-to-pay for clean-label certification. METI functional food labeling permits specific protein and fiber claims, creating regulatory differentiation for domestic manufacturers. HPP-equipped contract manufacturers in the Chubu region accelerate distributed production closer to urban demand centers.
India
Students and young professionals in Bangalore and Mumbai drive volume concentration for mid-tier protein efficiency positioning. FSSAI quantitative ingredient declaration mandates accelerate reformulation toward recognizable whole-food bases. Domestic brands with transparent sourcing capture first-mover advantages in health food channels.
Australia
Private-label penetration in Coles and Woolworths compresses branded margins for granola formats, while protein bar exports to Southeast Asia sustain contract manufacturing growth. TGA alignment with New Zealand MPI on novel protein approvals shapes cross-border R&D investment. Sydney and Melbourne health food shops reward organic NASAA certification with shelf-space premiums.
Vietnam
Modern trade expansion in Ho Chi Minh City creates whitespace for premium-positioned entrants before local private-label consolidation. Cold-chain infrastructure gaps limit refrigerated distribution to ambient-stable formats. Convenience channel growth in urban corridors attracts regional manufacturers testing ASEAN market entry.
Asia-Pacific Snack Bar Market Competitive Environment
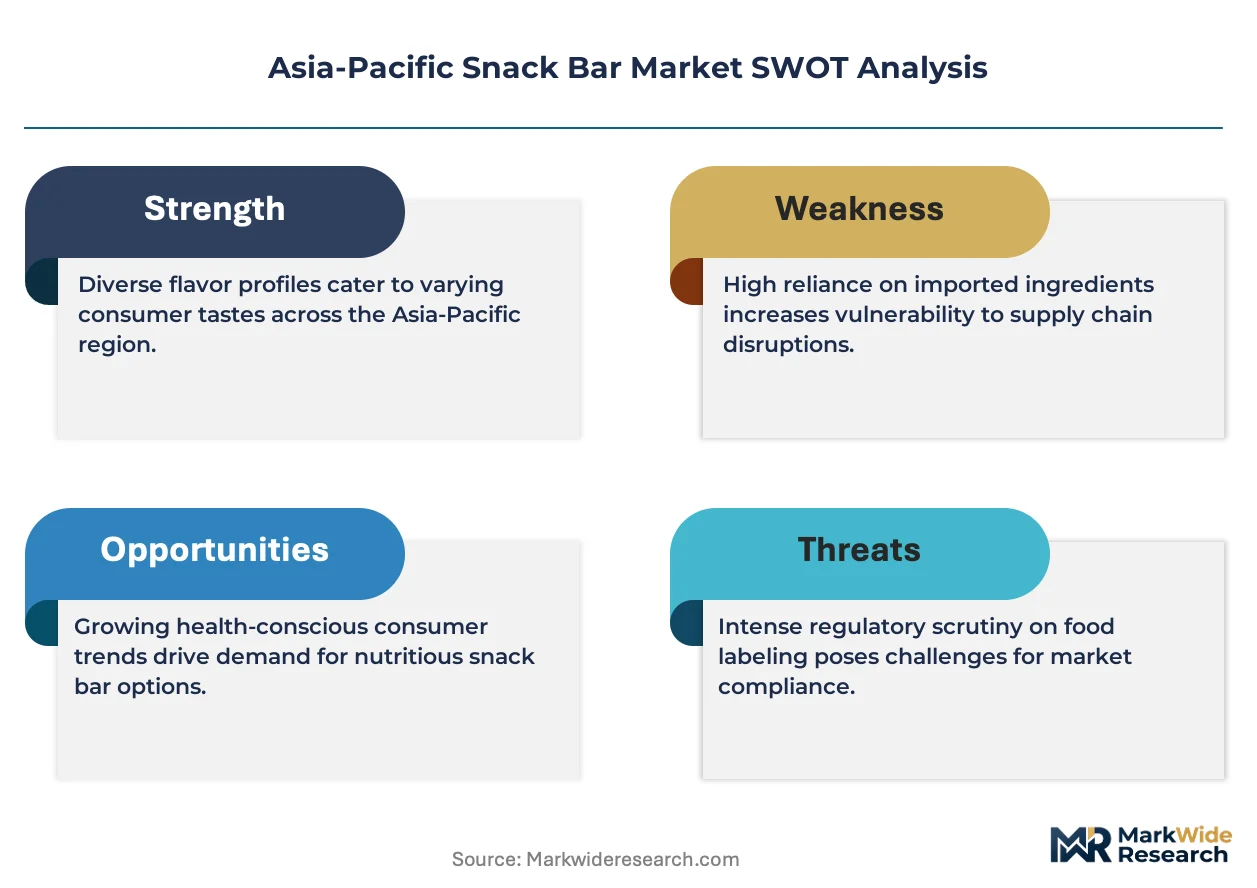
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific snack bar market. The vendor base separates into multinational CPG conglomerates with dairy protein supply chains, domestic Japanese and Indian specialists with regional formulation expertise, and Australian contract manufacturers serving export demand. Strategic archetypes include refrigerated distribution specialists, clean-label reformulation leaders, and private-label scale operators. Competitive moves concentrate on cold-press extrusion capacity expansion and cross-border regulatory certification alignment.
Within the multinational conglomerate tier, Nestlé S.A. and Mondelēz International, Inc. occupy positions anchored by manufacturing scale and convenience channel penetration. Calbee, Inc. exemplifies the domestic specialist archetype with soy-based formulation expertise competing against Western whey-dominant recipes. Among India-based operators, ITC Limited represents the diversified conglomerate model extending food processing capabilities into portable nutrition formats.
| Leading Market Players |
|---|
| General Mills Inc. |
| Mondelēz International, Inc. |
| Asahi Group Holdings Ltd |
| ITC Limited |
| Nestlé S.A. |
| Calbee, Inc. |
| Kellogg Company |
| Freedom Foods Group Limited |
| Bagrrys India Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
Cold-press extrusion scale economies in Guangdong and Victoria manufacturing zones concentrate production capacity among operators with refrigerated distribution networks, compressing price floors for ambient-stable formats while elevating premiums for HPP-equipped contract manufacturers serving Japanese functional food channels.
Pricing Analysis
FSSAI quantitative declaration mandates and SAMR GB standards on nutritional claim substantiation dictate the pricing tier structure across the Asia-Pacific snack bar market. Three-tier pricing structure across premium, standard, and economy levels separates HPP-equipped functional claim products from cold-pressed ambient formats and mass-market baked alternatives. Cost compression in mid-tier protein bars is intensifying because palm oil price volatility transmits directly to coating and binding structures. Students in India's metropolitan corridors exhibit highest price sensitivity, while health-conscious consumers in Tokyo and Sydney demonstrate lowest elasticity for organic NASAA and JAS certified variants.
Supply Chain Analysis
China and Australia anchor protein isolate processing and HPP-equipped contract manufacturing for export-led demand across Southeast Asia. Supply chains draw from whey and plant protein concentrates, enzyme-based binding systems, and palm-derived coating materials. Single-source vulnerability concentrates in Southeast Asian palm oil supply disruptions that transmit directly to margin structures. Distribution runs through 7-Eleven and Lawson convenience chains for ambient formats, with refrigerated logistics expanding into corporate wellness direct-supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific snack bars sit in early-cycle expansion as corporate wellness procurement displaces traditional retail channels across Shanghai, Bangalore, and Sydney technology campuses.
For Market Incumbents: Compound refrigerated distribution advantages by expanding cold-press extrusion capacity in Guangdong and Victoria zones before emerging entrants secure HPP equipment. Defend against private-label compression in Australian supermarkets through exclusive corporate wellness supply contracts that bypass slotting-fee structures. Certification investment in FSSAI clean-label compliance creates moats against multinational entrants facing 14-18 month dual-registration timelines. For New Entrants and Emerging Players: Corporate wellness procurement gaps in Vietnam and Indonesia present whitespace before local private-label consolidation hardens. Target Ho Chi Minh City and Jakarta modern trade expansion with ambient-stable premium formats that circumvent cold-chain infrastructure limitations. Direct-to-consumer subscription models via Tmall and Lazada enable trial-sized assortment packs without traditional retail markup barriers. For Investors and Strategic Acquirers: Australian contract manufacturers with HPP-equipped distributed production capabilities represent the priority acquisition archetype for functional food positioning. Long-term viability hinges on regulatory alignment between TGA and MPI on novel protein approvals that would fragment R&D investment if divergent. Watch METI functional food labeling expansion as the inflection signal for premium claim differentiation rewards.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Capacity Expansion | Guangdong manufacturing zones capture tier-one urban demand from Shanghai and Shenzhen technology campuses. |
| HPP Equipment Adoption | Chubu region contract manufacturers enable distributed production closer to Tokyo and Osaka demand centers. |
| FSSAI Clean-Label Certification | Domestic Indian brands with transparent sourcing capture first-mover advantages in Bangalore health food channels. |
| Corporate Wellness Direct Supply | Bypasses Coles and Woolworths category captain arrangements that disadvantage smaller entrants. |
| Refrigerated Distribution Network Buildout | Unlocks convenience-channel placement for high-protein formats previously reserved for lower-nutrition alternatives. |
Study Parameters
Desk research of FSSAI regulatory filings, SAMR GB standard documentation, and METI functional food labeling guidelines preceded structured interviews with brand managers at multinational CPG conglomerates, category buyers at 7-Eleven and Lawson chains, cold-chain logistics operators, and contract manufacturing executives. Secondary validation drew from Nielsen retail audit data, customs import records for protein isolates, and pharmaceutical-grade protein processing equipment disclosures. Bottom-up demand modeling across metropolitan corridors triangulated with top-down manufacturing capacity assessments.
Variance decomposition across product type, distribution channel, end user, and ingredient certification tiers shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration in corporate wellness versus traditional retail procurement. Forecast inputs incorporated cold-press protein stabilization adoption curves and HPP equipment installation rates at Chinese and Australian contract manufacturers.
Underlying assumptions cover sustained corporate wellness program expansion, regulatory alignment on novel protein approvals, and palm oil supply stability, with deviation risk concentrated in FSSAI-SAMR registration timeline extensions and fresh fruit substitution acceleration in Japanese convenience channels. Recalibration cycles align with material shifts in METI functional food labeling scope and cold-chain infrastructure completion in Vietnam and Indonesia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
UAE Snack Bar Market
Snacks
Low-Fat Tortillas Market
Snacks
North America Snack Pellets Market
Snacks
Europe Snack Bar Market
Snacks
Snack Food Packaging Market
Snacks
Granola Market
Snacks
India Energy Bar Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Premium Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Forti Flakes Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
South Africa Savory Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Dairy Snacks Market
Snacks
North America Baked Savory Snacks Market