
 Low Calorie Biscuits Market | 2026-2036
Low Calorie Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Biscuits Market Analytics
Aftermarket nutrition consulting and personalized diet planning is rewriting how biscuit brands capture lifetime value from health-focused consumers. Mondelez International leverages its global R&D network to reformulate core brands with reduced caloric density. Britannia Industries anchors its portfolio with fiber-enriched variants tailored to Indian dietary preferences. Lotus Bakeries specializes in premium positioning through clean-label ingredient sourcing.
Low calorie biscuits are baked goods formulated with reduced fat, sugar, or overall caloric content through modified recipes, alternative sweeteners such as maltitol or stevia, and adjusted flour-to-fiber ratios, designed to deliver sensory satisfaction within controlled energy budgets for weight management and glycemic control. Sugar-free formulations lead volume due to diabetic consumer pull, while high-protein variants represent the fastest-growing niche as fitness culture permeates mainstream snacking. Fiber-enriched products command premium shelf placement in specialty stores where margin pools remain deepest.
The FDA governs health claim substantiation and serving-size disclosure, while the FSSAI mandates maximum permissible sugar thresholds in India, and the EFSA evaluates novel ingredient safety for European market access. These frameworks collectively elevate formulation costs but also create defensible market positions for compliant manufacturers. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to pursue preemptive certification ahead of regulatory deadlines.
Market Dynamics
The FDA's updated Nutrition Facts labeling and WHO sugar reduction guidelines are compressing formulation timelines and forcing manufacturers to rebuild recipes around alternative sweeteners and fiber enrichment before compliance deadlines hit.
Growth Catalysts
- Corporate wellness programs:Health-conscious millennials and Gen Z employees in the United States, United Kingdom, and India drive institutional procurement of portion-controlled, low-glycemic snacking options for office pantries.
- FSSAI sugar thresholds:India's mandatory maximum permissible sugar limits in processed foods create a regulated demand floor that rewards early reformulators with preferred retail placement.
- Alternative sweetener maturation:Stevia and maltitol production scale-up is collapsing input costs for reduced-sugar formulations, enabling price parity with conventional biscuits in mass retail channels.
Market Restraints
- Wheat and oat fiber price volatility:Climate-driven harvest variability in North American and Black Sea grain belts compresses margins for fiber-enriched product lines during drought cycles.
- Clean-label ingredient concentration:Premium natural sweetener supply concentrates among three major producers, creating single-source vulnerability for brands pursuing EFSA-compliant clean-label positioning.
- Sensory-performance tradeoffs:Current fat-replacement technologies cannot replicate mouthfeel and crumb structure simultaneously, limiting consumer acceptance in indulgence-oriented segments.
Strategic Opportunities
- Specialty retail aisle expansion:United Kingdom supermarkets are carving dedicated functional snacking sections that command 15-25% shelf-space premiums for compliant low-calorie entrants.
- Personalized nutrition convergence:Integration of at-home glucose monitoring with AI-driven meal planning apps creates data partnerships between biscuit brands and digital health platforms.
- Indian diabetic population:Underpenetrated tier-2 and tier-3 cities present whitespace for sugar-free formulations distributed through pharmacy-adjacent convenience networks.
Industry Challenges
- Novel food ingredient dossier preparation:EFSA safety evaluations for emerging fiber sources and sweetener blends demand 18-36 month timelines that misalign with fast-moving retail reset cycles.
- Legacy equipment retrofitting:Existing biscuit production lines require humidity-control and dough-handling modifications to process high-fiber, low-fat batters without throughput degradation.
- Front-of-pack labeling fragmentation:Divergent national color-coded warning systems and Nutri-Score implementations force SKU proliferation and complicate pan-European supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Biscuits Market |
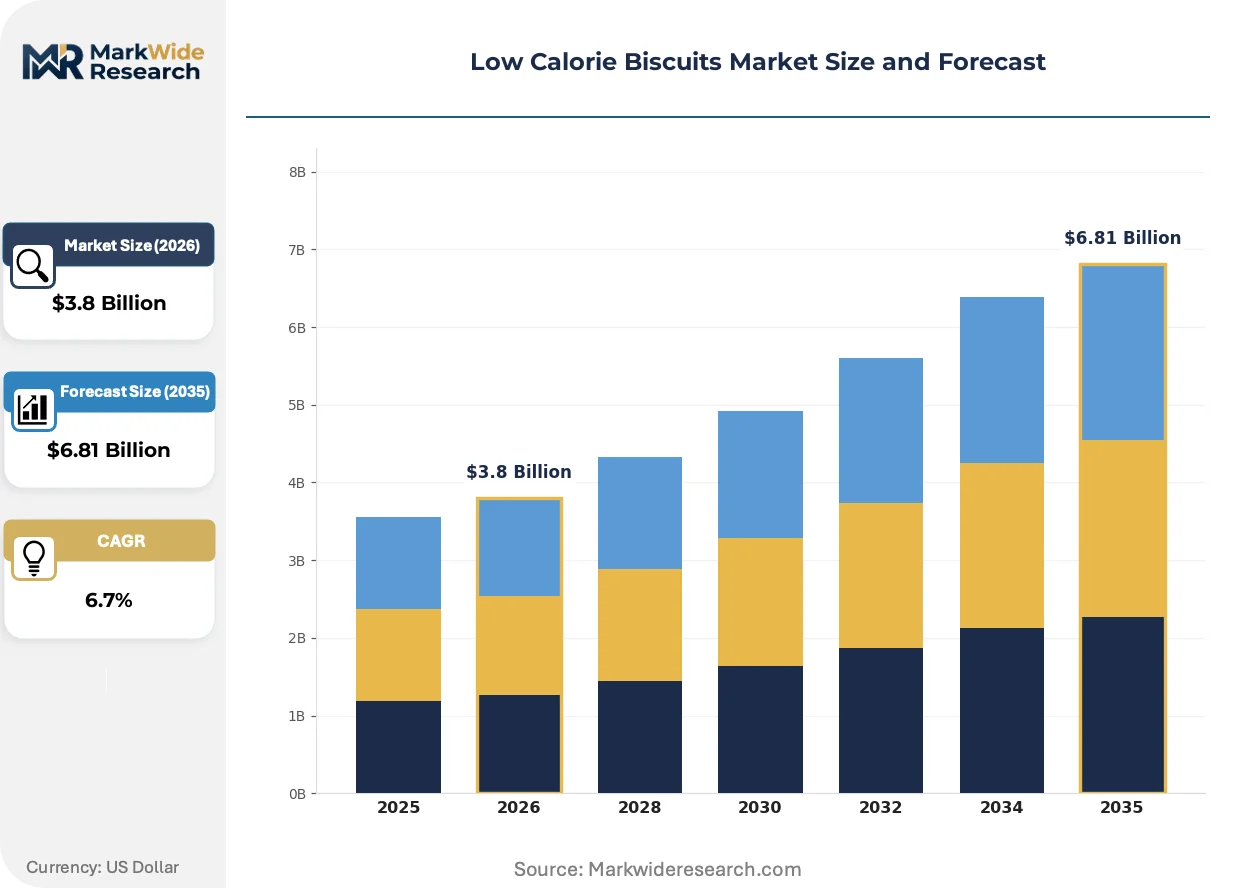
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Sugar-Free, High-Protein, Fiber-Enriched Packaging Type: Box, Bag, Pouch, Tin End User: Weight Watchers, Health Enthusiasts, Fitness Buffs, Diabetic Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Lotus Bakeries, Arnott's, Mondelez International, ITC Limited, Parle Products, Nestle, Kraft Heinz, McVitie's, Britannia Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Biscuits Market Evolving Landscape
Reformulation science and digital traceability are converging to redefine how low-calorie biscuits demonstrate value beyond the nutrition panel, shifting competitive advantage from ingredient lists to verified health outcomes.
Enzymatic fiber modification technology is collapsing the texture gap between high-fiber and conventional biscuits by breaking down insoluble fibers into shorter chains that retain bulk without grittiness. Bakery R&D teams in the United States and Netherlands are adopting these systems at pilot scale, with commercial rollout accelerating as equipment costs drop below $2 million per line. The structural consequence is compressing the premium commanded by fiber-enriched products toward mass-market parity.
EFSA's evolving guidance on health claim substantiation for glycemic response is forcing manufacturers to commission clinical trials demonstrating measurable postprandial glucose effects. This regulatory tightening eliminates vague "low sugar" positioning and rewards brands with peer-reviewed data packages. Diabetic consumer segments in Germany and France are migrating toward products bearing approved Article 13.5 claims, creating a two-tier market split between substantiated and unsubstantiated entrants.
Direct-to-pantry subscription models are displacing impulse purchases in health-focused households, with curated monthly boxes of portion-controlled snacks replacing supermarket aisle browsing. This channel shift concentrates buyer power among three major wellness platforms that demand exclusive SKUs and transparent supply chain documentation. The United States and United Kingdom show the fastest migration velocity, particularly among urban professionals aged 28-42 managing weight or metabolic conditions.
Low Calorie Biscuits Market Segmentation
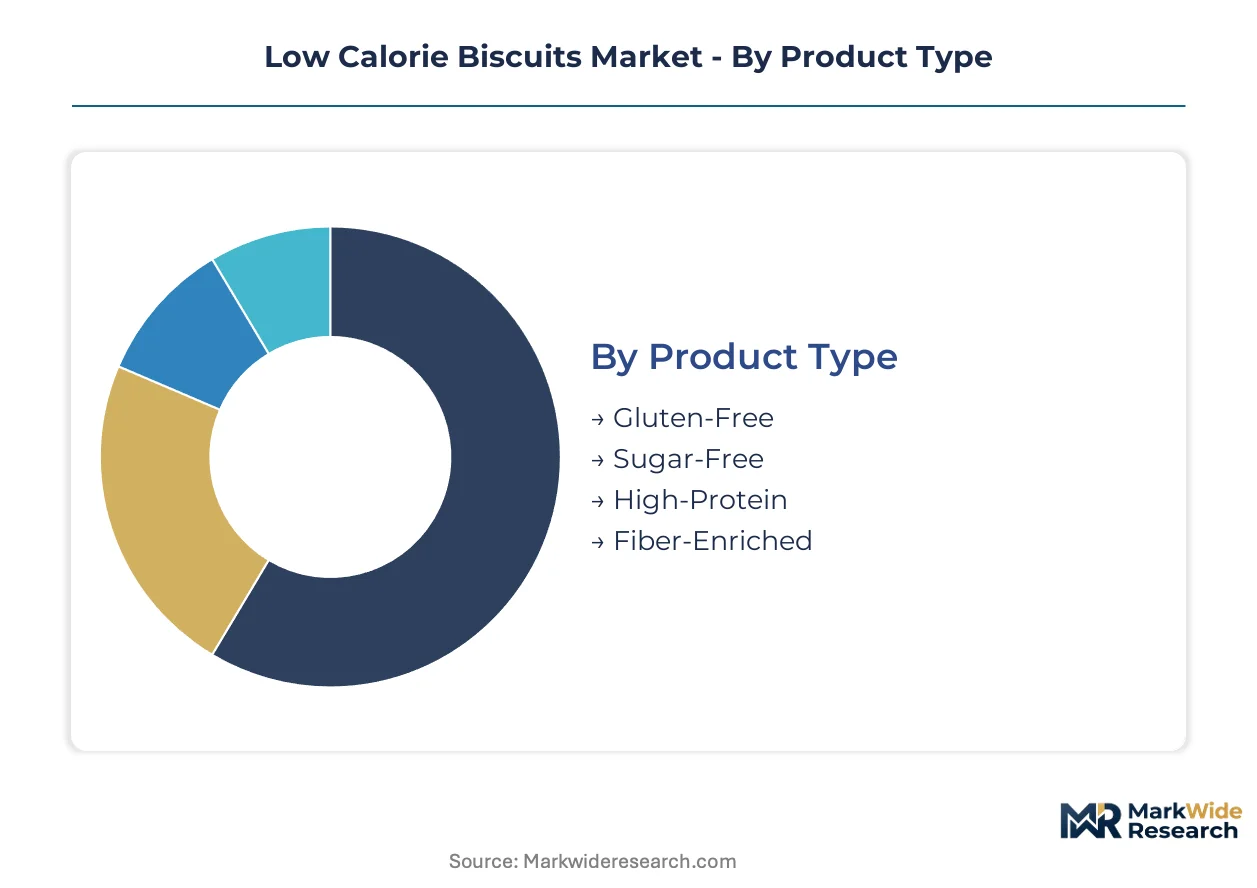
Segmentation in low-calorie biscuits determines formulation priorities, packaging investments, and channel economics. Manufacturers must align R&D spend with the specific dietary protocols and purchasing behaviors of distinct consumer clusters.
Product Type:
After-sales service intensity varies sharply across product types, with sugar-free and diabetic-focused lines requiring pharmacist partnerships and nutritional hotline support that conventional biscuits never demand.
- Sugar-Free:Formulated with maltitol, stevia, or monk fruit to eliminate glycemic impact while maintaining sweetness. Diabetic consumers in India and the United States drive institutional procurement through pharmacy networks and corporate wellness programs.
- High-Protein:Incorporates whey isolate, pea protein, or collagen to deliver 10-15g protein per serving with adjusted fat ratios. Fitness enthusiasts in urban United Kingdom and Indian metros are shifting snack budgets toward these functional formats as gym culture mainstreams.
- Gluten-Free:Utilizes rice flour, almond meal, or tapioca starch to replace wheat protein structures. Celiac and wheat-sensitive consumers in specialty retail channels.
- Fiber-Enriched:Adds soluble and insoluble fiber from oat bran, chicory root, or psyllium to enhance satiety. Health-conscious households seeking digestive benefits.
Sugar-Free holds the largest share; momentum sits with High-Protein.
Packaging Type:
Cost tier stratification runs through packaging choices, with premium tins and single-serve pouches commanding 40-60% price multiples over commodity bag formats.
- Pouch:Flexible laminated films with reseal zippers and portion-control windows dominate convenience channel velocity. Urban millennials in United States and United Kingdom supermarkets favor grab-and-go pouches for desk-drawer storage.
- Box:Rigid paperboard with nutritional callouts and recipe suggestions anchors family-size retail placement. Indian households in tier-1 cities prefer boxed assortments for pantry visibility and gifting occasions.
- Bag:Lightweight polypropylene with basic barrier properties serves price-sensitive mass market. Value retailers and promotional channels.
- Tin:Metal canisters with heritage aesthetics and extended shelf life support premium gifting and export positioning. Specialty stores and duty-free channels.
Pouch formats lead volume; tin packaging captures value concentration.
End User:
Application-specific formulation requirements split manufacturing lines, with diabetic consumers demanding batch-tested glycemic validation that fitness segments rarely require.
- Diabetic Consumers:Requires precise carbohydrate disclosure, low glycemic index certification, and often physician endorsement. United States and India show concentrated demand through pharmacy-adjacent retail and prescription-adjacent nutrition counseling.
- Fitness Buffs:Prioritizes macronutrient ratios, protein density, and pre/post-workout timing claims. Metropolitan gym ecosystems in United Kingdom and United States drive subscription box and direct-to-pantry purchasing.
- Weight Watchers:Calorie-counting households seeking portion-controlled indulgence within strict energy budgets. Commercial diet program partnerships.
- Health Enthusiasts:Broad wellness-focused buyers responding to clean-label and functional ingredient narratives. Mainstream supermarket shoppers.
Diabetic Consumers anchor stable demand; Fitness Buffs are expanding most quickly.
Distribution Channel:
Customer type concentration shapes channel investment, with health-focused professionals migrating toward digital-first purchasing that bypasses traditional retail entirely.
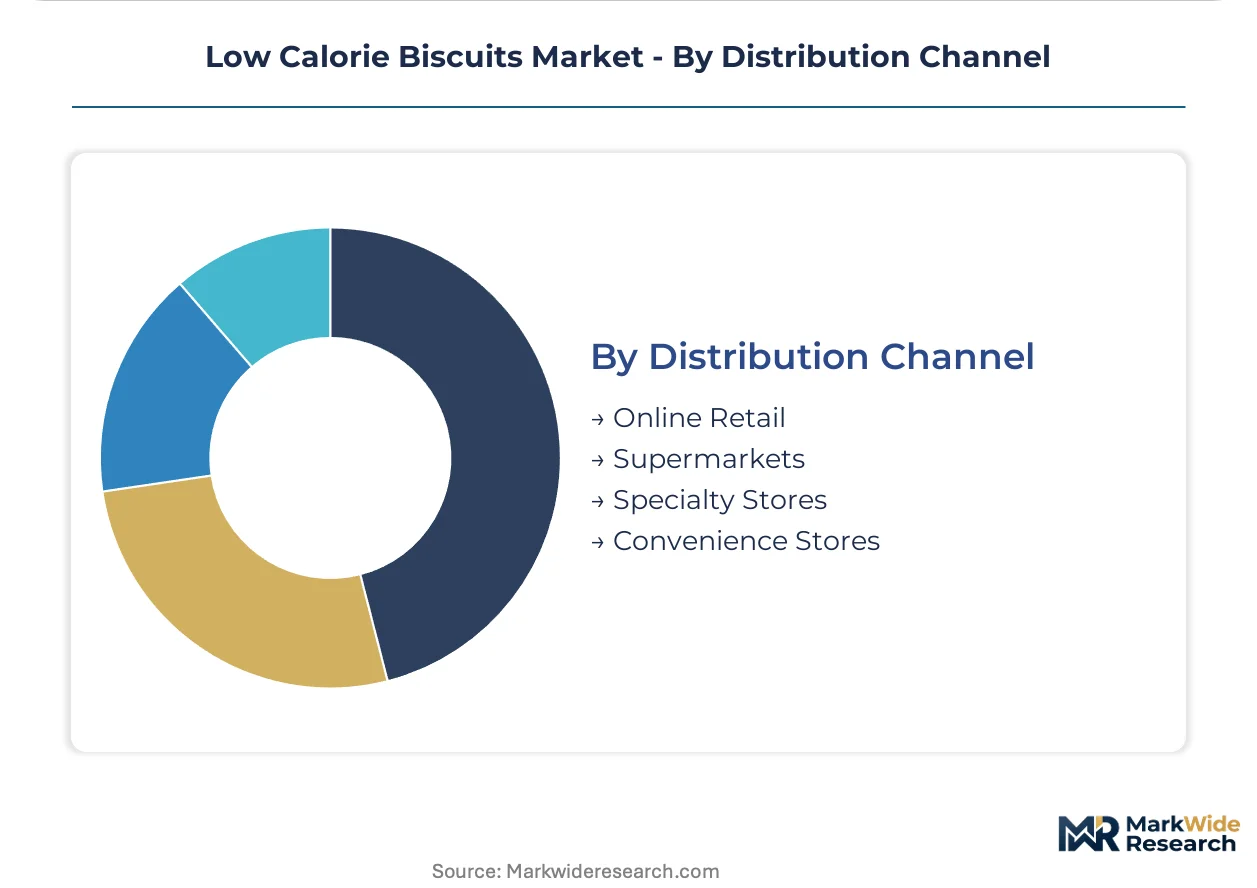
- Supermarkets:Dedicated functional snacking aisles in United Kingdom and United States chains command shelf-space premiums and require slotting fee negotiations. Britannia and Mondelez leverage existing retail relationships for preferred placement.
- Online Retail:Direct-to-pantry subscription models and wellness platform partnerships concentrate buyer power among curated box services. Urban professionals aged 28-42 in United States and United Kingdom show fastest migration velocity.
- Specialty Stores:Health food retailers and organic chains with educated staff and ingredient transparency requirements. Premium positioning and margin capture.
- Convenience Stores:Impulse-oriented small-format retail with limited SKU depth and price-sensitive positioning. Travel and emergency purchase occasions.
Supermarkets retain volume leadership; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States households prioritize portion-controlled subscription formats, while Indian consumers favor pharmacy-distributed sugar-free assortments. European markets demand EFSA-substantiated glycemic claims that command shelf-space premiums in dedicated functional aisles.
United States
Corporate wellness programs and direct-to-pantry subscription models drive procurement of low-glycemic, portion-controlled formats. FDA updated Nutrition Facts labeling mandates force reformulation timelines that favor early movers with reduced-sugar portfolios. Chicago and New York Metro clusters concentrate R&D activity where enzymatic fiber modification pilot programs are scaling toward commercial rollout.
United Kingdom
Supermarket functional snacking aisles command 15-25% shelf-space premiums for compliant entrants targeting urban professionals aged 28-42. EFSA evaluation of novel ingredient safety creates 18-36 month dossier timelines that misalign with fast-moving retail reset cycles. London and Southeast England anchor demand concentration where Nutri-Score implementations are forcing SKU proliferation.
India
Diabetic consumer segments in tier-2 and tier-3 cities present whitespace for sugar-free formulations distributed through pharmacy-adjacent convenience networks. FSSAI mandatory maximum permissible sugar thresholds create a regulated demand floor rewarding early reformulators with preferred retail placement. Maharashtra and Gujarat manufacturing belts concentrate production capacity where fiber-enriched variants are being tailored to local dietary preferences.
Germany
Diabetic consumer segments migrate toward products bearing approved Article 13.5 health claims, creating a two-tier market split between substantiated and unsubstantiated entrants. EFSA guidance on glycemic response substantiation eliminates vague positioning and rewards peer-reviewed data packages. Bavaria and North Rhine-Westphalia host clinical trial infrastructure where manufacturers commission postprandial glucose effect studies.
Netherlands
Bakery R&D teams adopt enzymatic fiber modification systems at pilot scale as equipment costs drop below $2 million per line. EFSA-compliant clean-label positioning concentrates premium natural sweetener supply among limited producers, creating single-source vulnerability. Amsterdam-Rotterdam corridor clusters food technology innovation where texture-gap compression between high-fiber and conventional biscuits is accelerating.
Low Calorie Biscuits Market Competitive Landscape
Capability concentration sits with specialty clean-label formulators; scale advantage sits with multinational packaged food conglomerates. The market structures around three tiers: global diversified giants with reformulated core brands, regional specialists with fiber-enriched or sugar-free portfolios, and emerging direct-to-consumer platforms with subscription-based distribution. Dominant competitive moves include portfolio diversification into functional snacking and strategic partnerships with digital health platforms for personalized nutrition integration.
Within the global diversified tier, Mondelez International and Nestle occupy positions exemplifying scale-driven reformulation capabilities across multiple geographies. Britannia Industries represents the regional specialist archetype with India-focused portfolio tailoring. Lotus Bakeries sits within the premium clean-label positioning tier where heritage aesthetics and extended shelf-life formats command duty-free and specialty retail premiums.
| Leading Market Players |
|---|
| Lotus Bakeries |
| Arnott's |
| Mondelez International |
| ITC Limited |
| Parle Products |
| Nestle |
| Kraft Heinz |
| McVitie's |
| Britannia Industries |
| Others |
Value Network & Pricing Analysis
Maharashtra and Gujarat manufacturing belts anchor South Asian production capacity for fiber-enriched and sugar-free formulations, with their scale dynamics directly transmitting into pricing power across pharmacy-adjacent retail networks in tier-2 and tier-3 Indian cities.
Pricing Analysis
Long-term offtake contracts between major biscuit manufacturers and maltitol or stevia suppliers dominate input procurement, insulating reformulated product lines from spot-market volatility in alternative sweeteners. Three-tier pricing structure across premium clean-label, standard functional, and economy mass-market levels separates EFSA-substantiated claims from basic reduced-sugar positioning. Price differentiation rests on certification grade and brand heritage aesthetics, with tin-packaged heritage formats commanding sustained premiums. Cost compression in standard tiers is intensifying as enzymatic fiber modification equipment costs drop below $2 million per line, while diabetic consumers through pharmacy channels show lowest price sensitivity due to physician endorsement requirements.
Supply Chain Analysis
Tariff exposure between North American grain belts and European processing facilities dominates risk profiles for wheat and oat fiber inputs, with climate-driven harvest variability compressing margins during drought cycles. Manufacturing capacity concentrates in India, the United Kingdom, and the Netherlands, where bakery R&D clusters feed from chicory root, psyllium, and enzymatically modified fiber sources. Single-source vulnerability concentrates among three major premium natural sweetener producers for EFSA-compliant clean-label positioning. Distribution runs through supermarket functional snacking aisles, direct-to-pantry subscription platforms, and pharmacy-adjacent convenience networks with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical trial infrastructure capable of generating Article 13.5 glycemic response data packages creates defendable moats for manufacturers with established EFSA submission capabilities, while legacy equipment retrofitting expertise remains concentrated among specialized engineering firms.
For Market Incumbents: Insulate core portfolio value by commissioning preemptive clinical trials for glycemic response substantiation ahead of EFSA deadline acceleration, and secure backward integration into enzymatic fiber modification technology through exclusive equipment partnerships with Netherlands-based pilot-scale providers. Threats from direct-to-pantry subscription platforms concentrating buyer power demand channel control through exclusive SKU development for wellness box services. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities present whitespace for sugar-free formulations distributed through pharmacy-adjacent convenience networks, with FSSAI mandatory sugar thresholds creating a regulated demand floor that rewards early reformulators. Fitness-focused high-protein variants in metropolitan United Kingdom gym ecosystems offer the most penetrable segment for subscription box entry. Go-to-market execution should prioritize AI-driven meal planning app partnerships for personalized nutrition data integration. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaged food conglomerates seeking to divest non-core biscuit portfolios amid reformulation cost pressures. Long-term viability across the analysis window favors manufacturers with demonstrated EFSA dossier preparation capabilities and established relationships with digital health platforms. The signal to watch is front-of-pack labeling mandate harmonization progress, which would eliminate SKU proliferation burdens and reward pan-European supply chain scale.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Preparation | Article 13.5 glycemic response substantiation creates two-tier market split in Germany and France. |
| Enzymatic Fiber Modification Scale-Up | Pilot programs in Chicago and Amsterdam-Rotterdam corridor compress texture gap toward mass-market parity. |
| Direct-to-Pantry Subscription Launch | Urban professionals aged 28-42 in United States and United Kingdom bypass traditional retail entirely. |
| Pharmacy-Adjacent Distribution Expansion | FSSAI sugar thresholds in India reward early reformulators with preferred placement in tier-2 cities. |
| Digital Health Platform Partnership | AI-driven meal planning apps create data partnerships with at-home glucose monitoring integration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at Mondelez International and Britannia Industries, category buyers at United Kingdom supermarket chains, supply planners managing alternative sweetener procurement, and regulatory affairs specialists navigating EFSA novel food dossier preparation. Secondary validation drew from FDA Nutrition Facts labeling guidance documents, FSSAI sugar threshold notifications, EFSA health claim evaluation registers, and Nielsen retail audit data tracking functional snacking aisle velocity. Bottom-up volume modeling across product type, packaging format, end-user segment, and distribution channel triangulated against top-down macroeconomic consumption pattern analysis.
Calibration against historical reformulation timelines and regulatory compliance cost curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging tier, end-user dietary protocol, and distribution channel, with regional regulatory cluster effects layered across United States, United Kingdom, Indian, and European market access requirements. CAGRs were derived from fitted growth curves incorporating alternative sweetener production scale-up trajectories, enzymatic fiber modification equipment cost decline rates, and corporate wellness program procurement expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium functional foods or corporate wellness program budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA evaluation timeline standardization and FSSAI enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Popcorn Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
Fried Potato Chips Market
Snacks
Mushroom Based Jerky Market
Snacks
Spain Energy Bar Market
Snacks
North America Fruit Snacks Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Pretzel Salts Market
Snacks
Sweet Potato Fries Market
Snacks
Roasted Corn Market
Snacks
Energy Bar Market
Snacks
South Africa Savory Snacks Market
Snacks
India Energy Bar Market
Snacks
Indonesia Snack Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Argentina Snack Bar Market