
 United Kingdom Smart Home Market | 2026-2036
United Kingdom Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Smart Home Market Insights
Buyer concentration among residential property developers is shifting as fragmented buy-to-let landlords and Build-to-Rent operators enter the smart home procurement channel. Schneider Electric SE leverages its Wiser ecosystem to anchor premium professional installation segments. Samsung Electronics Co., Ltd. competes through SmartThings platform interoperability across white goods and entertainment devices. Amazon.com Inc dominates voice-first control interfaces through Echo hardware penetration and Alexa Skills marketplace breadth.
The United Kingdom Smart Home Market comprises networked sensor, actuator, and control systems that automate environmental, security, and entertainment functions through centralized hubs or distributed edge processing, typically operating on 2.4 GHz wireless spectra with mesh redundancy protocols for sub-100 millisecond response latency. Smart Lighting and Smart Security Systems currently occupy the largest installed base volumes, though Smart Thermostats capture disproportionate margin pools through recurring energy optimization service fees. Zigbee and Z-Wave mesh technologies sustain professional installation loyalty, while Wi-Fi Direct protocols extend DIY accessibility for price-sensitive first-time adopters.
Ofgem mandates smart meter deployment obligations that shape device interoperability standards, while BEIS Future Homes Standards regulate new-build thermal efficiency minimums that drive integrated HVAC control demand. The UK Product Security and Telecommunications Infrastructure Act imposes baseline cybersecurity certification requirements that filter non-compliant hardware from retail channels. Stakeholders must monitor whether BSI Kitemark expansion into IoT security creates de facto market access barriers for budget-tier imports.
Market Dynamics
Retrofit demand from England's ageing Victorian and Edwardian housing stock is colliding with BEIS Future Homes Standards to create a bifurcated installation base split between legacy property upgrades and new-build integrated systems.
Growth Catalysts
- Ofgem smart meter rollout obligations:Mandated deployment timelines force utility providers to subsidize gateway device installation, lowering consumer entry barriers for whole-home automation expansion.
- Build-to-Rent operators:Institutional landlords in Greater London and Manchester are specifying integrated smart home packages as tenant retention tools, creating volume procurement channels distinct from retail.
- Zigbee and Z-Wave mesh protocols:Interoperability certifications reduce ecosystem lock-in anxiety among professional installers, sustaining loyalty against Wi-Fi Direct DIY alternatives.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for sensor chipsets depends on East Asian foundry capacity, exposing UK device assemblers to geopolitical logistics volatility.
- Cybersecurity certification costs:UK Product Security and Telecommunications Infrastructure Act compliance creates fixed overhead that filters budget-tier imports from retail channels.
- Fragmented landlord ownership:Buy-to-let property dispersion across individual investors prevents coordinated building-scale upgrades, throttling per-structure system economics.
Strategic Opportunities
- Social housing retrofit programs:Local authority decarbonization tenders in Scotland and Wales represent underpenetrated volume channels with consolidated decision-making.
- Matter protocol convergence:Thread radio and IP-based device addressing is unifying previously siloed ecosystems, enabling cross-brand configuration tools that reduce installer training burdens.
- Energy optimization service fees:Smart thermostat vendors can capture recurring revenue through utility demand-response partnerships, shifting hardware margins toward software monetization.
Industry Challenges
- Electrical installer certification gaps:Shortage of technicians qualified for both mains voltage work and low-voltage network configuration extends project timelines for whole-home deployments.
- Legacy HVAC integration complexity:Boiler control interfaces in pre-2000 housing stock use proprietary analog signaling, requiring costly bridging hardware for smart thermostat compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Smart Home Market |
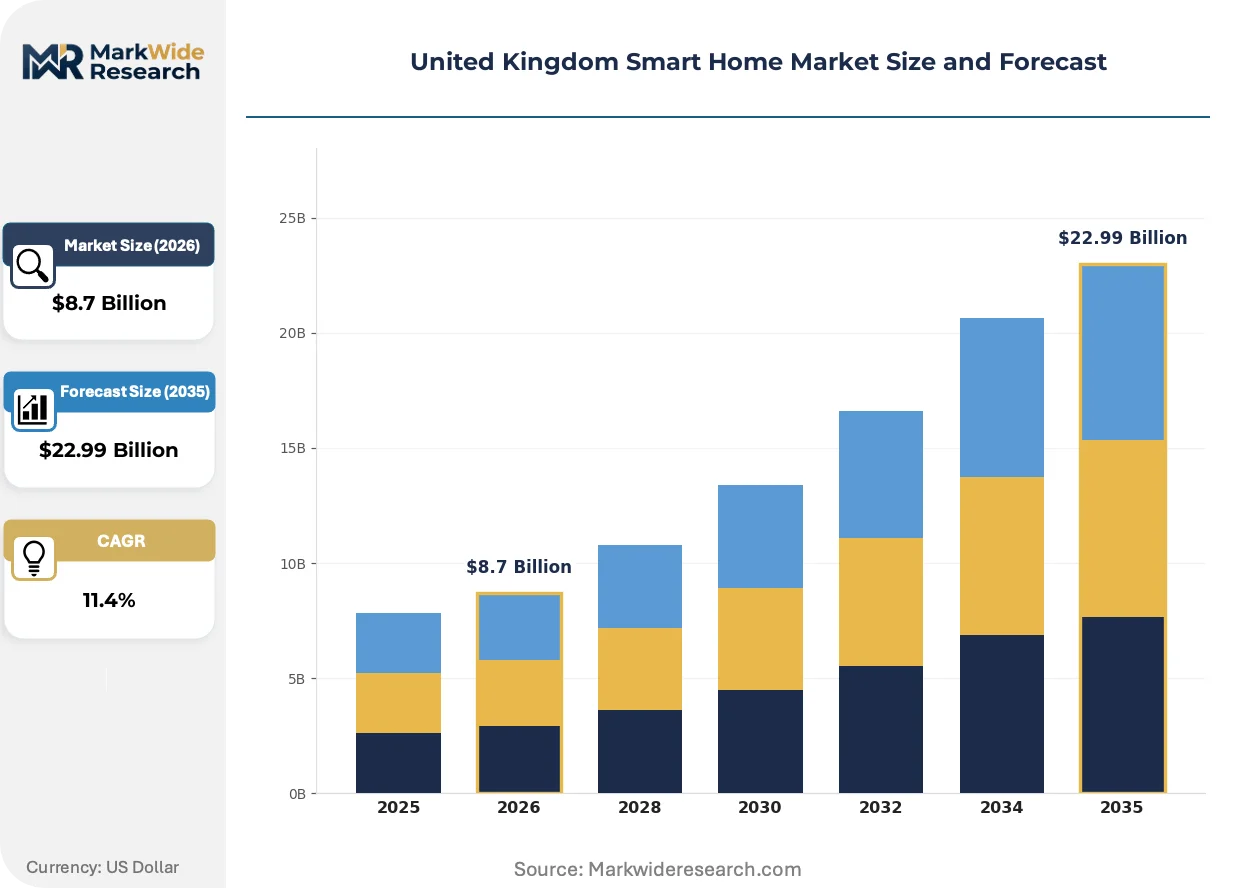
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Security Systems, Smart Speakers End User: Residential Customers, Property Developers, Retailers, Facility Managers Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Deployment: DIY Solutions, Professional Installations, Hybrid Systems, Managed Services |
| Companies Covered | Schneider Electric SE, Samsung Electronics Co., Ltd., ABB Ltd., Robert Bosch Smart Home GmbH, Philips Lighting (Signify Holding), Amazon.com Inc, Alphabet Inc, Hive (Centrica Connected Home), LG Electronics Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Smart Home Market Trends and Innovations
Device intelligence is migrating from cloud dependency toward edge processing, while regulatory pressure on energy performance is hardening interoperability requirements for building control systems.
Matter-over-Thread connectivity is unifying previously incompatible smart home ecosystems under a single application-layer protocol. Professional installers in South East England new-build developments are specifying Matter-certified devices to future-proof against ecosystem obsolescence. This convergence is compressing vendor differentiation strategies toward hardware quality and installation service rather than proprietary software lock-in.
BEIS Future Homes Standards mandate integrated building control systems that meet minimum thermal efficiency thresholds in all new residential construction. The regulation forces HVAC and lighting control vendors to certify combined system performance rather than individual component efficiency. Housebuilders in Greater London are responding by pre-specifying certified control packages to secure planning approvals.
Institutional landlords are consolidating smart home procurement through national framework agreements with installation service providers. Build-to-Rent operators in Birmingham and Leeds are displacing fragmented local contractor relationships with centralized facilities management contracts that include predictive maintenance analytics. This concentration is most visible in purpose-built rental developments where tenant turnover costs justify upfront system investment.
United Kingdom Smart Home Market Segmentation
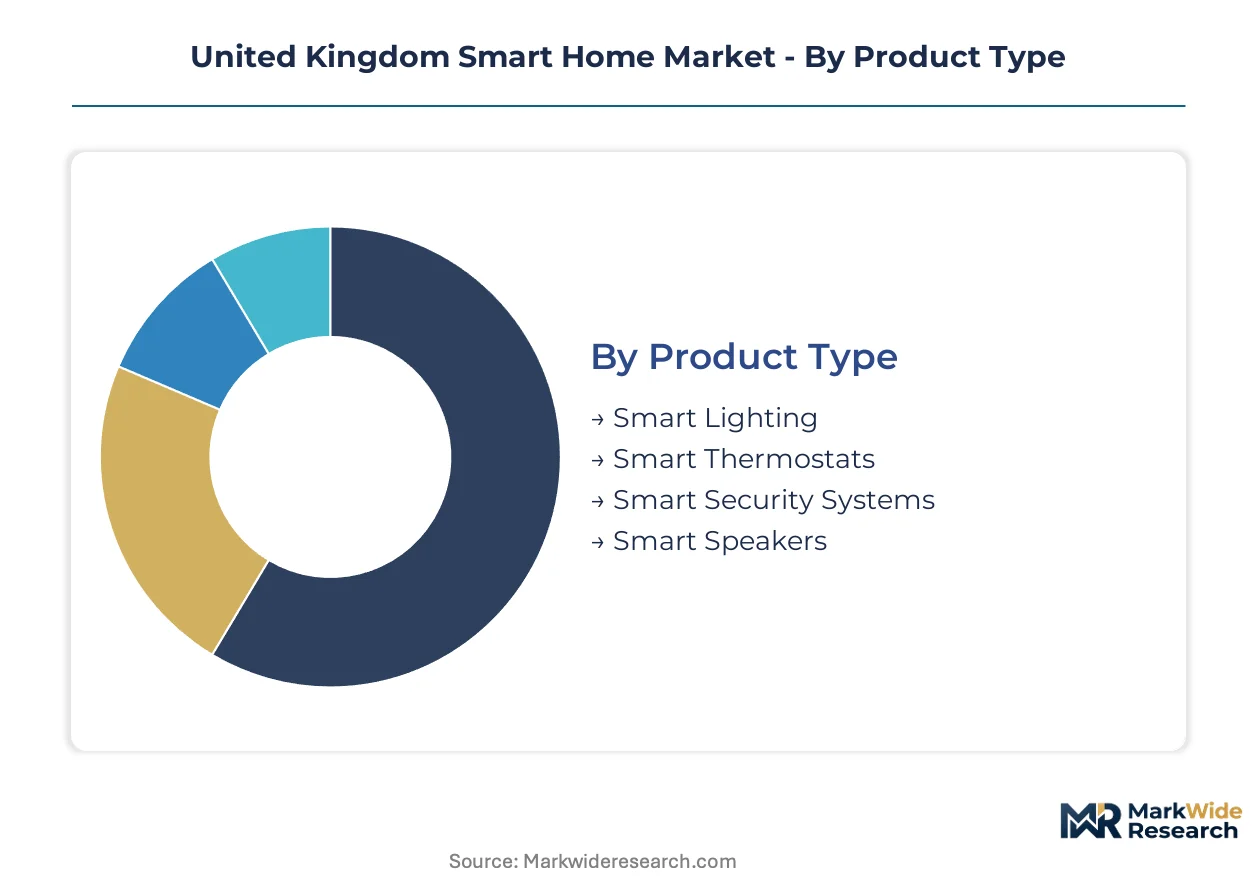
Smart home segmentation in the United Kingdom reveals divergent channel economics between mass-market DIY adoption and premium professional installation. Each dimension—product, buyer, protocol, and deployment mode—carries distinct margin profiles and regulatory exposure that shape vendor strategy.
Product Type:
Volume concentrates in entry-level devices while premium margins accrue to systems with recurring service components.
- Smart Lighting:LED fixture and control module bundles dominate retrofit volumes across Victorian and Edwardian housing stock. Demand clusters in Greater London buy-to-let conversions where landlords seek tenant-visible upgrades with minimal wiring disruption.
- Smart Thermostats:Boiler-integrated controllers with utility demand-response capability capture disproportionate margin pools through subscription energy optimization fees. BEIS Future Homes Standards mandate compatibility in new-build developments, forcing HVAC vendor certification.
- Smart Security Systems:Camera and sensor arrays with cloud storage subscriptions serve suburban owner-occupiers. Installation complexity sustains professional channel loyalty against DIY alternatives.
- Smart Speakers:Voice-first control hubs function as ecosystem gateways, with Amazon Echo and Google Nest hardware penetration driving downstream device attachment rates.
Today's leader: Smart Lighting. Tomorrow's challenger: Smart Thermostats.
End User:
Procurement authority is fragmenting from traditional retail toward institutional buyers with framework contracting power.
- Residential Customers:Owner-occupiers in South East England new-builds drive Matter-certified device demand. Purchase decisions favor interoperability assurance over proprietary ecosystem depth.
- Property Developers:Housebuilders in Greater London pre-specify integrated control packages to secure BEIS planning approvals. Procurement concentrates through national merchant relationships rather than consumer retail.
- Retailers:DIY multiples and electrical wholesalers face margin compression from direct-to-installer vendor bypass. Curated product selection shifts toward cybersecurity-certified SKUs under PSTI Act compliance pressure.
- Facility Managers:Build-to-Rent operators in Birmingham and Manchester displace fragmented landlord relationships with centralized smart home procurement including predictive maintenance analytics.
Property Developers command current volume. Facility Managers are gaining procurement concentration fastest.
Technology:
Protocol choice determines installer loyalty versus consumer accessibility trade-offs.
- Wi-Fi:Direct IP connectivity eliminates hub requirements for price-sensitive first-time adopters. Congestion in dense urban 2.4 GHz spectra limits whole-home reliability in multi-dwelling units.
- Zigbee:Mesh networking with sub-100 millisecond latency sustains professional installer certification programs. Interoperability certifications reduce ecosystem lock-in anxiety among electrical contractors.
- Z-Wave:Sub-GHz spectrum penetration excels in solid-wall Victorian construction where 2.4 GHz attenuation frustrates Wi-Fi deployments. Vendor certification costs limit budget-tier hardware availability.
- Bluetooth:Low-energy beacon protocols enable proximity-based automation for accessory control. Range constraints restrict whole-home coverage without mesh extension.
Zigbee anchors professional loyalty. Matter-over-Thread convergence is eroding protocol-specific differentiation.
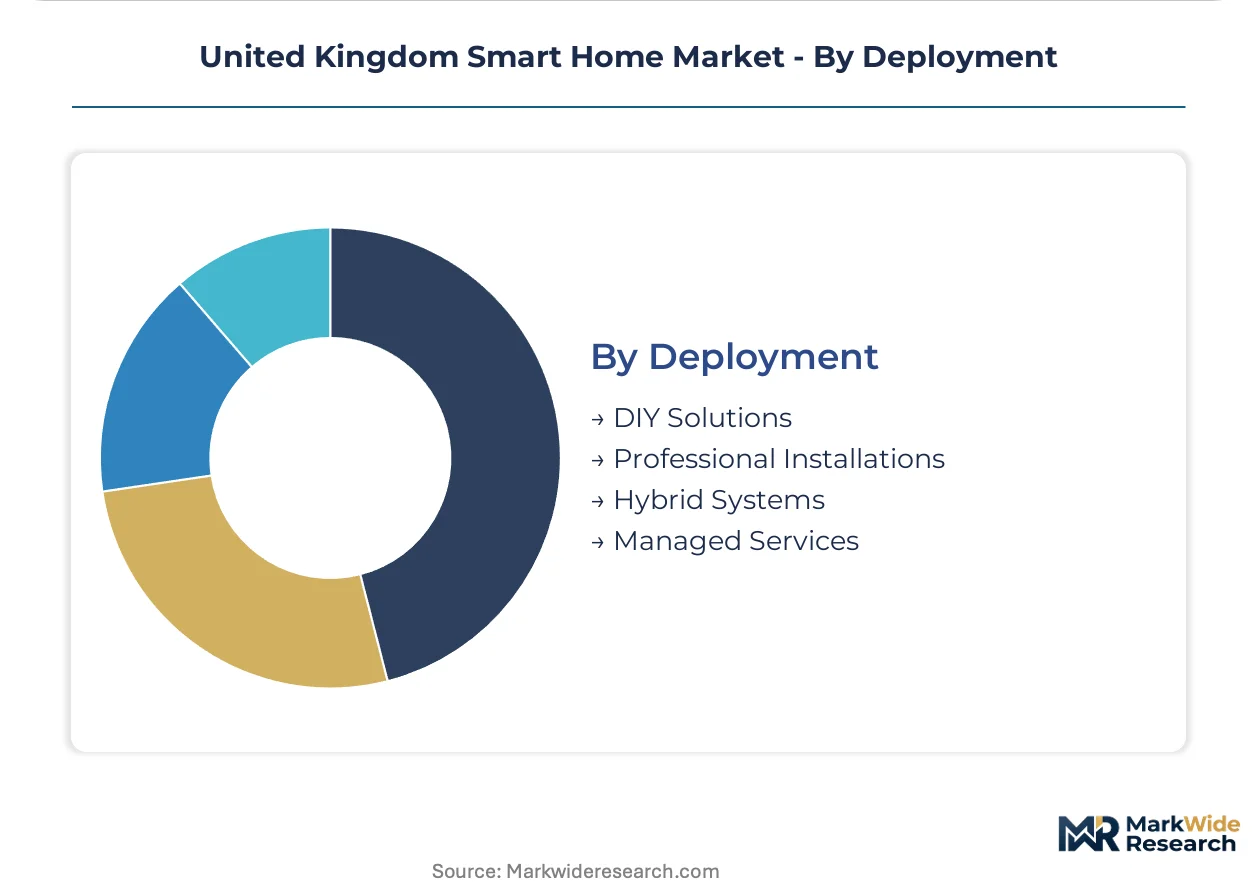
Deployment:
Service intensity separates one-time hardware margins from recurring revenue capture.
- DIY Solutions:Self-install kits with app-based configuration target tech-confident millennials in urban rental markets. Price transparency and review dependency compress brand premium extraction.
- Professional Installations:Mains-voltage qualified technicians configure integrated systems in heritage properties with legacy wiring. Shortage of dual-qualified electrical-network technicians extends project timelines.
- Hybrid Systems:Hub-and-spoke architectures combine professional backbone installation with consumer device expansion flexibility. Matter protocol adoption accelerates cross-brand compatibility.
- Managed Services:Subscription models with remote monitoring and predictive maintenance target Build-to-Rent institutional landlords. Service bundling shifts vendor economics toward recurring revenue.
Professional Installations dominate premium retrofit. Managed Services are climbing the fastest as institutional landlord concentration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England dominates UK smart home deployment volumes while Scotland's social housing retrofit programs present contrasting procurement dynamics. Wales and Northern Ireland trail in per-capita adoption but show concentrated institutional investment patterns.
Greater London and South East England
Build-to-Rent operators in London's purpose-built rental towers specify integrated smart home packages as tenant retention tools. BEIS Future Homes Standards mandate certified building control systems for all new residential construction. Housebuilders in Surrey and Kent counties pre-specify Matter-certified device packages to secure planning approvals ahead of 2025 compliance deadlines.
Midlands
Birmingham's institutional landlord concentration drives managed services procurement for multi-unit residential portfolios. Ofgem smart meter rollout obligations compel regional utility providers to subsidize gateway device installation. Build-to-Rent developments in Leicester and Nottingham displace fragmented local contractor relationships with centralized facilities management contracts.
North England
Manchester's rental market expansion attracts national framework agreements from installation service providers. Victorian and Edwardian housing stock in Leeds and Sheffield generates retrofit demand for Z-Wave mesh solutions that penetrate solid-wall construction. Local authority decarbonization tenders in Yorkshire represent underpenetrated volume channels with consolidated procurement authority.
Scotland
Social housing retrofit programs in Glasgow and Edinburgh concentrate decision-making through local authority tenders. Scottish Government energy efficiency mandates exceed England's BEIS standards, accelerating connected heating control upgrades. Highlands and Islands regions lag in adoption but receive targeted subsidy programs for rural property electrification.
Wales
Cardiff's new-build developments align with England's regulatory trajectory but at reduced deployment scale. Welsh Government Warm Homes program subsidizes smart thermostat installation in fuel-poor households. Swansea and Newport industrial zones host emerging device assembly operations serving UK retail channels.
United Kingdom Smart Home Market Competitive Landscape
French and German producers anchor the premium professional installation tier; South Korean and US technology specialists hold the consumer-facing ecosystem layer. Market structure splits between consolidated platform operators with voice-first control dominance and fragmented hardware vendors competing on interoperability certification. Three archetypes define competitive positioning: integrated building control specialists, consumer electronics ecosystem orchestrators, and utility-anchored energy service providers. Dominant competitive moves include strategic partnerships for Matter protocol certification and vertical integration into installation service networks.
Within the integrated building control tier, Schneider Electric SE and ABB Ltd. exemplify European industrial conglomerates that leverage professional installer certification programs to defend premium positioning. Samsung Electronics Co., Ltd. anchors the consumer electronics archetype through SmartThings platform breadth across white goods and entertainment devices. Amazon.com Inc occupies the voice-first control layer, with Echo hardware penetration driving downstream device attachment through Alexa Skills marketplace depth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Samsung Electronics Co., Ltd. |
| ABB Ltd. |
| Robert Bosch Smart Home GmbH |
| Philips Lighting (Signify Holding) |
| Amazon.com Inc |
| Alphabet Inc |
| Hive (Centrica Connected Home) |
| LG Electronics Inc |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer costs from East Asian foundries cascade through three distinct pricing tiers before reaching UK installers, with Matter-certified devices commanding premiums over uncertified alternatives while budget-tier imports face exclusion under PSTI Act compliance overhead.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for sensor chipsets that anchor device bill-of-materials. Three-tier pricing structure across premium professional installation, standard retail DIY, and economy grey-import segments stratifies by cybersecurity certification grade and after-sales service bundling. Pricing pressure stems from Ofgem-mandated smart meter subsidies that compress gateway device margins. Buy-to-let landlords in Greater London exhibit highest price sensitivity, while Build-to-Rent operators accept premium positioning for predictive maintenance inclusions.
Supply Chain Analysis
UK Product Security and Telecommunications Infrastructure Act certification gates retail channel access, filtering non-compliant hardware regardless of origin. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with sensor chipsets and radio modules drawing from East Asian foundry capacity. Single-source vulnerability in Zigbee and Z-Wave silicon supply exposes UK assemblers to geopolitical logistics disruption. Distribution runs through electrical merchant networks and direct-to-installer vendor bypass channels that displace traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Smart Home Market functions as a geographic-arbitrage play where regulatory stringency exceeds continental Europe, creating premium positioning opportunities for PSTI Act-compliant vendors against lower-standard imports.
For Market Incumbents: Hedge against Matter protocol commoditization by deepening installer certification programs that lock professional channel loyalty. Acquire predictive maintenance analytics capabilities to capture recurring revenue from Build-to-Rent operators. Defend margin position through backward integration into UK-based device assembly that reduces tariff exposure.
For New Entrants and Emerging Players: Edge-native processing architectures offer technology-first wedge into latency-sensitive security applications where cloud-dependent incumbents face reliability constraints. Target social housing retrofit tenders in Scotland and Wales where consolidated local authority procurement reduces customer acquisition costs. Pursue white-label partnerships with national electrical merchants rather than direct retail builds.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual-qualified electrical-network technician scarcity extends project timelines and fragments installer capacity. Five-to-ten year viability favors vendors with recurring service revenue streams over pure hardware plays. Monitor BSI Kitemark expansion into IoT security as inflection signal for compliance-cost barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-brand interoperability reduces installer training burdens and accelerates professional adoption. |
| Installer Network Acquisition | Captive installation capacity secures distribution control against electrical merchant intermediaries. |
| Energy Optimization Service Launch | Utility demand-response partnerships shift vendor economics toward recurring software monetization. |
| Predictive Maintenance Platform Development | Build-to-Rent operator retention tools justify upfront system investment in institutional portfolios. |
| Social Housing Framework Bidding | Consolidated local authority procurement in Scotland and Wales offers volume channel access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart home platform engineers, electrical contractor network managers, facilities procurement leads at Build-to-Rent operators, and BEIS policy implementation officers with secondary validation against Ofgem smart meter deployment statistics, UK Product Security and Telecommunications Infrastructure Act consultation documents, and housebuilder planning application databases. Bottom-up device shipment estimates and top-down construction activity indices underwent cross-referencing for triangulation.
Historical reference periods anchored the projection horizon through verified installation volumes and regulatory implementation timelines. Segmentation modeling spanned product category, deployment mode, protocol technology, and end-user archetype across the analysis window. CAGRs derived from fitted growth curves calibrated to policy mandate deadlines and housing stock turnover rates. Forecast inputs incorporated BEIS Future Homes Standards compliance thresholds and Ofgem smart meter rollout obligation trajectories.
The model holds under stable regulatory enforcement and continued East Asian semiconductor supply availability; deviation in geopolitical trade restrictions or BSI Kitemark scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Tennis Shoes Market
Consumer Goods
Europe Cigarette Lighter Market
Consumer Goods
Lawn and Garden Water Equipment Market
Consumer Goods
Pet Transporting Service Market
Consumer Goods
Brazil Luxury Goods Market
Consumer Goods
Europe Aromatherapy Diffuser Market
Consumer Goods
Caffeine Eye Creams Market
Consumer Goods
Colombia Laundry Appliances Market
Consumer Goods
Baby Gate Market
Consumer Goods
Infuser Water Bottles Market
Consumer Goods
US Fanny Packs Market
Consumer Goods
United States Laundry Appliances Market
Consumer Goods
Personal Flotation Devices Market
Consumer Goods
Driving Footwear Market
Consumer Goods
Audio Jack Market
Consumer Goods
Outdoor Pet Backpack Market