
 High-End French Door Refrigerator Market | 2026-2036
High-End French Door Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
High-End French Door Refrigerator Market Insights
Subscription-based filter replacement and software-defined cooling management is consolidating around major appliance ecosystems. LG leverages its ThinQ platform to anchor recurring revenue streams alongside hardware sales. Samsung competes through SmartThings integration that extends connectivity across kitchen and home automation layers. Sub-Zero specializes in built-in configurations that dominate ultra-premium residential channel control.
A high-end French door refrigerator is a full-size refrigeration appliance with side-by-side upper doors and a bottom freezer drawer, typically featuring dual evaporator systems, stainless steel or panel-ready exteriors, and internal capacities exceeding 20 cubic feet, designed for residential and commercial food preservation with precise temperature zoning. Built-in and counter-depth product types command the deepest margin pools due to custom installation requirements and longer replacement cycles. Smart connectivity technology leads growth velocity as touchscreen interfaces and app-based energy management reshape buyer expectations. Residential end users sustain the largest volume base, though luxury homes represent the fastest-expanding sub-segment for premium finishes.
The U.S. Department of Energy and the EPA's ENERGY STAR program shape efficiency benchmarks and eligibility for consumer rebates, directly influencing compressor technology roadmaps and insulation material choices. The EU F-Gas Regulation and Ecodesign requirements from the European Commission restrict refrigerant types and mandate minimum efficiency performance, creating compliance barriers for non-European manufacturers. Stakeholders must monitor how refrigerant phase-down schedules intersect with smart-feature development costs to preserve margin structure.
Market Dynamics
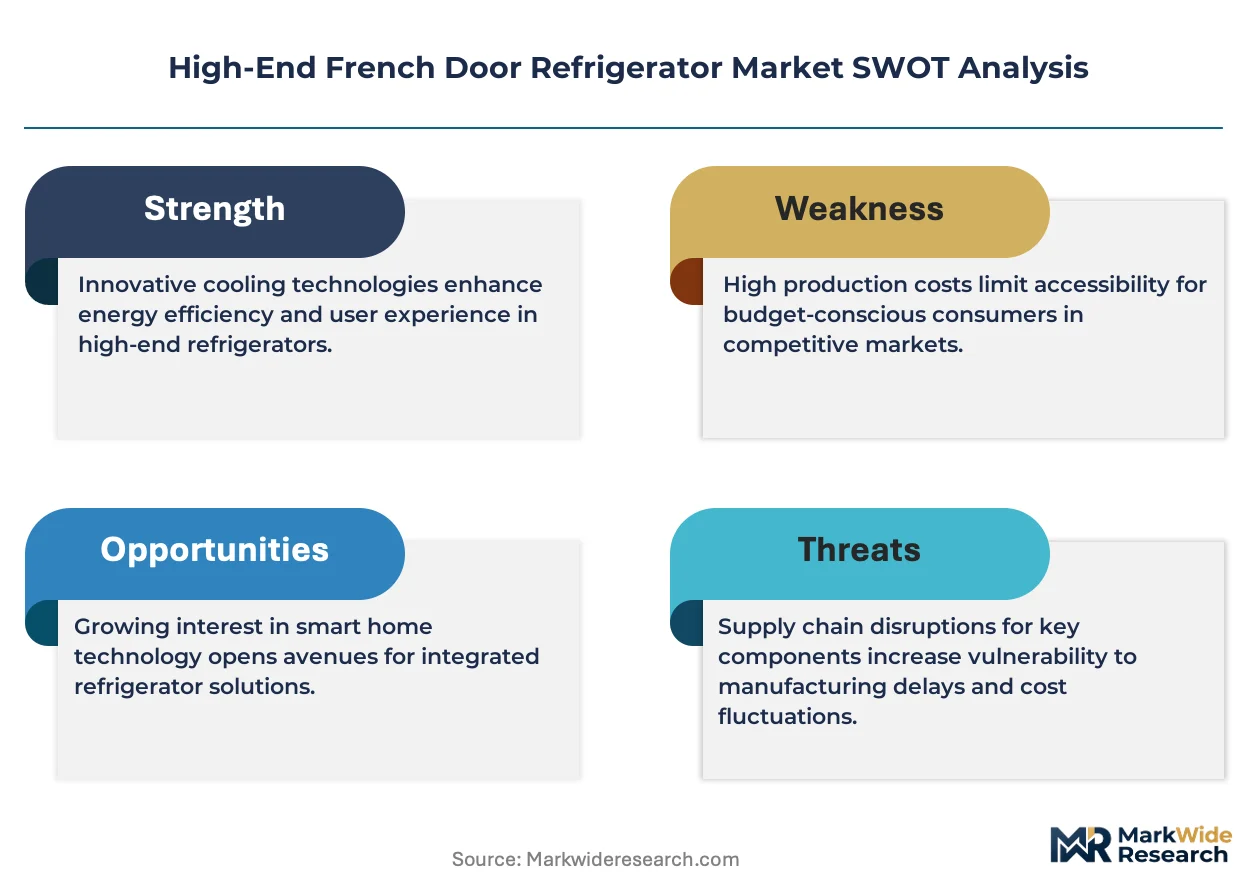
Dual-evaporator cooling architecture and variable-speed compressor migration are compressing replacement cycles while elevating technical barriers for component suppliers. The U.S. Department of Energy's efficiency standards are accelerating R&D investment toward software-defined thermal management.
Growth Catalysts
- Smart-home ecosystem integration:Connected kitchen platforms in luxury residential developments across Dubai and Riyadh are mandating app-controllable appliances. Developers specify WiFi-enabled units with touchscreen interfaces.
- F-Gas Regulation phase-down:The EU's refrigerant restrictions are forcing compressor redesigns toward lower-GWP alternatives. European manufacturers gain first-mover compliance advantages.
- Kitchen renovation cycles:Premium homeowners in the United States, South Korea, and Germany are replacing appliances every 8-10 years. Built-in configurations capture margin from custom cabinetry integration.
Market Restraints
- Copper and aluminum price volatility:Compressor and heat exchanger production faces input cost swings. Manufacturers struggle to pass through material inflation in contracted builder channels.
- Panel-ready supply concentration:Custom exterior fabrication concentrates among Italian and German specialist metalworkers. Lead times extend to 14-16 weeks for bespoke finishes.
- Refrigerant IP licensing:Proprietary blends from chemical suppliers impose royalty structures. Smaller OEMs face margin compression against vertically integrated competitors.
Strategic Opportunities
- Subscription filter services:Water and air filtration cartridges generate recurring revenue. LG's ThinQ platform demonstrates ecosystem anchoring potential.
- Commercial foodservice crossover:High-end residential styling penetrates boutique hospitality. Small restaurants specify counter-depth units for open-kitchen visibility.
- ENERGY STAR rebate stacking:The EPA program combines with state-level incentives. California and New York buyers recover 15-20% of purchase price through utility partnerships.
Industry Challenges
- Software engineering talent scarcity:Firmware development for IoT connectivity competes with automotive and medical device sectors. Appliance OEMs struggle to retain embedded systems engineers.
- Dual-certification timelines:Products must satisfy both DOE efficiency testing and FCC wireless emissions standards. Parallel approval processes extend launch windows by 4-6 months.
- Legacy BMS integration:Smart refrigerators must communicate with existing home automation protocols. Compatibility testing against fragmented third-party systems consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End French Door Refrigerator Market |
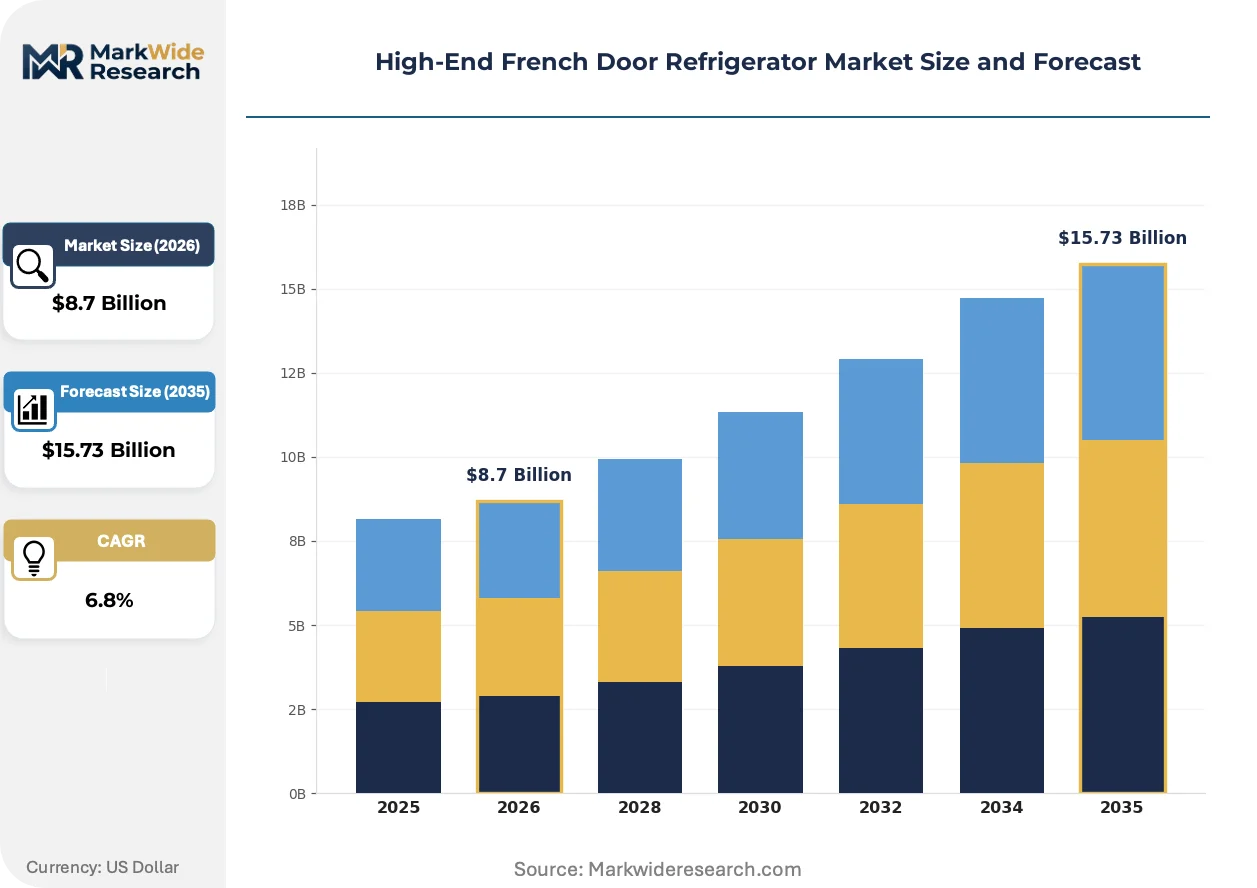
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counter-Depth, Built-In, Freestanding, Modular Technology: Smart Connectivity, Energy-Efficient, Dual Cooling, Touchscreen End User: Residential, Commercial, Luxury Homes, Apartment Complexes Feature: Water Dispenser, Ice Maker, Adjustable Shelves, LED Lighting |
| Companies Covered | LG, GE Appliances, Bosch, Café Appliances, Samsung, Sub-Zero, Thermador, Monogram, Miele, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End French Door Refrigerator Market Trends and Innovations
Refrigeration technology is converging with digital infrastructure and sustainable chemistry. Manufacturers are repositioning hardware margins around software-defined service layers.
Variable-speed inverter compressors are integrating with AI-driven load prediction algorithms. Premium residential buyers in Germany and South Korea specify units that adapt cooling intensity to usage patterns detected via door sensors. This capability is integrating energy optimization with predictive maintenance alerts, compressing traditional service contract models into bundled hardware-software offerings.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is mandating R-600a and R-290 hydrocarbon transitions. Compressor manufacturers must redesign seals and electrical safety systems for flammable refrigerants. European-built units are responding with proprietary charging protocols that limit aftermarket servicing to certified technicians, creating channel control advantages.
Builder procurement is consolidating around single-brand kitchen packages. Luxury developers in Dubai specify full-suite appliance contracts rather than mix-and-match configurations. Samsung's SmartThings and LG's ThinQ ecosystems are capturing these bundled decisions through pre-installation integration testing, locking out standalone competitors from new-construction channels.
High-End French Door Refrigerator Market Segmentation
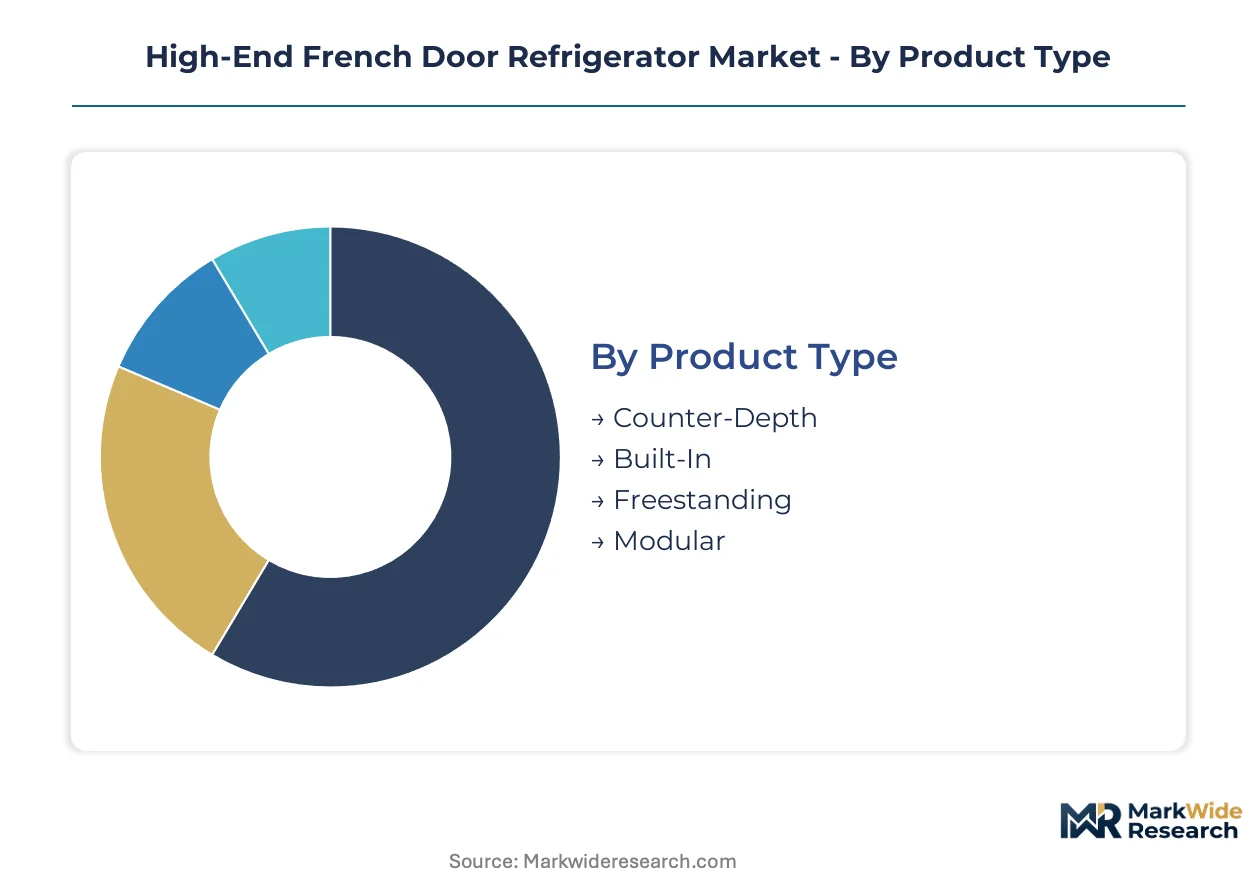
Segmentation in high-end French door refrigeration reveals how certification requirements, installation complexity, and connectivity specifications fragment procurement channels. Builders, renovators, and commercial operators each face distinct compliance burdens that reshape vendor selection criteria.
Product Type:
Built-in configurations require UL and FCC certification for integrated electrical systems, while counter-depth units face additional ENERGY STAR testing for depth-constrained insulation performance. Modular systems trigger the most fragmented approval landscape across jurisdictions.
- Counter-Depth:Shallower profiles align with standard cabinetry at 24-inch depths, sacrificing 3-5 cubic feet of capacity. Demand concentrates in United States kitchen renovations where flush aesthetics command premium positioning alongside smart-home integration requirements.
- Built-In:Panel-ready exteriors and compressor-forward engineering enable seamless architectural integration. Luxury residential developments in Dubai and Riyadh specify these units for developer-controlled finish matching, extending replacement cycles to 12-15 years.
- Freestanding:Standard-depth units with finished sides suit flexible placement.
- Modular:Separate refrigeration and freezer columns allow customized spatial configuration.
Freestanding sits at the top of the volume ranking, with built-in climbing the fastest.
Technology:
Technology tiers separate hardware-only offerings from software-anchored ecosystems, with certification costs escalating proportionally to connectivity depth.
- Smart Connectivity:WiFi-enabled units with app-based temperature management and predictive maintenance alerts. South Korean and German buyers prioritize these systems for integration with existing home automation protocols, driving firmware update subscription models.
- Dual Cooling:Independent evaporators for refrigerator and freezer compartments prevent odor transfer and humidity migration. This architecture dominates premium residential specifications where precise preservation of organic produce and wine collections justifies cost premiums.
- Energy-Efficient:Variable-speed compressors meeting DOE and EU Ecodesign thresholds.
- Touchscreen:Embedded displays for inventory management and recipe integration.
Energy-efficient units anchor baseline procurement volumes, while smart connectivity expands most quickly.
End User:
End-user segmentation maps directly to replacement cycle timing and specification authority concentration.
- Residential:Owner-occupied homes with 8-10 year renovation-driven replacement patterns. United States households concentrate demand for ENERGY STAR rebate eligibility, compressing payback periods through utility partnership programs.
- Luxury Homes:Custom builds and whole-home renovations where appliance selections occur during architectural design phases. Developers in Dubai bundle full-suite specifications, locking out standalone competitors through pre-installation integration testing.
- Commercial:Boutique hospitality and small restaurants requiring open-kitchen visibility.
- Apartment Complexes:Multi-unit residential with standardized specifications and bulk procurement.
Residential commands absolute volume leadership, with luxury homes gaining share fastest.
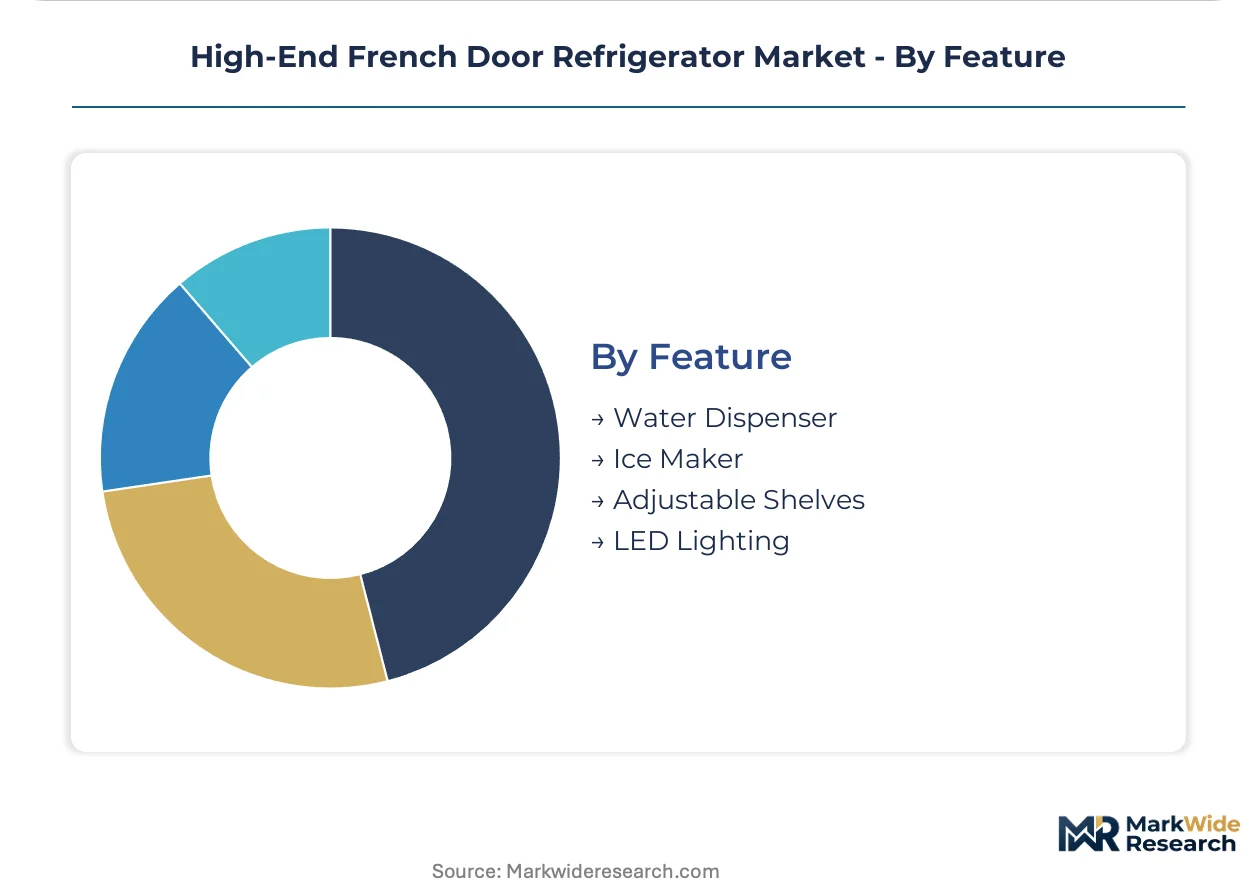
Feature:
Feature bundling determines aftermarket revenue potential and installation complexity.
- Water Dispenser:Filtered dispensing systems with replaceable cartridges generating recurring revenue streams. EPA and state-level water quality certifications add compliance layers that favor established OEMs with testing infrastructure.
- Ice Maker:Clear ice and nugget variants for premium entertaining. German and South Korean buyers specify these for residential bar and beverage station integration, driving dual-compressor configurations.
- Adjustable Shelves:Modular interior configurations for flexible storage.
- LED Lighting:Energy-efficient interior illumination with color temperature control.
Water dispenser installations dominate feature penetration, with ice maker specification climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany diverge in replacement cycle timing, with American households renovating every 8-10 years while German buyers extend intervals to 12-15 years for built-in configurations. This temporal gap creates distinct inventory and service contract strategies for manufacturers serving each market.
United States
ENERGY STAR rebate programs compress payback periods for variable-speed compressor units. The EPA partners with California and New York utilities to recover 15-20% of purchase price. Premium kitchen renovations concentrate in coastal metros and Texas growth corridors.
Germany
EU Ecodesign requirements and F-Gas Regulation phase-downs mandate R-600a hydrocarbon transitions. The KBA's indirect influence through industrial standards shapes compressor safety protocols. Baden-Württemberg engineering clusters dominate variable-speed inverter development.
South Korea
Smart-home integration rates exceed global averages in Seoul Capital Area developments. The MFDS regulates water filtration certifications for dispenser-equipped units. Busan-Ulsan manufacturing corridors anchor compressor and electronics component supply.
United Arab Emirates
Luxury residential developments in Dubai mandate app-controllable appliances through developer specifications. MOHAP oversees product safety import standards. Panel-ready configurations dominate new-construction channels with 14-16 week custom finish lead times.
Saudi Arabia
Riyadh's luxury housing boom drives built-in refrigerator demand through bundled kitchen packages. The SFDA regulates food-contact materials and water quality standards. Eastern Province industrial zones supply regional distribution hubs serving Gulf Cooperation Council markets.
High-End French Door Refrigerator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-anchored players capturing bundled new-construction decisions while standalone fabricators serve renovation channels. The vendor base concentrates around three tiers: full-suite appliance ecosystems, ultra-premium built-in specialists, and mid-premium connectivity-focused brands. Strategic archetypes include ecosystem bundlers, custom installation specialists, and component-integrated manufacturers. Dominant competitive moves involve pre-installation integration testing for developer lock-in and subscription service layering atop hardware margins.
Within the ecosystem-anchored tier, LG and Samsung represent the convergence of smart-home platform control with appliance hardware. LG exemplifies recurring revenue architecture through filter subscription services tied to its ThinQ platform. Samsung occupies a position spanning kitchen and whole-home automation through SmartThings integration. Sub-Zero anchors the ultra-premium built-in specialist archetype, commanding channel control in custom architectural specifications where replacement cycles extend longest.
| Leading Market Players |
|---|
| LG |
| GE Appliances |
| Bosch |
| Café Appliances |
| Samsung |
| Sub-Zero |
| Thermador |
| Monogram |
| Miele |
| Others |
Pricing and Supply Chain Analysis
Compressor engineering talent concentration in Baden-Württemberg and Busan-Ulsan corridors feeds labor-cost differentials that widen pricing-tier spreads between mass-market variable-speed units and ultra-premium built-in configurations with proprietary charging protocols.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for variable-speed compressor modules, compressing margins on mid-tier smart connectivity offerings. Pricing stratifies across premium built-in, standard counter-depth, and economy freestanding tiers based on certification grade and custom finish complexity. Pricing pressure stems from copper and aluminum volatility that manufacturers struggle to pass through contracted builder channels. Luxury home developers exhibit lowest price sensitivity; apartment complex procurement teams demonstrate highest.
Supply Chain Analysis
Single-source vulnerability sits with Italian and German specialist metalworkers for panel-ready exterior fabrication. Manufacturing concentrates in South Korea, China, and Germany for compressor electronics, heat exchangers, and hydrocarbon-compatible sealing systems. The chain draws from copper rod, aluminum coil, and refrigerant chemical feedstocks. Tariff exposure on Chinese compressor components creates structural risk. Distribution runs through developer-specified builder channels, retail kitchen renovation specialists, and commercial foodservice equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Replacement cycles compress toward premium specifications as ENERGY STAR rebate stacking and smart-home integration mandates reshape buyer calculus.
For Market Incumbents: Hedge refrigerant transition risk by securing hydrocarbon compressor supply agreements before EU F-Gas phase-down deadlines tighten. Deepen backward integration into water filtration cartridge production to capture subscription revenue streams that LG's ThinQ platform already demonstrates. Software engineering talent scarcity from automotive and medical device competitors threatens IoT roadmap execution. For New Entrants and Emerging Players: Boutique hospitality channel partners offer lowest barrier-to-entry for counter-depth units with residential styling and open-kitchen visibility. Target commercial foodservice crossover applications where small restaurants prioritize aesthetic integration over full commercial specifications. White-space sits in ENERGY STAR rebate-eligible value-tier smart connectivity for cost-conscious renovators. For Investors and Strategic Acquirers: Full-suite appliance ecosystems are the most active acquirer in this space, seeking compressor technology and smart-platform engineering teams. Five-to-ten year viability hinges on software-defined service revenue attachment rates overtaking hardware margin dependence. Watch for inflection when subscription filter attach rates cross threshold penetration in developer-controlled new-construction channels.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Platform Integration | ThinQ and SmartThings ecosystems lock out standalone competitors through pre-installation testing protocols. |
| Hydrocarbon Compressor Transition | R-600a and R-290 redesigns satisfy EU F-Gas Regulation while creating aftermarket channel control. |
| Subscription Filter Services | Recurring revenue from water and air cartridges anchors lifetime customer value beyond hardware margins. |
| Developer Bundle Contracts | Full-suite kitchen specifications in Dubai and Riyadh capture new-construction decisions before renovation channels activate. |
| ENERGY STAR Rebate Stacking | Utility partnerships in California and New York recover purchase premiums and accelerate payback periods. |
Research Methodology
Multiple input streams — appliance manufacturer R&D executives, luxury residential developers in Dubai and Riyadh, kitchen renovation contractors, and compressor component procurement leads — were reconciled against customs records, ENERGY STAR certification databases, and SEC appliance segment disclosures. Secondary validation drew from EU Ecodesign implementation reports, EPA rebate program documentation, and F-Gas Regulation compliance filings. Bottom-up unit shipment estimates and top-down market value reconstruction were triangulated for convergence.
Data-stream reconciliation applied product type, technology tier, end-user segment, and feature bundling dimensions across the projection horizon. CAGRs were derived from replacement cycle timing, smart-home penetration curves, and refrigerant transition compliance schedules. Forecast inputs included builder procurement consolidation rates and software subscription attach rate trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, refrigerant IP licensing disputes, and software engineering talent retention. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Home Appliances Glass Market
Home Appliances
Household Appliance Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
UK Household Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market