
 Green Smart Household Appliances Market | 2026-2036
Green Smart Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Green Smart Household Appliances Market Insights
The capital-intensity gap between integrated manufacturers and assembly-dependent competitors is collapsing as in-house semiconductor and compressor production becomes mandatory for energy-optimization features. Samsung Electronics leverages its captive chip foundry to dominate connected-kitchen system-on-chip supply. LG Electronics anchors its position through backward integration into linear compressor technology, locking in variable-speed refrigeration cycles that competitors license at margin cost.
Green smart household appliances combine embedded sensors, machine-learning control algorithms, and low-global-warming-potential refrigerants to minimize energy consumption while enabling remote diagnostics and grid-interactive load management. Wi-Fi-enabled units now lead volume shipments, though Zigbee deployments are accelerating fastest among multi-appliance ecosystems where mesh-network reliability outperforms router-dependent protocols. Residential end users still occupy the dominant demand pool, but rental properties represent the fastest-expanding channel as European landlords outfit units to comply with tightening building energy certificates.
The EU Green Deal and F-Gas Regulation drive refrigerant-phaseout timelines that reshape product roadmaps across European manufacturing lines, while EPA SNAP rules in the United States enforce parallel hydrofluorocarbon restrictions. China's GB standards for smart-home interoperability, administered by MIIT, create compliance barriers that favor domestic champions with established certification relationships. Stakeholders must decide whether to absorb the capital burden of multi-protocol control-technology stacks or accept channel exclusion in markets with divergent connectivity mandates.
Market Dynamics
Semiconductor and compressor in-house production now determines competitive survival as energy-optimization features become baseline requirements rather than premium differentiators.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for hydrofluorocarbon refrigerants forces appliance refresh cycles across European manufacturing lines, accelerating replacement demand for low-global-warming-potential units.
- AI-integrated cooling systems:China's MIIT smart-grid interoperability mandates tie national infrastructure rollout directly to appliance procurement specifications, concentrating demand among certified domestic suppliers.
- Carbon-neutral building standards:Japan's METI-backed certification programs for multi-unit residential complexes create procurement obligations for grid-responsive appliances in new construction and retrofit projects.
Market Restraints
- Copper and rare-earth magnet costs:Variable-speed motor and compressor manufacturing faces input price volatility that compresses margins for assembly-dependent competitors lacking captive material sourcing.
- Taiwan semiconductor foundry concentration:System-on-chip supply for connected-kitchen ecosystems rests on a narrow geographic base, exposing appliance manufacturers to geopolitical disruption risk.
- Refrigerant thermodynamic limits:Hydrocarbon and CO2 alternatives impose efficiency penalties in high-ambient-temperature climates, restricting product viability in specific geographic markets.
Strategic Opportunities
- European rental property channel:Landlords outfitting units to meet tightening building energy certificate requirements represent an underpenetrated procurement segment with volume concentration potential.
- Zigbee mesh ecosystems:Multi-appliance installations favor protocol reliability over router-dependent Wi-Fi, creating white space for ecosystem vendors with certified interoperability stacks.
- US IRA efficiency rebates:Federal incentive programs for electrification and grid-interactive appliances reduce consumer price elasticity and compress payback periods for premium product tiers.
Industry Challenges
- Embedded firmware engineering talent:Machine-learning control algorithm development requires specialized skill sets that appliance manufacturers compete with automotive and consumer electronics sectors to secure.
- Multi-protocol certification timelines:Divergent connectivity mandates across China's GB standards, EU CE marking requirements, and US FCC regulations extend product launch cycles and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Smart Household Appliances Market |
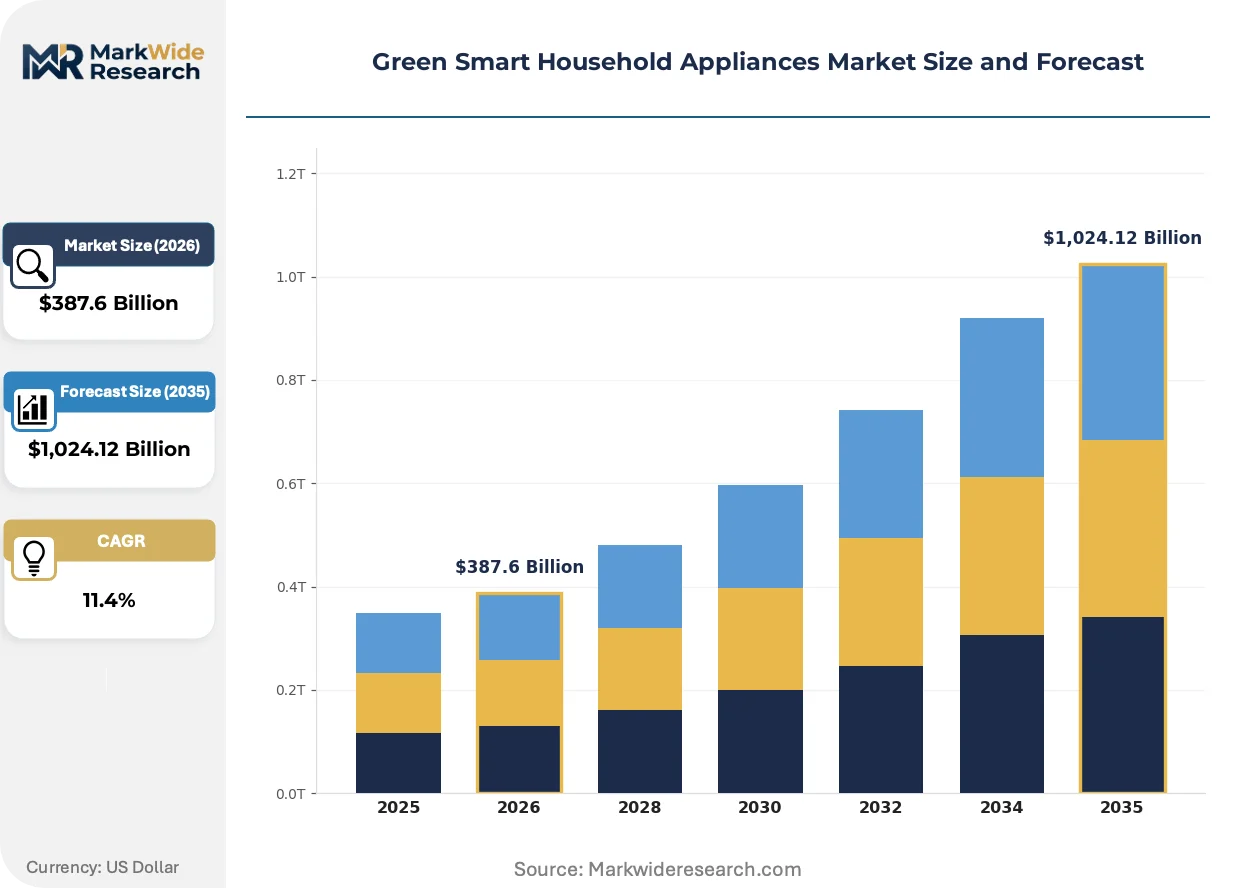
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Microwaves Energy Source: Solar, Electric, Gas, Hybrid Control Technology: Wi-Fi, Bluetooth, Zigbee, NFC End User: Residential, Commercial, Institutions, Rental Properties |
| Companies Covered | Samsung Electronics, LG Electronics, Haier Smart Home, Whirlpool Corporation, Bosch Home Appliances, Electrolux AB, General Electric Company, Panasonic Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Smart Household Appliances Market Trends and Innovations
Refrigerant chemistry, connectivity architecture, and procurement channel structure are undergoing simultaneous transformation that redefines product roadmaps and competitive positioning.
Variable-speed linear compressor technology is supplanting fixed-speed reciprocating designs in premium refrigeration segments. German and Japanese residential complexes specify these units for grid-responsive load management. The technology compresses energy consumption curves while enabling real-time utility communication protocols.
EPA SNAP rules enforce parallel hydrofluorocarbon restrictions to EU F-Gas timelines, forcing US manufacturers to synchronize refrigerant transitions across Atlantic and Pacific product lines. Commercial refrigeration and residential heat pump categories face the steepest compliance cost escalations. Domestic suppliers accelerate propane and CO2 platform development to maintain market access.
Landlord-driven bulk procurement is fragmenting traditional retail channel dominance in European urban markets. Property management platforms specify certified appliance packages to streamline energy certificate compliance. This pattern concentrates most visibly in German and Dutch rental housing stock where regulatory enforcement is strictest.
Green Smart Household Appliances Market Segmentation
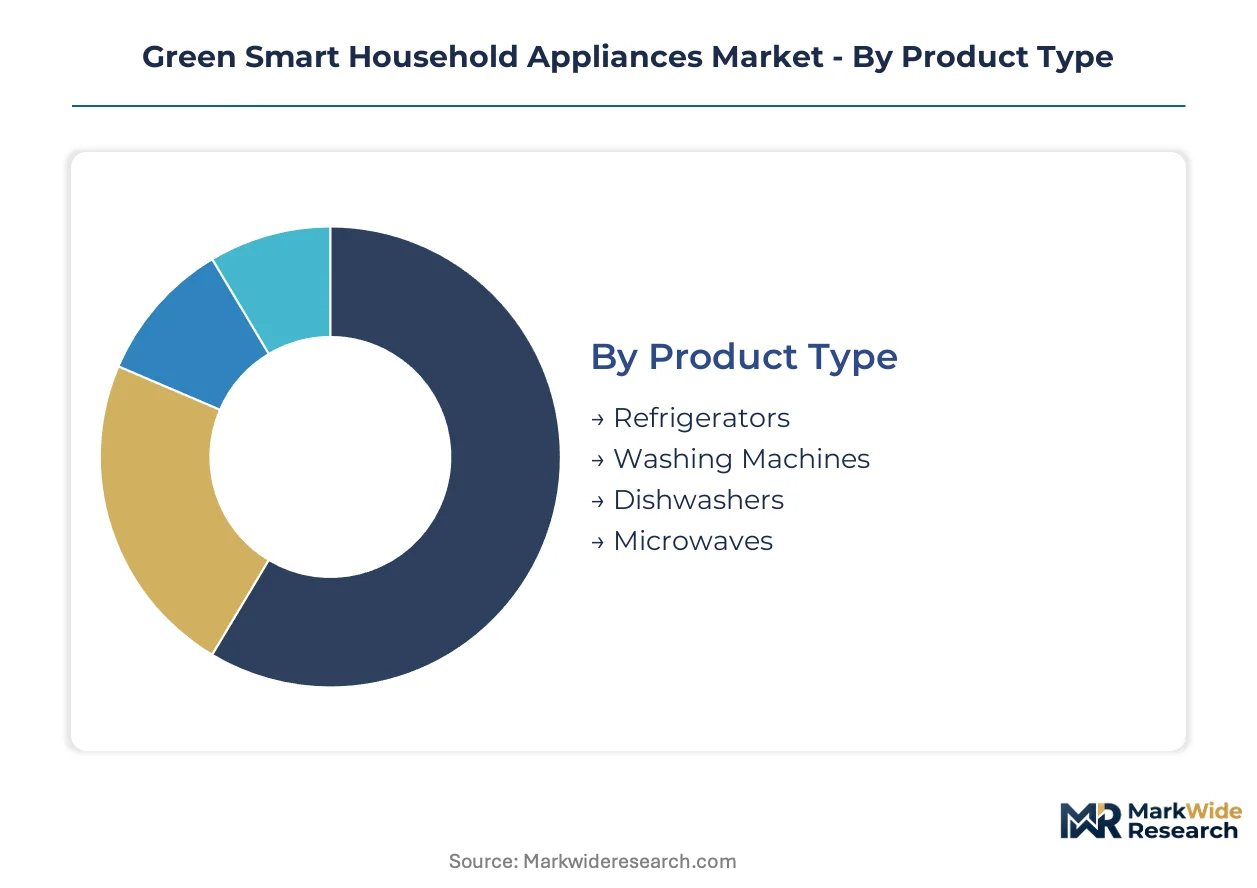
Segmentation in green smart household appliances reveals how procurement channels, connectivity mandates, and energy compliance requirements fragment demand across incompatible specification regimes. Manufacturers must align product configurations with distinct regulatory and customer-type requirements rather than pursuing universal platform strategies.
Product Type:
Refrigeration platforms dominate export-led manufacturing from South Korea and China, while washing machine assembly concentrates in European domestic production serving landlord procurement channels.
- Refrigerators:Linear compressor architectures with variable-speed cycles enable real-time grid communication protocols demanded by Japan's METI-certified residential complexes. German urban developments specify these units for building energy certificate compliance, locking in premium procurement volumes.
- Washing Machines:Motor-inverter integration with load-sensing algorithms reduces water and energy draw per cycle. European rental property channels drive replacement demand as landlords retrofit units to meet tightening efficiency mandates.
- Dishwashers:Heat-pump drying systems replace resistive elements in premium tiers.
- Microwaves:Solid-state RF heating modules displace magnetron architectures in connected-kitchen ecosystems.
Refrigerators command the established base. The steepest expansion runs through washing machines.
Energy Source:
Cost-tier stratification separates premium solar-hybrid installations from standard electric-grid units, with gas platforms retreating to legacy replacement markets.
- Solar:DC-coupled appliance architectures bypass inverter losses in off-grid and net-zero residential installations. Australia's high rooftop penetration rates concentrate demand for solar-native refrigeration and cooling systems with battery-buffered operation.
- Electric:Grid-interactive load management features align with China's MIIT smart-home interoperability standards. Domestic suppliers with certified protocol stacks capture concentrated procurement from national infrastructure rollout programs.
- Gas:Absorption-cycle refrigeration persists in recreational vehicle and remote-site applications.
- Hybrid:Dual-source heat pumps switch between electric compressor and gas-fired operation based on utility rate signals.
Electric platforms anchor current volume. Solar configurations are gaining share fastest in high-penetration rooftop markets.
Control Technology:
Customer-type preferences split between router-dependent consumer installations and mesh-network reliability demanded by multi-unit property managers.
- Wi-Fi:Ubiquitous protocol support reduces certification overhead for mass-market distribution. Volume shipments concentrate in North American retail channels where single-appliance replacement dominates purchasing patterns.
- Zigbee:Mesh-network topology eliminates single-point-of-failure risks in multi-appliance installations. European rental property specifications increasingly mandate Zigbee-certified ecosystems for centralized energy management.
- Bluetooth:Proximity-based commissioning simplifies initial setup for smartphone-centric users.
- NFC:Tap-to-pair functionality accelerates service technician diagnostics in commercial maintenance contracts.
Wi-Fi retains the volume base. Zigbee climbs the fastest as property-management platforms consolidate procurement specifications.
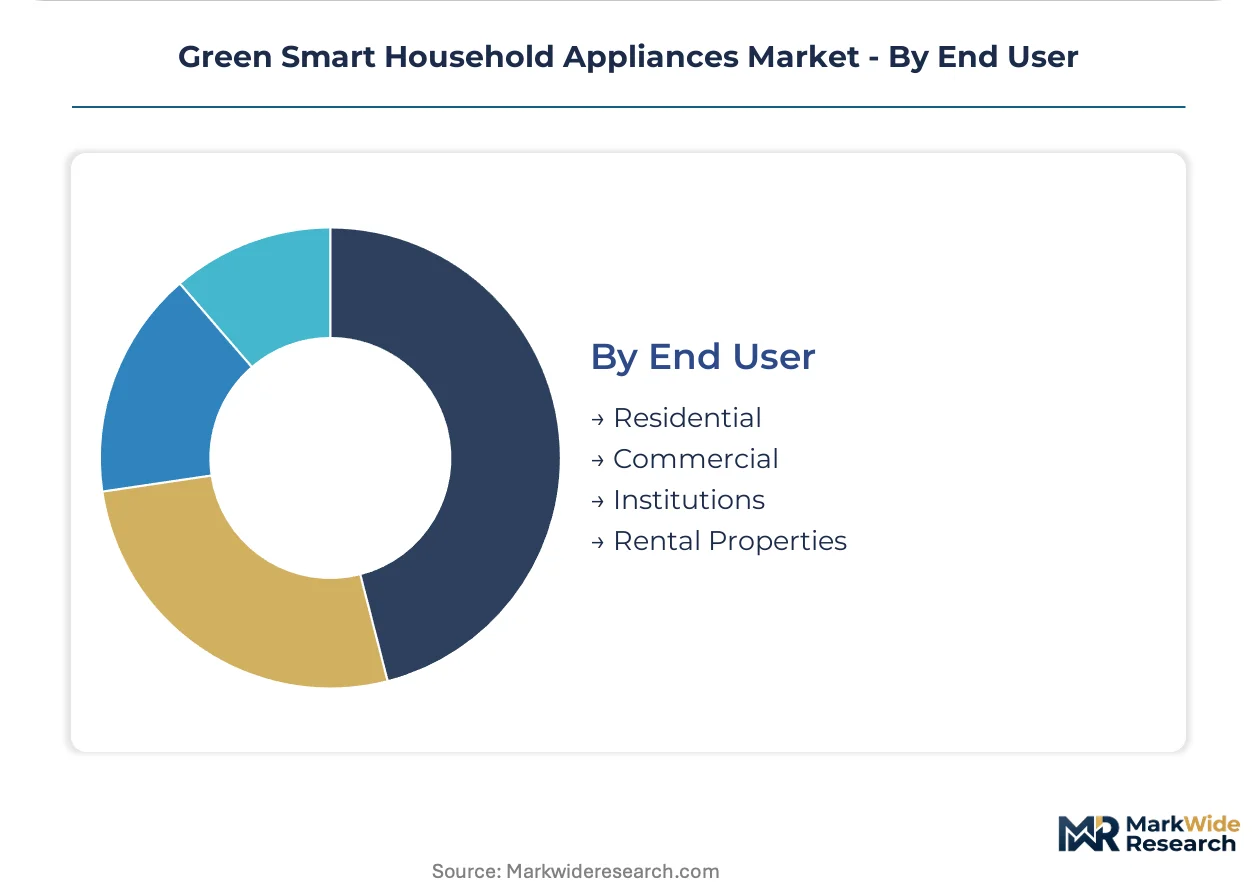
End User:
Maturity differentials separate saturated residential replacement cycles from emerging institutional and rental channels with concentrated volume potential.
- Residential:Individual household procurement drives replacement demand tied to appliance lifecycle expiration. Energy-optimization features compete on payback period calculations against lower-first-cost conventional alternatives.
- Rental Properties:Landlord-driven bulk procurement fragments traditional retail channel dominance in German and Dutch urban markets. Property management platforms specify certified appliance packages to streamline regulatory compliance documentation.
- Commercial:Food service and hospitality operators prioritize remote diagnostics to minimize downtime costs.
- Institutions:University and hospital procurement offices mandate extended warranty terms and standardized maintenance protocols.
Residential end users anchor existing demand. Rental properties represent the steepest expansion trajectory as European regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Japan outstrips China and South Korea by double-digit margins, reflecting regulatory premium capture versus volume-scale competition. This asymmetry shapes where manufacturers deploy captive semiconductor capacity versus assembly-only operations.
United States
IRA efficiency rebates compress payback periods for grid-interactive appliances, accelerating premium-tier adoption in electrification-focused states. EPA SNAP rules enforce hydrofluorocarbon phaseouts that synchronize with EU F-Gas timelines. Texas and California housing markets concentrate smart-grid pilot deployments tied to FERC-interconnected utility programs.
Germany
Urban rental complexes in Berlin and Hamburg drive bulk procurement of building energy certificate-compliant appliances. EU Green Deal mandates force refrigerant transitions across manufacturing lines. Bavarian industrial clusters anchor linear compressor production for grid-responsive refrigeration systems exported throughout the EU.
China
MIIT-administered GB standards for smart-home interoperability concentrate demand among certified domestic suppliers. National smart-grid rollout programs tie infrastructure investment directly to AI-integrated cooling procurement. Yangtze River Delta manufacturing bases supply captive semiconductor and compressor components for energy-optimization features.
Japan
METI-backed carbon-neutral building standards create procurement obligations for grid-responsive appliances in Tokyo and Osaka multi-unit residential construction. Variable-speed linear compressor specifications dominate premium refrigeration demand. Kanto region technology clusters integrate machine-learning control algorithms with utility communication protocols.
South Korea
National smart-grid programs concentrate AI-cooling system demand among domestic champions with certified protocol stacks. Seoul metropolitan area residential complexes specify connected-kitchen ecosystems with mesh-network reliability. Busan-Ulsan industrial corridors anchor system-on-chip foundry capacity for appliance-integrated semiconductors.
Green Smart Household Appliances Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive semiconductor and compressor production. Assembly-dependent competitors face margin compression as energy-optimization features become baseline requirements. Three archetypes dominate: vertically integrated electronics conglomerates, specialized home appliance manufacturers with backward component control, and contract assemblers dependent on licensed technology. Competitive moves center on foundry capacity expansion and multi-protocol certification stack development to access divergent regional mandates.
Among vertically integrated electronics conglomerates, Samsung Electronics and LG Electronics exemplify archetypes built on captive chip foundry and linear compressor technology respectively. Haier Smart Home occupies a position representing Chinese domestic champions with established MIIT certification relationships. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Haier Smart Home |
| Whirlpool Corporation |
| Bosch Home Appliances |
| Electrolux AB |
| General Electric Company |
| Panasonic Corporation |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Linear compressor substitution for fixed-speed reciprocating designs simultaneously concentrates supply geography in German and South Korean manufacturing clusters while compressing margin structures for assembly-dependent competitors lacking captive production. This input transition reshapes pricing economics as energy-optimization features shift from premium tier to baseline requirement.
Pricing Analysis
Configured-to-order pricing for grid-responsive appliances commands substantial premiums over standard electric-grid units in German and Japanese urban developments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and connectivity protocol stack complexity. Cost compression in the economy tier intensifies because assembly-dependent manufacturers license linear compressor technology at margin penalty. Landlord-driven bulk procurement in European rental properties exhibits lowest price sensitivity, while individual residential replacement cycles remain most elastic.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Busan port corridors fluctuate with container availability on Asia-Europe trade lanes, compressing landed cost predictability for semiconductor and compressor components. Captive supply of system-on-chip devices centers on South Korean foundry capacity, while linear compressor manufacturing draws from German and Chinese production bases. Single-source vulnerability in Taiwan semiconductor foundry concentration exposes appliance manufacturers to geopolitical disruption risk. Distribution runs through property management platforms in European rental channels and traditional retail networks in North American replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
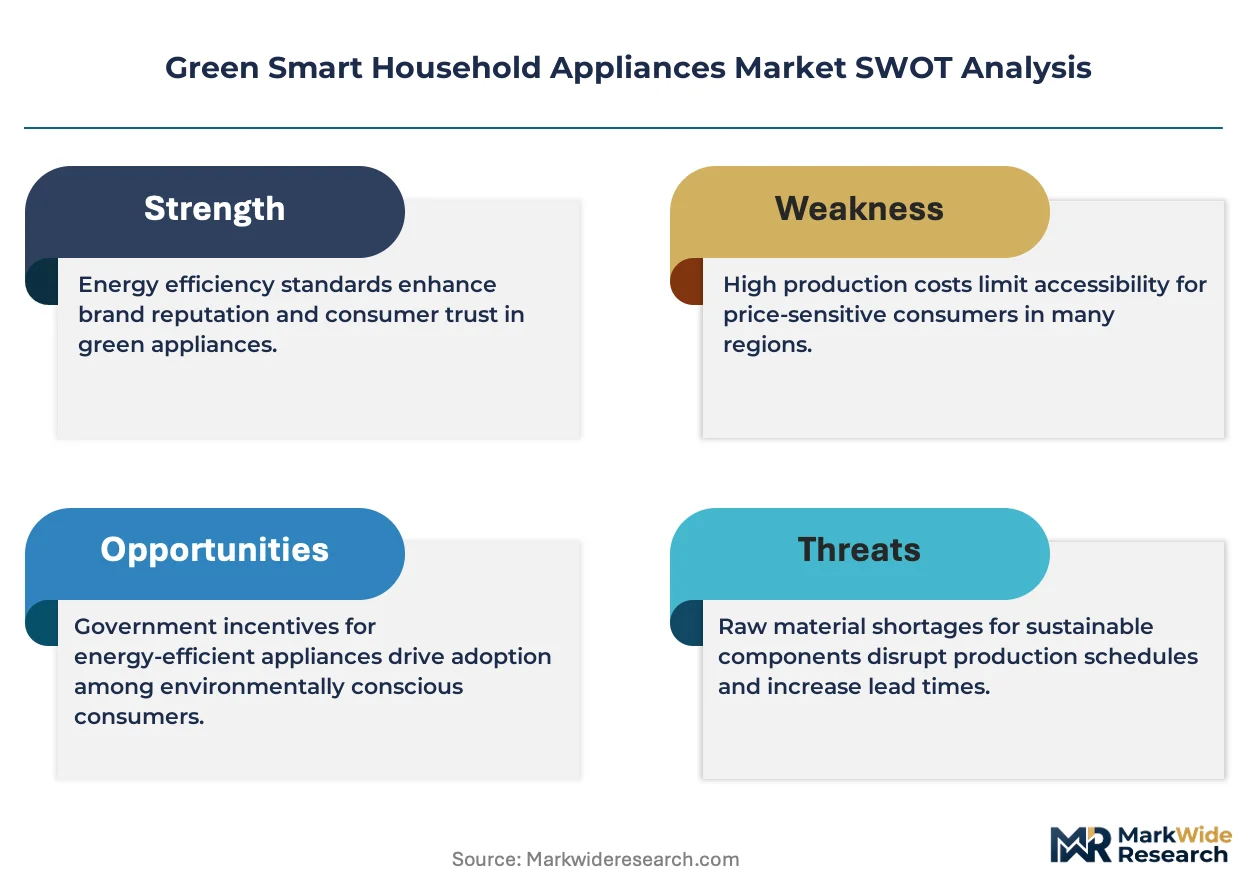
This market demands substitution defense against refurbished appliance circularity models that undercut premium pricing with certified pre-owned grid-responsive units. Incumbents must navigate this threat while consolidating positions in semiconductor and compressor captive production.
For Market Incumbents: Compound backward integration into linear compressor technology to eliminate licensing cost penalties and lock in variable-speed refrigeration cycle supply. Deepen system-on-chip foundry capacity in South Korean industrial corridors to secure connected-kitchen ecosystem dominance against assembly-dependent competitors. This defensive posture addresses margin compression from energy-optimization feature commoditization.
For New Entrants and Emerging Players: Remote diagnostics service layers for commercial food service operators represent underpenetrated white space where incumbents under-serve downtime-sensitive buyers. Zigbee mesh ecosystem certification gaps in European rental property channels offer penetrable entry points. Pursue direct contracting with property management platforms in German and Dutch urban markets to bypass retail channel establishment costs.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with established MIIT certification relationships and captive compressor production. Long-term viability across the projection horizon favors manufacturers with protocol stack development capabilities spanning China's GB standards and EU CE marking requirements. Watch F-Gas Regulation enforcement intensity as inflection indicator for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Compressor Production | Eliminates margin-draining licensing costs for variable-speed refrigeration cycles demanded by EU Green Deal compliance. |
| Multi-Protocol Certification Stack Development | Unlocks channel access across China's MIIT-administered GB standards and EU CE marking requirements simultaneously. |
| Property Management Platform Partnership | Captures landlord-driven bulk procurement volumes in German and Dutch rental housing compliance channels. |
| System-on-Chip Foundry Capacity Expansion | Secures connected-kitchen semiconductor supply against Taiwan concentration risk and geopolitical disruption exposure. |
| Grid-Interactive Load Management Feature Development | Aligns product roadmaps with Japan's METI-backed carbon-neutral building standards and national smart-grid rollout programs. |
Research Methodology
Operator-level perspectives from appliance manufacturing executives, property management platform procurement directors, smart-grid program administrators, and semiconductor foundry operations managers anchored the qualitative base. Primary interview data combined with secondary validation from MIIT GB standard documentation, EU F-Gas Regulation filings, EPA SNAP rule dockets, and customs trade flow records. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction across product type, control technology, and end-user segmentation dimensions.
Sensitivity analysis tested forecast robustness against refrigerant transition timeline acceleration, copper and rare-earth magnet price volatility scenarios, and connectivity protocol mandate divergence. The analytical framework modeled volume and value outputs across the projection horizon through refrigeration, washing machine, dishwasher, and microwave product categories with energy source and control technology cross-segmentation. CAGRs derived from replacement cycle timing, regulatory compliance deadline clustering, and infrastructure rollout pace assumptions tied to national smart-grid programs.
Underlying assumptions cover refrigerant chemistry transition feasibility, semiconductor supply continuity, and regulatory enforcement consistency, with deviation risk concentrated in geopolitical disruption to Taiwan foundry operations and F-Gas Regulation timeline acceleration. Forecasts reflect these documented conditions and stated variable ranges. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
North America Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Japan Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
Brazil Home Appliances Market