
 Merchandizing Refrigerators Market | 2026-2036
Merchandizing Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Merchandizing Refrigerators Market Foresight
Convenience store chains is restructuring the end-use mix for merchandizing refrigerators as smaller-format retailers expand fresh and frozen offerings. Carrier Global Corporation leverages its scale in glass door and walk-in systems to serve national convenience operators. Hussmann Corporation anchors its position through deep channel control with supermarket retrofit programs. Epta S.p.A. competes on energy-efficient compressor technology tailored to European efficiency codes.
Merchandizing refrigerators are self-contained or remote commercial cooling units designed to display food and beverages at controlled temperatures, typically operating between minus 18 degrees Celsius for frozen goods and 4 degrees Celsius for chilled products, using vapor-compression cycles with hydrocarbon or HFO refrigerants. Glass door units dominate replacement demand due to superior thermal efficiency and compliance with tightening energy standards. Open front formats retain share in high-traffic supermarket aisles where impulse purchase behavior justifies higher energy consumption. Multi-temperature configurations are gaining traction among bakeries and restaurants seeking flexible storage in constrained floor plans.
The EPA regulates refrigerant transitions under SNAP, while the DOE sets minimum energy conservation standards for commercial refrigeration equipment; California's Title 24 building codes impose additional efficiency requirements that shape product specifications for manufacturers serving the US market. The EU F-Gas Regulation and Ecodesign directives drive parallel compliance investments for exporters like Arneg and AHT Cooling Systems. Stakeholders must monitor refrigerant phase-down schedules and regional efficiency tier updates to align R&D pipelines with compliance timelines.
Market Dynamics
EPA's SNAP refrigerant phase-down mandates are forcing simultaneous retooling of compressor architectures and supply chains across the merchandizing refrigerator value chain, compressing product development cycles while elevating compliance costs.
Growth Catalysts
- Convenience Store Expansion:Chains like 7-Eleven and Circle K are expanding refrigerated grab-and-go sections, driving unit demand for glass-door vertical cases and under-counter units.
- California Title 24:The state's building efficiency codes mandate LED lighting and high-performance glazing, accelerating replacement cycles in the US Southwest.
- Hydrocarbon Adoption:R290 and R600a compressors are penetrating European retrofit markets as the EU F-Gas Regulation tightens HFC quotas.
Market Restraints
- Copper and Steel Volatility:Coil and cabinet material costs swing with commodity markets, squeezing margin stability for mid-tier manufacturers.
- Compressor Supply Concentration:Three Asian suppliers control over 60% of variable-speed scroll compressor output, creating single-source risk for remote condensing units.
- Refrigerant Transition Friction:EPA SNAP timelines compress certification windows, forcing parallel inventory of HFO and hydrocarbon architectures.
Strategic Opportunities
- India Cold Chain Buildout:Government PLI schemes for food processing infrastructure are opening demand for multi-temperature display cases in Tier-2 cities.
- Pharmacy Vaccine Storage:Hospital and retail pharmacy chains need 2-8°C precision units with data logging, expanding addressable market beyond food retail.
- IoT-Enabled Predictive Maintenance:Sensor-integrated cabinets allow service unbundling and uptime guarantees, shifting revenue toward subscription models.
Industry Challenges
- Refrigerant Technician Shortage:Hydrocarbon handling certification remains scarce in North American service networks, slowing field conversion rates.
- Legacy Control Integration:Supermarket energy management systems use proprietary protocols, complicating smart cabinet deployment without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Merchandizing Refrigerators Market |
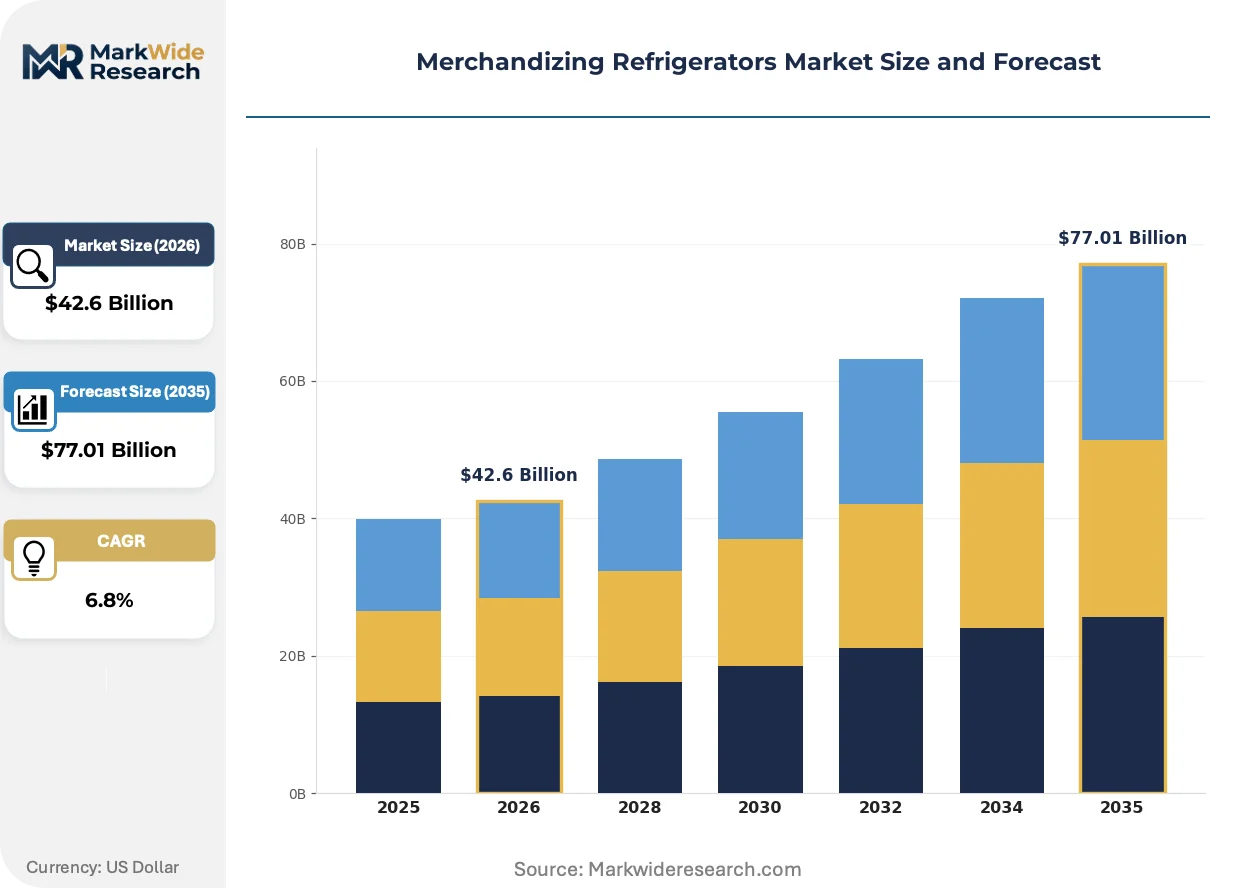
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $77.01 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Front, Glass Door, Under Counter, Walk-In End User: Supermarkets, Convenience Stores, Restaurants, Bakeries Temperature Type: Freezer, Chiller, Multi-Temperature, Low-Temperature Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | Carrier Global Corporation, Hussmann Corporation, Dover Corporation, Danfoss, Haier Group, Epta S.p.A., Arneg, True Manufacturing, AHT Cooling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Merchandizing Refrigerators Market Shifts & Advancements
Refrigeration architecture is pivoting from static efficiency compliance toward dynamic, connected systems that optimize energy use against real-time occupancy and utility pricing signals.
Variable-speed compressor technology paired with electronic expansion valves is rewriting thermal management economics in high-door-count installations. Convenience operators with 24-hour operations are retrofitting glass-door lines first, accepting 18-24 month payback periods. The shift is compressing demand for fixed-speed legacy units and elevating factory-integrated controls to competitive necessity.
The EU F-Gas Regulation's 2024 quota cut is accelerating HFC-404A phase-out across export-dependent manufacturers. Commercial refrigeration OEMs serving European supermarket chains must now certify R454A and R455A blends ahead of schedule. Remote condensing architectures are gaining share in Northern European markets where heat recovery integration satisfies building code efficiency bonuses.
Foodservice distributors are consolidating procurement through national account structures, displacing regional dealer networks. Broadline operators like Sysco and US Foods now specify cabinet performance standards directly, compressing manufacturer margin through volume aggregation. This concentration is most visible in the US Southeast, where chain restaurant expansion drives standardized rollouts across hundreds of locations.
Merchandizing Refrigerators Market Segmentation
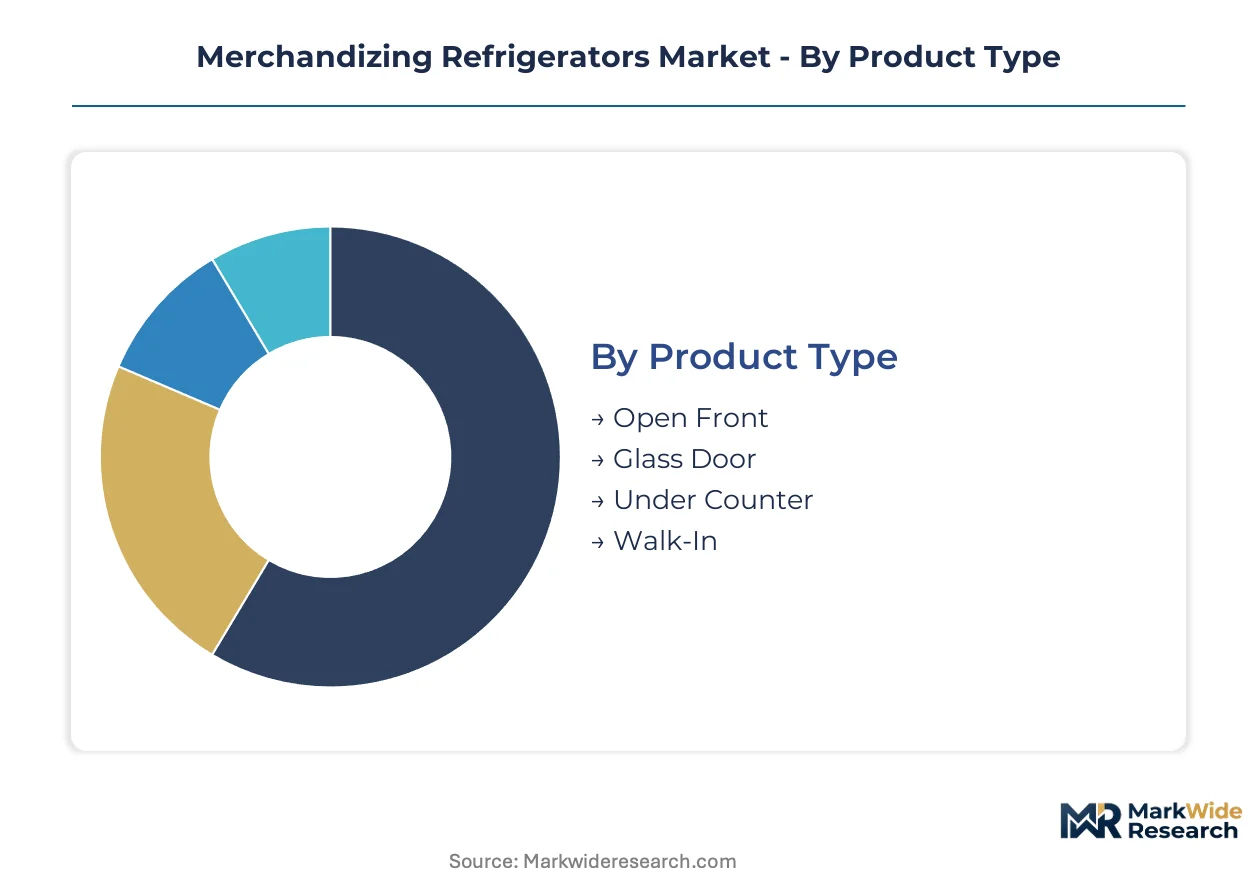
Segmentation in merchandizing refrigerators reveals how thermal architecture, buyer scale, and channel economics split demand into distinct procurement patterns. Each category exposes different margin pressures and compliance burdens for manufacturers.
Product Type:
Buyers select formats based on traffic density, energy cost exposure, and retrofit constraints rather than uniform efficiency targets.
- Glass Door:Vertical and reach-in units with double-pane low-emissivity glazing and LED illumination achieve thermal efficiency ratings that satisfy California Title 24 mandates. Convenience store chains in the US Southwest specify these for 24-hour operations where electricity tariffs compress payback windows.
- Open Front:Air-curtain cabinets maintain product visibility for impulse categories in high-aisle-traffic supermarket environments. European retailers absorb higher energy penalties where F-Gas Regulation compliance costs already dominate capital budgets.
- Under Counter:Compact self-contained units serve back-of-house and front-counter foodservice locations with constrained floor plates.
- Walk-In:Remote condensing systems with modular panel construction anchor large-format supermarket retrofit programs.
Glass Door leads volumes today; Under Counter configurations are gaining share fastest among smaller-format retailers.
End User:
Procurement scale and replacement frequency separate national account buyers from fragmented independent operators.
- Supermarkets:Enterprise buyers negotiate multi-year rollouts specifying variable-speed compressor architectures and integrated energy management protocols. US national chains drive standardization across hundreds of locations, compressing manufacturer margins through volume aggregation.
- Convenience Stores:Smaller-footprint operators prioritize rapid installation and plug-and-play controls for grab-and-go expansion. 7-Eleven and Circle K procurement teams specify glass-door vertical cases with factory-integrated monitoring.
- Restaurants:Foodservice distributors consolidate purchasing through broadline operators, displacing regional dealer relationships.
- Bakeries:Multi-temperature flexibility matters more than capacity scale for pastry display and ingredient storage.
Supermarkets dominate absolute unit demand; Convenience Stores show the steepest expansion trajectory as fresh food penetration accelerates.
Temperature Type:
Refrigerant selection and insulation specification diverge sharply across thermal setpoints.
- Chiller:2-8°C cabinets for dairy, beverages, and prepared foods constitute the largest installed base. Pharmacy vaccine storage applications are expanding addressable demand beyond food retail into hospital and retail clinic networks.
- Freezer:Minus 18°C operation demands thicker cabinet insulation and higher compressor displacement. Hydrocarbon R290 architectures are penetrating European retrofit markets ahead of HFC quota reductions.
- Multi-Temperature:Dual-zone cabinets with independent evaporator circuits serve bakeries and restaurants seeking flexible storage.
- Low-Temperature:Specialized units for ice cream and frozen specialties operate below minus 20°C with enhanced defrost cycles.
Chiller configurations anchor current volumes; Multi-Temperature designs are climbing the fastest as hybrid foodservice formats proliferate.
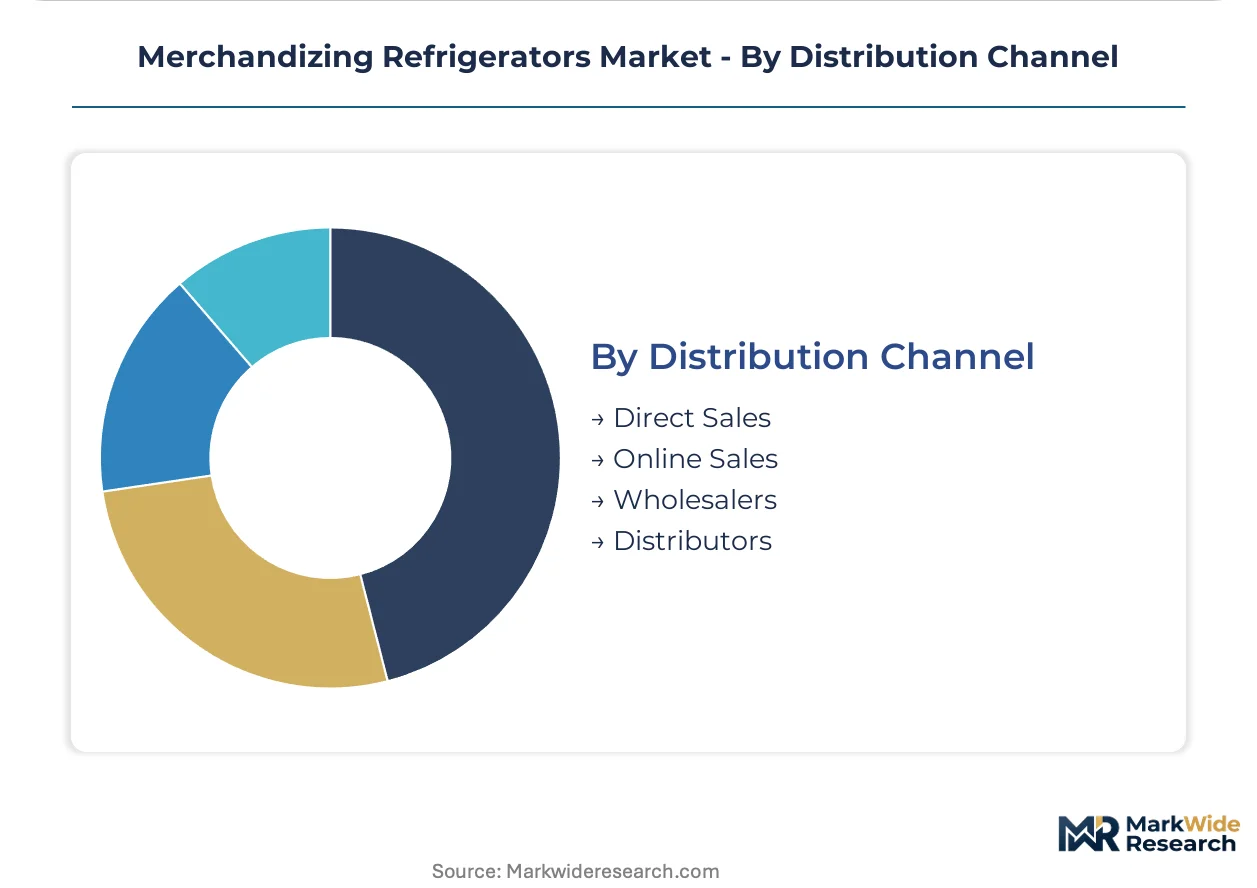
Distribution Channel:
Channel selection reflects buyer technical sophistication and service integration requirements.
- Direct Sales:National supermarket and convenience chains source factory-direct for standardized rollouts with dedicated account engineering. Manufacturers like Carrier Global and Hussmann maintain direct relationships to control specification and capture aftermarket service revenue.
- Distributors:Independent foodservice operators and regional retail chains rely on stocking distributors for shorter lead times and local installation support.
- Wholesalers:Price-sensitive smaller buyers procure through broadline equipment wholesalers with limited technical support.
- Online Sales:Replacement parts and compact under-counter units move through e-commerce channels for cost-conscious independent operators.
Direct Sales commands the largest transaction values; Distributors are expanding share fastest among mid-tier foodservice buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors the merchandizing refrigerator supply chain through Hussmann Corporation's manufacturing footprint and retrofit program density across Midwestern supermarket chains. The United States, Germany, China, India, and Japan concentrate distinct demand drivers and regulatory frameworks that shape regional procurement patterns.
United States
Supermarket retrofit cycles and convenience store grab-and-go expansions drive replacement volumes across the Southeast and Southwest. The EPA's Significant New Alternatives Policy mandates low-GWP refrigerant transitions, compressing product certification windows. California's Title 24 building codes in Los Angeles and San Diego accelerate LED lighting and high-performance glazing specifications.
Germany
Energy efficiency mandates and hydrocarbon compressor adoption dominate capital planning for supermarket chains. The EU F-Gas Regulation's 2024 quota reduction forces HFC-404A phase-out ahead of schedule. Industrial clusters around Stuttgart and Munich concentrate remote condensing system manufacturing for Northern European heat recovery integration.
China
Cold chain infrastructure buildout and food retail modernization expand addressable demand in Tier-2 cities. The Ministry of Ecology and Environment's dual carbon goals tighten efficiency standards for commercial cooling equipment. Manufacturing concentration in the Yangtze River Delta supplies domestic foodservice distributors and export markets.
India
Government PLI schemes for food processing infrastructure open demand for multi-temperature display cases beyond metro markets. The Bureau of Indian Standards enforces efficiency labeling for commercial refrigeration equipment. Industrial corridors in Maharashtra and Gujarat attract component assembly investments serving quick-service restaurant expansion.
Japan
Convenience store 24-hour operations and precision temperature requirements for prepared foods sustain replacement demand. METI efficiency standards and refrigerant transition timelines align with commercial building energy codes. Manufacturing presence in the Chubu region around Nagoya supports domestic service networks and technology licensing.
Merchandizing Refrigerators Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers align compressor suppliers with control system integrators to accelerate connected cabinet development. The vendor base splits between integrated full-line suppliers and specialized component fabricators, with three distinct competitive tiers emerging. Scale-driven multinationals anchor national account relationships, mid-cap specialists occupy regional retrofit niches, and Asian component houses control compressor supply. Portfolio diversification and technology licensing represent the dominant competitive moves, with manufacturers expanding into predictive maintenance subscriptions and IoT-enabled service contracts.
Within the integrated systems tier, Carrier Global Corporation and Hussmann Corporation exemplify scale-driven positioning through direct national account engineering and aftermarket service capture. Epta S.p.A. occupies a specialist position anchored by European efficiency code compliance and compressor technology integration. Haier Group represents the Asia-Pacific manufacturing archetype with domestic market density and export platform economics. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors in a market where factory-integrated controls and refrigerant architecture flexibility determine procurement outcomes.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Hussmann Corporation |
| Dover Corporation |
| Danfoss |
| Haier Group |
| Epta S.p.A. |
| Arneg |
| True Manufacturing |
| AHT Cooling Systems |
| Others |
Supply & Pricing Matrix
Captive compressor production at Asian component houses anchors pricing power for remote condensing units while compressing margin flexibility for mid-tier cabinet assemblers in North America and Europe. This upstream integration choice simultaneously secures supply continuity for variable-speed scroll architectures and concentrates cost pass-through leverage among three dominant suppliers.
Pricing Analysis
Copper coil and steel sheet pass-through from commodity markets drives quarterly price adjustments across glass-door and walk-in product lines. Pricing stratifies across premium certified tiers, standard efficiency bands, and economy fixed-speed units based on California Title 24 compliance and hydrocarbon refrigerant architecture. Cost compression in mid-tier segments is intensifying because supermarket national accounts aggregate volume across hundreds of locations. Independent convenience operators show highest price sensitivity due to constrained capital budgets, while enterprise retrofit programs absorb premium positioning for factory-integrated monitoring.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from 7-Eleven and Circle K procurement teams, while regional distributors serve fragmented foodservice buyers with shorter lead-time requirements. Manufacturing concentrates in China, Italy, and the United States, with coil fabrication and compressor assembly drawing from Yangtze River Delta and Chubu region industrial clusters. Raw material dependencies span copper refrigerant tubing, low-emissivity glass, and variable-speed electronic controllers. Single-source vulnerability pervades scroll compressor supply where three Asian suppliers control dominant share. Distribution runs through factory-direct national accounts, stocking distributors, and broadline equipment wholesalers serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchandizing refrigerator procurement arbitrages regulatory cost differentials between EPA SNAP-mandated US retrofits and EU F-Gas quota-driven European replacement cycles, creating margin expansion opportunities for manufacturers with dual-certification capabilities.
For Market Incumbents: Anchor aftermarket service revenue through predictive maintenance subscriptions tied to IoT-enabled cabinet deployments. Defend position against Asian component house forward integration by deepening direct national account engineering relationships with convenience store chains. Prioritize hydrocarbon compressor certification investments to capture European retrofit demand ahead of HFC phase-down deadlines.
For New Entrants and Emerging Players: Enter via pharmacy vaccine storage applications where 2-8°C precision requirements and data logging specifications create specification gaps incumbent food-retail suppliers have not fully addressed. Target India Tier-2 city cold chain buildout under government PLI schemes for food processing infrastructure. Pursue broadline distributor partnerships rather than direct sales to bypass entrenched supermarket procurement relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional service networks with hydrocarbon technician certification because refrigerant transition friction creates captive maintenance demand and recurring revenue visibility. Five-to-ten year viability hinges on IoT platform integration capabilities and factory-integrated control architecture ownership. Monitor EPA SNAP timeline acceleration and California Title 24 tier updates as inflection indicators for replacement cycle timing and compliance investment intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Compressor Certification | EU F-Gas quota reductions force R290 architecture adoption ahead of HFC phase-out schedules. |
| IoT Platform Integration | Sensor-enabled cabinets shift revenue toward subscription-based uptime guarantees and predictive service. |
| Direct National Account Engineering | Factory-direct relationships with 7-Eleven and Circle K capture specification control and retrofit program access. |
| India Manufacturing Footprint | Maharashtra and Gujarat industrial corridors position suppliers for PLI scheme food processing infrastructure demand. |
| Pharmacy Cold Chain Expansion | Hospital and retail clinic vaccine storage opens addressable market beyond traditional food retail segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with supermarket energy management directors, convenience store procurement leads, refrigeration contractor service managers, and compressor OEM technical sales teams with secondary validation against EPA SNAP filings, DOE energy conservation standard dockets, EU F-Gas Regulation quota tracking, and customs trade data for commercial refrigeration equipment. Bottom-up unit deployment estimates triangulated against top-down replacement cycle modeling across regional regulatory clusters.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product architecture, temperature setpoint, end-user scale, and distribution channel structure. CAGRs derived from fitted growth curves incorporating refrigerant transition timelines, retrofit cycle density, and convenience store format expansion rates. Forecast inputs included commodity price indices for copper and steel, electricity tariff trajectories in California and Germany, and hydrocarbon compressor adoption curves in European retrofit markets.
Inputs from regulatory filing databases and distributor shipment reports were available through the study window; gaps in real-time supermarket capital expenditure disclosure introduce uncertainty bands around replacement cycle timing. Forecasts reflect documented assumptions regarding EPA SNAP enforcement pace and EU F-Gas quota allocation mechanics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Japan Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Saudi Arabia Major Home Appliances Market