
 Europe White Goods Market | 2026-2036
Europe White Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Europe White Goods Market Intelligence
The integration of smart connectivity with energy-efficient inverter motor technology is rewriting the performance and user experience standards for household appliances in Europe. This shift enables remote diagnostics and optimized energy consumption. BSH Hausgeräte GmbH leverages its strong brand presence in the premium segment, particularly within the German market. Electrolux AB competes on a portfolio emphasizing sustainability across multiple product categories.
White goods comprise major household appliances, including refrigerators, washing machines, and ovens, traditionally finished with a white enamel coating over steel. These devices are engineered for long service lives, often incorporating components like compressors or heating elements designed for high-duty cycles. Within product types, washing machines and refrigerators remain the largest categories by volume, while smart ovens and dishwashers represent the fastest-growing segments. E-commerce is rapidly gaining share as a distribution channel, challenging traditional specialty stores.
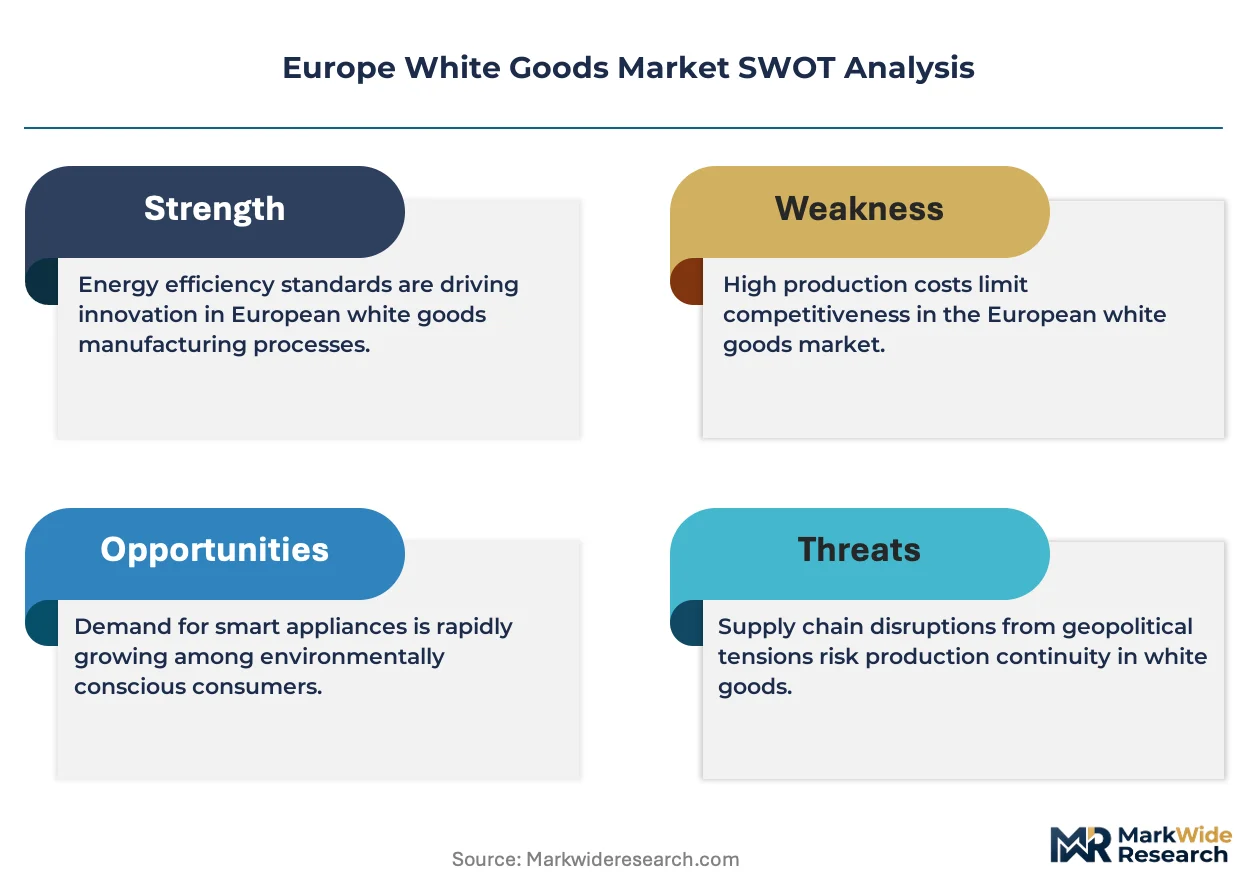
The European market is heavily shaped by the EU's Ecodesign Directive and mandatory energy labeling, which set strict efficiency standards. Concurrently, the 'Right to Repair' initiative mandates the availability of spare parts and repair information, influencing product design and after-sales service models. Manufacturers must now balance investments in smart features against the increasing regulatory pressure for durability and reparability.
Market Dynamics
The European white goods market is defined by the dual pressures of stringent EU regulations on energy efficiency and reparability, and rising consumer expectations for smart, connected appliances. This dynamic forces manufacturers to innovate on both hardware durability and software features simultaneously.
Growth Catalysts
- EU Energy Labeling:Rescaled energy labels mandate higher efficiency, spurring innovation in inverter motors and creating demand for premium appliances.
- Residential Construction Boom:New multi-family housing projects, especially in Germany, generate large-volume orders for integrated kitchen and laundry appliances.
- Smart Home Integration:Consumer demand for connected ecosystems in markets like France pulls sales toward feature-rich smart refrigerators and ovens.
Market Restraints
- Input Cost Volatility:Fluctuating prices for steel and polymers create margin pressure and complicate cost planning for European appliance manufacturers.
- Right to Repair Mandates:The EU's repairability rules require costly product redesigns for modularity and force the maintenance of extensive spare parts inventories.
- Semiconductor Supply Risk:The industry's reliance on semiconductor imports from Asia for smart appliance logic boards creates significant supply chain vulnerability.
Strategic Opportunities
- Appliance-as-a-Service Models:Subscription-based offerings for high-end appliances can capture recurring revenue from urban renters and property managers, especially in Germany.
- Circular Economy Platforms:Certified refurbishment programs and secondary sales channels align with EU Green Deal goals, creating a market for second-life appliances.
- AI-Powered Predictive Maintenance:Integrating AI into connected appliances to predict failures creates a new value proposition for premium after-sales service contracts.
Industry Challenges
- Ecodesign Compliance Cycles:The continuous evolution of the EU's Ecodesign Directive necessitates frequent and capital-intensive R&D cycles to ensure all product lines remain compliant.
- Software Engineering Talent:A shortage of skilled software engineers and data scientists in Europe hampers the development and maintenance of sophisticated smart appliance ecosystems and mobile apps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe White Goods Market |
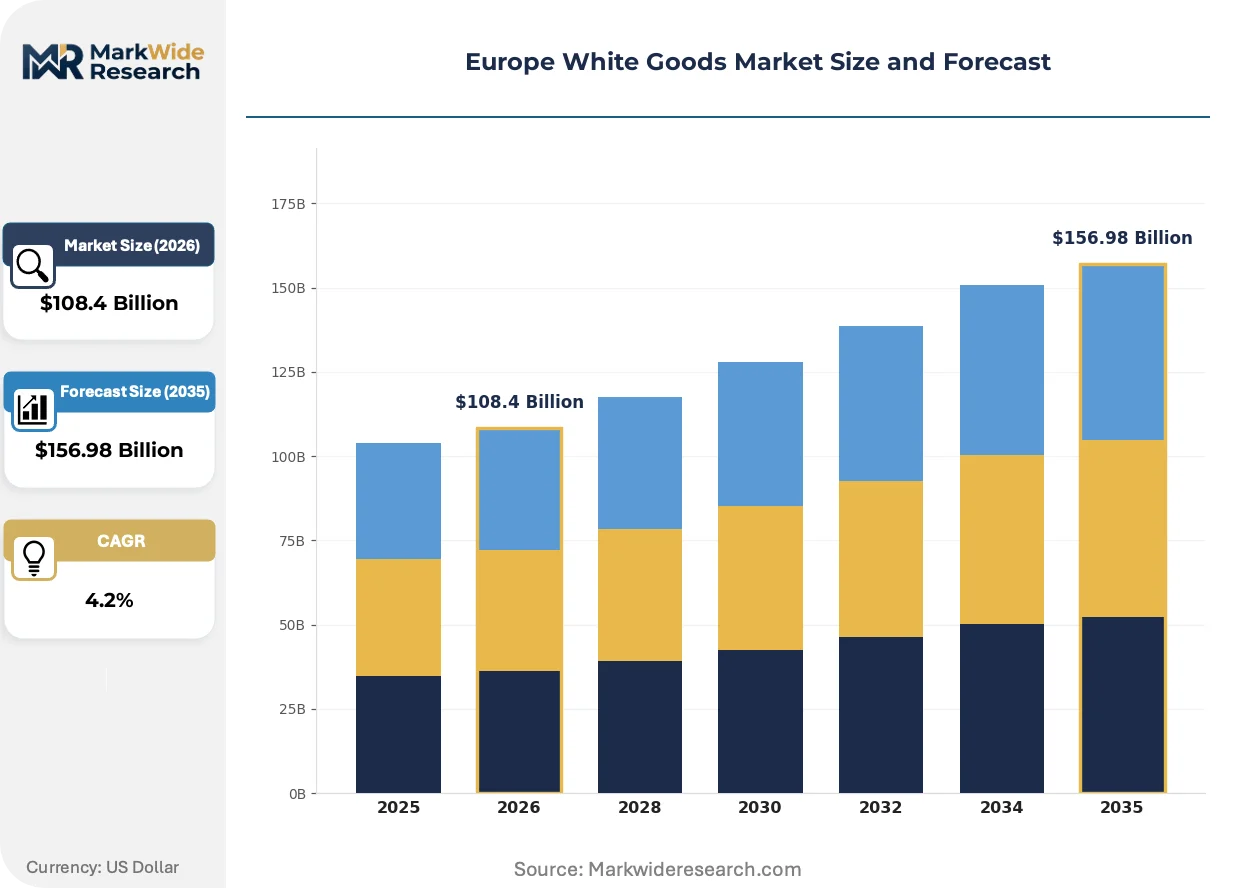
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $156.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
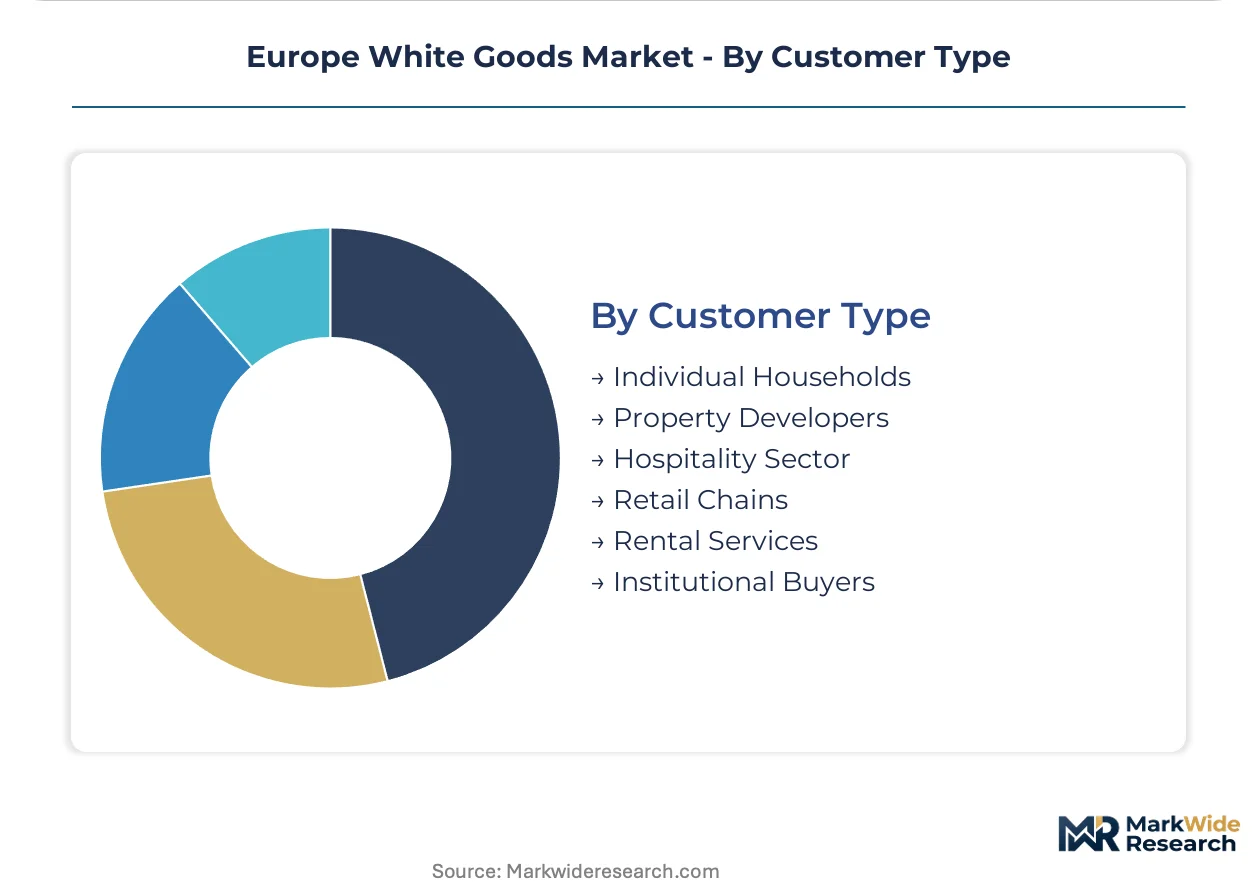
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Ovens, Microwaves, Freezers Technology: Inverter Motor, Twin Wash, Hygienic Care, Steam Cleaning, Smart Connectivity, Energy Efficient Distribution Channel: Specialty Stores, E-commerce, Mass Merchandisers, Direct Sales, Appliance Retailers, Home Improvement Centers Customer Type: Individual Households, Property Developers, Hospitality Sector, Retail Chains, Rental Services, Institutional Buyers |
| Companies Covered | BSH Hausgeräte GmbH, Electrolux AB, Arçelik A.Ş., Whirlpool Corporation, LG Electronics, Miele, Robert Bosch GmbH, Haier Smart Home, Samsung Electronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe White Goods Market Strategic Shifts & Innovations
The market is transitioning from a focus on standalone hardware performance to integrated, software-defined ecosystems. This shift elevates the importance of connectivity, data analytics, and adherence to circular economy principles in product design and service models.
Digital twin technology creates a dynamic virtual replica of a physical appliance, tracking its operational state and performance data in real time. Appliance manufacturers are adopting this for remote troubleshooting and predictive service alerts. This technology is virtualizing the initial diagnostic visit from a service technician, reducing operational costs and improving customer uptime.
Mandates from the EU's 'Right to Repair' initiative are transforming product lifecycles. This policy legally obligates manufacturers to provide spare parts and repair information for up to a decade, influencing design choices. The washing machine and dishwasher segments are most affected, with a clear trend toward more modular and easily disassembled product architectures.
A clear behavioral shift toward subscription-based consumption is emerging for high-value appliances. This model disrupts the traditional one-time purchase, offering users access to the latest technology without a large upfront investment. This trend is gaining traction with property developers in Germany and the build-to-rent sector in other major European markets.
Europe White Goods Market Segmentation
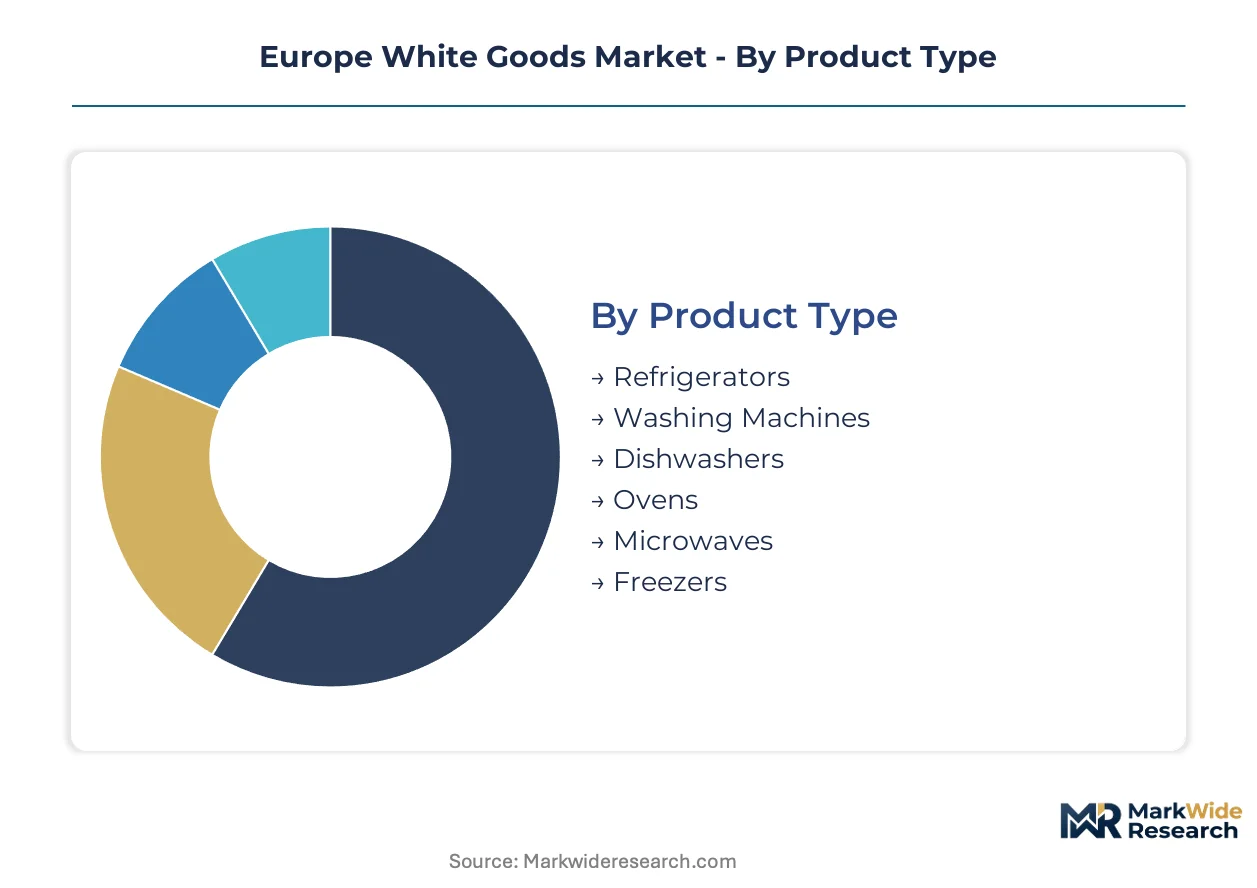
The Europe white goods market segmentation reveals distinct consumer preferences and operational demands across product types, technologies, and distribution channels. Understanding these segments is crucial for manufacturers navigating stringent EU regulations and evolving consumer expectations for smart, connected appliances.
Product Type:
Product type segmentation highlights the varying service intensity required throughout an appliance's lifecycle, especially with 'Right to Repair' mandates.
- Washing Machines:These appliances feature complex mechanics and water management systems, necessitating robust after-sales support and spare parts availability. Demand concentrates in new multi-family housing projects across Germany, driven by large-volume orders from property developers.
- Refrigerators:Essential for continuous operation, these units integrate advanced cooling technologies and often smart connectivity for enhanced user experience. France shows strong demand for premium, feature-rich smart refrigerators, aligning with smart home integration trends.
- Dishwashers:Focused on water and energy efficiency, these appliances are increasingly incorporating smart features for optimized cycles.
- Ovens:Modern ovens offer diverse cooking functions and smart connectivity, representing a rapidly expanding segment in European households.
- Microwaves:These compact appliances provide quick heating solutions, serving as a staple in most kitchens due to convenience.
- Freezers:Designed for long-term food preservation, freezers emphasize energy efficiency and reliable temperature control.
By volume, washing machines and refrigerators lead. By growth pace, smart ovens and dishwashers represent the fastest-growing segments.
Technology:
Technology segmentation demonstrates varying margin implications, with advanced features often commanding higher price points and requiring more specialized R&D investment.
- Smart Connectivity:This technology enables remote diagnostics, app control, and integration into broader smart home ecosystems, enhancing user convenience. Consumer demand for connected ecosystems in France pulls sales towards these feature-rich appliances.
- Inverter Motor:Inverter motors offer variable speed control, reducing noise and energy consumption, which aligns with stringent EU energy labeling requirements. Germany's market favors these efficient components, especially in premium washing machines.
- Hygienic Care:Features like steam cycles and specialized filters provide enhanced sanitization and allergen removal for health-conscious consumers.
- Steam Cleaning:This technology is integrated into ovens and washing machines for effective cleaning and odor reduction, minimizing chemical use.
- Twin Wash:Allowing two separate loads to run simultaneously, this innovation caters to households needing flexible laundry solutions.
- Energy Efficient:This broad category encompasses design and component choices aimed at minimizing power consumption, driven by EU Ecodesign Directives.
Smart connectivity solutions are gaining share fastest. Inverter motor technology also shows a strong upward trajectory.
Distribution Channel:
Distribution channel segmentation reflects how different customer types access white goods, influencing logistics and sales strategies.
- E-commerce:Online platforms provide convenience and a wider product selection, increasingly challenging traditional retail models. This channel gains traction with urban renters and property managers seeking efficient procurement.
- Specialty Stores:These outlets offer expert advice, installation services, and a tactile shopping experience for consumers seeking premium or complex appliances. They cater to individual households prioritizing personalized service.
- Mass Merchandisers:Large retail chains offer a broad range of products at competitive prices, appealing to budget-conscious consumers.
- Direct Sales:Manufacturers engage directly with consumers, often for high-end or niche products, building brand loyalty and providing tailored service.
- Appliance Retailers:Focused solely on white goods, these stores provide specialized product knowledge and after-sales support.
- Home Improvement Centers:These centers cater to consumers undertaking renovation projects, often bundling appliance purchases with other home goods.
E-commerce is rapidly gaining share. Specialty stores maintain a strong position for premium segment sales.
Customer Type:
Customer type segmentation highlights the varying volume potential and purchasing drivers across different buyer groups, from individual consumers to large-scale developers.
- Property Developers:This segment generates substantial volume orders for integrated kitchen and laundry appliances, particularly for new multi-family residential construction projects. New housing developments in Germany drive significant demand for these bulk purchases.
- Individual Households:Comprising the largest consumer base, these buyers focus on replacement cycles, personal preferences, and energy efficiency. French households frequently seek connected ecosystems and premium features for their homes.
- Hospitality Sector:Hotels and restaurants require commercial-grade, durable appliances capable of high-duty cycles and specific regulatory compliance.
- Retail Chains:These entities purchase white goods for staff facilities, display units, and sometimes for resale within their own operations.
- Rental Services:Companies offering appliance subscriptions or short-term rentals require robust, easily maintainable units for their customer base.
- Institutional Buyers:Schools, hospitals, and other public bodies procure appliances based on tenders, durability, and specific functional requirements.
Property developers represent a substantial volume opportunity. Rental services show a steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialized appliance manufacturers export high-efficiency white goods across the European Union, supporting advanced product development and market penetration. This trade flow across the continent reflects a strong regional supply chain. The EU's stringent regulatory environment shapes regional consumer preferences and production strategies for white goods.
Germany
Property developers in Germany drive significant demand for integrated kitchen and laundry appliances, particularly for new multi-family projects. The EU Ecodesign Directive mandates continuous innovation for energy efficiency in this sophisticated market. Berlin's urban housing projects frequently feature bulk orders for premium, smart-enabled white goods, reflecting consumer preferences.
France
French consumers increasingly seek connected ecosystems and premium features for their homes, especially in smart refrigerators and ovens. The EU's 'Right to Repair' initiative influences product design for longevity and spare parts availability across the country. Paris and other major cities show strong sales of feature-rich smart appliances, aligning with modern lifestyle trends.
United Kingdom
Urban renters and the expanding build-to-rent sector in the UK generate demand for durable, easily maintainable appliances. Post-Brexit, the UK still largely aligns with EU product standards, including stringent energy efficiency requirements. London's property management firms often procure white goods for high-density residential developments, valuing reliability and serviceability.
Italy
Italian households prioritize appliance design and functionality, with a growing interest in smart ovens and dishwashers for modern kitchens. The EU's energy labeling regulations push manufacturers towards more efficient models, impacting purchasing decisions. Milan's design-conscious consumers often invest in aesthetically pleasing, feature-rich appliances that integrate seamlessly into home aesthetics.
Spain
Spanish residential construction and the vibrant hospitality sector fuel sustained demand for robust, energy-efficient white goods. The EU Green Deal initiatives encourage sustainable product lifecycles and responsible material use within the market. Barcelona's expanding urban centers see strong uptake of connected appliances for new builds and tourist accommodations.
Europe White Goods Market Key Industry Players
On the supply side, the industry is moderately consolidated, with a few large multinational corporations holding significant market share across Europe. The competitive landscape features a blend of global diversified appliance manufacturers, specialized premium segment players, and emerging technology-focused disruptors. Dominant competitive moves include strategic partnerships for smart home integration and continuous portfolio diversification to meet evolving consumer demands. Companies also engage in geographical expansion within key European markets to capture new construction opportunities.
Within the premium and sustainability-focused archetype, BSH Hausgeräte GmbH, a German-based entity, exemplifies innovation in high-efficiency appliances and smart technology integration. Electrolux AB, a Swedish-headquartered corporation, occupies a position emphasizing sustainable solutions and circular economy principles across multiple product categories. Miele, another German-based company, anchors the ultra-premium segment, known for exceptional durability, sophisticated engineering, and long service lives. These players collectively represent the industry's drive towards advanced features and environmental responsibility in the European market.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Electrolux AB |
| Arçelik A.Ş. |
| Whirlpool Corporation |
| LG Electronics |
| Miele |
| Robert Bosch GmbH |
| Haier Smart Home |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Commodity volatility for steel and polymers directly determines pricing tier spreads and shapes the supply chain for European white goods. These fluctuating input costs create margin pressure and complicate manufacturers' cost planning efforts.
Pricing Analysis
The technology-generation pricing gap separates premium smart appliances from standard and economy models. Pricing stratifies across premium, standard, and economy tiers, driven by advanced smart features, inverter motor efficiency, and established brand premium. Pricing pressure stems from regulatory compliance costs for Ecodesign and Right to Repair, alongside semiconductor supply risks. Customers of mass merchandisers exhibit the highest price sensitivity, while property developers and buyers in the premium segment demonstrate less.
Supply Chain Analysis
Upstream feedstock for white goods heavily draws from global sources, particularly semiconductors imported from Asia for logic boards from manufacturing hubs like Taiwan and South Korea. Raw material dependencies include steel and polymers sourced from various European and international suppliers. Single-source vulnerability for critical semiconductor components represents a structural risk. Distribution runs through a hybrid model, balancing rapidly growing e-commerce with established specialty stores and mass merchandisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe white goods market presents a defensive-moat story, primarily justified by regulatory entrenchment through the EU's Ecodesign Directive and Right to Repair mandates. These stringent regulations create high barriers to entry for new players.
For Market Incumbents: Harden core product lines against continuous Ecodesign compliance cycles by investing in modular design and sustainable materials R&D. Secure long-term component supply agreements, especially for semiconductors, to mitigate supply chain vulnerability. Deepen vertical integration into software development to counter emerging technology-focused disruptors. Strengthen after-sales service networks to leverage Right to Repair mandates.
For New Entrants and Emerging Players: Pursue niche opportunities within the circular economy by launching certified refurbishment programs for second-life appliances. Target the build-to-rent sector in major European cities with subscription-based models for high-end appliances. Offer AI-powered predictive maintenance as a premium after-sales service, starting with urban renters in Germany. This strategy leverages unmet demand for flexible consumption and extends product lifecycles.
For Investors and Strategic Acquirers: The market sits at a mature growth phase that favors established brands with strong regulatory compliance and software integration capabilities. Long-term viability over the next decade remains strong, driven by replacement cycles and expanding smart home ecosystems. Identify specialized premium segment players and software-defined appliance innovators as key acquisition targets. Watch for increased M&A activity focused on AI and IoT capabilities as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Modularization | Reduces repair costs and extends product lifecycles under Right to Repair mandates. |
| AI-Powered Predictive Maintenance Integration | Enhances after-sales service value proposition for premium appliance users. |
| Circular Economy Program Launch | Aligns with EU Green Deal goals and creates a market for refurbished units. |
| E-commerce Channel Expansion | Captures growing demand from urban renters and property managers efficiently. |
| Strategic Semiconductor Sourcing | Mitigates supply chain vulnerability for critical smart appliance components. |
Research Approach
The analysis maps major white goods sub-sectors including washing machines, refrigerators, smart ovens, and dishwashers, each validated through extensive primary interviews with product development engineers, procurement managers, retail channel partners, and property developers. Secondary validation drew from EU energy labeling databases, national statistical offices, corporate financial filings, and relevant trade association reports. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecast framework holds constant the current EU regulatory trajectory while varying technological innovation and consumer adoption rates across the analysis window. Segmentation dimensions modeled include product type, technology, distribution channel, customer type, and regional regulatory adherence. Compound annual growth rates were derived from a weighted average of segment-specific growth rates. Key forecast inputs included residential construction starts in Germany and anticipated updates to the EU Ecodesign Directive.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global diversified manufacturers or specialized premium players would shift outcomes. Forecasts reflect assumptions about stable economic conditions and predictable regulatory evolution. Cross-checking against EU market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Germany Washing Machine Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Electric Fireplace Market
Home Appliances
Green Smart Household Appliances Market