
 United Kingdom Home Appliances Market | 2026-2036
United Kingdom Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Home Appliances Market Analytics
AI-driven predictive maintenance and connected diagnostics is reshaping how manufacturers engineer reliability into home appliances. Samsung Electronics leverages its SmartThings ecosystem to control the software layer across multiple appliance categories. Miele & Cie. KG anchors its market position through exceptional build quality and extended product lifecycles that justify premium positioning. Dyson Ltd. differentiates by integrating proprietary motor technology and filtration systems developed through intensive in-house R&D.
United Kingdom Home Appliances encompass electrically powered machines designed for domestic tasks, typically operating at 230V/50Hz with energy efficiency ratings from A to G under current labeling schemes, manufactured through stamped steel forming, injection molding, and automated assembly of compressor or motor subsystems. Refrigerators and washing machines occupy the largest volume positions due to universal household necessity and shorter replacement cycles compared to other categories. Smart Appliances and IoT-Enabled segments attract disproportionate investment as manufacturers pursue recurring service revenue and data monetization opportunities beyond the initial hardware sale.
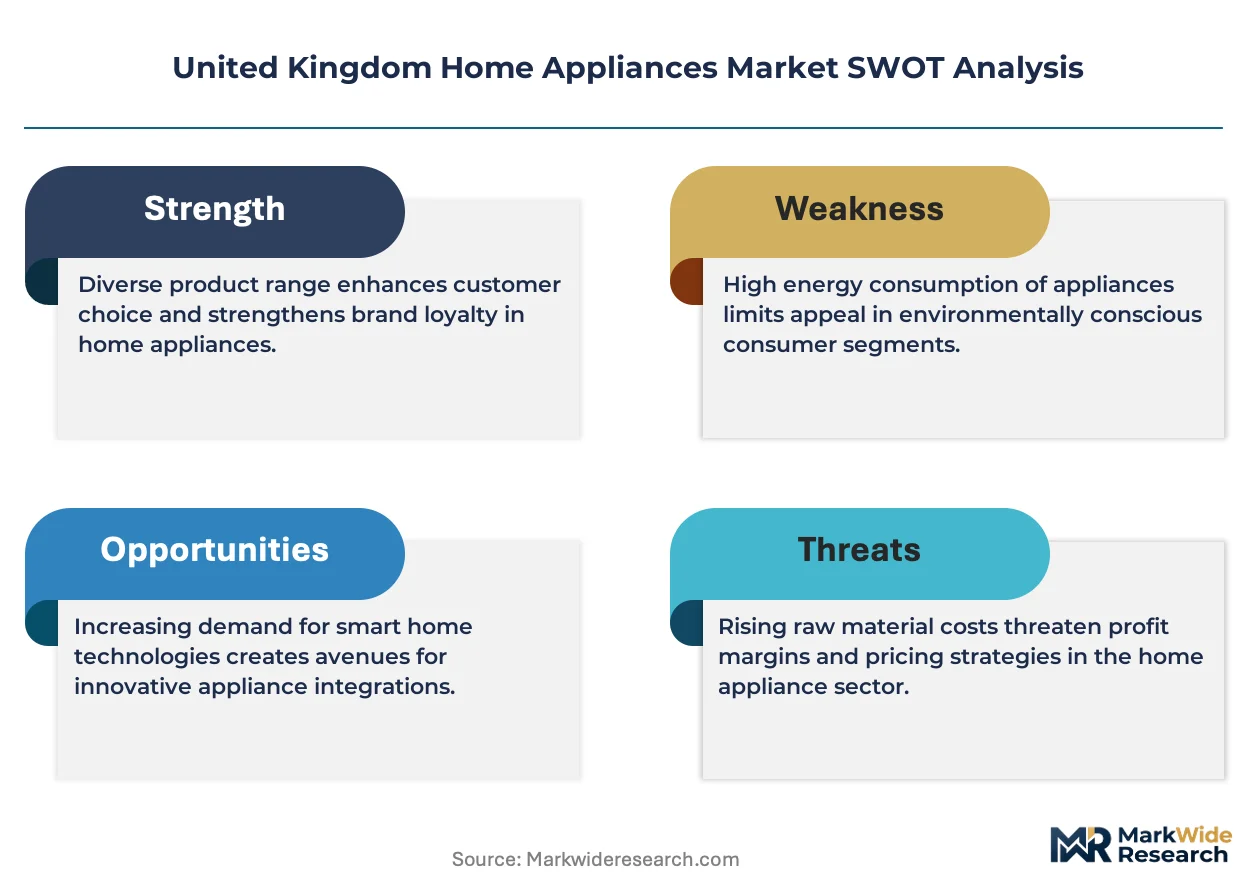
BEIS enforces minimum energy performance standards through the Ecodesign framework while the UKCA marking regime governs product safety and electromagnetic compatibility post-Brexit. Trading Standards offices across England, Scotland, Wales and Northern Ireland conduct market surveillance to remove non-compliant products from distribution channels. Stakeholders must monitor evolving interoperability mandates and right-to-repair legislation that will determine whether proprietary connected ecosystems become competitive moats or regulatory liabilities.
Market Dynamics
The UK Home Appliances Market is being fundamentally restructured by the BEIS Ecodesign for Energy-Related Products Regulations, which mandate minimum energy performance standards and force manufacturers to redesign compressors, motors, and control systems across refrigerator and washing machine portfolios.
Growth Catalysts
- Landlord-driven replacement cycles:Rental property owners in Greater London and the South East are modernizing appliance fleets to meet energy efficiency standards and attract tenants. This creates concentrated demand pulses in high-turnover housing markets.
- Right-to-repair legislation momentum:Pending UK regulations mandating spare parts availability and repair documentation are extending product lifecycles and creating aftermarket service revenue streams for manufacturers with established UK service networks.
- Smart home ecosystem integration:IoT-enabled appliances operating through unified control platforms are capturing disproportionate investment as manufacturers pursue recurring software revenue beyond hardware margins.
Market Restraints
- Steel and copper input volatility:Stamped steel forming and motor winding operations face margin compression from commodity price swings, forcing manufacturers to absorb costs or risk volume loss in price-sensitive segments.
- UKCA marking transition friction:Post-Brexit product safety and electromagnetic compatibility certification requirements create dual compliance burdens for manufacturers serving both UK and EU markets from shared production lines.
- Heat pump substitution threat:Gas boiler replacement programs and building efficiency retrofits are diverting household capex toward HVAC upgrades, compressing discretionary appliance replacement budgets in northern regions.
Strategic Opportunities
- Scotland and northern England underpenetration:Lower housing stock turnover and new build rates in these regions create whitespace for rental property appliance modernization programs targeting social housing providers.
- Predictive maintenance service contracts:AI-driven diagnostic capabilities embedded in connected appliances enable manufacturers to monetize failure prediction and proactive part replacement as subscription offerings.
- Energy label A-grade premium positioning:Trading Standards enforcement of revised A-G efficiency labeling creates regulatory tailwind for manufacturers with superior compressor and inverter technology portfolios.
Industry Challenges
- Embedded systems firmware talent scarcity:Connected appliance development requires software engineers with IoT security and real-time operating system expertise that competes with automotive and industrial automation sectors for limited UK talent pools.
- UKCA-CE dual certification timeline compression:Parallel conformity assessment procedures for product safety and electromagnetic compatibility create bottlenecks in new product introduction schedules.
- Legacy housing electrical infrastructure compatibility:Pre-1980s residential wiring in northern England and Wales limits adoption of high-power connected appliances requiring stable 230V supply for smart control modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Home Appliances Market |
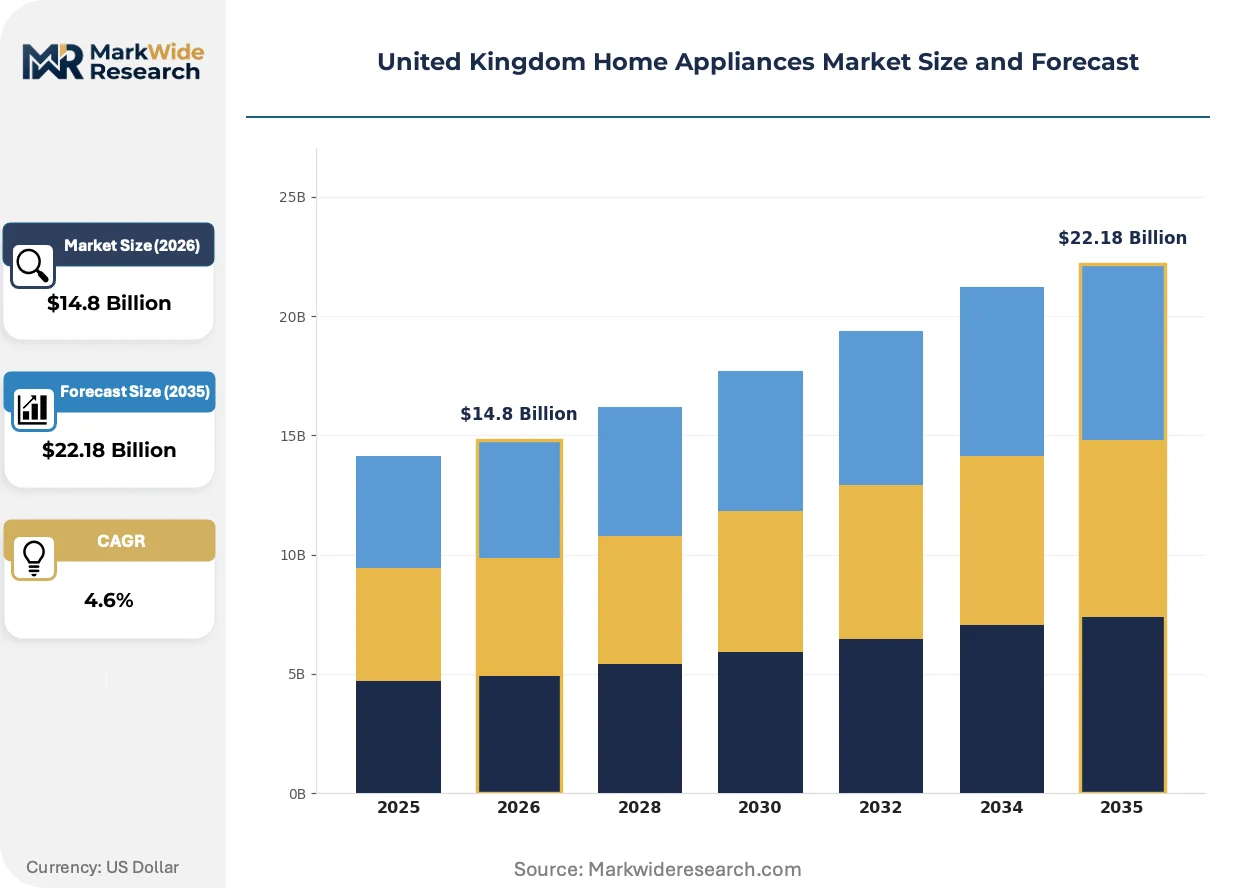
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Dishwashers Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Traditional End User: Households, Rental Properties, Commercial Kitchens, Hotels Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Discount Stores |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Electrolux AB, BSH Hausgeräte GmbH, Haier Electronics Group Co. Ltd, Panasonic Corporation, Miele & Cie. KG, Dyson Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Home Appliances Market Evolving Landscape
Connected diagnostics and AI-driven failure prediction are compressing traditional replacement cycles while creating new service revenue models. Manufacturers are racing to control the software layer across multiple appliance categories before interoperability mandates erode proprietary ecosystem advantages.
Inverter-driven variable-speed compressor technology is collapsing energy consumption differentials between premium and mid-tier refrigerator segments. Buy-to-let landlords in Greater London are specifying A-rated inverter models as standard fitments to minimize utility exposure in inclusive-rent contracts. This technology compression is eroding the historical 40% efficiency gap that justified premium pricing tiers.
The UKCA marking regime governing product safety and electromagnetic compatibility post-Brexit is fragmenting certification pathways for manufacturers with pan-European production footprints. Dual conformity assessment procedures now apply to appliances destined for UK versus EU markets, increasing compliance overhead and extending time-to-market for new product introductions. Refrigerator and washing machine categories face the heaviest documentation burdens due to compressor motor safety requirements.
After-sales service unbundling is accelerating as independent repair networks gain access to spare parts and technical documentation under emerging right-to-repair frameworks. Manufacturers with captive service operations in the South East are seeing aftermarket revenue migrate to third-party technicians, while pure-play hardware vendors without service infrastructure face margin pressure from commoditized repair competition. This channel shift is most visible in urban rental markets where landlords prioritize rapid turnaround over brand-authorized service relationships.
United Kingdom Home Appliances Market Segmentation
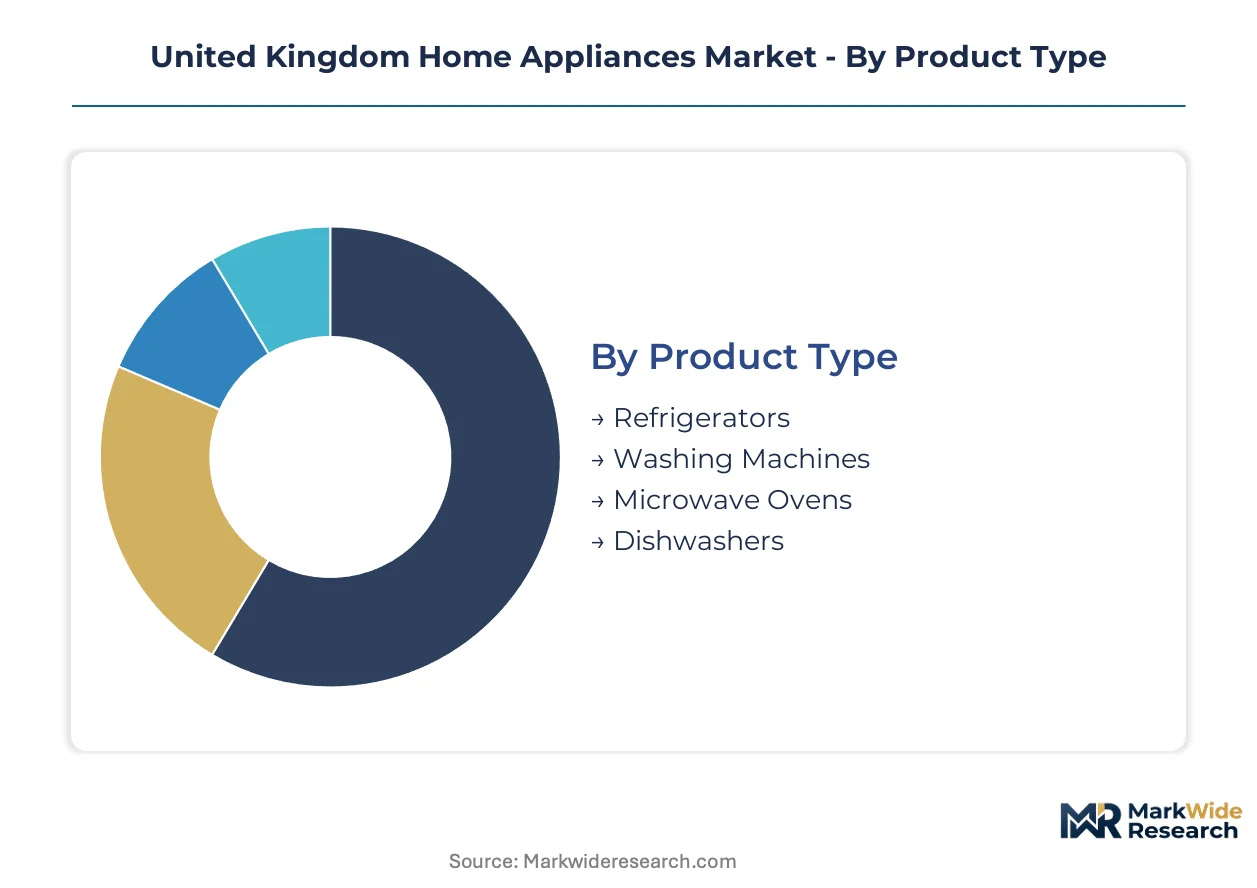
United Kingdom Home Appliances Market segmentation reveals distinct demand patterns across product maturity, technology adoption, and channel economics. Landlord-driven replacement cycles in Greater London concentrate volume in specific product and technology categories while creating geographic asymmetries in channel performance.
Product Type:
Mature categories dominate replacement volume while emerging segments capture technology-driven upgrades.
- Refrigerators:Compressor-based cooling systems with inverter-driven variable-speed technology now span A-rated efficiency tiers. Demand concentrates in Greater London rental properties where landlords specify energy-efficient models to minimize utility exposure under inclusive-rent contracts.
- Washing Machines:Front-loading drum assemblies with brushless direct-drive motors deliver water and energy savings through sensor-controlled load detection. South East housing stock turnover drives replacement cycles as property investors modernize units ahead of tenant changeover.
- Microwave Ovens:Magnetron-based heating systems with inverter power control enable precise temperature management for defrosting and cooking applications.
- Dishwashers:Recirculating pump systems with soil sensors optimize water consumption across variable load sizes for household and commercial installations.
Refrigerators retain volume leadership; Smart Appliances hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium connected systems from price-sensitive conventional equipment.
- Smart Appliances:Embedded Wi-Fi modules and cloud-connected control platforms enable remote operation and diagnostic telemetry through proprietary ecosystems. Greater London households and rental property managers drive adoption as energy monitoring becomes standard in premium housing segments.
- Energy-Efficient:Inverter compressors, heat pump drying systems, and advanced insulation materials deliver A-grade performance under revised BEIS labeling schemes. South East new build specifications mandate these technologies, creating regulatory tailwind for compliant manufacturers.
- IoT-Enabled:Sensor arrays and edge computing capabilities support predictive maintenance and usage pattern analytics for subscription service monetization.
- Traditional:Electromechanical control systems without network connectivity serve price-sensitive segments and legacy housing with incompatible electrical infrastructure.
Energy-Efficient models command the largest installed base; IoT-Enabled systems are climbing the fastest.
End User:
Customer type determines replacement urgency, specification requirements, and service relationship preferences.
- Households:Owner-occupiers in the South East prioritize A-rated efficiency and extended warranties for long-horizon ownership. Replacement cycles accelerate as BEIS Ecodesign regulations render older models non-compliant for resale or property transfer.
- Rental Properties:Buy-to-let landlords in Greater London specify durable mid-tier equipment with rapid repair turnaround capabilities. Energy efficiency minimizes utility cost exposure where rents include service charges.
- Commercial Kitchens:High-duty-cycle refrigeration and dishwashing equipment with stainless steel construction withstand continuous operation in food service environments.
- Hotels:Compact in-room appliances with quiet operation and integrated design aesthetics serve guest accommodation requirements across hospitality portfolios.
Rental Properties generate the most concentrated demand pulses; Commercial Kitchens show the steepest specification escalation.
Distribution Channel:
Geographic concentration in Greater London and the South East shapes channel performance and logistics economics.
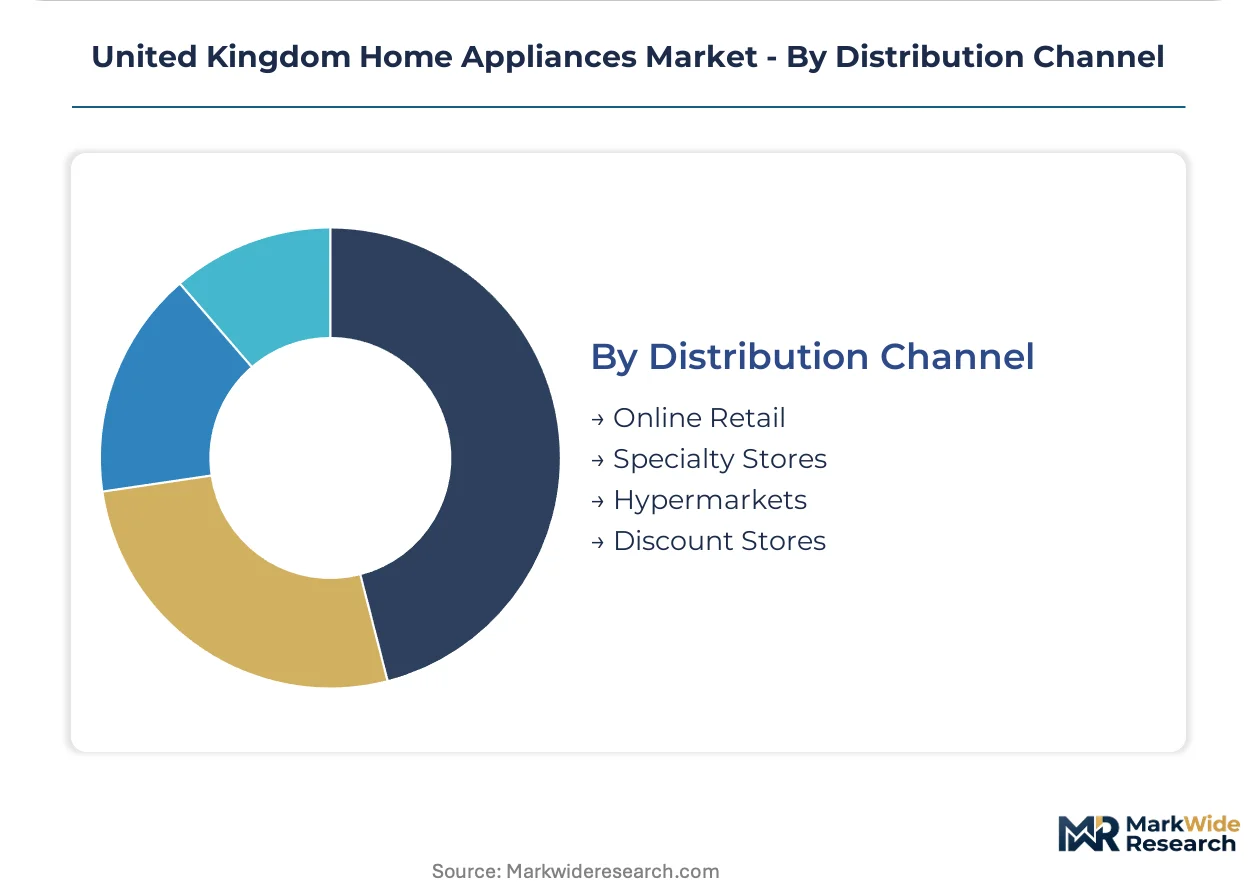
- Online Retail:Direct-to-consumer platforms with next-day delivery networks capture urban household purchases. Greater London density enables cost-effective last-mile fulfillment for bulky appliances.
- Specialty Stores:Curated showrooms with product demonstration and installation coordination serve high-consideration purchases. South East affluence supports premium positioning and extended service contracts.
- Hypermarkets:High-volume general merchandise retailers with established appliance categories serve price-comparison shoppers.
- Discount Stores:Limited-assortment operators with aggressive pricing target replacement-driven purchases in northern England and Wales.
Online Retail is gaining share fastest; Specialty Stores retain margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buy-to-let landlords in Greater London and the South East drive concentrated replacement demand, while northern regions present whitespace for appliance modernization programs targeting social housing providers.
Greater London
Rental property investors specify A-rated inverter refrigerators and washing machines to minimize utility exposure under inclusive-rent contracts. BEIS Ecodesign regulations enforce minimum energy performance standards that render older models non-compliant for property transfers. The South East commuter belt clusters installation and service infrastructure to support rapid turnaround requirements.
South East England
New build housing developments mandate smart-ready appliance specifications as standard fitments. UKCA marking requirements for electromagnetic compatibility create compliance overhead for manufacturers supplying this high-volume construction corridor. Brighton and Southampton port facilities handle inbound component shipments for regional distribution networks.
Midlands
Manufacturing heritage supports established appliance assembly and component stamping operations. Trading Standards offices in Birmingham conduct market surveillance to remove non-compliant products from distribution channels. The region's logistics infrastructure connects northern England and Wales to southern demand centers.
Scotland
Lower housing stock turnover creates underpenetration relative to southern England, presenting opportunity for social housing appliance modernization. Scottish Government energy efficiency programs diverting household capex toward building retrofits compress discretionary replacement budgets. Glasgow and Edinburgh rental markets show emerging specification escalation for connected diagnostics.
Northern England
Pre-1980s residential wiring in Manchester and Leeds limits adoption of high-power connected appliances requiring stable 230V supply. Heat pump substitution programs for gas boiler replacement compete for household capital expenditure. Discount retail channels capture price-sensitive replacement purchases in this region.
United Kingdom Home Appliances Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price positions. The vendor base stratifies between scale-driven diversified electronics conglomerates and focused premium appliance fabricators. Three archetypes dominate: ecosystem-integrated technology platforms, craftsmanship-positioned longevity specialists, and motor-technology vertical integrators. Competitive moves concentrate on smart home platform control and predictive maintenance service unbundling.
Within the ecosystem-integrated tier, Samsung Electronics represents the connected platform archetype through its SmartThings infrastructure. Miele & Cie. KG exemplifies the craftsmanship-positioned specialist model with extended lifecycle engineering. Dyson Ltd. occupies a position as the motor-technology vertical integrator developing proprietary systems through intensive in-house research. These three anchors illustrate divergent strategic paths for capturing value beyond hardware margins.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Haier Electronics Group Co. Ltd |
| Panasonic Corporation |
| Miele & Cie. KG |
| Dyson Ltd. |
| Others |
Value Network & Pricing Analysis
The Port of Felixstowe container corridor feeds UK appliance distribution networks where shipping cost indexation in supplier contracts compresses margins for inland-bound inventory. Steel coil and copper cathode arrivals through this gateway concentrate supply-side leverage among Rotterdam-integrated traders, forcing manufacturers to absorb freight volatility or surrender pricing power in the South East rental property segment.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate raw material procurement for compressor and motor assemblies. Three-tier pricing structure across premium, standard, and economy levels separates A-rated inverter models from conventional fixed-speed equipment, with certification grade as the primary differentiation driver. Pricing pressure stems from landlord procurement consolidation in Greater London, where volume buyers extract service bundling concessions. Price-sensitive discount channel purchasers in northern England resist premium positioning, while South East owner-occupiers accept extended warranty premiums.
Supply Chain Analysis
Supplier-financing facilities with 90-day extended terms anchor working capital structures for Chinese and Turkish component exporters serving UK assembly operations. Stamped steel forming draws from German and Italian tooling suppliers, while compressor motors rest on South Korean and Chinese winding operations. Single-source vulnerability concentrates in inverter control module semiconductors from Taiwan. Distribution runs through Midlands consolidation hubs connecting port arrivals to Greater London last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump HVAC systems threaten to displace discretionary appliance replacement budgets as UK building efficiency programs accelerate, forcing incumbents to defend share through service unbundling and predictive maintenance monetization.
For Market Incumbents: Build captive predictive maintenance ecosystems before interoperability mandates erode proprietary platform advantages. Deepen backward integration into inverter compressor manufacturing to defend margin position against commodity motor suppliers. Secure BEIS Ecodesign pre-certification for next-generation A-rated portfolios to outpace regulatory compliance timelines.
For New Entrants and Emerging Players: Build out social housing appliance modernization programs in Scotland and northern England where landlord-driven replacement cycles remain underpenetrated. Target rapid-repair service contracts for Greater London rental properties where turnaround speed outweighs brand loyalty. Pursue white-label connected module partnerships with established South East distributors lacking IoT development capabilities.
For Investors and Strategic Acquirers: Connected hardware vendors with established UK service infrastructure represent the most defensible acquisition archetype as right-to-repair legislation fragments aftermarket revenue. Long-term viability hinges on recurring software revenue attachment rates exceeding hardware replacement cycle compression. Monitor BEIS interoperability mandate announcements as the critical inflection signal for proprietary ecosystem valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Launch | Converts failure prediction algorithms into subscription revenue streams beyond initial hardware margins. |
| Inverter Compressor Backward Integration | Captures efficiency technology margins previously surrendered to South Korean motor specialists. |
| UKCA Pre-Certification Investment | Accelerates time-to-market advantage as dual CE-UKCA compliance burdens intensify post-Brexit. |
| Social Housing Channel Partnership | Unlocks Scotland and northern England whitespace through local authority procurement frameworks. |
| Smart Home Platform Integration | Positions appliances within unified control ecosystems before interoperability mandates fragment connectivity standards. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, procurement directors at buy-to-let property management firms, Trading Standards enforcement officers, and aftermarket service technicians; alongside secondary validation through BEIS regulatory filings, UKCA certification databases, customs import records, and housing stock turnover statistics from the Office for National Statistics. Bottom-up volume estimates triangulated against top-down spending allocation models across the projection horizon.
Forecast inputs span product type, technology tier, end-user category, and distribution channel segmentation with regional granularity at Greater London, South East, Midlands, Scotland, and northern England levels. CAGRs were derived from replacement cycle velocity modeling incorporating BEIS Ecodesign compliance deadlines and landlord portfolio modernization schedules. Energy label revision timelines and right-to-repair legislative progressions served as scenario-weighting variables throughout the modeling period.
Stress conditions across steel and copper price volatility, UKCA-CE dual certification timeline compression, and heat pump substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and rental property investment flows. Macroeconomic contraction, accelerated interoperability mandates, or breakthrough solid-state cooling technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Italy Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Residential Dishwashers Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
White Goods Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
Mexico Home Appliances Market