
 Saudi Arabia Home Appliances Market | 2026-2036
Saudi Arabia Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Home Appliances Market Analytics
Smart connectivity and inverter-driven compressor architectures are reshaping how manufacturers engineer cooling and cleaning appliances for Saudi households. Samsung Electronics leverages its semiconductor supply chain to integrate AI-powered diagnostics into refrigerators and washing machines. LG Electronics anchors its position through localized production capacity and climate-specific product tuning for Gulf humidity profiles. Haier Group competes aggressively on modular smart-home ecosystems that unify appliance control through single-platform interfaces.
Saudi Arabia home appliances encompass electromechanical devices designed for domestic tasks, typically operating on 220-240V at 60Hz with thermal insulation ratings adapted for ambient temperatures exceeding 45°C, serving functions of food preservation, garment cleaning, meal preparation, and indoor climate management. Air conditioners dominate volume due to cooling-degree-day intensity across the Kingdom, while smart appliances capture margin expansion through subscription-linked maintenance and energy optimization services. The hospitality end user segment shows structural momentum as hotel construction in NEOM and the Red Sea Project generates fleet procurement of standardized, connected room appliances.
SFDA enforces electrical safety and electromagnetic compatibility standards for all imported home appliances, while SASO mandates energy efficiency labeling that restricts market access for non-compliant products. The Saudi Energy Efficiency Center periodically revises minimum performance standards, forcing manufacturers to redesign compressor systems and insulation packages. Stakeholders must monitor how forthcoming building code integrations of appliance-level energy budgeting reshape specification requirements for new residential developments.
Market Dynamics
SFDA electrical safety mandates and SASO energy labeling revisions are forcing manufacturers to redesign compressor architectures and thermal insulation packages specifically for ambient temperatures exceeding 45°C.
Growth Catalysts
- NEOM hospitality construction:Hotel fleet procurement of standardized connected room appliances creates bulk demand for climate-optimized cooling and cleaning systems.
- Saudi Energy Efficiency Center mandates:Minimum performance standard revisions accelerate replacement cycles for non-compliant imported cooling equipment.
- Smart-home ecosystem convergence:Single-platform appliance control interfaces are migrating from premium to mid-market residential segments.
Market Restraints
- Copper and refrigerant input volatility:Compressor manufacturing costs fluctuate with global commodity pricing, squeezing margin structures for cooling equipment.
- East Asian supply concentration:Semiconductor and inverter component sourcing depends heavily on concentrated East Asian foundry capacity.
- SFDA electromagnetic compatibility testing:Extended certification timelines delay product launches for imported smart appliances.
Strategic Opportunities
- Red Sea Project tourism infrastructure:Coastal resort developments require corrosion-resistant outdoor units and humidity-optimized indoor climate systems.
- Subscription-linked maintenance services:Predictive diagnostics and energy optimization packages create recurring revenue streams beyond hardware sales.
- Building code energy budgeting:New residential developments in Riyadh and Jeddah are integrating appliance-level consumption specifications into construction standards.
Industry Challenges
- AI diagnostics engineering talent:Firmware development for predictive maintenance algorithms requires scarce embedded systems specialists.
- Legacy 220-240V infrastructure integration:Smart appliances must maintain compatibility with existing residential electrical distribution without full rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Home Appliances Market |
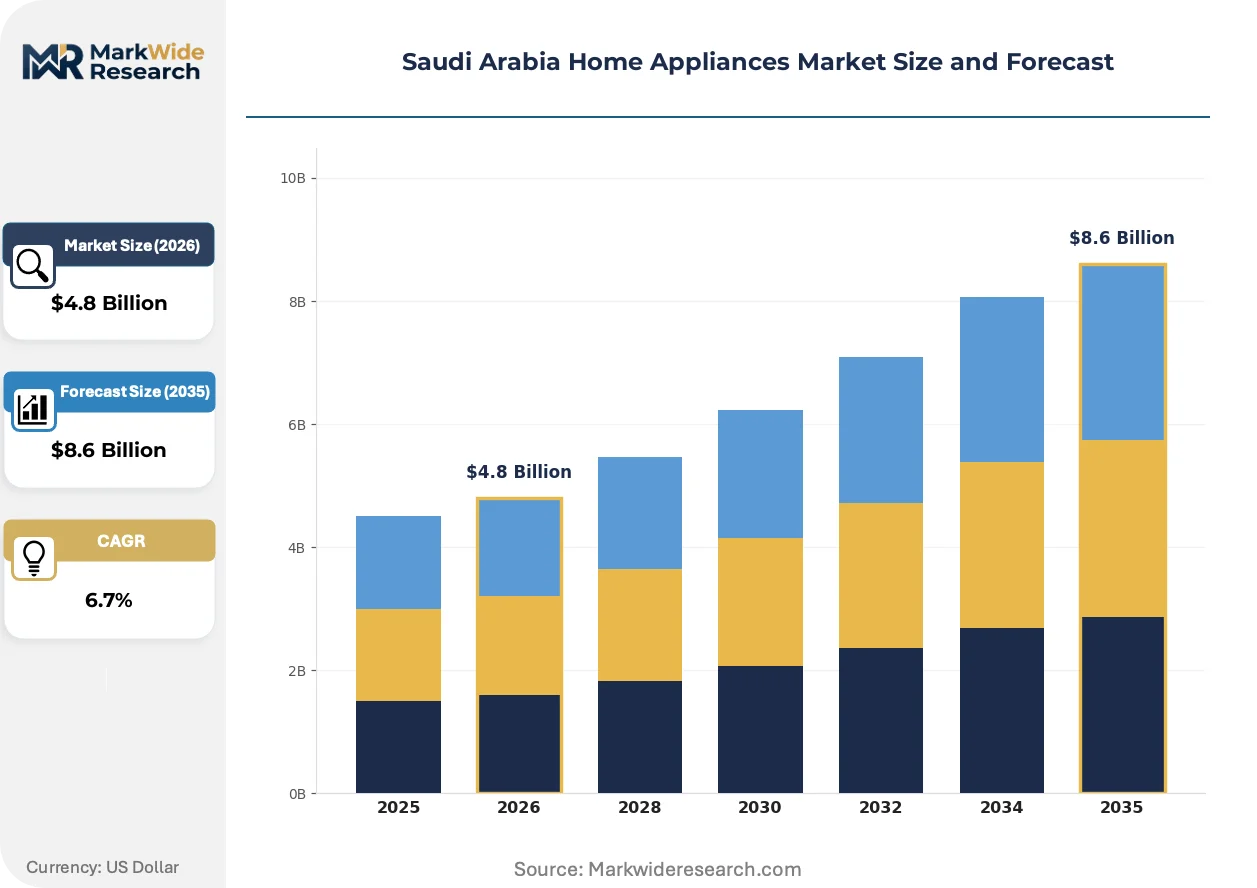
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Hypermarkets, Specialty Retailers, Distributors Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled |
| Companies Covered | Haier Group, Midea Group, Samsung Electronics, Electrolux AB, Panasonic Corporation, LG Electronics, Bosch, Hisense Group, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Home Appliances Market Evolving Landscape
Connectivity architectures and climate-specific engineering are reshaping how cooling and cleaning equipment serve Saudi households. Manufacturers now tune products for Gulf humidity profiles rather than adapting global platforms.
Inverter-driven compressor technology is migrating from fixed-speed to variable-speed modulation in residential air conditioners. Young urban families in Riyadh and Jeddah are adopting these units for granular temperature control. This migration from on-off cycling to continuous modulation is compressing energy consumption peaks and extending equipment lifespan.
SASO energy efficiency labeling mandates restrict market access for products below minimum performance tiers. The Saudi Energy Efficiency Center periodically revises these thresholds, forcing redesigns of insulation packages and motor systems. Cooling equipment importers are responding by pre-qualifying compressor architectures against anticipated standard updates.
After-sales service unbundling is fragmenting traditional dealer-warranty bundles. Direct-to-consumer digital channels are replacing authorized service networks for routine maintenance scheduling. This pattern is most visible in Jeddah's premium residential towers, where building management systems integrate predictive diagnostics into facility operations.
Saudi Arabia Home Appliances Market Segmentation
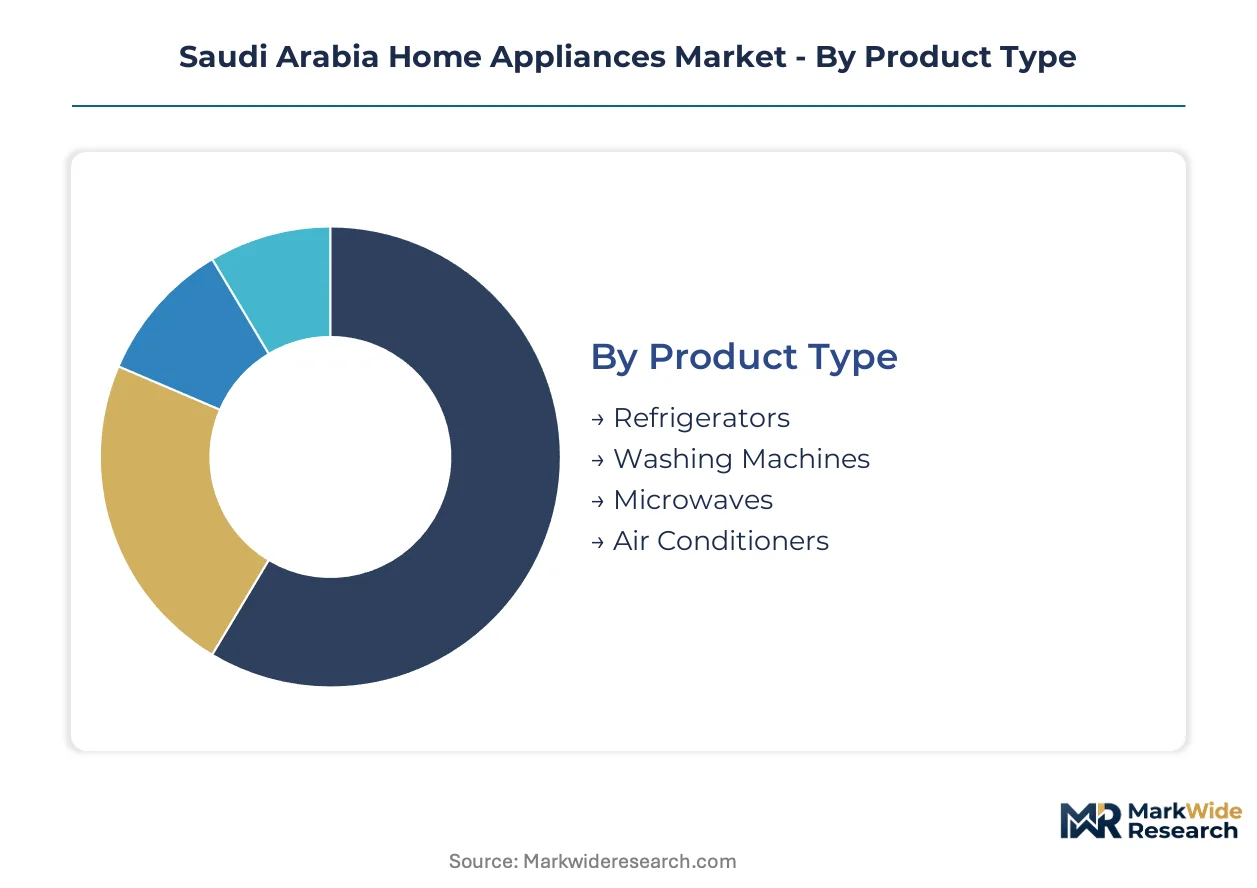
Segmentation in the Saudi Arabia home appliances market reveals distinct service intensity patterns across product categories. After-sales maintenance requirements vary dramatically between cooling equipment with compressor warranties and connected appliances with firmware update dependencies.
Product Type:
After-sales-service intensity peaks with cooling equipment requiring refrigerant handling certification, while cleaning appliances demand less specialized technical intervention.
- Air Conditioners:Split-system and window units dominate residential cooling loads with inverter-driven compressor architectures. Riyadh apartment towers and Jeddah coastal villas drive replacement demand as SASO efficiency mandates disqualify fixed-speed models from import clearance.
- Refrigerators:Frost-free and direct-cool configurations serve food preservation needs across Saudi households. Smart diagnostic models with AI-powered temperature management are gaining traction in premium residential developments near the Red Sea Project.
- Washing Machines:Front-load and top-load configurations address garment cleaning with varying water efficiency profiles.
- Microwaves:Solo, grill, and convection variants support meal preparation in compact urban kitchens.
By volume, air conditioners lead. By growth pace, smart refrigerators with predictive maintenance capabilities are climbing the fastest.
End User:
Cost tier differentiation separates fleet procurement with standardized specifications from individual household purchases prioritizing feature customization.
- Residential:Individual household purchases span studio apartments to villa compounds across Riyadh, Jeddah, and Dammam. Young urban families prioritize connected appliances with energy optimization subscriptions over extended warranty bundles.
- Hospitality:Hotel operators in NEOM and the Red Sea Project specify corrosion-resistant outdoor units and unified control interfaces for guest room fleets. Bulk procurement contracts emphasize predictive maintenance integration with building management systems.
- Commercial:Office complexes and retail spaces require durable cooling systems with extended duty cycles.
- Retail:Showroom and storage facilities need climate control for inventory preservation.
Residential captures the largest unit volumes. Hospitality procurement is expanding most quickly as giga-project construction accelerates.
Distribution Channel:
Geography concentrates premium appliance sales in Riyadh and Jeddah retail corridors, while peripheral regions depend on distributor networks with longer fulfillment timelines.
- Hypermarkets:Carrefour, Lulu, and Panda hypermarkets anchor mass-market appliance sales with immediate inventory availability. These channels dominate standard-efficiency cooling equipment purchases in suburban Riyadh districts.
- Online:Direct-to-consumer platforms and marketplace aggregators are displacing authorized dealer networks for routine maintenance scheduling. Jeddah's premium residential towers increasingly integrate predictive diagnostics through digital procurement channels.
- Specialty Retailers:Branded experience centers and multi-brand appliance showrooms serve specification-intensive buyers.
- Distributors:Regional wholesalers extend market reach into secondary cities and northern border provinces.
Hypermarkets maintain volume leadership. Online channels are gaining share fastest among connected appliance categories.
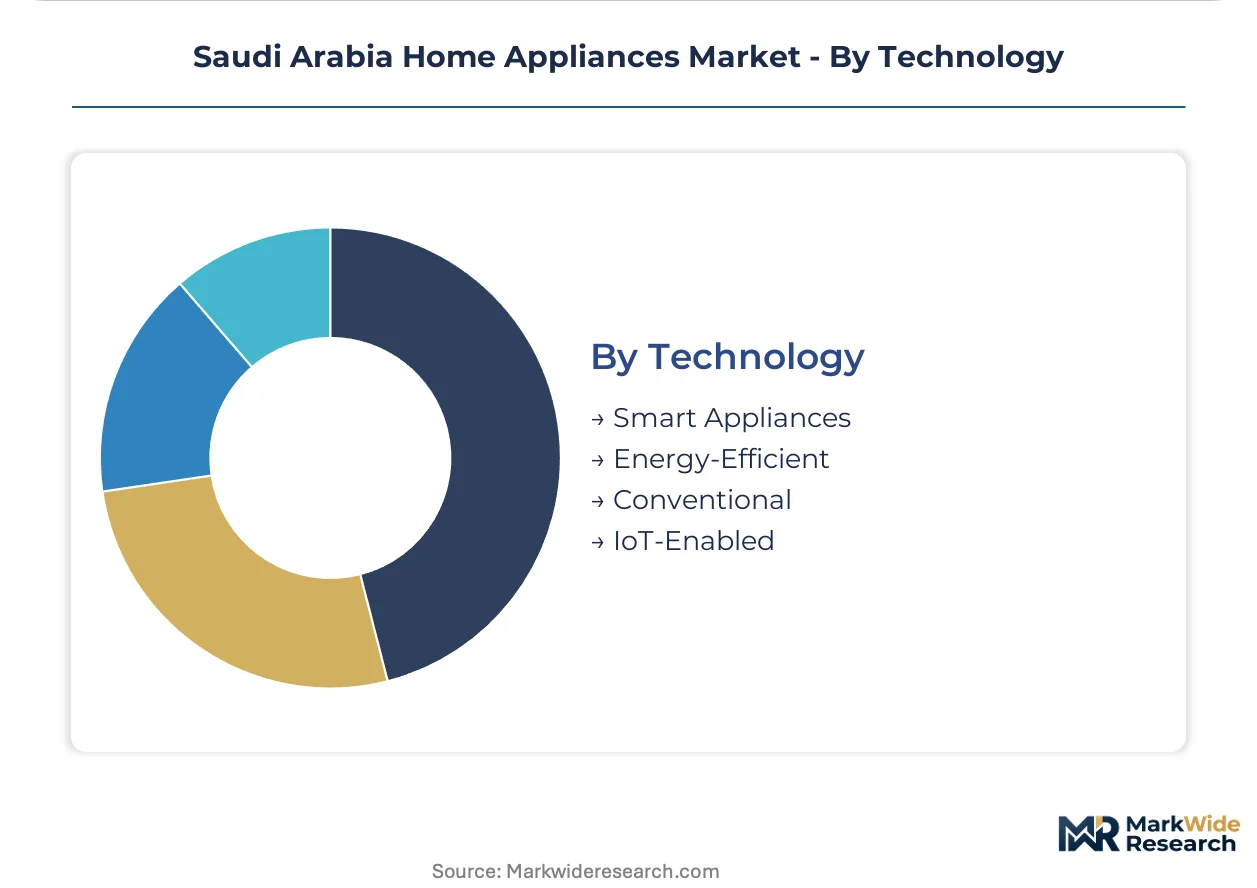
Technology:
Margin structures diverge sharply between subscription-linked smart appliances and conventional equipment sold through one-time transactions.
- Smart Appliances:AI-powered diagnostics and single-platform control interfaces unify refrigerator, washing machine, and air conditioner management. SFDA electromagnetic compatibility testing extends certification timelines for these imported units.
- IoT-Enabled:Connected sensors and cloud-based monitoring enable predictive maintenance and energy optimization services. NEOM hospitality developers specify these systems for centralized facility management integration.
- Energy-Efficient:Inverter compressors and enhanced insulation packages meet Saudi Energy Efficiency Center minimum performance standards.
- Conventional:Fixed-speed compressors and mechanical controls serve price-sensitive segments in peripheral regions.
Energy-efficient models dominate current unit sales. IoT-enabled appliances are on the steepest expansion trajectory as building code integrations advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium residential buyers concentrate in Riyadh and Jeddah, where new apartment towers and coastal villa compounds drive specification-intensive procurement of connected cooling and cleaning systems.
Riyadh
Young urban families in Al Olaya and King Abdullah Financial District prioritize smart refrigerators with AI-powered diagnostics and subscription-linked maintenance services. SFDA electrical safety mandates and SASO energy labeling revisions force importers to pre-qualify compressor architectures against anticipated standard updates. The King Abdullah Petroleum Studies and Research Center corridor anchors showroom clusters for Electrolux AB and Bosch experience centers.
Jeddah
Red Sea Project hospitality construction generates fleet procurement of corrosion-resistant outdoor units and unified control interfaces for guest room management. Building management systems in Al Hamra and Al Andalus districts integrate predictive diagnostics through digital procurement channels bypassing traditional dealer networks. The Jeddah Economic City development attracts premium appliance brands with climate-specific product tuning for Gulf humidity profiles.
Eastern Province
Dammam and Khobar industrial zones sustain commercial cooling demand from petrochemical facility expansion and port logistics infrastructure. SASO energy efficiency labeling restricts market access for fixed-speed compressor models, accelerating replacement cycles in Jubail residential compounds. The King Fahd Industrial Port cluster concentrates distributor warehouses serving northern border provinces with extended fulfillment timelines.
NEOM Northwest
Giga-project construction mandates standardized connected room appliances with centralized facility management integration for hospitality operators. The Saudi Energy Efficiency Center periodically revises minimum performance standards, forcing redesigns of insulation packages for ambient temperatures exceeding 45°C. THE LINE and Oxagon developments specify modular smart-home ecosystems unifying appliance control through single-platform interfaces.
Saudi Arabia Home Appliances Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where hypermarket dominance in suburban Riyadh contrasts with digital displacement of authorized service networks in Jeddah premium towers. The vendor base fragments between semiconductor-integrated manufacturers with captive AI diagnostics capability and climate-specific engineering specialists with localized production capacity. Two strategic archetypes dominate: ecosystem architects bundling single-platform control interfaces, and efficiency-focused fabricators redesigning compressor systems for SASO compliance cycles. Competitive moves concentrate on backward integration into inverter component sourcing and predictive maintenance service unbundling from traditional warranty bundles.
Within the ecosystem architect tier, Samsung Electronics and LG Electronics occupy positions defined by semiconductor supply chain leverage and localized Gulf climate tuning respectively. Haier Group anchors the modular smart-home convergence vector. Midea Group and Hisense Group exemplify scale-driven manufacturers with regional distributor network density. Bosch and Electrolux AB sit within the European-engineering positioning cluster, while Whirlpool Corporation and Panasonic Corporation represent diversified appliance portfolios with hospitality fleet procurement relationships.
| Leading Market Players |
|---|
| Haier Group |
| Midea Group |
| Samsung Electronics |
| Electrolux AB |
| Panasonic Corporation |
| LG Electronics |
| Bosch |
| Hisense Group |
| Whirlpool Corporation |
| Others |
Value Network & Pricing Analysis
Guangdong province manufacturing clusters anchor compressor and inverter component production, concentrating upstream capacity in ways that downstream Saudi distributors translate into tiered procurement leverage. SFDA electromagnetic compatibility testing extends certification timelines for smart appliances, compressing margin structures for importers who must pre-qualify inventory against anticipated SASO efficiency revisions.
Pricing Analysis
Cost-plus contracts with copper and refrigerant indexation dominate bulk procurement between East Asian manufacturers and Saudi distributors. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled smart appliances with subscription bundling from inverter-driven efficiency models and fixed-speed legacy units. Pricing pressure stems from commodity volatility in compressor metals, squeezing margin structures for cooling equipment. Hospitality fleet buyers in NEOM and the Red Sea Project exhibit lowest price sensitivity due to specification-intensive procurement, while individual households in peripheral provinces drive volume through economy-tier transactions.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Luxshare, and BYD Electronics holding capacity for semiconductor-integrated appliance controllers. China, South Korea, and Vietnam anchor component sourcing for inverter compressors, smart sensors, and connected control modules. Raw material dependencies center on copper windings, rare-earth magnets for motor efficiency, and refrigerant formulations compliant with evolving environmental protocols. Single-source vulnerability in East Asian foundry capacity for AI diagnostic chips poses structural risk. Distribution runs through Jeddah and Riyadh hypermarket corridors with extended fulfillment timelines to northern border provinces via Dammam distributor warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as single-platform appliance control interfaces migrate from premium installations to mid-market residential specifications, interoperability becoming the primary value capture mechanism.
For Market Incumbents: Entrench ecosystem control by deepening backward integration into inverter semiconductor sourcing and pre-qualifying compressor architectures against anticipated Saudi Energy Efficiency Center revisions. Defend against modular smart-home entrants by locking building management system integrations in Jeddah premium towers and NEOM hospitality developments. Channel control through hypermarket exclusivity agreements in suburban Riyadh remains a critical lever.
For New Entrants and Emerging Players: Northern border provinces and secondary cities beyond Dammam-Jubail corridor present underpenetrated distribution whitespace with extended fulfillment timelines creating service gaps. Target corrosion-resistant outdoor unit segments for Red Sea Project coastal resorts where humidity-optimized engineering requirements disqualify standard global platforms. Pursue direct-to-consumer digital channels with predictive maintenance subscription bundling to bypass entrenched authorized dealer networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive appliance divisions lacking Gulf climate-specific engineering capabilities. Long-term viability hinges on subscription-linked recurring revenue attachment rates exceeding hardware margin compression trajectories. Monitor SASO energy efficiency labeling revision timing as inflection indicator for replacement cycle acceleration and inventory obsolescence risk among non-compliant importers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inverter Components | Captive semiconductor supply secures AI diagnostic chip allocation ahead of SFDA certification bottlenecks. |
| Building Management System Partnership | Integration with Jeddah premium tower facility operations locks out competing smart-home platforms. |
| Subscription-Linked Maintenance Launch | Predictive diagnostics bundling transforms transactional hardware sales into recurring revenue streams. |
| Coastal Corrosion-Resistant Product Line | Red Sea Project hospitality specifications create defensible niche against standard global platforms. |
| Distributor Network Expansion | Direct warehousing in northern border provinces compresses fulfillment timelines versus Dammam hub dependency. |
Research Methodology
Desk research of customs import records, SASO certification databases, and hospitality procurement disclosures preceded structured interviews with appliance category managers at hypermarket chains, SFDA regulatory affairs specialists, and NEOM project procurement leads. Primary fieldwork with compressor manufacturers and inverter component suppliers validated secondary trade flow analysis. Bottom-up unit shipment estimates triangulated against top-down retail audit data from Riyadh and Jeddah corridor stores.
Assumption sets held Saudi Energy Efficiency Center mandate timelines and SFDA electromagnetic compatibility testing durations within observed historical patterns while varying NEOM construction pace and Red Sea Project hospitality rollout scenarios across the analysis window. Segmentation modeling incorporated product type, end-user vertical, distribution channel, and technology tier dimensions. CAGRs derived from regression analysis of replacement cycle acceleration against regulatory compliance deadlines, with compressor efficiency curves and smart appliance attachment rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling moves by semiconductor-integrated manufacturers or accelerated SASO efficiency tier revisions would shift outcomes beyond modeled ranges. Quarterly review of SFDA certification queue lengths, copper futures pricing, and NEOM hospitality construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
US Household Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
United States Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
White Goods Market
Home Appliances
Germany Household Side by Side Refrigerator Market