
 Mexico Major Home Appliance Market | 2026-2036
Mexico Major Home Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Major Home Appliance Market Foresight
The split between inverter-driven premium refrigerators and basic top-load washers is realigning how manufacturers allocate factory capacity across Mexico's appliance belt. Mabe leverages its Monterrey production base to dominate the domestic mid-range segment. Whirlpool sustains export-oriented scale from its Ramos Arizpe complex while competing for shelf space in Soriana and Chedraui chains.
Major home appliances encompass electrically powered refrigeration, clothes washing, dish cleaning, and food cooking equipment typically rated between 100 and 3,000 watts for residential and commercial installation. These units employ vapor-compression cycles, induction heating elements, or resistive coils to perform thermodynamic work, with efficiency measured by coefficient of performance or energy factor metrics under standardized test conditions. Refrigerators occupy the largest revenue pool given replacement cycles and frost-free technology penetration, while dishwashers represent the fastest-expanding category as Mexican households adopt built-in kitchen configurations. The price tier dimension concentrates margin capture in premium inverter models where LG Electronics and Samsung Electronics lead, whereas budget segments face compression from Hisense and Midea import strategies.
CONUEE enforces NOM-015 and NOM-022 energy-efficiency standards that mandate minimum performance thresholds for refrigerators and air conditioners sold in Mexico, directly influencing product design and import eligibility. PROFECO's consumer protection mandates require standardized labeling and warranty terms that shape retail competition and brand trust. Stakeholders must monitor potential alignment between Mexican efficiency standards and US Department of Energy rules given integrated North American supply chains.
Market Dynamics
NOM energy-efficiency labeling from Mexico's national standards body is compressing product development cycles while concentrating procurement power among large-format retailers in Mexico City and Guadalajara. Manufacturers must redesign compressor systems and insulation specifications to maintain import eligibility and shelf placement.
Growth Catalysts
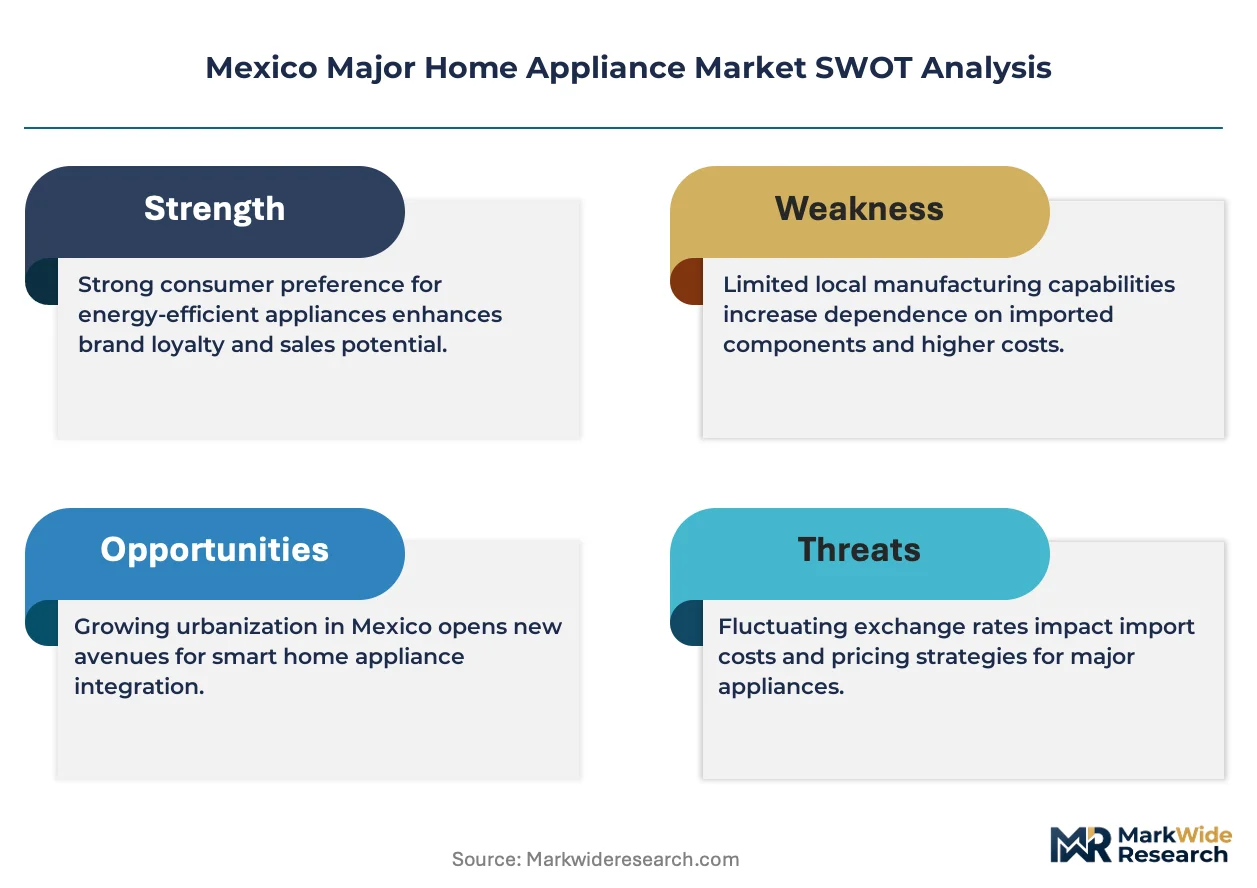
- Urban kitchen modernization:Households in Mexico City's Polanco and Condesa districts are replacing 15-year-old refrigerators with frost-free inverter models. This replacement wave accelerates as NOM-015 compliance becomes a visible purchase criterion.
- CONUEE efficiency mandates:The national energy efficiency commission's tightening of minimum performance thresholds for washing machines and refrigerators is forcing technology upgrades that expand the addressable premium segment.
- Querétaro manufacturing corridor concentration:Appliance production clusters near San Luis Potosí generate localized supplier ecosystems that reduce component lead times for domestic assembly operations.
Market Restraints
- Copper and steel input volatility:Compressor housings and cabinet frames depend on commodity metals whose price swings compress margin visibility for mid-range product lines.
- Import dependency for inverter modules:Power electronics for variable-speed compressors concentrate among Asian suppliers, creating single-source vulnerability for Mexican assembly plants.
- NOM certification timeline friction:PROFECO's testing and labeling requirements add 8-14 weeks to product launch schedules, disadvantaging smaller importers against established domestic producers.
Strategic Opportunities
- Built-in dishwasher penetration:Mexican kitchen renovation rates in Guadalajara's Zapopan district lag European benchmarks by 40 percentage points, creating expansion space for integrated appliance configurations.
- Induction cooktop substitution:Natural gas price uncertainty in central Mexico is accelerating electrician referrals for 240V kitchen circuits, enabling premium cooking equipment upgrades.
- Soriana and Chedraui private label expansion:Major retail chains are developing captive appliance brands that source directly from Querétaro-area factories, bypassing traditional distributor markups.
Industry Challenges
- Refrigerant technician certification gaps:Mexico's vocational training infrastructure produces insufficient technicians qualified to handle R600a and R290 hydrocarbon systems now required for high-efficiency units.
- Legacy 127V electrical infrastructure:Older residential circuits in Mexico City's central neighborhoods cannot support induction cooktops or large-capacity inverter refrigerators without costly rewiring.
- Warranty service network fragmentation:After-sales coverage in Baja California Sur and Yucatán depends on third-party contractors with inconsistent parts inventory, eroding brand trust in peripheral states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Major Home Appliance Market |
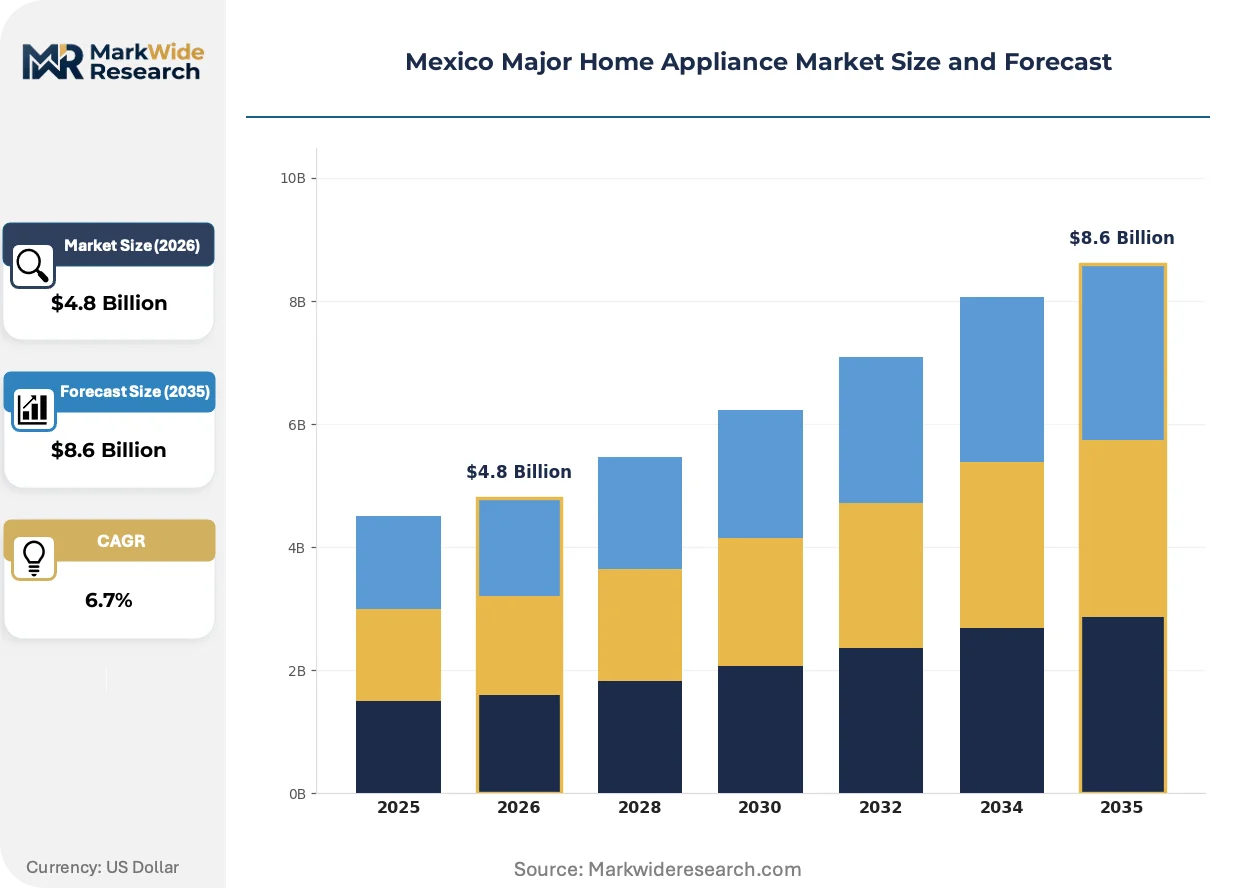
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Ovens End User: Residential, Commercial, Retail, Hospitality Distribution Channel: Online, Offline, Direct Sales, Wholesalers Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Mabe, Whirlpool, LG Electronics, Samsung Electronics, Hisense, Electrolux, Haier, BSH Home Appliances, Midea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Major Home Appliance Market Shifts & Advancements
Inverter-driven compressor technology is restructuring competitive advantage across Mexico's appliance belt. Variable-speed systems now dominate premium positioning while forcing recalibration of service revenue models and technician training investments.
Smart connectivity modules are automating diagnostic workflows and predictive maintenance scheduling for high-end refrigerator lines. Monterrey-based service operations deploy these systems to reduce truck rolls and compress resolution times. The technology is automating traditional break-fix revenue streams into subscription-based monitoring contracts.
CONUEE's alignment discussions with US Department of Energy efficiency protocols are creating dual-certification pathways for manufacturers operating integrated North American supply chains. Ramos Arizpe and Monterrey assembly plants face revised test procedures that harmonize NOM-015 with DOE refrigerator standards. This regulatory convergence most affects export-oriented facilities supplying cross-border retail channels.
Buyer concentration within Chedraui and Soriana procurement departments is displacing traditional distributor networks in metropolitan markets. Large-format retailers now specify energy efficiency tiers and warranty terms directly with Querétaro-area factories. This channel consolidation concentrates pricing power and compresses margin pools for independent appliance dealers in Mexico City and Guadalajara.
Mexico Major Home Appliance Market Segmentation
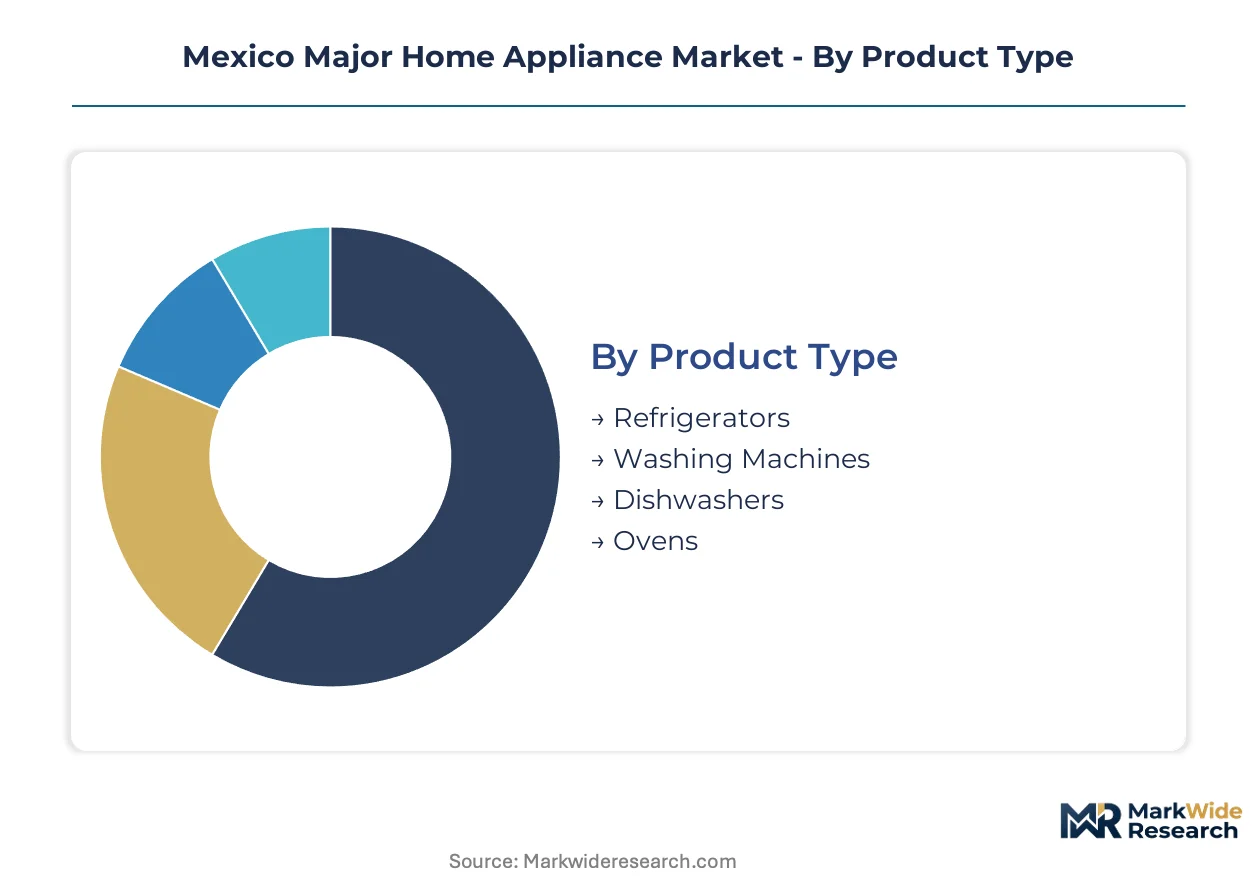
Segmentation in Mexico's appliance market tracks how NOM efficiency mandates and urban kitchen renovation cycles concentrate demand across distinct product tiers and buyer profiles. Manufacturers calibrate factory output across these dimensions to align with replacement waves in Mexico City and Guadalajara.
Product Type:
Replacement cycles and efficiency upgrades are concentrating procurement decisions around specific appliance categories as households modernize aging kitchen equipment.
- Refrigerators:Frost-free inverter models with variable-speed compressors dominate upgrade activity in Polanco and Condesa districts. NOM-015 compliance visibility drives purchasing toward certified units with hydrocarbon refrigerants.
- Washing Machines:Front-load configurations with water-recovery systems are gaining share in Guadalajara's Zapopan corridor. CONUEE tightening of minimum performance thresholds is forcing technology upgrades that expand premium addressability.
- Dishwashers:Built-in units lag European penetration by substantial margins, creating expansion space as kitchen renovations accelerate.
- Ovens:Induction and convection systems depend on 240V circuit availability in newer residential construction.
Volume placements concentrate in refrigerators; the faster expansion belongs to dishwashers.
End User:
Cost tier differentiation shapes how manufacturers allocate service infrastructure and warranty terms across buyer categories with diverging replacement frequencies.
- Residential:Urban households in central Mexico drive frost-free refrigerator upgrades with 12-15 year replacement cycles. Energy efficiency labeling directly influences purchasing decisions at Soriana and Chedraui point-of-sale.
- Commercial:Restaurant and food-service operations in Querétaro's manufacturing corridor demand heavy-duty refrigeration with rapid recovery cycles. NOM certification timelines create procurement friction for smaller operators.
- Retail:Appliance dealers in peripheral states face margin compression from large-format retailer procurement concentration.
- Hospitality:Hotel renovation cycles in Baja California Sur and Yucatán depend on third-party service networks with inconsistent parts inventory.
Residential buyers anchor volume; hospitality applications are climbing the fastest as tourism infrastructure expands.
Distribution Channel:
Channel configuration determines how efficiency specifications and warranty terms flow from Querétaro-area factories to end buyers across Mexico's geographic spread.
- Online:E-commerce platforms are capturing growing share of inverter refrigerator sales in metropolitan markets with standardized NOM labeling visibility.
- Offline:Soriana and Chedraui procurement departments now specify energy tiers directly with manufacturers, displacing traditional distributor networks.
- Direct Sales:Project-based channels serve commercial kitchen configurations with customized installation requirements.
- Wholesalers:Independent dealers in Mexico City and Guadalajara face pricing power concentration from retail chain private label expansion.
Offline channels dominate current volume; online penetration is gaining share fastest in urban districts.
Price Tier:
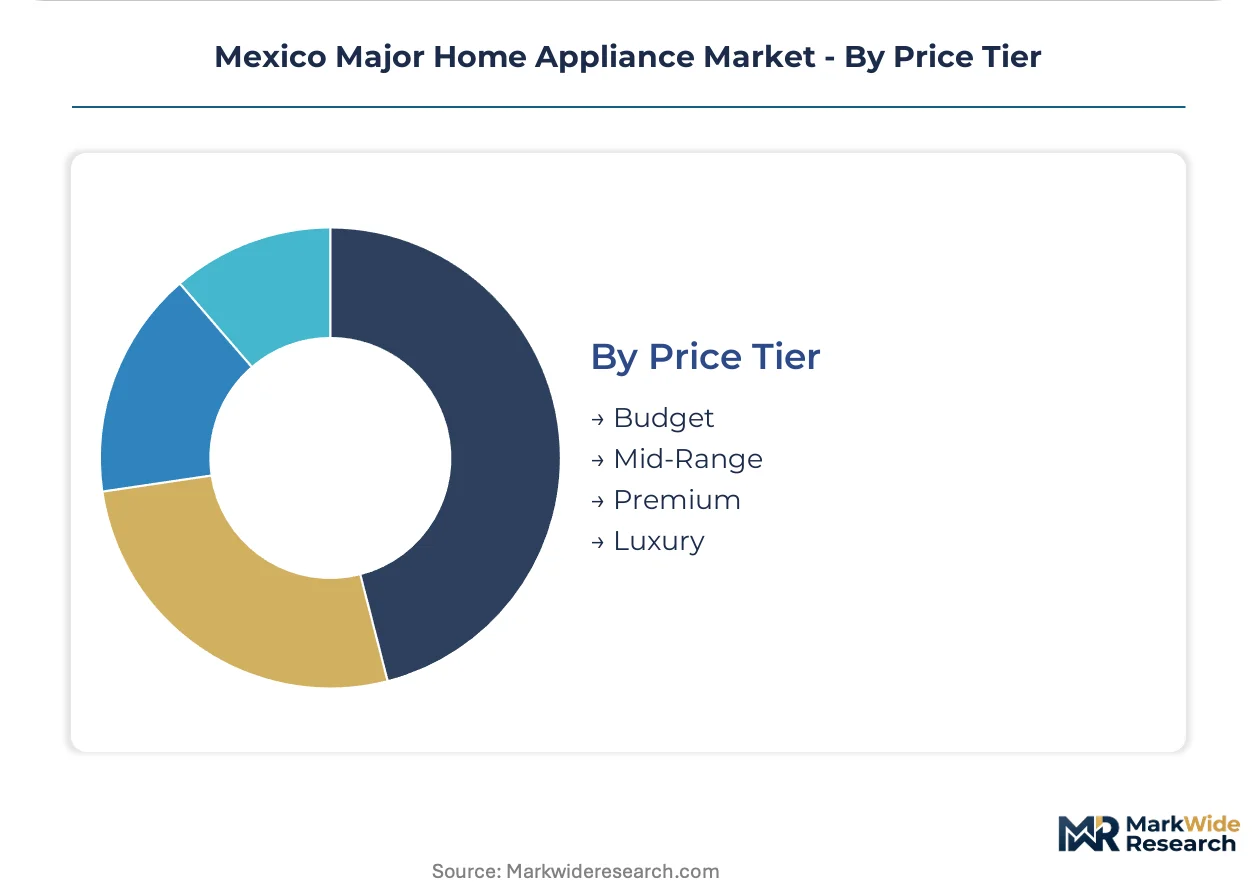
Margin capture stratifies across efficiency certification levels and compressor technology tiers, with inverter modules concentrating value in upper segments.
- Budget:Basic top-load washers and single-door refrigerators face compression from Hisense and Midea import strategies targeting price-sensitive buyers.
- Mid-Range:Mabe leverages Monterrey production to dominate this segment with NOM-compliant units balancing efficiency and accessibility.
- Premium:Inverter-driven frost-free refrigerators with smart connectivity modules command expanded margins in Mexico City's upgrading districts.
- Luxury:Built-in configurations and professional-grade cooking equipment serve high-end kitchen renovation projects with specialized installation requirements.
Mid-range placements anchor domestic factory output; premium tier applications show steepest expansion trajectory as efficiency mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central Mexico's manufacturing corridor from Querétaro through San Luis Potosí concentrates appliance production capacity and supplier ecosystems. This geographic clustering shapes procurement patterns for retailers across the republic.
Mexico City Metro
Households in Polanco and Condesa districts drive frost-free refrigerator upgrades with 12-15 year replacement cycles. CONUEE's NOM-015 energy-efficiency labeling directly influences purchasing decisions at Soriana and Chedraui point-of-sale. The metropolitan area's dense electrical infrastructure supports induction cooktop adoption despite legacy 127V circuit limitations in older central neighborhoods.
Nuevo León
Monterrey anchors domestic mid-range production with localized assembly operations serving northern Mexico distribution networks. PROFECO's warranty enforcement mandates shape after-sales service investments by manufacturers operating from this industrial base. The state's technical vocational institutes struggle to produce sufficient technicians qualified for hydrocarbon refrigerant systems.
Jalisco
Guadalajara's Zapopan corridor exhibits front-load washing machine penetration growth as kitchen renovation rates accelerate. CONUEE tightening of minimum performance thresholds for washing equipment expands premium segment addressability. Local appliance dealers face margin compression from large-format retailer procurement concentration.
Bajío Region
Querétaro's manufacturing belt generates localized supplier ecosystems reducing component lead times for domestic assembly. NOM certification timelines create procurement friction for smaller commercial operators sourcing heavy-duty refrigeration. The corridor's industrial parks attract power electronics suppliers for variable-speed compressor modules.
Northern Border States
Export-oriented facilities in Ramos Arizpe face revised test procedures harmonizing NOM-015 with US Department of Energy refrigerator standards. Dual-certification pathways affect cross-border retail channel supply strategies. Copper and steel input volatility from commodity markets compresses margin visibility for mid-range product lines assembled in this zone.
Mexico Major Home Appliance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across inverter technology tiers and energy-efficiency certification levels. The market structure consolidates around three distinct player categories: domestic manufacturers with established service networks, multinational assemblers with export-oriented scale, and import-dependent distributors targeting price-sensitive segments. Strategic differentiation concentrates in vertical control over compressor technology and captive after-sales infrastructure.
Within the domestic manufacturer tier, Mabe leverages its Monterrey production base to anchor mid-range positioning. Among multinational electronics groups, LG Electronics and Samsung Electronics occupy the premium inverter refrigerator segment. Hisense and Midea represent import-dependent challengers compressing budget-tier pricing through direct sourcing strategies.
| Leading Market Players |
|---|
| Mabe |
| Whirlpool |
| LG Electronics |
| Samsung Electronics |
| Hisense |
| Electrolux |
| Haier |
| BSH Home Appliances |
| Midea |
| Others |
Supply & Pricing Matrix
NOM-015 energy-efficiency certification gates both qualified component supply and premium-tier pricing access for manufacturers operating in Mexico's appliance market. This regulatory threshold concentrates procurement power among large-format retailers while forcing redesign cycles that compress margin visibility for non-compliant importers.
Pricing Analysis
Energy-factor performance anchors value-based pricing for frost-free inverter refrigerators sold through Soriana and Chedraui networks. Three-tier pricing structure across premium, standard, and economy levels separates NOM-certified inverter models from basic top-load configurations, with certification grade and compressor technology tier as primary differentiation drivers. Cost compression in budget segments is intensifying because Hisense and Midea direct-import strategies bypass traditional distributor markups. Residential buyers in Mexico City's Polanco district show lowest price sensitivity for smart-connectivity premium lines, while peripheral state households remain most responsive to promotional pricing on entry-level units.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and compressor refurbishment remain underdeveloped across Mexico's appliance belt, creating aftermarket service gaps in Baja California Sur and Yucatán. Component manufacturing concentrates in China, South Korea, and Mexico's Querétaro corridor, with power electronics for variable-speed compressors drawing from Asian suppliers. Copper and steel input volatility creates margin compression risk for mid-range product lines assembled in Monterrey and Ramos Arizpe. Distribution runs through large-format retail procurement departments that now specify efficiency tiers directly with Querétaro-area factories, displacing independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technician scarcity for hydrocarbon refrigerant systems props pricing for incumbent service networks while constraining expansion capacity across Mexico's peripheral states.
For Market Incumbents: Hedge against import-dependent inverter module vulnerability by cultivating captive supply relationships with Querétaro-area power electronics suppliers. Secure backward integration into compressor assembly operations to defend margin position against Asian direct-import challengers. Prioritize certification investment for NOM-015 alignment with prospective US Department of Energy harmonization. For New Entrants and Emerging Players: Begin with built-in dishwasher penetration in Guadalajara's Zapopan corridor, where kitchen renovation rates lag European benchmarks by substantial margins. Target hospitality operators in Baja California Sur tourism zones with third-party service partnerships that address warranty network fragmentation. Deploy direct-to-contractor go-to-market angles that bypass established retail channel concentration. For Investors and Strategic Acquirers: CONUEE alignment announcements with US Department of Energy protocols are the leading indicator that dual-certification capacity will command acquisition premiums. Frame long-term viability around manufacturers with integrated North American supply chain positioning and captive after-sales infrastructure. Monitor PROFECO warranty enforcement actions as signals of service network quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of variable-speed modules reduces Asian import dependency for Monterrey assembly plants. |
| NOM-015 Dual Certification Investment | Harmonized testing protocols with US DOE standards unlock cross-border retail channel access from Ramos Arizpe. |
| Technician Training Partnership Expansion | Collaboration with Nuevo León vocational institutes addresses hydrocarbon refrigerant certification gaps. |
| Direct Retail Procurement Relationships | Bypassing distributor networks with Soriana and Chedraui specifications concentrates pricing power. |
| Smart Connectivity Module Integration | Predictive maintenance subscriptions transform break-fix service revenue for high-end refrigerator lines. |
Research Methodology
CONUEE regulatory filings, PROFECO consumer protection databases, and Mexican customs trade records formed the secondary backbone for this analysis. Primary interviews with appliance manufacturing plant managers, large-format retail category buyers, aftermarket service network operators, and CONUEE compliance officers combined with secondary validation to construct segment-level demand estimates. Bottom-up triangulation across factory output data and top-down cross-checks against retail channel shipment records anchored volume projections.
Historical trendline analysis of replacement cycle patterns and efficiency upgrade penetration informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel configuration, and price tier positioning. CAGRs derived from regression analysis of certified unit shipment growth and urban household formation rates in central Mexico manufacturing corridors, with NOM-015 compliance timelines and copper price volatility as key forecast inputs.
Underlying measurement precision varies by segment; refrigerator and washing machine categories carry tighter precision than dishwasher and induction cooktop estimates due to established certification reporting requirements. Forecasts reflect documented assumptions regarding CONUEE enforcement intensity and retail channel consolidation velocity. Practitioners should monitor hydrocarbon refrigerant technician graduation rates and natural gas price movements in central Mexico for early signals of market trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Washing Machine Market
Home Appliances
Built-In Hobs Market
Home Appliances
Major Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Chile Home Appliances Market
Home Appliances
Range Hood Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Home Appliances Glass Market