
 UAE Major Home Appliances Market | 2026-2036
UAE Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Major Home Appliances Market Analytics
Aftermarket service revenue is rewriting profit expectations for distributors serving the UAE's appliance base. Panasonic Marketing Middle East & Africa FZE leverages its regional parts depot network to capture recurring maintenance contracts. Robert Bosch Middle East FZE anchors its position through technician certification programs that lock in dealer loyalty. Samsung Gulf Electronics competes by extending same-day repair coverage across Dubai, Sharjah, and Abu Dhabi corridors.
UAE major home appliances encompass electrically powered domestic machines with rated capacities from 200-liter refrigeration volumes to 12-kilogram laundry loads, engineered for ambient temperatures exceeding 45 degrees Celsius in Gulf climates. These units cool, clean, cook, or preserve food within residential and commercial premises governed by tropicalized compressor specifications and sand-filtered ventilation designs. Refrigerators lead product-type shipments due to replacement cycles shortened by harsh operating conditions, while smart appliances represent the fastest-expanding technological feature as Wi-Fi-enabled diagnostics align with UAE utility demand-response programs. Built-in units command premium positioning in new villa developments across Mohammed bin Rashid City and Saadiyat Island, where developers specify integrated kitchen packages.
MOHAP enforces electrical safety conformity for all imported appliances, while the Emirates Authority for Standardization and Metrology mandates energy-label grading that restricts entry of sub-tier cooling equipment. ESMA's ecodesign regulations are pushing manufacturers to redesign compressor systems for the local climate, effectively filtering out legacy platforms not engineered for Gulf thermal stress. Stakeholders must monitor how Abu Dhabi's forthcoming building codes for sustainable districts will specify appliance efficiency tiers before procurement cycles for master-planned communities finalize.
Market Dynamics
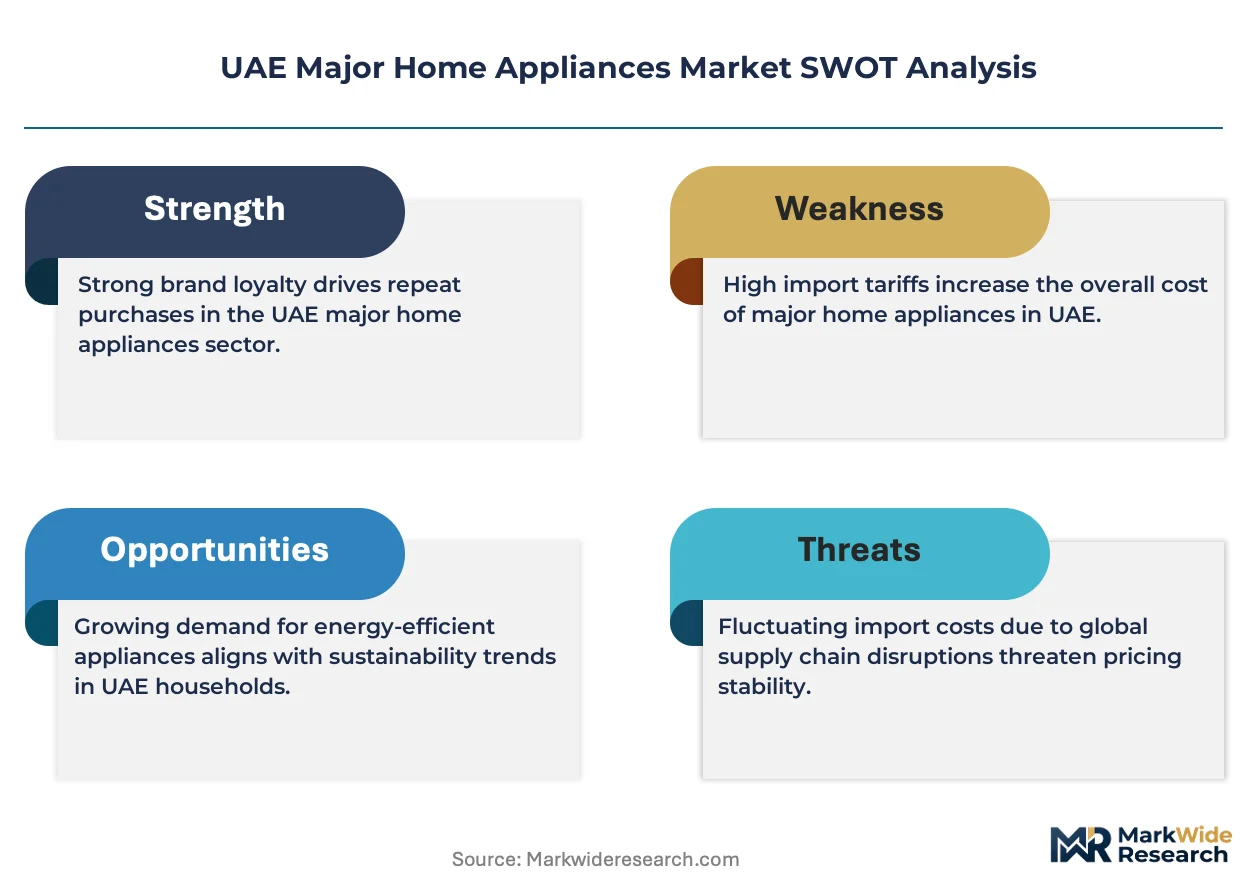
ESMA's ecodesign regulations are compressing product lifecycles for cooling equipment while accelerating compressor redesign cycles among manufacturers serving the Emirates. This regulatory pressure is restructuring procurement specifications for master-planned communities across Dubai and Abu Dhabi.
Growth Catalysts
- Smart Kitchen Suites:Wi-Fi-enabled diagnostics align with UAE utility demand-response programs, shortening replacement cycles for residential buyers in premium villa developments.
- MOHAP Electrical Safety Conformity:Mandatory import certification creates quality-based filtering that elevates established distributors with compliant supply chains.
- Hospitality Sector Bulk Procurement:Hotel construction across Ras Al Khaimah and Fujairah drives built-in refrigeration and laundry system orders with multi-year service attachments.
Market Restraints
- Copper and Steel Input Volatility:Compressor manufacturing costs fluctuate with commodity pricing, squeezing margin buffers for mid-tier appliance assemblers.
- Single-Source Compressor Supply:Tropicalized compressor engineering concentrates among specialized Southeast Asian foundries, creating geographic concentration risk for UAE distributors.
- Legacy Platform Exclusion:ESMA energy-label grading filters out cooling equipment not engineered for Gulf thermal stress, eliminating low-cost import alternatives.
Strategic Opportunities
- Northern Emirates Hospitality:Underpenetrated hotel supply chains in Ajman and Umm Al Quwain offer first-mover positioning for integrated kitchen package providers.
- Aftermarket Service Unbundling:Recurring maintenance contracts for sand-filtered ventilation systems create recurring revenue streams separate from unit sales.
- Abu Dhabi Sustainable District Codes:Forthcoming building efficiency mandates will specify appliance tiers before procurement finalization for Saadiyat Island developments.
Industry Challenges
- Tropicalized Technician Certification:Gulf-specific compressor repair skills remain scarce, forcing distributors to fund in-house training programs or lose dealer loyalty.
- Multi-System Integration Complexity:Smart appliance diagnostics require coordination with UAE utility back-end systems, extending deployment timelines for property developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Major Home Appliances Market |
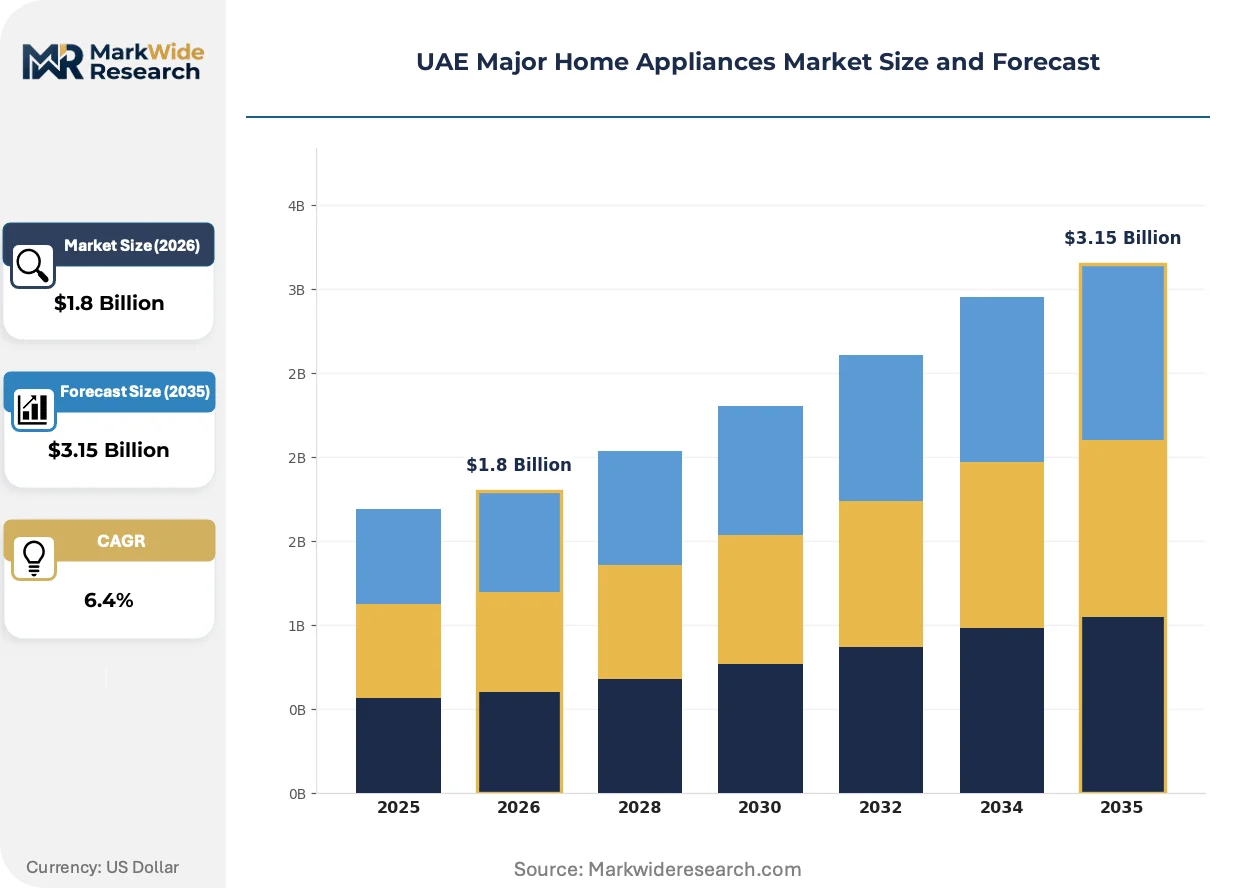
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Technological Feature: Smart Appliances, Energy-Efficient Models, Traditional Designs, Built-In Units End User: Residential Buyers, Rental Properties, Hospitality, Commercial Kitchens Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Panasonic Marketing Middle East & Africa FZE, Robert Bosch Middle East FZE, LG Electronics Gulf, AB Electrolux, Midea Middle East, Samsung Gulf Electronics, Haier Middle East, Sharp Middle East, Whirlpool Middle East, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Major Home Appliances Market Evolving Landscape
Climate-adaptive engineering and connected diagnostics are redefining product specifications across the Emirates. Manufacturers must now engineer for ambient thermal stress while embedding software architectures that interface with utility infrastructure.
Variable-speed inverter compressors optimized for 45-degree Celsius ambient operation are rendering obsolete fixed-speed refrigeration platforms across UAE residential installations. Property developers in Mohammed bin Rashid City specify these units exclusively for new villa deliveries. The technology is compressing replacement cycles as legacy systems fail prematurely under Gulf thermal load.
ESMA's ecodesign regulations mandate energy-label grading that restricts sub-tier cooling equipment from UAE import channels. Manufacturers must redesign compressor systems specifically for local climate stress or exit the market. Residential buyers in Dubai and Abu Dhabi now filter procurement through efficiency tier specifications that did not exist three years prior.
After-sales service unbundling is separating maintenance contracts from initial unit sales across hospitality procurement. Hotel operators in Sharjah and Ras Al Khaimah now negotiate multi-year technician coverage independent of appliance purchase agreements. This shift elevates distributors with captive service networks over pure-play equipment vendors.
UAE Major Home Appliances Market Segmentation
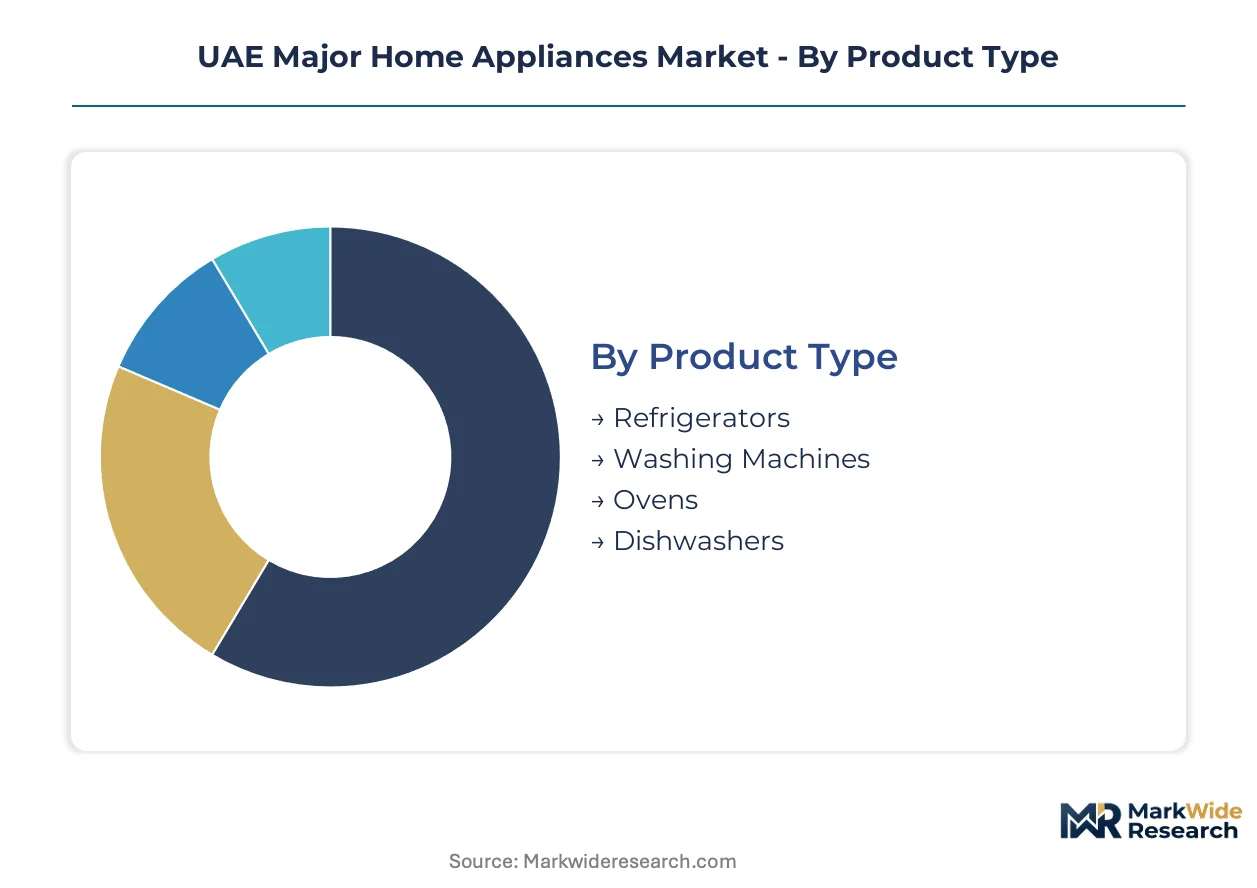
Segmentation in the UAE major home appliances market reveals how regulatory pressure, climate engineering requirements, and hospitality sector procurement reshape demand patterns across product categories and distribution channels. Understanding these divisions exposes where compressor redesign investments concentrate and where service unbundling creates recurring revenue.
Product Type:
Mature refrigeration platforms coexist with emerging smart cooking systems as ESMA regulations force divergent investment timelines across cooling and thermal appliances.
- Refrigerators:Tropicalized compressor systems rated for 45-degree Celsius ambient operation dominate specifications, with variable-speed inverter platforms displacing fixed-speed units in Dubai and Abu Dhabi villa developments. Harsh Gulf thermal stress shortens replacement cycles to under seven years, accelerating aftermarket parts demand.
- Washing Machines:Front-loading platforms with sand-filtered ventilation designs capture bulk hospitality procurement across Ras Al Khaimah hotel construction. ESMA water-efficiency labeling now filters import eligibility for units above 8-kilogram load capacity.
- Ovens:Built-in convection systems integrate with smart kitchen suites specified by Mohammed bin Rashid City developers.
- Dishwashers:Compact under-counter units serve commercial kitchen installations in Sharjah and Ajman hospitality clusters.
Refrigerators retain volume leadership; built-in ovens hold the steepest expansion curve.
Technological Feature:
Cost tiers separate premium connected diagnostics from economy traditional platforms as utility integration mandates reshape procurement specifications.
- Smart Appliances:Wi-Fi-enabled compressor diagnostics interface with UAE utility demand-response programs, requiring software architectures that extend deployment timelines for property developers. These units command 40-60% price premiums in Saadiyat Island villa specifications.
- Energy-Efficient Models:ESMA energy-label grading restricts sub-tier cooling equipment from import channels, forcing compressor redesign specifically for Gulf thermal stress. Residential buyers now filter procurement through efficiency tiers absent three years prior.
- Traditional Designs:Fixed-speed refrigeration platforms without inverter technology serve price-sensitive rental property segments in northern emirates.
- Built-In Units:Integrated kitchen packages specified by developers in sustainable district codes anchor premium positioning.
Energy-efficient models dominate unit shipments; smart appliances are expanding most quickly as utility integration mandates harden.
End User:
Customer type determines service attachment rates and procurement cycle length, with hospitality operators unbundling maintenance from initial equipment purchase.
- Residential Buyers:Villa owners in Dubai and Abu Dhabi upgrade to smart kitchen suites as ESMA regulations elevate efficiency expectations. Replacement cycles accelerate as legacy systems fail under thermal load.
- Hospitality:Hotel construction across Ras Al Khaimah and Fujairah drives bulk procurement of built-in refrigeration with multi-year technician coverage negotiated separately from purchase agreements.
- Rental Properties:Cost-optimized traditional designs serve landlord specifications in Sharjah and Ajman residential towers.
- Commercial Kitchens:Heavy-duty laundry and refrigeration systems face MOHAP electrical safety conformity requirements for all imported equipment.
Residential buyers anchor volume demand; hospitality procurement delivers the steepest service revenue expansion.
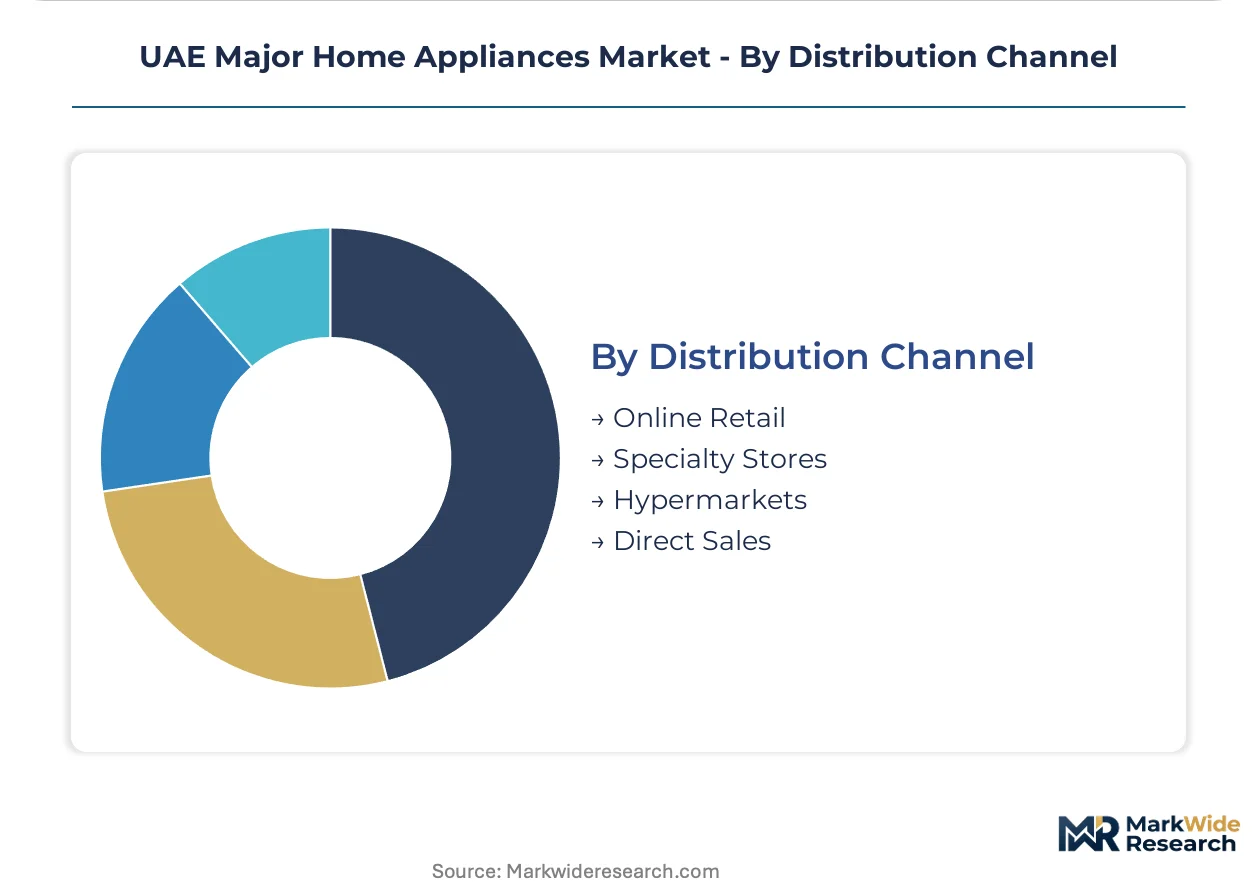
Distribution Channel:
Supply concentration in captive service networks differentiates distributor performance as aftermarket contracts separate from unit sales.
- Specialty Stores:Technicians certified for tropicalized compressor repair anchor dealer loyalty through in-house training programs. These outlets capture premium built-in kitchen package sales in Mohammed bin Rashid City developments.
- Online Retail:Same-day repair coverage across Dubai, Sharjah, and Abu Dhabi corridors elevates platforms with captive logistics networks. Smart appliance diagnostics require coordination with utility back-end systems.
- Hypermarkets:Volume-driven economy appliance sales concentrate in northern emirates retail footprints.
- Direct Sales:Bulk hospitality procurement bypasses retail channels for integrated kitchen package negotiations.
Specialty stores retain margin leadership; online retail gains share fastest through service coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Emirates. Dubai and Abu Dhabi buyers prioritize smart features and energy efficiency with minimal price elasticity, while northern emirates procurement remains cost-driven with shorter replacement cycles.
Dubai
Villa developments in Mohammed bin Rashid City specify integrated kitchen packages with variable-speed inverter compressors. ESMA energy-label grading filters sub-tier cooling equipment from retail channels. Smart appliance penetration concentrates in Saadiyat Island and Downtown Dubai clusters where utility demand-response integration commands 40-60% price premiums.
Abu Dhabi
Sustainable district codes for Masdar City and Al Reem Island mandate appliance efficiency tiers before master-planned community procurement finalizes. MOHAP electrical safety conformity elevates established distributors with compliant supply chains. Built-in refrigeration systems dominate new villa specifications on Yas Island.
Sharjah
Mid-market residential towers drive volume demand for cost-optimized traditional designs. Same-day repair coverage corridors anchor online retail platform expansion. Sand-filtered ventilation maintenance contracts create recurring revenue streams separate from unit sales.
Northern Emirates
Hotel construction across Ras Al Khaimah and Fujairah drives bulk procurement of built-in refrigeration with multi-year service attachments. Underpenetrated supply chains in Ajman and Umm Al Quwain offer first-mover positioning for integrated kitchen providers. Hospitality operators unbundle maintenance from initial equipment purchase.
UAE Major Home Appliances Market Competitive Landscape
Multi-regional electronics conglomerates and specialized Middle East distributors split the market through divergent channel strategies. The vendor base concentrates around captive service networks and certified technician programs rather than pure manufacturing scale. Three archetypes dominate: Gulf-based regional subsidiaries with localized parts depots, global brands with dedicated Middle East distribution arms, and integrated kitchen package specialists serving property developers. Competitive moves center on technician certification lock-in and multi-year hospitality service contracts.
Within the regional subsidiary tier, Panasonic Marketing Middle East & Africa FZE and Robert Bosch Middle East FZE exemplify distributors leveraging in-house training programs to anchor dealer loyalty. Samsung Gulf Electronics occupies a position emphasizing logistics network density for same-day repair coverage. These three entities represent contrasting approaches to aftermarket revenue capture—parts depot infrastructure, certification-based lock-in, and service response speed—each aligning with distinct procurement priorities across residential and hospitality segments.
| Leading Market Players |
|---|
| Panasonic Marketing Middle East & Africa FZE |
| Robert Bosch Middle East FZE |
| LG Electronics Gulf |
| AB Electrolux |
| Midea Middle East |
| Samsung Gulf Electronics |
| Haier Middle East |
| Sharp Middle East |
| Whirlpool Middle East |
| Others |
Value Network & Pricing Analysis
Single-source compressor dependency on Southeast Asian foundries compresses margin buffers for UAE distributors while simultaneously widening pricing spreads between premium inverter platforms and economy fixed-speed units. Copper and steel input volatility feeds directly into landed cost structures, forcing mid-tier assemblers to absorb fluctuations or cede position to vertically integrated rivals with captive component sourcing.
Pricing Analysis
Aftermarket service contracts now anchor lifetime value calculations across the Emirates, with multi-year technician coverage for sand-filtered ventilation systems commanding recurring premiums separate from initial unit sales. Pricing stratifies across premium smart kitchen suites with Wi-Fi diagnostics, standard energy-efficient models meeting ESMA label grades, and economy traditional designs for rental properties. Cost compression in mid-tier refrigeration stems from commodity volatility and compressor redesign cycles, while hospitality procurement shows minimal price sensitivity compared to northern emirates residential buyers.
Supply Chain Analysis
Extended payment terms from Thai and Malaysian compressor foundries have become standard for UAE distributors managing working capital through supply-chain finance facilities. Manufacturing concentration in Thailand, Vietnam, and China feeds tropicalized compressor engineering requirements, with copper winding and rare-earth magnet dependencies exposing assemblers to commodity price swings. Single-source vulnerability in specialized Southeast Asian foundries creates geographic concentration risk, while distribution runs through captive parts depot networks that lock in dealer loyalty through certified technician programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE major home appliances market functions as a regulatory-moat arena where ESMA certification requirements and tropicalized engineering standards create formidable switching costs for incumbent distributors with compliant supply chains.
For Market Incumbents: Harden dealer loyalty through accelerated technician certification programs targeting Gulf-specific compressor repair skills, while expanding captive parts depot coverage into underpenetrated northern emirates hospitality corridors. ESMA's tightening ecodesign mandates threaten legacy platform distributors; backward integration into tropicalized compressor sourcing or exclusive partnerships with Southeast Asian foundries secures supply continuity. For New Entrants and Emerging Players: Ajman and Umm Al Quwain hospitality supply chains present first-mover positioning for integrated kitchen package providers willing to unbundle maintenance contracts from equipment sales. Hotel construction across Ras Al Khaimah and Fujairah offers bulk procurement entry points, with same-day repair coverage corridors in Sharjah providing a service-led go-to-market angle distinct from established Dubai-Abu Dhabi incumbents. For Investors and Strategic Acquirers: Regional distributors with captive service networks and ESMA-compliant import certifications represent the most defensible acquisition archetype in this market. Long-term viability hinges on recurring aftermarket revenue attachment rates rather than unit sales velocity; monitor ESMA enforcement intensity and Abu Dhabi sustainable district code finalization as inflection indicators for procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Expansion | Panasonic and Bosch anchor dealer loyalty through Gulf-specific training programs that competitors cannot replicate without multi-year investment. |
| Parts Depot Network Extension | Samsung's same-day repair coverage across Dubai-Sharjah-Abu Dhabi corridors creates service-response differentiation that pure-play vendors lack. |
| Integrated Kitchen Package Positioning | Developers in Mohammed bin Rashid City specify built-in suites exclusively, locking out vendors without full-category portfolios. |
| Hospitality Service Unbundling | Hotel operators in Ras Al Khaimah now negotiate multi-year technician coverage separate from purchase agreements, elevating distributors with captive networks. |
| ESMA Compliance Infrastructure | Energy-label grading and electrical safety conformity requirements filter sub-tier imports, entrenching established distributors with compliant supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with appliance distribution executives, hospitality procurement managers, certified technician program directors, and ESMA regulatory affairs specialists. Secondary validation drew from Emirates Authority for Standardization and Metrology filings, MOHAP electrical safety conformity records, UAE customs trade data, and hospitality development pipeline databases. Bottom-up shipment estimates by product category and end-use segment were triangulated against top-down market value reconstructions.
Calibration against historical replacement cycle data and compressor failure rates in Gulf thermal conditions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technological feature tier, end-user category, and distribution channel structure. CAGRs were derived from regression analysis of regulatory mandate timelines, hospitality construction permits, and residential villa completion schedules. Climate-adaptive engineering adoption curves and smart appliance utility integration rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese manufacturers or accelerated ESMA enforcement timelines would shift outcomes. Macroeconomic deviation in copper and steel markets, regulatory expansion of sustainable district codes, or breakthroughs in solid-state cooling technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Built-In Appliance Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Refrigerator Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Chile Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
North America Home Appliances Market
Home Appliances
United States Major Home Appliances Market