
 Middle East and Africa Coffee Market | 2026-2036
Middle East and Africa Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Coffee Market Foresight
Ethiopia's processing capacity expansion is tilting regional supply dynamics as the country deepens its washing station infrastructure and export-grade sorting capabilities. Nestlé SA leverages its soluble coffee manufacturing footprint across East Africa to sustain volume leadership in instant formats. JDE Peet's N.V. anchors its position through licensed roasting partnerships in the Gulf, while Al Mokha Yemen Coffee differentiates via heritage varietal sourcing from high-altitude microclimates. Strauss Group Ltd competes through café chain supply contracts in Israel and selective North African markets.
Coffee comprises roasted seeds of Coffea species, typically Arabica or Robusta, processed through washing or natural drying to achieve moisture contents below twelve percent for stable green bean storage and subsequent roasting to develop volatile aromatic compounds for beverage extraction. The primary commercial purpose spans prepared beverage service, retail packaged goods, and industrial ingredient supply for food manufacturing. Arabica commands premium positioning across Gulf café markets where consumers pay for traceable origin and cupping scores, while Robusta supplies the instant coffee segment where JDE Peet's and Nestlé concentrate manufacturing scale. The food service application leads value capture as Dubai and Riyadh hotel chains expand specialty coffee programs, whereas e-commerce distribution channels grow fastest through platform partnerships reaching Saudi households beyond traditional supermarket coverage.
Saudi Arabia's Saudi Food and Drug Authority governs import registration and labeling requirements for packaged coffee, while the UAE's Ministry of Industry and Advanced Technology administers product standards for roasted and soluble formats entering Gulf markets. Ethiopia's Coffee and Tea Authority regulates export licensing and quality grading, directly shaping which lots access premium European and Middle Eastern buyers. The EU Deforestation Regulation will force due diligence documentation onto African exporters, altering compliance costs and traceability investments. Stakeholders must monitor how Gulf sovereign wealth participation in East African farming concessions reshapes origin control and long-term supply contracting.
Market Dynamics
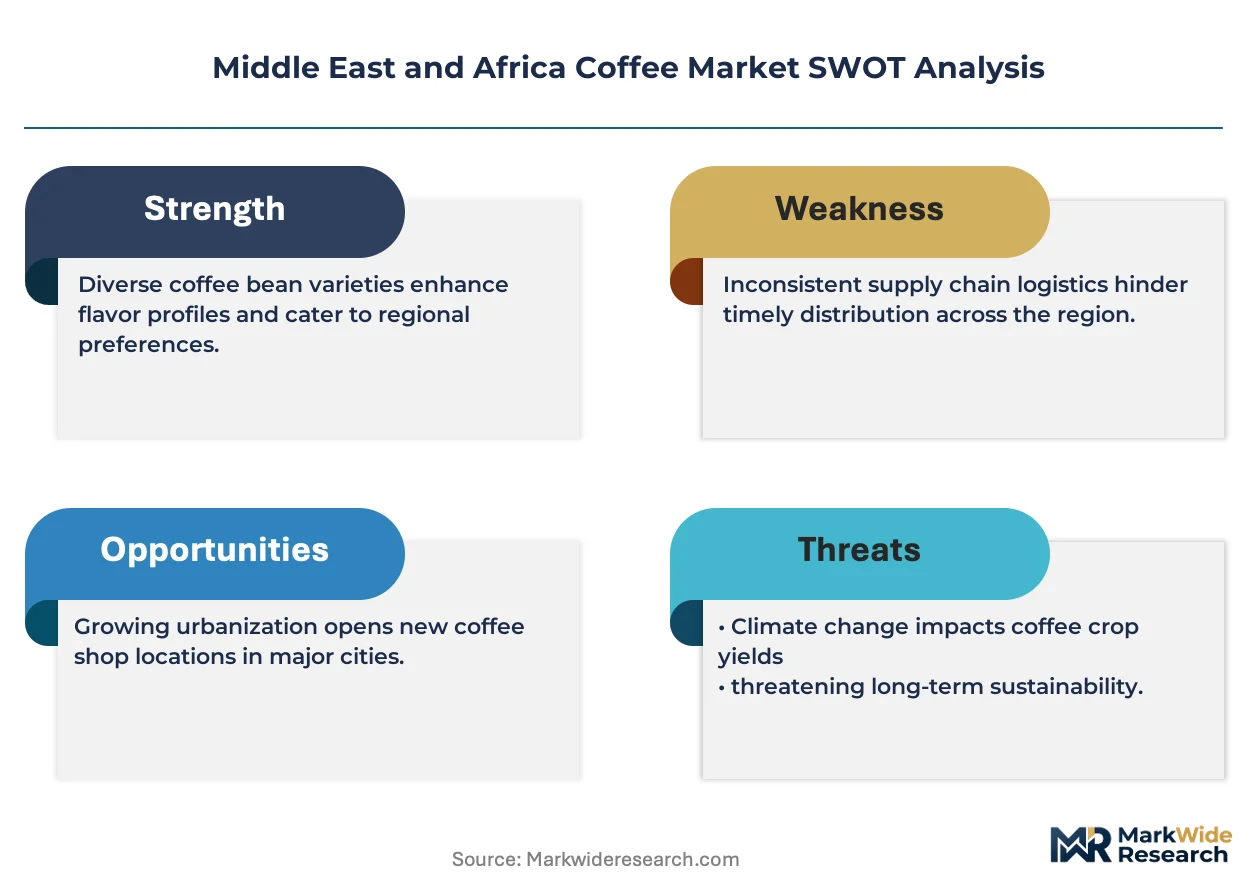
EU Deforestation Regulation due diligence requirements are forcing traceability infrastructure investments across East African supply chains, while Gulf café culture expansion pulls premium Arabica volumes northward through branded outlet networks.
Growth Catalysts
- SFDA Import Registration:Saudi Arabia's streamlined packaged coffee labeling protocols reduce entry friction for soluble and roasted formats, accelerating Gulf market penetration.
- Washing Station Infrastructure:Ethiopia's Coffee and Tea Authority-backed processing expansion upgrades export-grade sorting capabilities, tilting regional supply quality upward.
- Specialty Beverage Programs:Dubai and Riyadh hotel chains anchor demand through traceable origin cupping score procurement, pulling premium pricing tiers.
Market Restraints
- Green Bean Input Volatility:Weather-driven Arabica harvest fluctuations in Ethiopian highlands compress roasting margin stability for Gulf importers.
- Supply Concentration Risk:Washing station infrastructure clusters in Sidama and Yirgacheffe microclimates create geographic chokepoints for traceable premium lots.
- EU Green Deal Compliance:Deforestation-free documentation requirements impose traceability system costs that filter through to Middle Eastern buyer procurement budgets.
Strategic Opportunities
- E-Commerce Platform Partnerships:Saudi household penetration beyond traditional supermarket coverage represents underexploited retail channel expansion.
- Heritage Varietal Positioning:Yemen's high-altitude microclimate sourcing offers differentiation white space for traceable single-origin positioning in UAE specialty segments.
- Licensed Roasting Partnerships:Gulf sovereign wealth participation in East African farming concessions enables backward integration into origin control and long-term supply contracting.
Industry Challenges
- Cupping and Grading Talent Scarcity:Certified Q-grader availability lags behind washing station expansion rates in Ethiopia's quality-focused export zones.
- Legacy System Integration:Blockchain traceability platforms for EU Deforestation Regulation compliance must interface with established Ethiopian Coffee and Tea Authority licensing databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Coffee Market |
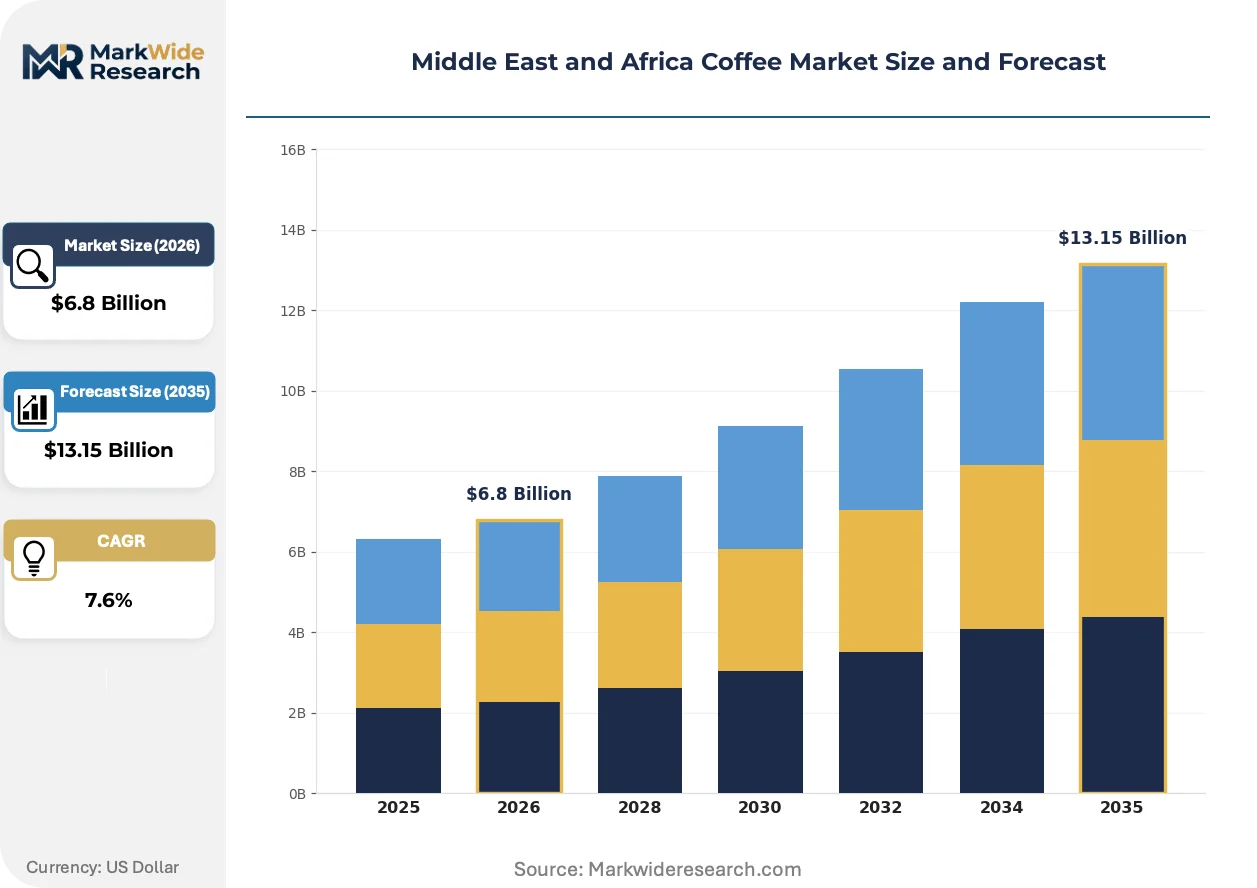
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Liberica, Excelsa Application: Food Service, Retail, Household, Instant Coffee End User: Cafes, Restaurants, Supermarkets, Online Retailers Distribution Channel: Direct Sales, Brokers, Wholesalers, E-commerce |
| Companies Covered | Luigi Lavazza S.p.A., Tchibo GmbH, Nestlé SA, RAW Coffee Company, Gruppo Illy S.p.A., JDE Peet’s N.V., Strauss Group Ltd, Al Mokha Yemen Coffee, Starbucks Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Coffee Market Shifts & Advancements
Processing technology and regulatory compliance infrastructure are converging to reshape how coffee moves from East African washing stations to Gulf café counters, with digitization and traceability as the dominant vectors.
Blockchain-enabled lot tracking systems are digitizing supply chain documentation for EU Deforestation Regulation compliance. Ethiopian exporters and Gulf importers are piloting platform integration at washing station origin points. The technology is compressing due diligence timelines while raising documentation standards for premium European and Middle Eastern buyers.
EU Green Deal due diligence requirements are mandating geolocation verification and deforestation-free attestations for all coffee entering European markets. African exporters face compliance cost restructuring that filters through to Middle Eastern procurement pricing. Specialty segments in Dubai and Riyadh are responding by accelerating direct trade relationships with certified washing stations.
Direct-to-consumer subscription models are displacing traditional retail packaged goods distribution in Saudi Arabia and the UAE. Specialty roasters are bypassing supermarket shelf space through platform partnerships reaching households in Jeddah, Riyadh, and Dubai. This channel rotation is most visible among urban professionals seeking traceable origin narratives and freshness-dated roasting.
Middle East and Africa Coffee Market Segmentation
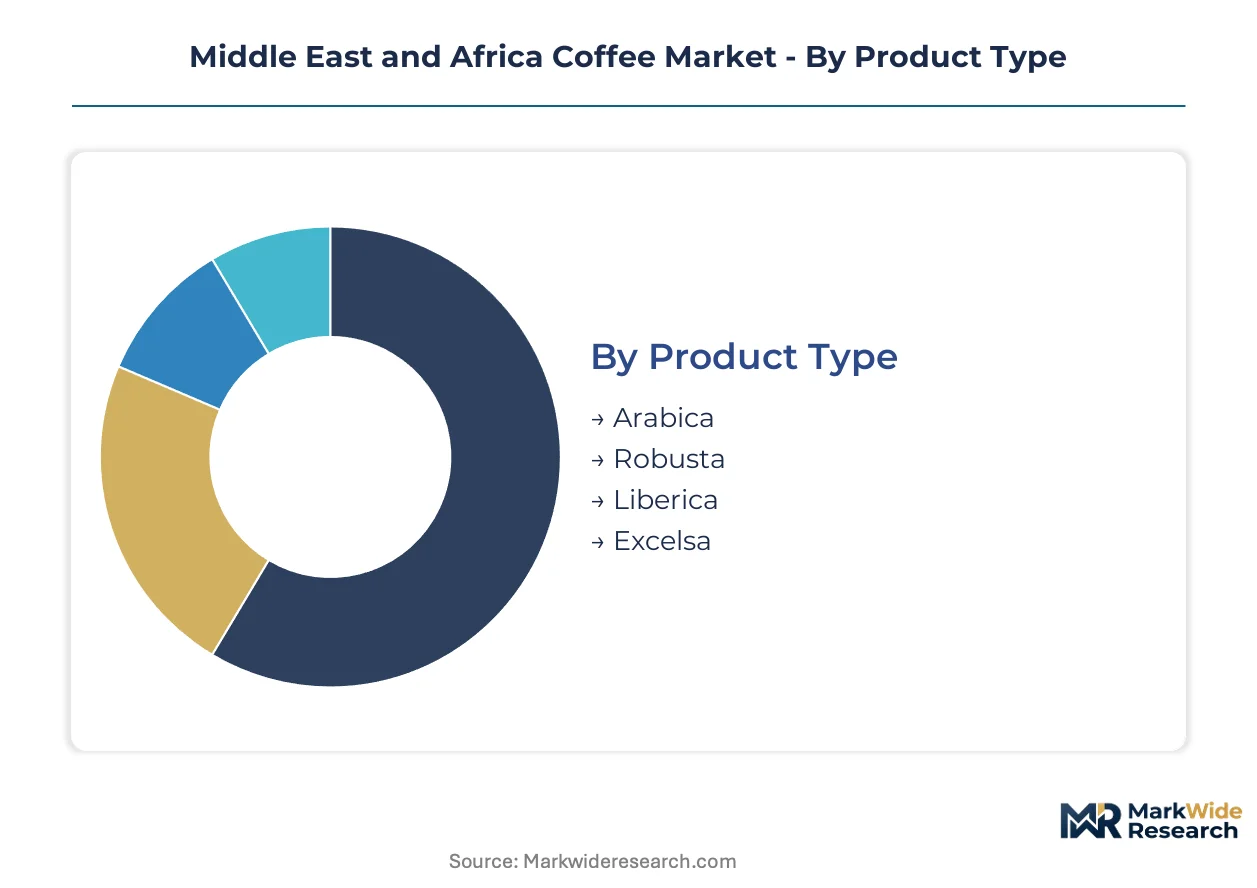
Segmentation in the Middle East and Africa Coffee Market reveals how divergent consumption patterns across Gulf café culture and East African export infrastructure create distinct commercial pathways. Product type and application splits expose where premium traceability investments concentrate versus where volume manufacturing scale dominates procurement decisions.
Product Type:
After-sales service intensity varies sharply across product types, with Arabica requiring cupping certification support and origin documentation that Robusta supply chains rarely replicate.
- Arabica:High-altitude cultivation in Ethiopian Sidama and Yirgacheffe microclimates delivers complex acidity profiles prized by Dubai and Riyadh specialty roasters. Jeddah's branded café chains anchor procurement for traceable single-origin lots with documented cupping scores above 85 points.
- Robusta:Higher caffeine content and disease resistance suit instant coffee manufacturing where Nestlé and JDE Peet's concentrate soluble production across East African facilities. Gulf supermarket private-label brands source Vietnamese and Ugandan Robusta for price-sensitive household segments.
- Liberica:Distinctive woody flavor profile from limited Philippine and West African cultivation occupies niche positioning in UAE specialty segments seeking differentiation.
- Excelsa:Tart, fruity notes from Southeast Asian origins support blend components for Riyadh roasters targeting experimental flavor profiles in third-wave café formats.
By volume, Robusta leads through instant coffee manufacturing scale. By growth pace, Arabica is ahead as Gulf café culture deepens origin traceability requirements.
Application:
Application segmentation tracks how value capture concentrates in food service channels where Dubai hotel chains command premium procurement terms versus retail formats competing on shelf turnover velocity.
- Food Service:Hotels and restaurant groups in Dubai and Riyadh anchor specialty coffee programs with direct trade relationships to Ethiopian washing stations, capturing margin through traceable origin narratives and in-house roasting capabilities.
- Retail:Packaged roasted coffee through Saudi supermarkets and UAE hypermarkets serves household brewing with brand loyalty built on consistency and regional taste profile calibration.
- Household:Green bean purchasing by home roasters in Jeddah and Riyadh represents an emerging segment bypassing commercial roasting entirely.
- Instant Coffee:Soluble manufacturing concentrated in East African Nestlé facilities supplies Gulf workplace and hospitality bulk brewing with cost efficiency overriding origin specificity.
Food service commands the highest per-kilogram pricing. Household green bean purchasing is expanding most quickly as roasting equipment penetration climbs in Saudi urban centers.
End User:
End user concentration shows how café chains in the Gulf Cooperation Council corridor pull supply chain investments toward licensed roasting partnerships and quality grading infrastructure.
- Cafes:Branded outlet expansion across Jeddah, Dubai, and Riyadh drives demand for consistent supply of traceable Arabica with documented processing method and altitude parameters.
- Restaurants:Hotel and independent dining establishments in the UAE prioritize batch consistency for espresso-based programs with medium-roast profiles calibrated to regional palate preferences.
- Supermarkets:Saudi Food and Drug Authority labeling compliance shapes packaged coffee shelf presence with Arabic-language origin disclosure and roast date requirements.
- Online Retailers:Platform partnerships in Saudi Arabia and the UAE enable subscription models displacing traditional retail through freshness-dated roasting and direct-to-door logistics.
Cafes dominate value capture through premium positioning. Online retailers are gaining share fastest as platform infrastructure matures across Gulf urban corridors.
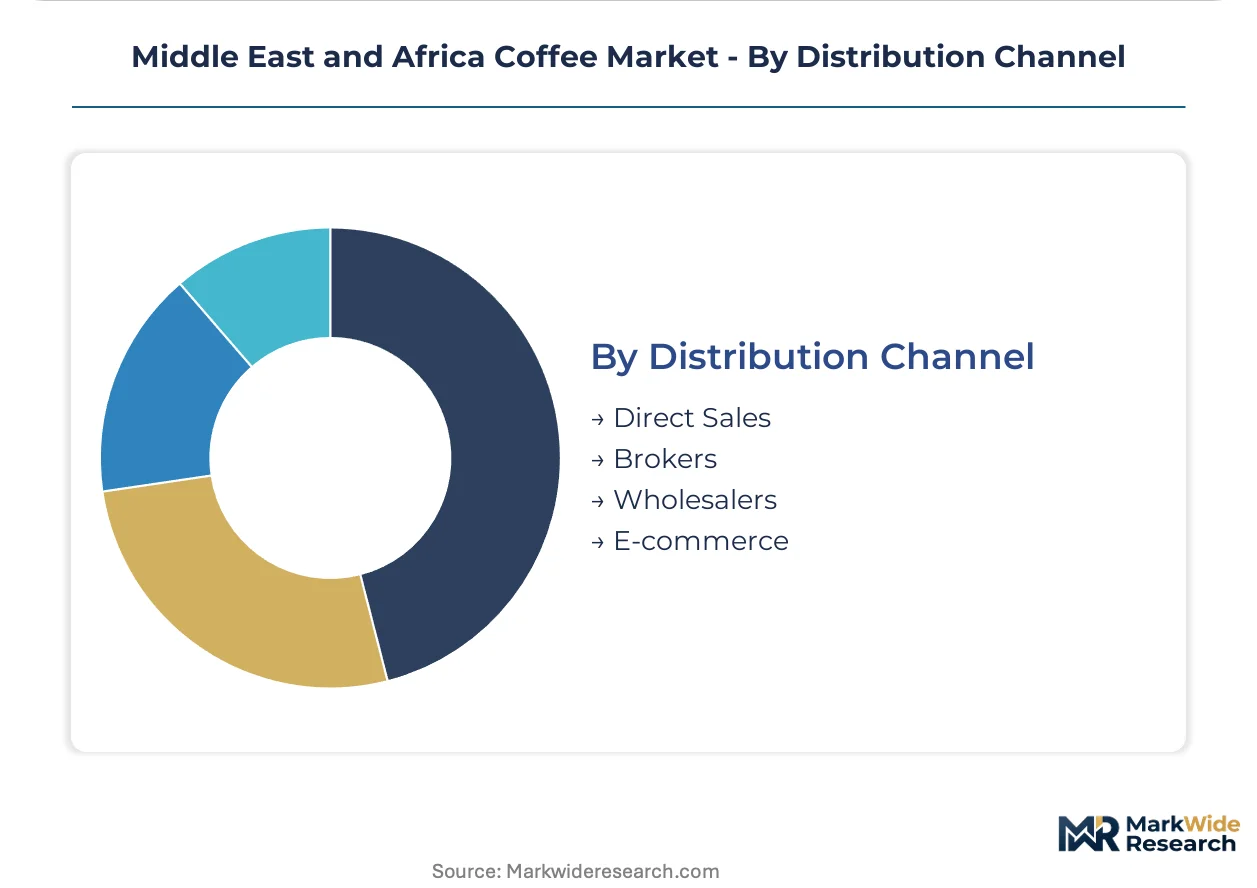
Distribution Channel:
Channel structure reflects the tension between established broker networks serving Ethiopian export licensing requirements and emerging digital platforms compressing intermediation layers.
- Direct Sales:Roasters and café chains in Dubai and Riyadh establish direct trade relationships with Ethiopian washing stations, bypassing traditional export brokers to secure lot traceability for EU Deforestation Regulation compliance.
- Brokers:Licensed Ethiopian Coffee and Tea Authority exporters aggregate smallholder production for Gulf importers lacking origin office infrastructure, capturing margin through quality grading and logistics coordination.
- Wholesalers:Regional distributors across Saudi Arabia and the UAE manage import clearance and temperature-controlled warehousing for supermarket and food service accounts.
- E-commerce:Platform-native roasters in Jeddah and Riyadh leverage social commerce and subscription algorithms to build direct household relationships outside traditional retail shelf competition.
Brokers still handle the largest volume flows. E-commerce is climbing the fastest as platform penetration deepens in Saudi secondary cities beyond Jeddah and Riyadh.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf states consume coffee as a premium café experience while East African nations supply raw beans through export-oriented processing infrastructure. This consumption-production split defines regional trade flows. Ethiopian washing stations and Saudi branded outlets operate on fundamentally different value-capture models.
Saudi Arabia
Branded café chains in Riyadh and Jeddah anchor Arabica procurement for traceable single-origin programs. The Saudi Food and Drug Authority governs import registration and Arabic-language labeling requirements. Riyadh's specialty roasting clusters are expanding licensed partnerships with Ethiopian washing stations for direct trade relationships.
United Arab Emirates
Dubai hotel chains and independent roasters drive demand for cupping-scored lots above 85 points. The Ministry of Industry and Advanced Technology administers product standards for roasted and soluble formats entering Gulf markets. Dubai's Jebel Ali logistics corridor concentrates temperature-controlled warehousing for regional redistribution.
Ethiopia
Smallholder production in Sidama and Yirgacheffe microclimates supplies premium traceable volumes to Middle Eastern buyers. The Coffee and Tea Authority regulates export licensing and quality grading standards. Addis Ababa's washing station infrastructure expansion is upgrading export-grade sorting capabilities for EU Deforestation Regulation compliance.
Israel
Café chain supply contracts in Tel Aviv and Jerusalem sustain medium-roast espresso program demand. The national food regulator oversees import standards for packaged roasted coffee. Tel Aviv's specialty roasting clusters are developing direct relationships with East African origins for traceability documentation.
Yemen
High-altitude microclimate sourcing from heritage varietals supports differentiation in UAE specialty segments. The national agricultural authority manages export documentation for traditional cultivation zones. Sana'a and Hodeidah processing clusters maintain natural drying methods for distinctive flavor profile preservation.
Middle East and Africa Coffee Market Competitive Landscape
Capability concentration sits with heritage-origin specialists; scale advantage sits with multinational soluble manufacturers. The market structures around three tiers: global beverage conglomerates with East African manufacturing footprints, Gulf-based licensed roasting partnerships, and single-origin micro-lot curators. Dominant competitive moves include backward integration into washing station equity stakes and e-commerce platform partnerships for direct-to-consumer subscription models.
Among Swiss- and Dutch-based beverage conglomerates, Nestlé SA and JDE Peet's N.V. represent the scale-driven manufacturing tier with soluble production concentration across East African facilities. Within the heritage-origin specialist tier, Al Mokha Yemen Coffee occupies a position exemplifying high-altitude microclimate differentiation for UAE specialty segments. Strauss Group Ltd anchors the regional supply contract tier through café chain relationships in Israel and selective North African markets.
| Leading Market Players |
|---|
| Luigi Lavazza S.p.A. |
| Tchibo GmbH |
| Nestlé SA |
| RAW Coffee Company |
| Gruppo Illy S.p.A. |
| JDE Peet's N.V. |
| Strauss Group Ltd |
| Al Mokha Yemen Coffee |
| Starbucks Corporation |
| Others |
Supply & Pricing Matrix
EU Deforestation Regulation compliance costs determine both the premium commanded by traceable Ethiopian lots and the shape of Gulf importer procurement networks. Roasters in Dubai and Riyadh absorb documentation overhead through direct washing station relationships, compressing margin spreads on non-certified volumes while widening tier differentials for deforestation-free attestations.
Pricing Analysis
Price spreads between Jeddah specialty cafés and Saudi supermarket shelves exceed threefold for comparable Ethiopian Sidama lots, reflecting origin documentation premiums. Three-tier pricing structure across specialty, commercial, and commodity levels segments buyers by cupping score threshold and traceability investment. Cost compression in instant coffee manufacturing intensifies as Nestlé and JDE Peet's scale East African soluble production. Supermarket private-label brands exhibit highest price sensitivity; Dubai hotel chains demonstrate lowest sensitivity due to program-level origin storytelling requirements.
Supply Chain Analysis
Tariff exposure between Ethiopia and Gulf Cooperation Council members remains minimal under preferential trade agreements, though EU Green Deal documentation requirements dominate supply chain risk assessment. Raw material flows concentrate in Ethiopian highlands for Arabica and Vietnamese central highlands for Robusta, with Ugandan volumes supplementing instant manufacturing. Green bean sourcing draws from smallholder washing station networks, roasted product distribution runs through Jebel Ali temperature-controlled warehousing, and e-commerce platforms displace traditional retail intermediation in Saudi secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern how Ethiopian washing stations connect with Gulf café chains, as subscription algorithms and blockchain traceability infrastructure restructure traditional broker intermediation. Interoperability between Ethiopian Coffee and Tea Authority licensing databases and EU compliance platforms determines which exporters capture premium positioning.
For Market Incumbents: Insulate margin position through backward integration into Sidama washing station equity stakes, securing lot traceability for EU Deforestation Regulation compliance before Q-grader talent scarcity intensifies. Licensed roasting partnerships in Riyadh and Dubai anchor volume commitments against direct-trade challengers. For New Entrants and Emerging Players: Establish a beachhead in Saudi e-commerce subscription channels, where platform-native roasters bypass supermarket shelf competition through freshness-dated direct delivery. Yemen heritage varietal sourcing offers differentiation white space in UAE specialty segments underserved by Ethiopian origin dominance. For Investors and Strategic Acquirers: EU Deforestation Regulation implementation reshapes the acquisition landscape toward traceability-integrated mid-tier exporters with existing geolocation verification infrastructure. Long-term viability favors targets with washing station equity in Yirgacheffe microclimates and established Gulf direct-trade relationships. Monitor blockchain platform adoption rates at Ethiopian origin points as inflection indicator for compliance cost pass-through capability.| Strategic Initiative | Industry Significance |
|---|---|
| Washing Station Equity Acquisition | Backward integration into Ethiopian Sidama processing secures traceable lot access for EU compliance. |
| Licensed Roasting Partnership | Gulf sovereign wealth participation enables origin control and long-term supply contracting with Ethiopian exporters. |
| Blockchain Traceability Deployment | Platform integration at washing station origin compresses due diligence timelines for premium buyers. |
| E-Commerce Subscription Launch | Direct-to-consumer algorithms in Saudi Arabia bypass traditional retail shelf competition entirely. |
| Heritage Varietal Sourcing Program | Yemen high-altitude microclimate differentiation captures UAE specialty segment pricing premiums. |
Research Methodology
A spread of perspectives from Ethiopian washing station operators, Gulf café chain procurement directors, Saudi Food and Drug Authority compliance officers, and EU import certification specialists converged on the working assumptions. Primary fieldwork combined structured interviews with licensed exporters in Addis Ababa and Dubai-based roasters with secondary validation through Ethiopian Coffee and Tea Authority export statistics, Saudi customs import records, and EU Deforestation Regulation guidance documents. Bottom-up volume modeling from washing station throughput data triangulated against top-down consumption estimates from Gulf hotel chain procurement disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling Arabica and Robusta splits alongside food service, retail, and instant application segments. Segmentation dimensions included product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derived from historical volume trajectories adjusted for washing station infrastructure expansion rates and Gulf café outlet growth pipelines. Forecast inputs incorporated EU compliance cost pass-through assumptions and platform e-commerce penetration curves in Saudi secondary cities.
Stress conditions across Ethiopian harvest volatility, Q-grader certification bottlenecks, and EU documentation timeline enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about washing station capacity expansion and Gulf sovereign wealth participation rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Oceania Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Raw Coffee Beans Market
Coffee
Coffee Grinder Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Europe Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Chewable Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Coffee Roaster Machine Market
Coffee
Coffee Decoction Maker Market
Coffee
Decaffeinated Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Take Out Coffee Market
Coffee
Middle East Coffee Market