
 South America Coffee Market | 2026-2036
South America Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
South America Coffee Market Outlook
Brazil is tilting toward mechanized harvesting across Minas Gerais and São Paulo states, expanding processing capacity for washed Arabica lots. JDE Peet's leverages its pan-regional roasting footprint to secure consistent supply from Brazilian cooperatives. Nestle S.A. anchors instant coffee demand through deep backward integration into Robusta sourcing in Espírito Santo. Sucafina S.A. competes on specialty-grade traceability, connecting Colombian micro-lots to European premium buyers.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora (Robusta), typically processed to moisture content below 12 percent and graded by screen size, defect count, and cupping score for beverage quality. The primary commercial purpose spans retail beverage preparation, foodservice extraction, and industrial soluble manufacturing. Arabica dominates value pools across specialty channels, while Natural processing methods sustain volume leadership in Brazilian commercial grades. Online Retail and Specialty Stores capture margin expansion as direct-to-consumer traceability platforms reshape price discovery.
Colombia's Federación Nacional de Cafeteros enforces minimum export standards that filter sub-par lots from international pipelines. Brazil's Ministry of Agriculture (MAPA) phytosanitary certifications and Peru's organic certification frameworks under SENASA shape market access rules for EU and North American buyers. Stakeholders must monitor how EU deforestation-free supply chain regulations redirect sourcing patterns toward traceable farm-gate systems.
Market Dynamics
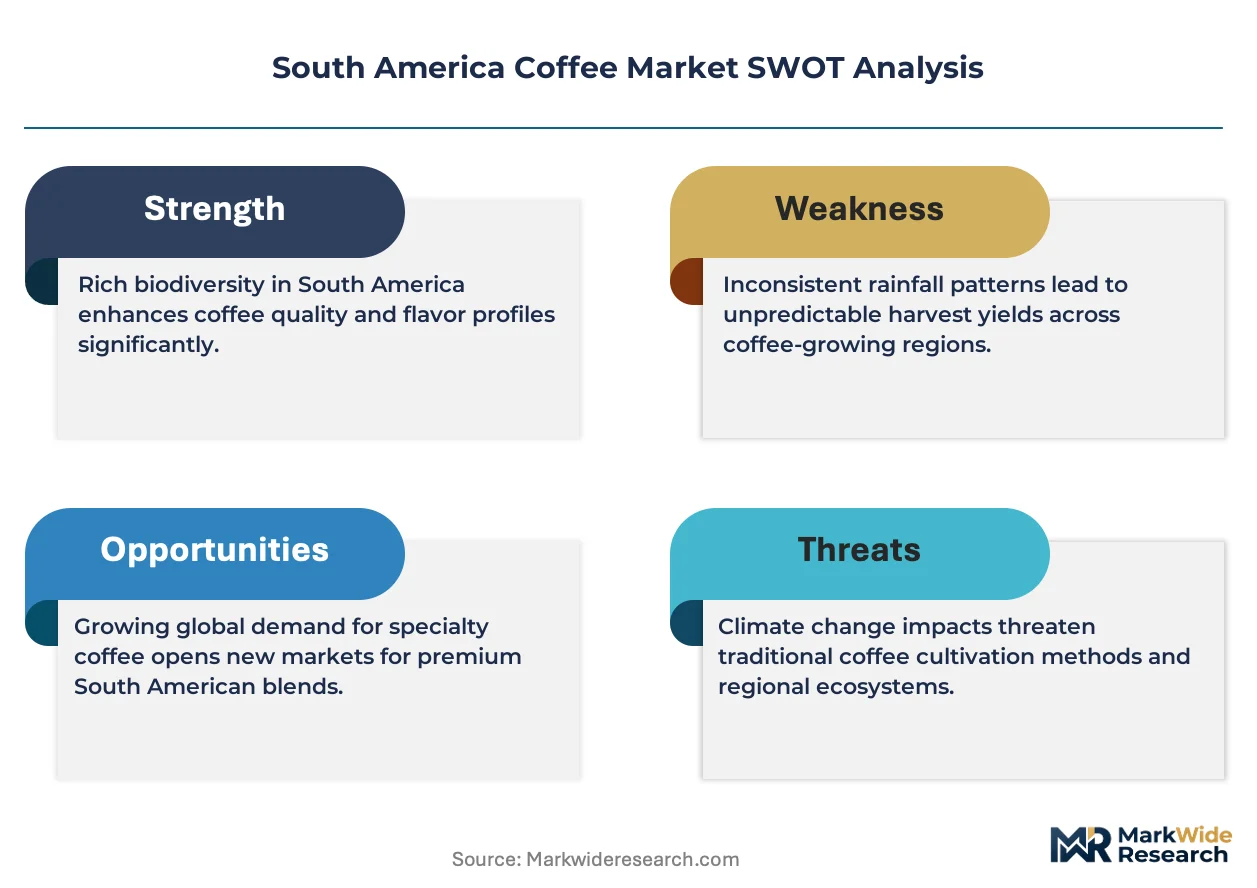
EU deforestation-free supply chain regulations are forcing South American exporters to rebuild traceability infrastructure from farm gate to port, compressing margins for non-compliant cooperatives while rewarding certified micro-lot aggregators.
Growth Catalysts
- Specialty cafe proliferation:Brazilian metropolitan markets sustain rising Arabica consumption through third-wave roasting culture and single-origin menu differentiation.
- MAPA phytosanitary certification:Brazil's Ministry of Agriculture enforces strict export protocols that filter sub-par lots and elevate national quality reputation among EU buyers.
- High-altitude terroir concentration:Colombian Nariño and Huila departments concentrate premium cupping scores that command specialty channel premiums.
Market Restraints
- Input cost volatility:Fertilizer and labor costs in Brazilian Cerrado fluctuate with currency movements, squeezing commercial-grade margins.
- Supply concentration risk:Minas Gerais state dominates Brazilian Arabica volume, creating regional climate exposure for global buyers.
- Regulatory friction:Peru's SENASA organic certification timelines extend export readiness by 8-14 months for new farm entrants.
Strategic Opportunities
- Ecuadorian highland expansion:Galapagos and Loja provinces offer underdeveloped Arabica acreage with emerging specialty recognition.
- Direct-to-consumer platforms:Online retail channels enable farm-gate pricing transparency and margin capture previously lost to intermediary exporters.
- EU Green Deal alignment:Deforestation-free compliance investments open preferential access to European premium buyers seeking verified provenance.
Industry Challenges
- Cupping talent scarcity:Qualified Q-graders remain concentrated in São Paulo and Bogotá, limiting quality control scaling in secondary growing regions.
- Wet mill capex intensity:Washed processing infrastructure demands capital deployment that outstrips cooperative financing capacity in Peru's northern highlands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Coffee Market |
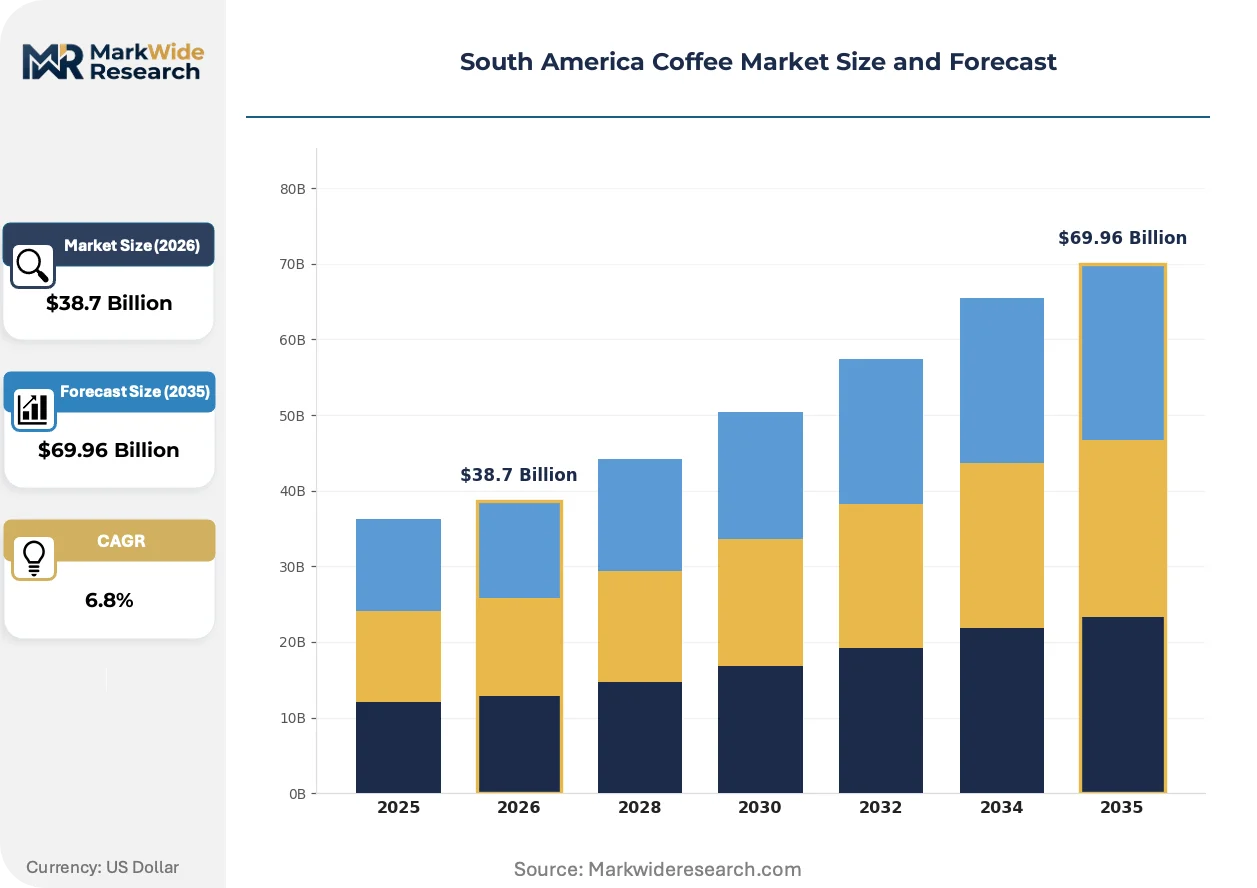
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Liberica, Excelsa Processing Method: Washed, Natural, Honey, Semi-Washed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafes End User: Households, Foodservice, Retailers, Exporters |
| Companies Covered | Starbucks Corporation, JDE Peet's, Nestle S.A., Cafes La Virginia S.A., Federación Nacional de Cafeteros de Colombia, Olam Food Ingredients, ECOM Agroindustrial Corp. Limited, Sucafina S.A., Cooperativa Agraria Cafetalera Cenfrocafe Peru, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Coffee Market Strategic Shifts
Processing technology and regulatory compliance requirements are compressing traditional supply chain layers, enabling farm-level actors to access premium buyers directly while bypassing legacy export intermediaries.
Mechanized selective harvesting is collapsing the labor cost advantage that previously sustained hand-picking across Brazilian commercial estates. Large São Paulo and Minas Gerais producers deploy optical sorting and GPS-guided harvesters to reduce per-kilogram collection costs. This automation compresses the price gap between estate lots and cooperative-sourced volumes, pressuring smallholder aggregation models.
EU deforestation-free supply chain regulations mandate geolocated farm mapping and third-party verification for all coffee entering European ports. Brazil's MAPA and Colombia's Federación Nacional de Cafeteros have aligned national traceability frameworks to pre-certify export lots. Specialty roasters in Germany and Italy now require block-chain verified provenance documentation as a procurement prerequisite.
Specialty buyers are consolidating direct relationships with Colombian micro-lot producers, displacing traditional exporter intermediaries. European premium roasters now contract harvests 6-12 months pre-collection through digital farm-gate platforms. This channel compression is most visible in Huila and Cauca departments, where cooperative membership is fragmenting into individual farm-brand arrangements.
South America Coffee Market Segmentation
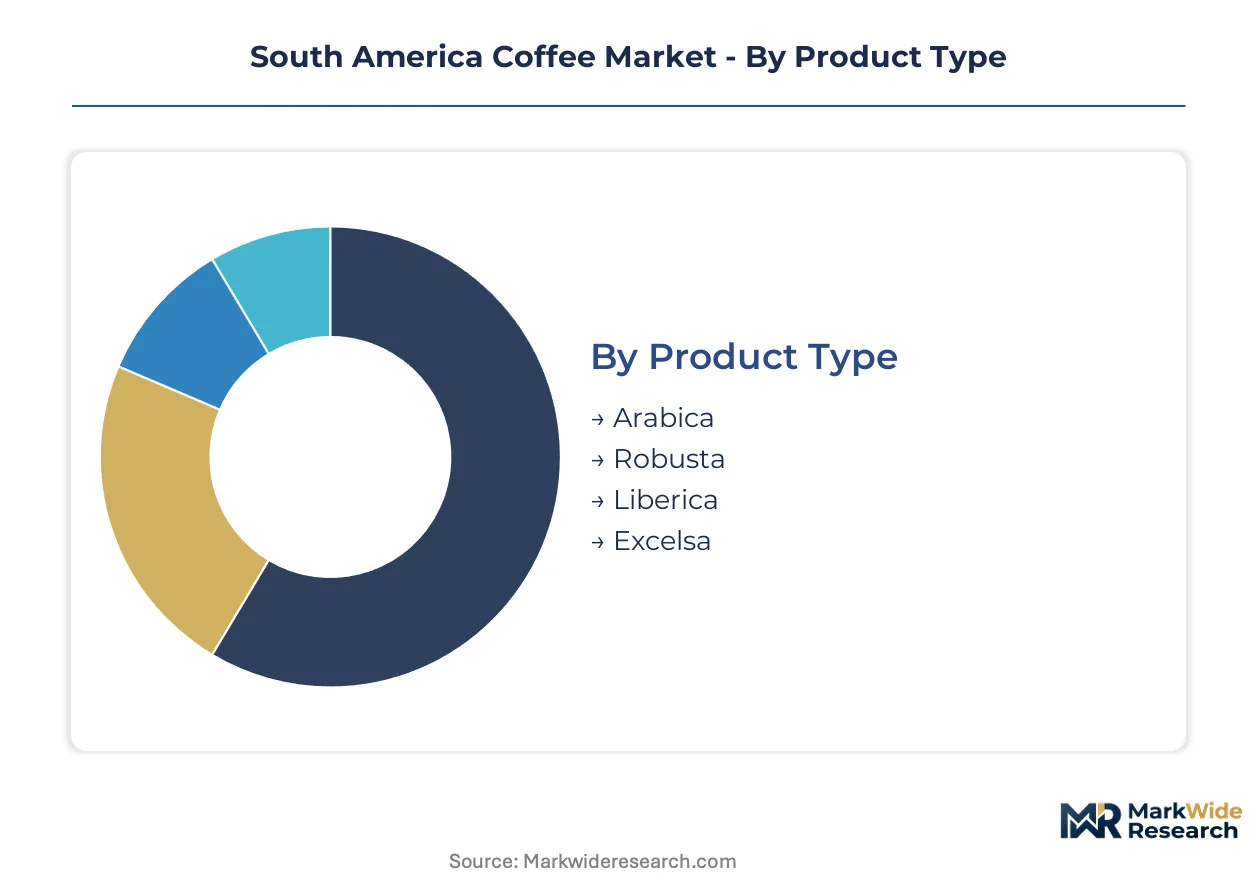
Segmentation in South America coffee markets reveals how processing technology, distribution infrastructure, and end-use requirements create distinct value pools. Understanding these divides enables stakeholders to align capital deployment with margin concentration zones across Brazilian estates and Colombian cooperatives.
Product Type:
Mature commercial grades dominate volume flows while emerging specialty varieties reshape premium positioning.
- Arabica:High-altitude Coffea arabica varieties grown above 1,200 meters in Minas Gerais and Huila deliver complex acidity profiles prized by specialty roasters. Brazilian washed Arabica from Cerrado commands premiums in German and Italian markets where MAPA phytosanitary certification opens port access.
- Robusta:Coffea canephora thrives in Espírito Santo's lower elevations, delivering higher caffeine content and crema stability for instant coffee manufacturing. Nestle S.A. maintains backward integration into Robusta estates here, securing captive supply for soluble processing plants.
- Liberica:Rare Coffea liberica specimens from isolated Amazonian plots attract niche collectors seeking genetic diversity outside mainstream commercial channels.
- Excelsa:Limited acreage in Ecuador's Loja province produces tart, fruity profiles for experimental roasting programs targeting third-wave cafe menus.
Arabica handles the majority of throughput; Excelsa is gaining share fastest among specialty buyers seeking menu differentiation.
Processing Method:
Cost tier stratification separates capital-intensive washed infrastructure from low-touch natural drying operations.
- Washed:Fermentation tanks and mechanical demucilaging equipment in Colombian cooperatives produce clean, consistent cupping scores required by European premium buyers. Federación Nacional de Cafeteros standards mandate defect thresholds that filter sub-par lots from export pipelines.
- Natural:Whole-cherry sun-drying on Brazilian commercial estates minimizes water consumption and labor inputs, sustaining volume leadership in commodity-grade exports despite weather-dependent quality variance.
- Honey:Partial mucilage retention in Costa Rican-influenced Peruvian operations creates sweetness-forward profiles for direct-to-consumer micro-lot platforms.
- Semi-Washed:Hybrid mechanical processing in São Paulo's mechanized estates bridges quality consistency with throughput economics for mid-tier roasters.
Natural processing handles the majority of throughput; Honey methods are expanding most quickly among specialty aggregators seeking flavor differentiation.
Distribution Channel:
Customer type determines margin capture, with direct-to-consumer platforms displacing legacy intermediary layers.
- Online Retail:Farm-gate digital platforms enable Brazilian cooperatives to bypass traditional exporters, capturing price premiums through blockchain-verified provenance documentation demanded by EU deforestation-free compliance.
- Supermarkets:Volume consolidation through São Paulo and Bogotá retail chains sustains commercial-grade Robusta flows for household soluble consumption.
- Specialty Stores:Curated single-origin selections in Rio de Janeiro and Medellín neighborhoods serve third-wave roasting culture with micro-lot traceability.
- Cafes:Metropolitan Brazilian specialty cafes drive rising Arabica consumption through single-origin menu differentiation and in-house roasting visibility.
Supermarkets handle the majority of throughput; Online Retail channels are climbing the fastest as traceability infrastructure matures.
End User:
Application requirements split procurement between commodity-scale extraction and provenance-verified specialty roasting.
- Households:Brazilian and Colombian domestic markets consume soluble and roast-and-ground formats through supermarket channels, with instant coffee anchoring volume in lower-income segments.
- Foodservice:Cafe chains across São Paulo and Buenos Aires require consistent supply contracts for espresso blends, prioritizing volume reliability over single-origin traceability.
- Retailers:European supermarket private-label programs source certified commercial grades through established export houses with pre-cleared EU deforestation documentation.
- Exporters:Licensed Colombian and Brazilian export aggregators manage phytosanitary certification, logistics, and customs clearance for international buyers lacking direct farm relationships.
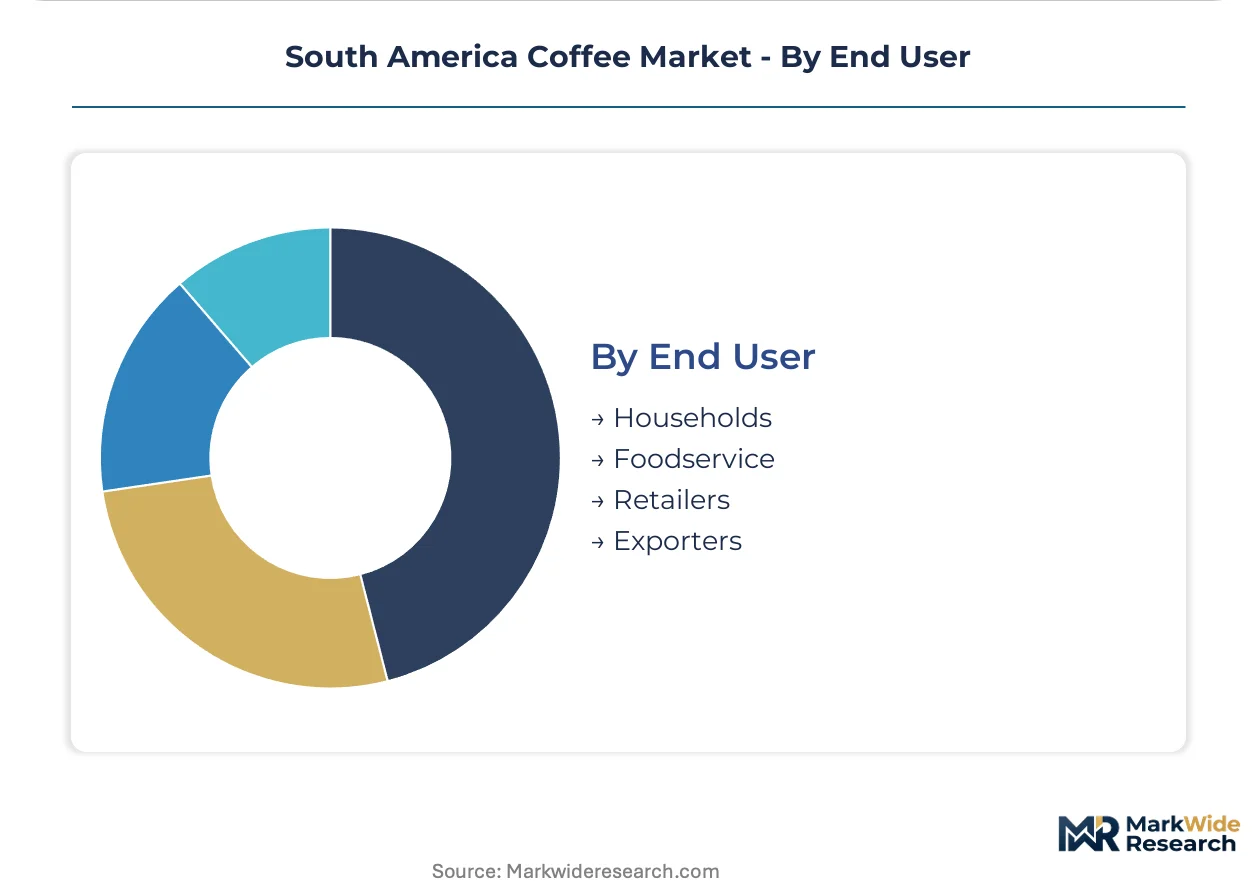
Households handle the majority of throughput; Foodservice is expanding most quickly as Brazilian cafe culture proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Ministry of Agriculture (MAPA) anchors regional trade governance through phytosanitary certification mandates that filter export lots and elevate national quality reputation among EU buyers. The report examines production concentration across five South American territories where regulatory frameworks and terroir advantages create distinct competitive positioning.
Brazil
Specialty cafe proliferation in São Paulo and Rio de Janeiro sustains rising Arabica consumption through third-wave roasting culture. MAPA enforces strict export protocols that reshape compliance costs for cooperatives seeking EU market access. Mechanized harvesting expands across Minas Gerais estates, collapsing labor cost advantages that previously sustained hand-picking.
Colombia
High-altitude terroir in Nariño and Huila departments concentrates premium cupping scores that command specialty channel premiums. The Federación Nacional de Cafeteros enforces minimum export standards that filter sub-par lots from international pipelines. Medellín specialty stores serve single-origin traceability demands from European premium roasters contracting harvests pre-collection.
Peru
Organic certification frameworks under SENASA shape market access rules for North American buyers seeking verified provenance. Northern highland cooperatives face wet mill capex intensity that outstrips financing capacity for washed processing infrastructure. Direct-to-consumer platforms enable farm-gate pricing transparency previously lost to intermediary exporters.
Ecuador
Galapagos and Loja provinces offer underdeveloped Arabica acreage with emerging specialty recognition among experimental roasting programs. The country's national agricultural regulator enforces traceability documentation aligned with EU deforestation-free supply chain regulations. Quito-based aggregators connect micro-lot producers to blockchain-verified provenance systems.
Argentina
Foodservice channels across Buenos Aires require consistent supply contracts for espresso blends prioritizing volume reliability. The national phytosanitary authority maintains certification reciprocity with Brazilian MAPA standards to facilitate cross-border bean flows. Domestic roasting clusters concentrate in Córdoba province for distribution to cafe chains.
South America Coffee Market Competitive Environment
Vertically integrated multinationals and cooperative aggregators split the market between captive supply security and farm-gate traceability. Nestle S.A. anchors instant coffee demand through backward integration into Robusta sourcing, while Sucafina S.A. competes on specialty-grade traceability connecting micro-lots to European buyers. Strategic differentiation concentrates on EU deforestation-free compliance investments and direct-to-consumer platform development.
Within the multinational tier, Nestle S.A., JDE Peet's, and Starbucks Corporation occupy positions exemplifying divergent sourcing archetypes. Nestle S.A. represents captive supply integration, JDE Peet's exemplifies pan-regional roasting footprint leverage, and Starbucks Corporation anchors specialty cafe channel proliferation. Cooperative aggregators including Federación Nacional de Cafeteros de Colombia and Sucafina S.A. sit within the traceability-verified tier, connecting farm-gate systems to premium buyer procurement prerequisites.
| Leading Market Players |
|---|
| Starbucks Corporation |
| JDE Peet's |
| Nestle S.A. |
| Cafes La Virginia S.A. |
| Federación Nacional de Cafeteros de Colombia |
| Olam Food Ingredients |
| ECOM Agroindustrial Corp. Limited |
| Sucafina S.A. |
| Cooperativa Agraria Cafetalera Cenfrocafe Peru |
| Others |
Value Chain & Pricing Dynamics
Minas Gerais estate concentration anchors upstream supply, channeling margin capture toward MAPA-certified exporters and blockchain-verified micro-lot aggregators while squeezing non-compliant cooperative intermediaries. Brazilian washed Arabica premiums in German and Italian markets reflect this geographic supply lock-in, with price differentiation widening between certified and conventional lots.
Pricing Analysis
Colombian Huila and Nariño micro-lots command substantial premiums over Brazilian commercial grades in European specialty channels. Three-tier pricing structure across specialty certified, standard commercial, and economy soluble levels segments buyer access. Pricing pressure stems from wet mill capex demands in Peru's northern highlands that outstrip cooperative financing capacity. Household soluble consumers exhibit highest price sensitivity, while German premium roasters show lowest sensitivity given EU deforestation compliance requirements.
Supply Chain Analysis
Extended payment terms from São Paulo and Bogotá export houses strain working capital for Peruvian and Ecuadorian farm-gate aggregators seeking washed processing infrastructure. Supply concentrates in Brazil, Colombia, and Peru, with raw material dependencies on fertilizer imports, fermentation equipment, and demucilaging machinery. Single-source vulnerability runs through Minas Gerais climate exposure for global Arabica buyers. Distribution runs through licensed export aggregators managing MAPA and Federación Nacional de Cafeteros certification for EU port clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU deforestation-free regulations fragment procurement relationships, creating white-space opportunities for traceability-verified aggregators and direct-to-consumer platforms that bypass legacy export intermediaries.
For Market Incumbents: Insulate specialty market position by deepening backward integration into Colombian micro-lot pre-collection contracting and accelerating MAPA certification coverage across cooperative networks. Defend against channel compression by deploying proprietary blockchain provenance systems that match European buyer compliance requirements. For New Entrants and Emerging Players: Ecuadorian highland acreage in Galapagos and Loja provinces offers the most penetrable specialty segment given minimal incumbent traceability infrastructure. Target direct-to-consumer digital platforms as the primary go-to-market angle, leveraging SENASA-aligned documentation to preempt EU regulatory barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian estate operators lacking EU compliance infrastructure. Five-to-ten year viability hinges on deforestation-free certification deployment speed. Watch for MAPA pre-certification completion rates as the inflection signal distinguishing premium-access assets from stranded volume.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | EU Green Deal compliance opens preferential German and Italian buyer access for verified Colombian micro-lots. |
| Mechanized Harvesting Scale-Up | Minas Gerais optical sorting and GPS-guided equipment collapses labor cost gaps between estates and cooperatives. |
| Direct-to-Consumer Platform Launch | Farm-gate digital channels enable Brazilian cooperatives to capture margins previously lost to export intermediaries. |
| Wet Mill Infrastructure Expansion | Peruvian northern highland cooperatives require fermentation tank financing to meet washed Arabica export standards. |
| Pre-Collection Contracting Programs | Huila and Cauca harvest contracting six-to-twelve months ahead displaces traditional exporter relationships. |
Study Parameters
Desk research of customs trade databases, Federación Nacional de Cafeteros export statistics, and MAPA phytosanitary filings preceded structured interviews with cooperative export managers, Q-grader certification bodies, European specialty roaster procurement leads, and SENASA organic certification officers. Bottom-up volume modeling across Brazilian estates and Colombian cooperatives triangulated against top-down trade flow analysis.
Assumptions held MAPA certification timelines and EU deforestation-free implementation schedules fixed while varying fertilizer cost trajectories and currency fluctuation scenarios across the projection horizon. Segmentation dimensions included processing method, distribution channel, and altitude-based terroir classification. CAGRs derived from historical trade volume trends and forward buyer contract coverage ratios.
Practitioners should monitor EU port enforcement consistency and MAPA audit frequency for early signals of compliance cost escalation. Forecasts reflect these documented assumptions; regulatory implementation delays or climate shocks in Minas Gerais would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Europe Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Chewable Coffee Market
Coffee
Coffee Bottle Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
US Instant Coffee Market
Coffee
High Protein Coffee Market
Coffee
Coffee and Tea Capsule Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Crystal Market
Coffee
Coffee Bags Market
Coffee
Coffee Capsules Market
Coffee
Caffeine Market
Coffee
Coffee Pods and Capsules Market