
 RTD Coffee Market | 2026-2036
RTD Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Coffee Market Outlook
The RTD coffee category is rebalancing as premium cold brew and nitro formats split from commodity-priced mainstream offerings in both positioning and margin structure. Nestlé S.A. leverages its Nescafé manufacturing scale and deep retail distribution to anchor volume across European and Latin American markets. Starbucks Corporation differentiates through licensed café-channel exclusivity and seasonal flavor innovation that sustains brand premiumization. PepsiCo Inc. competes aggressively in convenience-store cold cases with value-tier pricing and broad SKU proliferation.
Ready-to-drink coffee comprises brewed coffee formulations that are packaged, preserved through hot-fill or aseptic processing, and shelf-stabilized for ambient or refrigerated distribution, typically containing 75–200 mg caffeine per serving and adjusted to pH 4.6–5.2 for microbial stability. Its primary commercial purpose is to deliver portable, consistent caffeine delivery without equipment dependency for consumers in transit or workplace settings. Caffeinated variants dominate absolute volume, though organic sub-segments command disproportionate shelf-space allocation in premium retail channels. Cans lead packaging format share due to aluminum recyclability and chill-speed advantages, while tetra packs retain cost-driven penetration in emerging markets.
The FDA governs caffeine content labeling and GRAS status for coffee-derived ingredients in the United States, while the EU Green Deal and F-Gas Regulation pressure refrigerant choices across European cold-chain distribution. Japan's Food Labeling Act and METI energy-efficiency standards shape both ingredient disclosure and vending-machine deployment patterns. Stakeholders must monitor how diverging packaging-recovery mandates and caffeine-limit proposals across these jurisdictions reshape formulation and logistics investment priorities.
Market Dynamics
Cold brew processing technology and nitrogen infusion methods are splitting the RTD coffee category into premium-margin and commodity-volume tiers, forcing manufacturers to choose between equipment-intensive craft positioning and scale-driven mainstream distribution.
Growth Catalysts
- Office worker demand:Workplace caffeine consumption patterns favor grab-and-go formats that eliminate brewing equipment and cleanup time. Employers in Japan and South Korea increasingly stock cold-case RTD options as amenity investments.
- F-Gas Regulation compliance:European cold-chain operators are retrofitting refrigeration systems to meet EU Green Deal mandates, expanding addressable market for ambient-stable aseptic formulations that bypass refrigerated logistics entirely.
- Aluminum recyclability:Can packaging formats gain shelf-space preference as retailers respond to extended producer responsibility frameworks in multiple jurisdictions, compressing tetra pack share in premium channels.
Market Restraints
- Arabica price volatility:Input cost swings for high-altitude coffee beans compress margin predictability for cold brew specialists dependent on origin-specific sourcing contracts.
- Refrigerated distribution concentration:Cold-chain infrastructure ownership clusters among third-party logistics providers in the United States and Japan, creating bottleneck risk for nitro-infused products requiring pressurized cold storage.
- Caffeine limit proposals:Pending regulatory scrutiny of high-caffeine formulations in multiple jurisdictions threatens portfolio composition for brands anchored to 150-200 mg serving strengths.
Strategic Opportunities
- South Korea vending expansion:METI-aligned energy-efficiency standards in Japan create technology transfer potential for automated retail formats that chill individual cans on demand rather than maintaining full cold cases.
- Organic certification tailwinds:USDA Organic and EU Organic label penetration remains underdeveloped in Latin American retail channels relative to North American premium grocers.
- Aseptic-nitro convergence:Combining ambient-stable processing with dissolved nitrogen retention technology opens direct-to-consumer subscription channels that bypass traditional cold-chain dependencies.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise for stable cold brew flavor profiles without thermal degradation commands premium compensation, constraining R&D throughput for mid-tier manufacturers.
- Pressurized can filling capex:Nitrogen infusion lines require specialized sealing equipment that extends payback periods versus standard hot-fill installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Coffee Market |
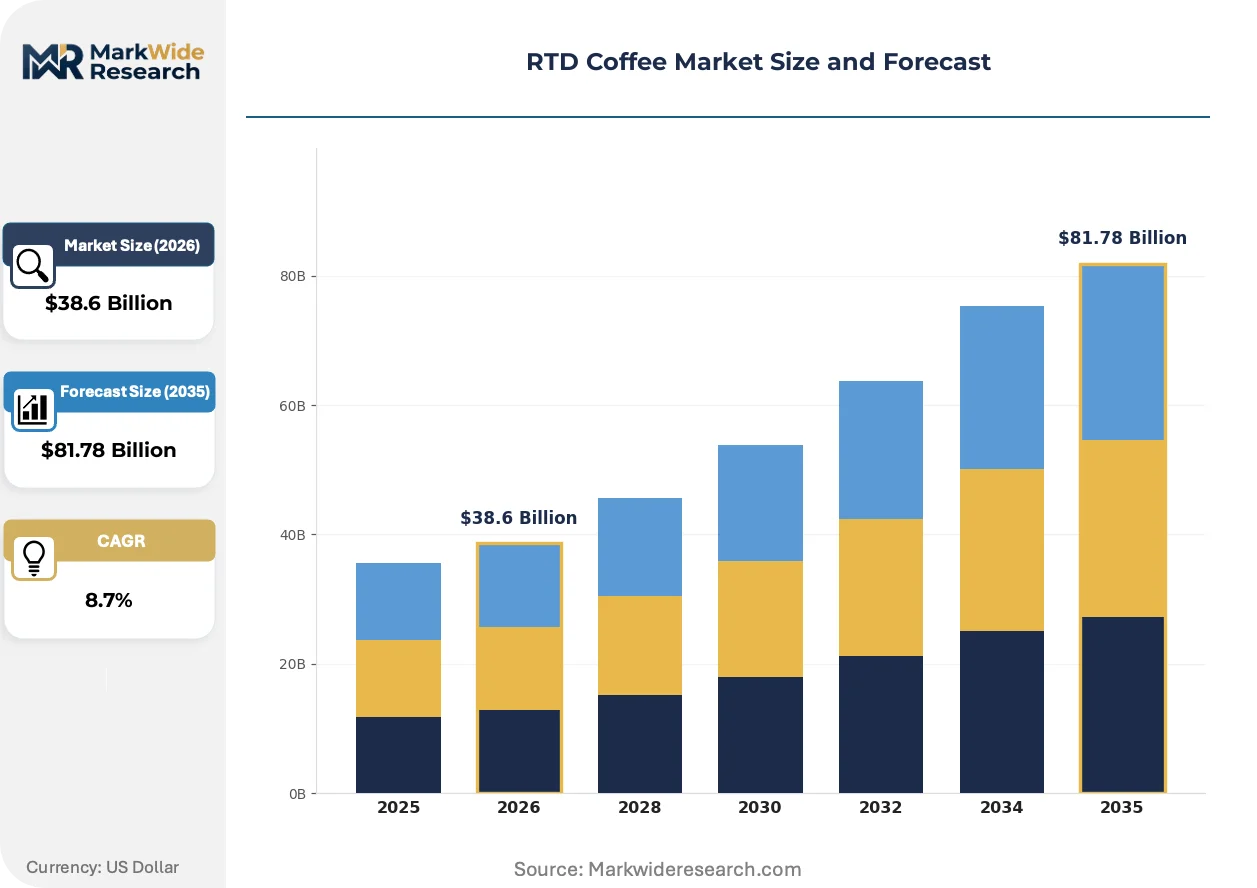
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Decaffeinated, Flavored, Organic Packaging Type: Cans, Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés End User: Students, Office Workers, Fitness Enthusiasts, Busy Professionals |
| Companies Covered | Danone S.A., Keurig Dr Pepper Inc., PepsiCo Inc., Suntory Beverage & Food Limited, Asahi Group Holdings Ltd., The Coca-Cola Company, McDonald's Corporation, Nestlé S.A., Starbucks Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Coffee Market Strategic Shifts
Processing technology divergence is fragmenting manufacturing investment strategies, with cold brew extraction and nitrogen dissolution systems requiring fundamentally different capital allocations than conventional hot-brew aseptic lines.
Cold brew extraction systems using extended steeping at ambient temperatures are overtaking traditional hot-brew methods for premium SKU development. Specialty café chains and direct-to-consumer brands are adopting these systems to deliver lower-acidity flavor profiles that justify price premiums. The technology is overtaking hot-fill infrastructure in new facility planning decisions, compressing demand for conventional thermal processing equipment.
The EU F-Gas Regulation is accelerating refrigerant phase-outs across European cold-chain networks, raising operating costs for refrigerated RTD distribution. Manufacturers are responding with reformulated ambient-stable products that maintain sensory quality without temperature-controlled logistics. Premium European retailers are reallocating shelf space toward aseptic cold brew formats that bypass refrigeration requirements entirely.
Subscription-based replenishment models are displacing impulse convenience-store purchases among high-frequency office workers in the United States. Direct-to-consumer platforms offer scheduled delivery of multi-can assortments with flavor rotation options. This pattern concentrates most visibly in coastal metropolitan markets where delivery density supports unit-economics viability.
RTD Coffee Market Segmentation
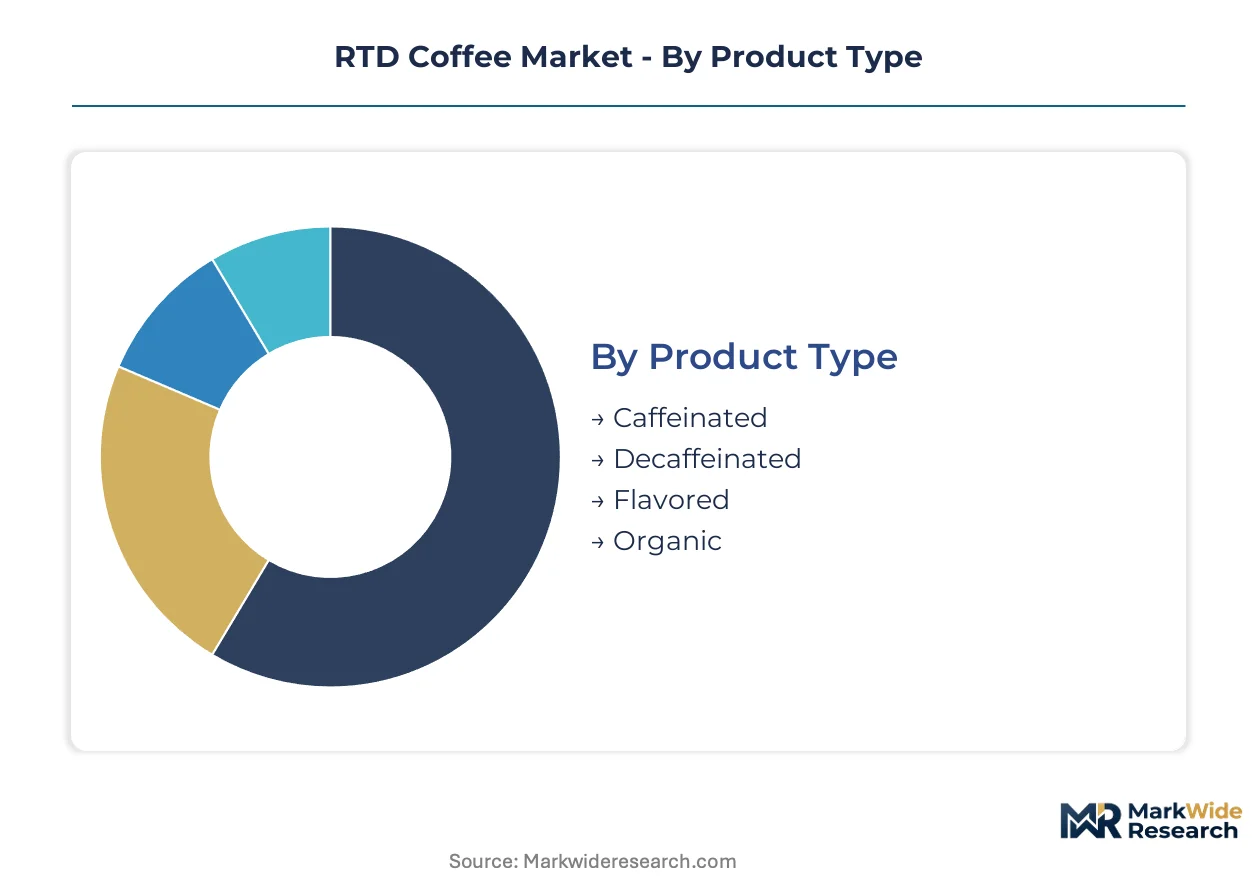
RTD coffee manufacturers configure production lines around specific consumption occasions and channel requirements. Segmentation decisions determine whether facilities invest in cold-chain infrastructure or ambient-stable processing, with direct implications for margin structure and geographic reach.
Product Type:
Consumer upgrade patterns from commodity instant coffee toward premium RTD formats reshape formulation priorities across manufacturing networks.
- Caffeinated:Standard formulations deliver 75–200 mg caffeine per serving through hot-fill or aseptic processing, with pH adjusted to 4.6–5.2 for microbial stability. Office workers in Japan and South Korea drive placement density in workplace cold cases and vending machines.
- Decaffeinated:Methylene chloride or Swiss water process removal reduces caffeine below 2.5% of original bean content, requiring additional labeling disclosure under FDA and Japan Food Labeling Act requirements. Demand clusters among evening consumption occasions and caffeine-sensitive demographics in premium urban retail channels.
- Flavored:Vanilla, mocha, and caramel variants use natural or artificial flavor systems with added sweeteners to mask cold brew bitterness.
- Organic:USDA Organic or EU Organic certification mandates 95% organic ingredient content and restricts synthetic pesticide residues in sourced arabica beans.
Volume placements concentrate in Caffeinated; the faster expansion belongs to Organic.
Packaging Type:
Cost tier differentiation separates premium positioning from mass-market penetration, with material choice signaling quality perception and determining cold-chain dependencies.
- Cans:Aluminum formats offer rapid chill-speed and high recyclability under extended producer responsibility frameworks, commanding preference in convenience stores and premium grocers. PepsiCo and Nestlé S.A. deploy can-dominant SKUs across North American and European refrigerated cold cases.
- Bottles:PET or glass containers support resealability for multi-serve consumption and enable transparent product visibility. Fitness enthusiasts favor bottle formats for gym bag portability and gradual consumption across extended workouts.
- Tetra Packs:Aseptic carton systems enable ambient distribution without refrigeration, reducing logistics cost in emerging markets with underdeveloped cold-chain infrastructure.
- Pouches:Flexible film formats minimize material weight and shipping cube, targeting direct-to-consumer subscription channels and on-the-go consumption.
Retail shelf space favors Cans; Tetra Packs are climbing the fastest in cost-sensitive distribution.
Distribution Channel:
Application-specific channel strategies align product temperature requirements with existing infrastructure investments and shopper mission types.
- Supermarkets:Full-category assortment including premium cold brew and nitro variants alongside value-tier mainstream offerings, with placement in both ambient aisles and refrigerated dairy cases. United States and South Korean hypermarket chains allocate expanding linear footage to RTD coffee as basket-building traffic drivers.
- Convenience Stores:Grab-and-go mission dominance favors single-serve cans in refrigerated open-air coolers, with placement optimized for commuter traffic patterns.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and flavor assortment rotation, bypassing traditional retail slotting fees.
- Cafés:Licensed and owned-channel exclusivity supports brand premiumization through controlled environment presentation and cross-sell with food items.
Transaction velocity peaks at Convenience Stores; Online Retail shows the steepest expansion trajectory.
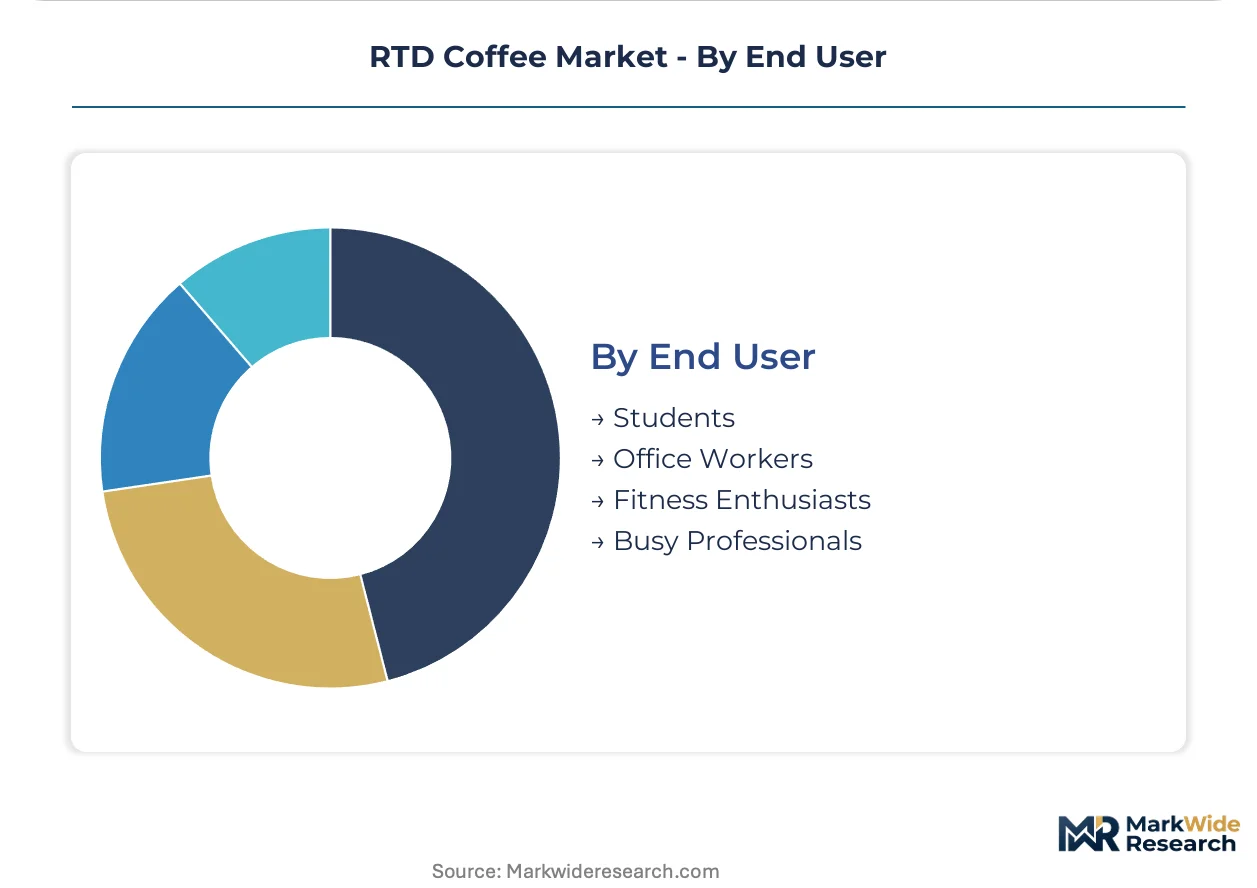
End User:
Customer type segmentation maps caffeine timing preferences against workplace structure, fitness routines, and mobility patterns.
- Office Workers:Workplace consumption patterns favor ambient or refrigerated grab-and-go formats that eliminate equipment dependency and cleanup time. Employers in Japan and South Korea increasingly stock RTD options as amenity investments to support productivity and retention.
- Busy Professionals:Erratic schedules and transit-heavy routines prioritize portability and rapid caffeine delivery without preparation friction.
- Students:Price sensitivity and late-night study schedules drive demand for value-tier caffeinated formats in campus retail and vending locations.
- Fitness Enthusiasts:Pre-workout and recovery positioning emphasizes functional ingredients, protein fortification, and sugar reduction to align with nutritional goals.
Absolute volume sits with Office Workers; Fitness Enthusiasts are gaining share fastest as functional positioning expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the highest RTD coffee vending-machine density worldwide, with metropolitan convenience chains deploying chilled units across office districts and transit corridors. This infrastructure concentration shapes formulation standards and packaging formats that diffuse into adjacent markets.
United States
Office-worker consumption in Manhattan and San Francisco drives subscription-model adoption for direct-to-consumer cold brew delivery. FDA caffeine-labeling requirements govern formulation disclosure for products exceeding 200 mg per serving. Seattle hosts Starbucks Corporation's product development operations, where licensed café-channel exclusivity reinforces brand premiumization strategies.
Japan
Corporate amenity investments by employers in Osaka and Tokyo expand workplace cold-case RTD stocking as retention tools. METI energy-efficiency standards reshape vending-machine deployment toward on-demand chilling rather than continuous refrigeration. Nagoya manufacturing clusters supply canning infrastructure adapted to nitrogen-infusion sealing requirements.
South Korea
Seoul Capital Area density supports automated retail expansion with technology transfer potential from Japanese METI-aligned systems. The country's Food Labeling Act mandates ingredient disclosure that exceeds baseline international standards. Busan-Ulsan port logistics handle imported arabica bean flows for domestic cold brew processing facilities.
Germany
Munich and Hamburg retail channels reallocate shelf space toward aseptic cold brew formats that bypass EU F-Gas Regulation refrigeration mandates. The EU Green Deal pressures cold-chain operators toward refrigerant retrofits that raise ambient-stable product competitiveness. Bavarian packaging equipment manufacturers supply nitrogen-dissolution systems for premium SKU development.
Brazil
São Paulo and Minas Gerais concentrate arabica sourcing contracts that feed cold brew specialist margin volatility. ANVISA governs caffeine-content thresholds and preservative approvals for export-oriented formulations. Campinas industrial corridors host tetra-pack aseptic processing lines serving cost-sensitive Latin American distribution.
RTD Coffee Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the RTD coffee category, with integrated beverage conglomerates controlling manufacturing infrastructure while specialty brands outsource to co-packers. Nestlé S.A. and PepsiCo Inc. anchor volume tiers through owned production networks spanning multiple continents. Three archetypes dominate: diversified conglomerates leveraging cross-category distribution, café-origin brands licensing retail exclusivity, and direct-to-consumer specialists subscription-anchoring premium positioning. Competitive moves concentrate on M&A absorption of regional cold brew specialists and capacity expansion into aseptic-nitro convergent processing.
Among diversified beverage conglomerates, Nestlé S.A., PepsiCo Inc., and The Coca-Cola Company occupy positions defined by manufacturing scale and retail cold-case penetration breadth. Nestlé S.A. exemplifies the volume-anchored archetype through Nescafé brand equity and European-Latin American distribution density. PepsiCo Inc. represents aggressive convenience-store positioning with value-tier SKU proliferation. The Coca-Cola Company sits within licensed-partnership models that access café-channel brand equity without owned retail infrastructure.
| Leading Market Players |
|---|
| Danone S.A. |
| Keurig Dr Pepper Inc. |
| PepsiCo Inc. |
| Suntory Beverage & Food Limited |
| Asahi Group Holdings Ltd. |
| The Coca-Cola Company |
| McDonald's Corporation |
| Nestlé S.A. |
| Starbucks Corporation |
| Others |
Value Chain & Pricing Dynamics
Arabica bean procurement costs cascade through three distinct pricing tiers, with high-altitude origin premiums separating cold brew specialists from hot-fill commodity producers and ambient-stable aseptic formats capturing margin from refrigerated distribution savings.
Pricing Analysis
Outcome-based pricing anchors premium cold brew and nitro-infused SKUs to sensory quality metrics and workplace productivity claims rather than per-ounce commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-infused craft positioning from conventional hot-fill and value-tier private label offerings. Price differentiation rests on certification grade and cold-chain dependency, with organic-certified and refrigerated formats commanding shelf-space premiums. Cost compression in the economy tier is intensifying because aluminum can input volatility and third-party logistics rate escalation squeeze value-brand margins. Students and price-sensitive emerging-market consumers exhibit highest price elasticity, while office-worker subscription segments show lowest sensitivity due to employer amenity subsidies.
Supply Chain Analysis
Domestic-content mandates under Brazil's ANVISA framework and EU Green Deal packaging-recovery requirements are reshaping sourcing toward regional canning infrastructure and certified arabica cooperatives. Supply concentrates in Brazil, Colombia, and Vietnam for bean inputs, with Germany and Japan hosting nitrogen-dissolution equipment manufacturing. Raw material dependencies span high-altitude arabica contracts, aluminum can sheet, and aseptic carton laminates. Single-source vulnerability in refrigerated third-party logistics clusters across the United States and Japan threatens nitro product distribution continuity. Distribution runs through supermarket refrigerated dairy cases, convenience-store open-air coolers, and direct-to-consumer subscription platforms bypassing traditional slotting-fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around capital-intensive processing technology, with equipment-heavy cold brew and nitrogen-infusion requirements forcing mid-tier co-packers toward acquisition or exit.
For Market Incumbents: To counter specialty direct-to-consumer brands eroding premium positioning, Nestlé S.A. and PepsiCo Inc. should acquire regional cold brew specialists with established nitrogen-infusion lines. Backward integration into high-altitude arabica sourcing contracts in Minas Gerais and Antioquia secures margin predictability against commodity volatility. Channel control through exclusive workplace cold-case placement agreements in Japanese and South Korean office districts reinforces volume defense.
For New Entrants and Emerging Players: Aseptic-nitro convergence technology offers entry into direct-to-consumer subscription channels without cold-chain infrastructure investment. Latin American organic certification penetration lags North American premium grocer saturation, creating white-space opportunity in São Paulo and Mexico City retail expansion. Fitness enthusiast functional positioning with protein fortification and sugar reduction claims provides the most penetrable segment against established café-origin brands.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier co-packers with underutilized aseptic capacity in Campinas and Campinas-adjacent industrial corridors. Long-term viability over the next decade hinges on nitrogen-retention technology ownership and METI-aligned energy-efficient vending system deployment capability. Watch for inflection signals in Japanese workplace amenity investment rates and EU F-Gas Regulation compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic-Nitro Processing Convergence | Combines ambient-stable distribution with dissolved nitrogen retention, opening direct-to-consumer channels without refrigerated logistics dependency. |
| Organic Certification Expansion | USDA Organic and EU Organic label penetration in Latin American retail channels captures premium positioning ahead of competitor saturation. |
| Workplace Cold-Case Placement | Employer amenity investments in Tokyo and Seoul office districts secure recurring volume through productivity-linked corporate procurement. |
| Energy-Efficient Vending Deployment | METI-aligned on-demand chilling systems reduce continuous refrigeration costs while maintaining grab-and-go accessibility in high-density transit corridors. |
| High-Altitude Sourcing Contracts | Origin-specific arabica agreements in Minas Gerais and Antioquia buffer margin volatility against commodity price swings for cold brew specialists. |
Study Parameters
Independent corroboration across regulatory filings, customs trade databases, and retail audit data underwrites the qualitative findings. Primary interviews with cold brew formulation chemists, beverage category buyers at convenience chains, nitrogen-infusion equipment manufacturers, and workplace facilities managers combined with secondary validation from FDA GRAS determinations, EU F-Gas Regulation implementation reports, and METI energy-efficiency standards documentation. Bottom-up facility capacity assessments and top-down retail velocity estimates triangulate volume conclusions.
Historical reference periods spanning installed base growth and channel shift patterns anchored the projection horizon. The analytical framework models product type, packaging format, distribution channel, and end-user segmentation dimensions across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs include arabica price volatility scenarios and refrigerated logistics cost trajectories under EU Green Deal compliance requirements.
Several conditions sit outside the modeled scope, including pending caffeine-limit regulatory proposals and breakthroughs in ambient nitrogen-retention shelf-life extension. Forecasts reflect documented assumptions about workplace consumption pattern continuity and employer amenity investment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Single Origin Coffee Market
Coffee
United States Coffee Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Ethiopia Coffee Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Espresso Powder Market
Coffee
Encapsulated Caffeine Market
Coffee
Raw Coffee Beans Market
Coffee
Coffee Pods Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Global Professional Coffee Machine Market
Coffee
China Coffee Market
Coffee
Instant Coffee Market
Coffee
Espresso Tamper Market
Coffee
Coffee and Tea Capsule Market