
 Green Coffee Extract Market | 2026-2036
Green Coffee Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Green Coffee Extract Market Foresight
Functional beverage formulation is decoupling from conventional roasted coffee derivatives as brands seek chlorogenic acid stability in ready-to-drink formats. Naturex leverages proprietary extraction protocols to supply standardized polyphenol concentrations for European nutraceutical clients. Glanbia anchors its position through integrated raw-material sourcing from Brazilian cooperatives. Kerry Group competes by extending flavor-masking technologies that offset the bitter profile of high-chlorogenic-acid extracts.
Green coffee extract comprises unroasted Coffea arabica or Coffea canephora beans processed through aqueous or supercritical CO2 extraction to preserve chlorogenic acid content typically ranging from 45% to 70% by dry weight; manufacturers deploy it primarily for antioxidant and metabolism-modulation applications in dietary supplements and functional foods. Powder formulations dominate bulk ingredient procurement due to superior shelf stability and blending compatibility, while liquid extracts capture premium positioning in beverage applications where rapid dissolution matters. The nutraceuticals segment leads volume absorption, though pharmaceutical-grade specifications are deepening margin pools as clinicians explore adjunct therapies for glycemic management.
FDA GRAS self-affirmation and EU Novel Food catalog inclusion govern market access for new extract suppliers, with EFSA health-claim rejections on chlorogenic acid weight-loss substantiation reshaping formulation marketing in Europe. India's FSSAI functional-food category is opening import channels for standardized extracts as domestic supplement brands build direct-to-consumer platforms. Stakeholders must monitor evolving pharmacovigilance requirements for high-dose chlorogenic acid products as regulatory scrutiny intensifies across multiple jurisdictions.
Market Dynamics
Chlorogenic acid stability requirements in ready-to-drink functional beverages are forcing extract suppliers to abandon conventional aqueous extraction for supercritical CO2 and encapsulation technologies that preserve bioactive potency through shelf life.
Growth Catalysts
- EU Novel Food catalog expansion:EFSA's evolving guidance on green coffee extract safety dossiers is accelerating compliant supplier qualification for European nutraceutical brands seeking metabolism-support positioning.
- Functional beverage formulation:Brands in Germany and the United States are deploying high-chlorogenic-acid extracts in sports nutrition and weight-management SKUs, pulling volume from traditional roasted coffee derivatives.
- Brazilian cooperative sourcing:Integrated raw-material procurement from Minas Gerais and São Paulo growing regions is securing arabica bean supply chains for pharmaceutical-grade extraction capacity.
Market Restraints
- Input cost volatility:Unroasted green coffee bean prices fluctuate with Brazilian climate patterns and currency movements, compressing margin predictability for standardized extract producers.
- Regulatory friction:EFSA's repeated rejection of chlorogenic acid weight-loss health claims forces European marketers to retreat to generic antioxidant positioning, limiting premium pricing power.
- Substitution threat:Synthetic chlorogenic acid and alternative polyphenol sources from green tea and grape seed extracts compete on cost and established regulatory pathways.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI functional-food category opening creates import channels for standardized extracts as domestic direct-to-consumer supplement platforms scale.
- Technology convergence:Combination of supercritical CO2 extraction with nano-encapsulation is enabling beverage applications previously blocked by chlorogenic acid degradation and bitter taste profiles.
- Regulatory tailwind:FDA GRAS self-affirmation pathway offers faster market access than EU Novel Food procedures, rewarding suppliers with robust toxicology dossiers.
Industry Challenges
- Pharmacovigilance compliance:Evolving adverse-event reporting requirements for high-dose chlorogenic acid products across FDA, EMA, and national European regulators demand expanded safety monitoring infrastructure.
- Flavor-masking integration:Bitterness suppression technologies must achieve clean-label status while maintaining extract standardization, complicating formulation partnerships with beverage manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Coffee Extract Market |
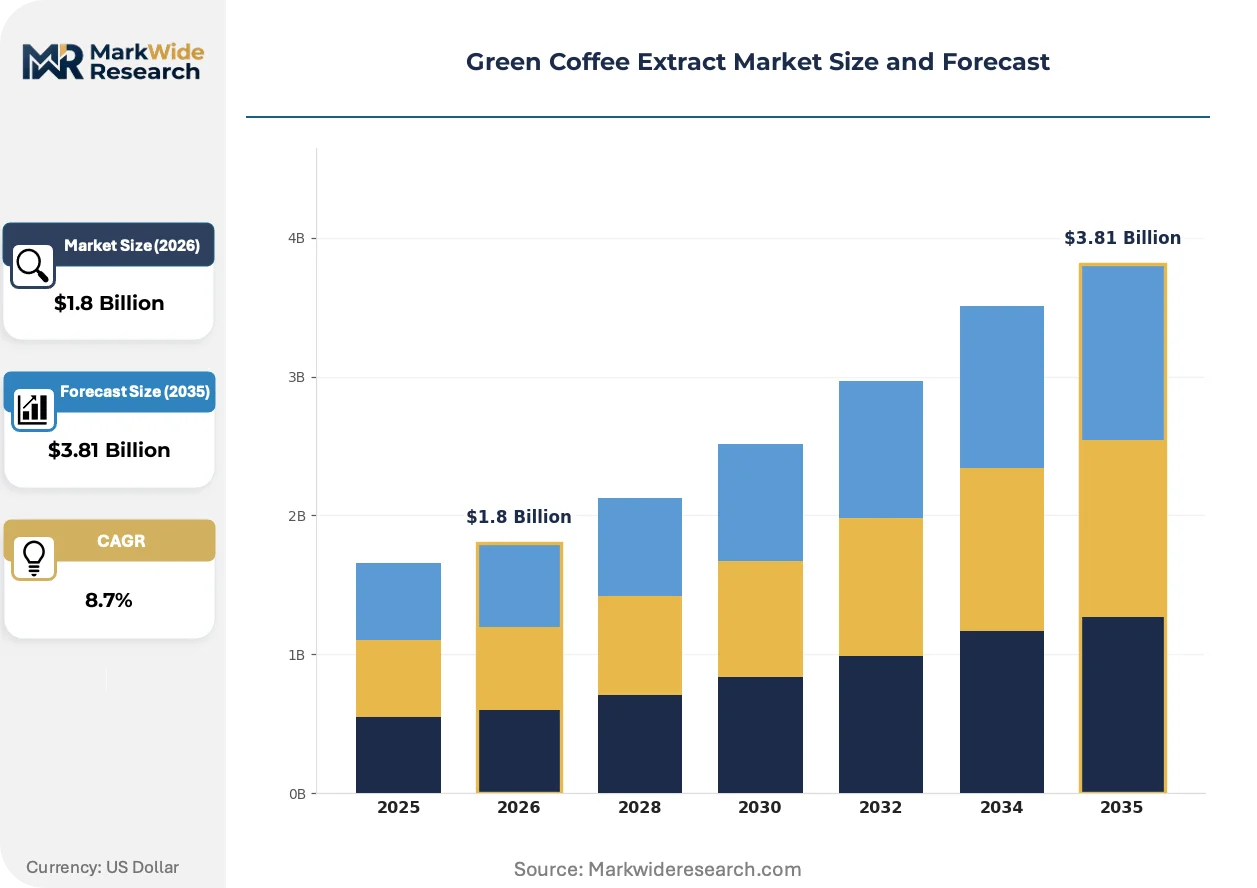
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Capsule, Granule Application: Nutraceuticals, Pharmaceuticals, Dietary Supplements, Food & Beverages End User: Health Conscious Consumers, Athletes, Diabetics, Weight Loss Seekers Distribution Channel: Online, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Naturex, Glanbia, Nestle, Dohler Group, Prinova Group LLC, Cargill, Archer Daniels Midland Company, Sunrise Nutrachem Group, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Coffee Extract Market Shifts & Advancements
Extraction technology and regulatory substantiation protocols are converging to redefine competitive advantage, with preservation of bioactive integrity and compliance velocity displacing scale economies as primary differentiators.
Supercritical CO2 extraction with integrated encapsulation is modularizing production workflows for chlorogenic acid preservation. Functional beverage manufacturers in North America are adopting these systems at pilot scale before full commercial deployment. The technology is modularizing supplier relationships by enabling smaller batch production with pharmaceutical-grade consistency, compressing minimum order quantities and opening procurement to mid-tier brands.
EFSA health-claim substantiation requirements are tightening evidentiary standards for weight-management positioning across European markets. This regulatory pressure is redirecting R&D investment toward glycemic management and antioxidant mechanisms with stronger clinical support. German and French nutraceutical brands are responding by reformulating marketing claims and pursuing pharmaceutical-adjacent positioning that bypasses food-supplement restrictions.
Direct-to-consumer supplement platforms are consolidating procurement power through private-label extract specifications. Traditional ingredient distributors in the United States and Germany face disintermediation as brands source directly from Brazilian and Indian extraction facilities with certified organic and fair-trade credentials. This channel compression is most visible in subscription-based wellness brands targeting metabolic health consumers with transparent supply chain storytelling.
Green Coffee Extract Market Segmentation
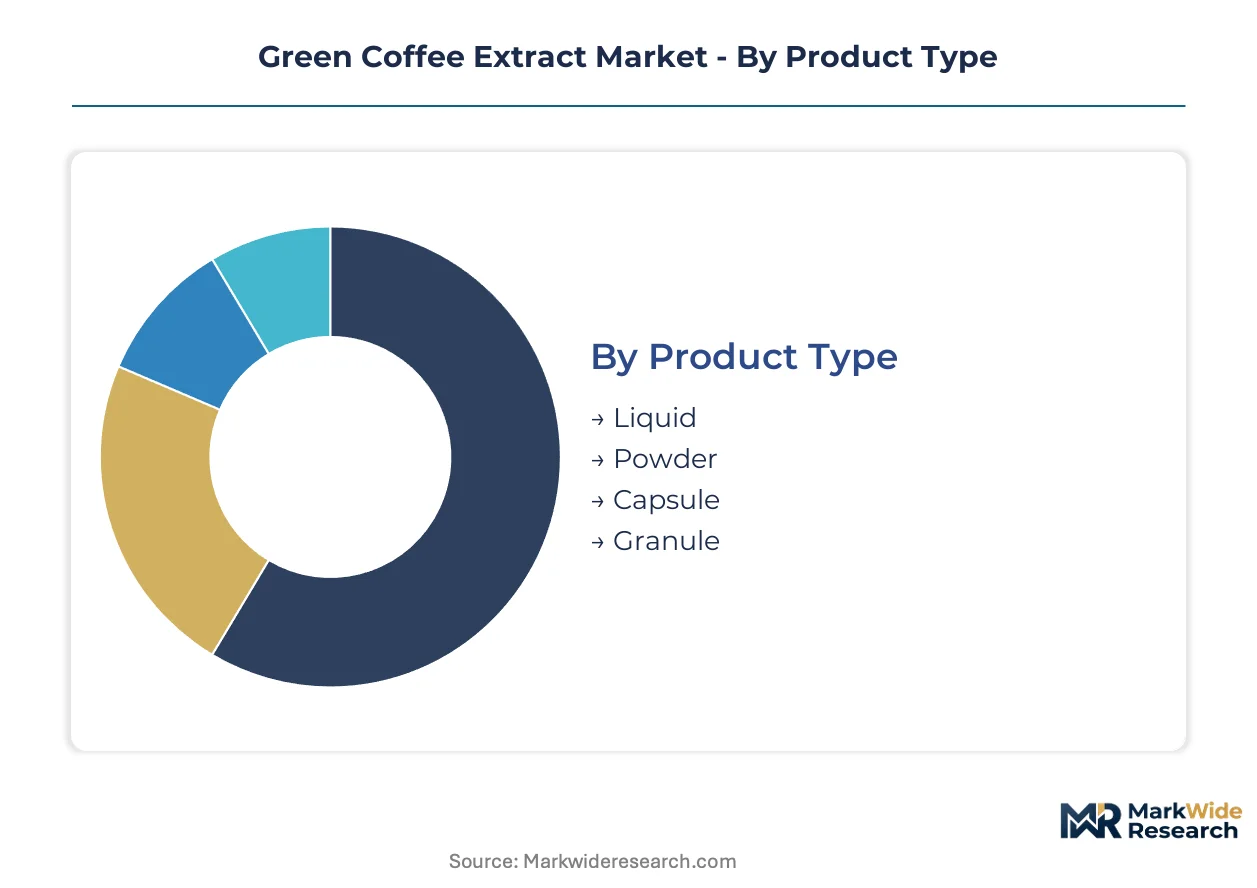
Green coffee extract procurement patterns diverge sharply across product formats and end-use specifications, with shelf-stability requirements and bioactive potency preservation driving supplier selection. Pharmaceutical-grade standardization commands premium positioning distinct from commodity nutraceutical sourcing, while direct-to-consumer channel expansion is fragmenting traditional distribution hierarchies.
Product Type:
Upgrade cycles in extraction technology are displacing legacy aqueous methods, with supercritical CO2 systems enabling new format possibilities previously blocked by chlorogenic acid degradation constraints.
- Powder:Dominates bulk ingredient procurement due to superior shelf stability and blending compatibility in dry-mix supplements. German nutraceutical manufacturers favor standardized 50-70% chlorogenic acid powders for metabolism-support formulations, though aqueous-extracted variants face margin pressure from supercritical CO2 alternatives.
- Liquid:Captures premium positioning in ready-to-drink functional beverages where rapid dissolution and batch-to-batch consistency matter. North American sports nutrition brands are accelerating adoption despite higher logistics costs and shorter shelf life, pulled by consumer preference for beverage delivery formats.
- Capsule:Serves standardized-dose convenience in direct-to-consumer supplement platforms with minimal flavor-masking requirements.
- Granule:Targets instant-dissolve applications in hot beverage formats, common in Asian functional food markets.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Cost tier stratification separates pharmaceutical-grade extraction investments from commodity nutraceutical sourcing, with glycemic management claims commanding substantiation premiums that weight-loss positioning no longer supports.
- Nutraceuticals:Leads volume absorption through dietary supplement and functional food integration, with EFSA health-claim rejections on weight-loss substantiation forcing retreat to generic antioxidant positioning. German and French brands are reformulating toward pharmaceutical-adjacent claims that bypass food-supplement restrictions.
- Pharmaceuticals:Deepens margin pools as clinicians explore chlorogenic acid adjunct therapies for glycemic management, requiring GMP-certified extraction facilities and pharmacovigilance infrastructure. Indian CDSCO import pathways are opening for pharmaceutical-grade specifications as domestic contract manufacturing scales.
- Dietary Supplements:Faces channel compression as direct-to-consumer platforms consolidate procurement power through private-label specifications.
- Food & Beverages:Depends on flavor-masking partnerships to offset bitter profiles in high-chlorogenic-acid formulations.
Margin capture concentrates in Pharmaceuticals; the steepest volume climb belongs to Nutraceuticals.
End User:
Customer type segmentation reflects divergent efficacy expectations and price sensitivity, with clinical validation requirements separating medical-adjacent users from wellness-oriented purchasers.
- Health Conscious Consumers:Drives mainstream volume through preventive wellness positioning and transparent supply chain storytelling, with subscription-based platforms capturing repeat purchase loyalty. Brazilian fair-trade and organic certifications feature prominently in brand differentiation.
- Weight Loss Seekers:Faces demand headwinds from EFSA claim rejections and FDA scrutiny of weight-management substantiation, forcing marketers toward metabolism-support framing with weaker clinical backing.
- Athletes:Pulls sports nutrition innovation through pre-workout and recovery formulations with rapid bioavailability requirements.
- Diabetics:Represents emerging clinical interest in glycemic management applications, though regulatory pathways for disease-related claims remain restricted.
Volume concentration sits with Health Conscious Consumers; Athletes show the most rapid segment expansion.
Distribution Channel:
Supply concentration in Brazilian extraction facilities and Indian import channels is compressing traditional distributor margins, with certified-organic credentials enabling direct brand-to-manufacturer relationships.
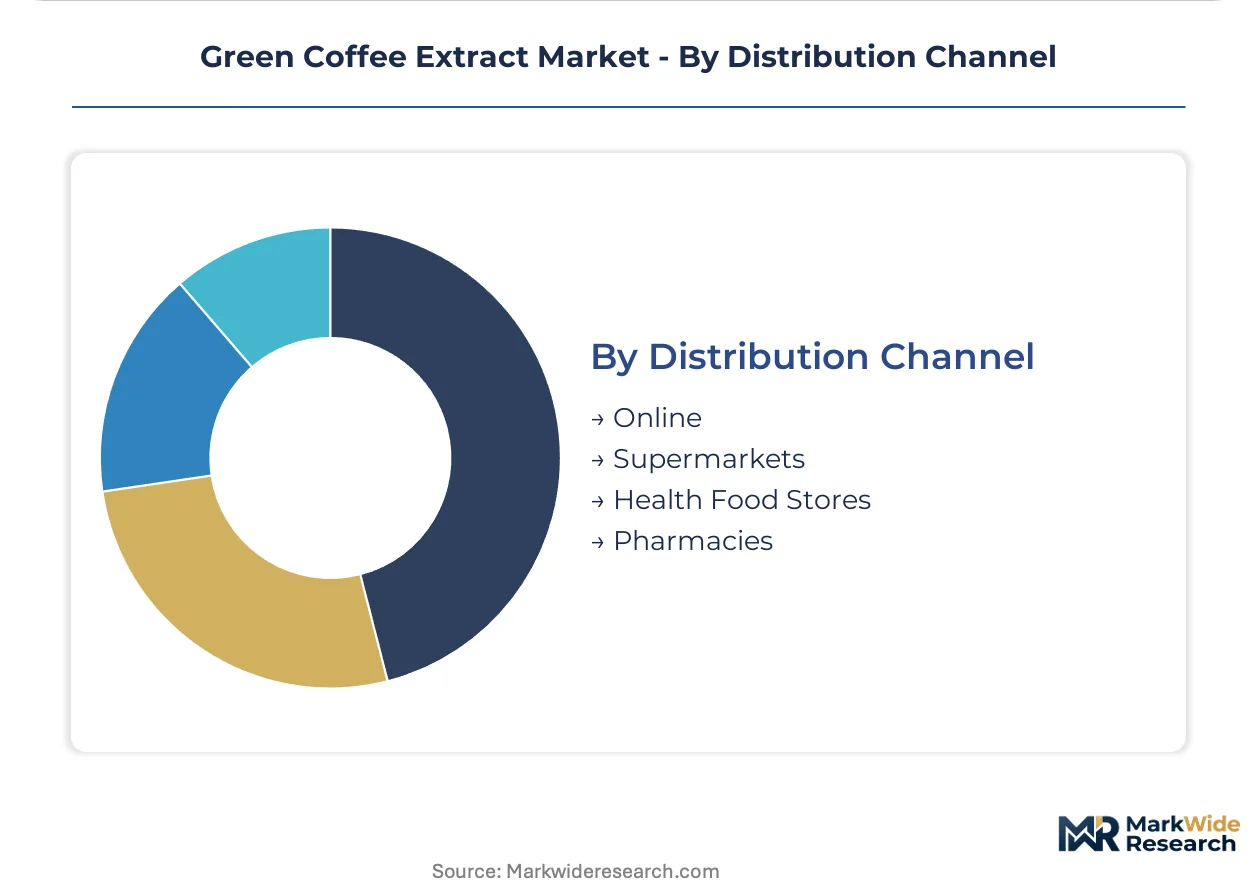
- Online:Disintermediates traditional ingredient distributors through direct-to-consumer supplement platforms and private-label brand procurement from certified extraction facilities. Subscription-based wellness brands in the United States and Germany are consolidating procurement power with transparent supply chain narratives.
- Health Food Stores:Maintains premium positioning for organic and fair-trade certified extracts, though foot traffic erosion shifts volume toward digital channels.
- Supermarkets:Captures mass-market functional beverage placement with standardized lower-potency formulations.
- Pharmacies:Requires pharmaceutical-grade specifications and national regulatory approvals that limit supplier qualification.
Volume is shifting fastest toward Online; Pharmacy channels retain the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates raw material supply through Minas Gerais and São Paulo growing regions, while Germany, the United States, and India absorb differentiated extract grades for nutraceutical and pharmaceutical applications. This production-consumption divide shapes procurement strategies across regulatory jurisdictions.
Germany
Functional beverage manufacturers in Bavaria and North Rhine-Westphalia accelerate procurement of chlorogenic acid-enriched extracts for metabolism-supporting product lines. EFSA health-claim rejections on weight-loss substantiation force reformulation toward pharmaceutical-adjacent positioning that bypasses food-supplement restrictions. Ingredient suppliers in Hamburg are building dedicated extraction capacity to serve pharmaceutical-grade contract manufacturing.
United States
Sports nutrition brands deploy high-chlorogenic-acid extracts in pre-workout and recovery formulations, pulling volume from traditional roasted coffee derivatives. FDA GRAS self-affirmation pathway rewards suppliers with robust toxicology dossiers through faster market access than EU Novel Food procedures. Direct-to-consumer supplement platforms in California and New York consolidate procurement power through private-label specifications with transparent supply chain narratives.
Brazil
Integrated raw-material procurement from arabica cooperatives secures bean supply chains for pharmaceutical-grade extraction capacity. ANVISA regulatory frameworks govern export certification for standardized extracts destined for North American and European nutraceutical markets. São Paulo-based extraction facilities leverage certified organic and fair-trade credentials to enable direct brand-to-manufacturer relationships that compress traditional distributor margins.
India
FSSAI functional-food category opening creates import channels for standardized extracts as domestic direct-to-consumer supplement platforms scale. CDSCO import pathways are opening for pharmaceutical-grade specifications as domestic contract manufacturing expands. Maharashtra and Karnataka clusters house extraction facilities serving subscription-based wellness brands targeting metabolic health consumers.
Green Coffee Extract Market Competitive Landscape
Top-tier vendors anchor premium pharmaceutical-grade supply, while mid-scale extraction specialists compete on certified organic credentials and regional regulatory compliance. The vendor base stratifies across integrated multinationals with Brazilian cooperative sourcing, European specialists with proprietary extraction protocols, and Asian manufacturers with cost-optimized aqueous methods. Strategic archetypes include backward-integrated raw-material controllers, technology-focused supercritical CO2 specialists, and flavor-masking formulation partners. Dominant competitive moves encompass capacity expansion in German pharmaceutical-grade facilities and strategic partnerships between extraction houses and direct-to-consumer wellness platforms.
Within the integrated multinational tier, Glanbia plc and Kerry Group plc exemplify divergent positioning strategies. Glanbia anchors supply security through upstream control over Brazilian arabica sourcing, while Kerry Group occupies a formulation-technology position extending flavor-masking capabilities that offset bitter chlorogenic acid profiles. Naturex SAS represents the European specialist archetype with proprietary extraction protocols serving standardized polyphenol concentrations. Among North American ingredient distributors, Prinova Group LLC and Archer Daniels Midland Company sit within the commodity-scale tier competing on volume procurement and logistics integration rather than differentiated bioactive preservation.
| Leading Market Players |
|---|
| Naturex |
| Glanbia |
| Nestle |
| Dohler Group |
| Prinova Group LLC |
| Cargill |
| Archer Daniels Midland Company |
| Sunrise Nutrachem Group |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade chlorogenic acid specifications from German contract manufacturers are forcing extract suppliers to secure dedicated aqueous and supercritical CO2 capacity, compressing spot-market availability and elevating premiums for GMP-certified batches. This demand-side specification tightening cascades through Brazilian arabica procurement, where certified organic premiums now separate qualified from commodity-tier suppliers.
Pricing Analysis
Short-lead-time procurement for pharmaceutical-grade extracts commands substantial premiums over contract offtake arrangements, with spot buyers in North America paying elevated rates for rapid GMP certification turnaround. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and commodity-economy levels reflects chlorogenic acid concentration and extraction method differentiation. Cost compression in the nutraceutical tier is intensifying because EFSA health-claim rejections have eroded weight-loss premium positioning. Direct-to-consumer supplement platforms show the highest price sensitivity, while pharmaceutical contract manufacturers accept premium pricing for validated pharmacovigilance documentation.
Supply Chain Analysis
ANVISA domestic-content certification requirements for Brazilian export facilities are reshaping sourcing patterns, with non-certified Indian and Southeast Asian extraction houses losing access to European pharmaceutical channels. Raw material supply concentrates in Brazil's Minas Gerais and São Paulo growing regions, with secondary sourcing from Vietnamese robusta cooperatives. Supercritical CO2 equipment and pharmaceutical-grade encapsulation materials draw from German and Italian specialty engineering suppliers. Single-source vulnerability runs through Brazilian climate-dependent arabica harvests. Distribution runs through direct brand-to-manufacturer relationships that disintermediate traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over certified organic Brazilian cooperatives and downstream capture of direct-to-consumer channels represent the decisive levers separating margin leaders from price-takers.
For Market Incumbents: Hedge against synthetic chlorogenic acid substitution threats by securing exclusive offtake agreements with São Paulo-based organic cooperatives and building captive supercritical CO2 capacity in Hamburg pharmaceutical-grade facilities. Channel control through direct partnerships with subscription wellness platforms defends against distributor disintermediation. For New Entrants and Emerging Players: Mid-tier sports nutrition brands in the United States seeking rapid dissolution liquid extracts represent an underserved buyer archetype bypassed by bulk powder specialists. India's FSSAI-compliant functional-food category offers the most penetrable geography for import-channel establishment. A certified organic, fair-trade supply chain narrative enables premium positioning without incumbent scale advantages. For Investors and Strategic Acquirers: The window for entry favors extraction technology specialists with integrated encapsulation capabilities and existing EFSA/FDA regulatory dossiers. Long-term viability hinges on pharmacovigilance infrastructure that pharmaceutical-grade contract manufacturing demands. The signal to monitor is CDSCO import pathway expansion for Indian pharmaceutical-grade specifications, which would validate glycemic management positioning and unlock clinical-adjacent margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazilian Cooperatives | Secures certified organic arabica supply chains against climate volatility and currency fluctuation. |
| Supercritical CO2 Capacity Expansion | Enables chlorogenic acid preservation for ready-to-drink beverage applications previously blocked by degradation. |
| Pharmaceutical-Grade Certification Investment | Unlocks GMP contract manufacturing relationships with German and Indian CDSCO-registered facilities. |
| Direct-to-Consumer Channel Partnership | Bypasses traditional distributor margins through transparent supply chain storytelling with subscription platforms. |
| Flavor-Masking Technology Licensing | Offsets bitter chlorogenic acid profiles for clean-label beverage formulations with Kerry Group-type positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction facility managers, nutraceutical brand formulators, pharmaceutical contract manufacturing procurement leads, and FSSAI regulatory consultants. EFSA guidance documents, FDA GRAS notifications, ANVISA export certifications, and Brazilian agricultural cooperative production statistics provided validation triangulation. Bottom-up volume modeling from extraction capacity utilization and top-down demand assessment from end-use application penetration were cross-referenced for consistency.
Reconciliation of production-volume data from Brazilian growing regions with import statistics from German and Indian customs authorities informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application tier, end-user archetype, and distribution channel, with extraction technology type as an industry-specific cross-cutting variable. CAGRs were derived from trend extrapolation of chlorogenic acid specification adoption rates and functional beverage formulation shifts, incorporating supercritical CO2 equipment deployment timelines and regulatory approval velocity as forecast inputs.
Revisions become necessary when EFSA substantiates novel health claims for chlorogenic acid, when Brazilian climate events disrupt arabica harvests, or when FDA issues adverse-event guidance for high-dose products. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
South America Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Global Cafe Market
Coffee
Chewable Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
US Instant Coffee Market
Coffee
Coffee Bags Market
Coffee
Coffee Beans Market
Coffee
North America Specialty Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Vietnam Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Middle East Coffee Market