
 Cold Brew Coffee Makers Market | 2026-2036
Cold Brew Coffee Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Brew Coffee Makers Market Insights
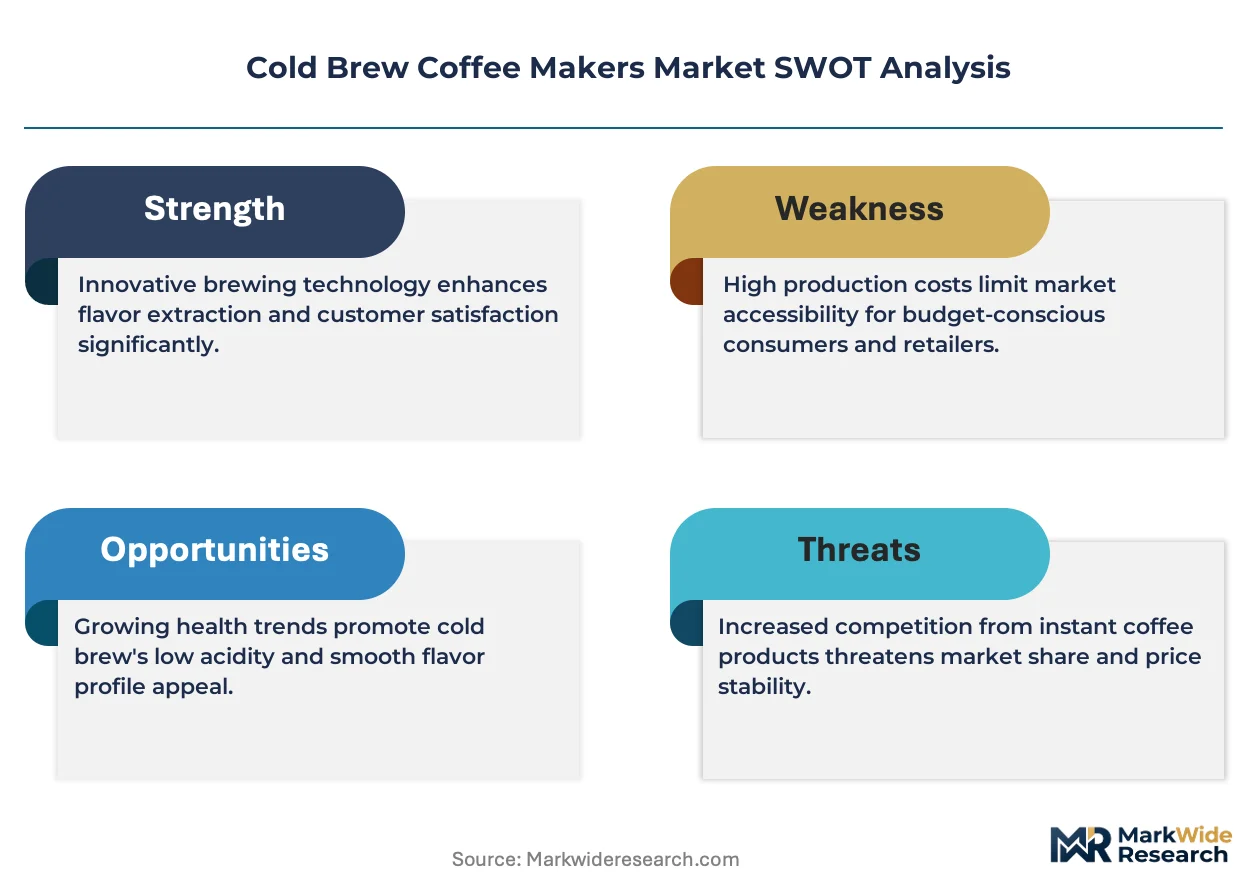
Subscription-based equipment leasing is rewriting competitive access for cold brew coffee makers, allowing smaller foodservice operators to deploy commercial-grade systems without capital outlay. BUNN leverages its institutional channel relationships to sustain placement density across hotel and university accounts. Cuisinart competes through multi-function countertop designs that anchor kitchen-counter presence. OXO differentiates via precision-engineered filtration mechanisms that command premium positioning in specialty retail.
Cold brew coffee makers are vessels or integrated systems designed to steep coarsely ground coffee in ambient or chilled water for extended durations, typically employing mesh filters, glass carafes, or sealed immersion chambers to produce low-acidity concentrate. Countertop units dominate household penetration due to compact footprint and intuitive operation, while commercial-grade systems capture concentrated margin pools in high-throughput cafe environments. The automatic technology segment leads volume shipments as consumers prioritize programmable steep cycles, though manual non-electric designs retain durable share among enthusiast subcultures.
FDA food-contact material regulations govern plastic and silicone components in domestic cold brew systems, while FCC certification applies to WiFi-enabled smart models. California's CEC Title 20 appliance standards constrain standby power draw for electric units, compressing design flexibility for manufacturers. Stakeholders must monitor how evolving energy efficiency mandates intersect with consumer demand for connected brewing features.
Market Dynamics
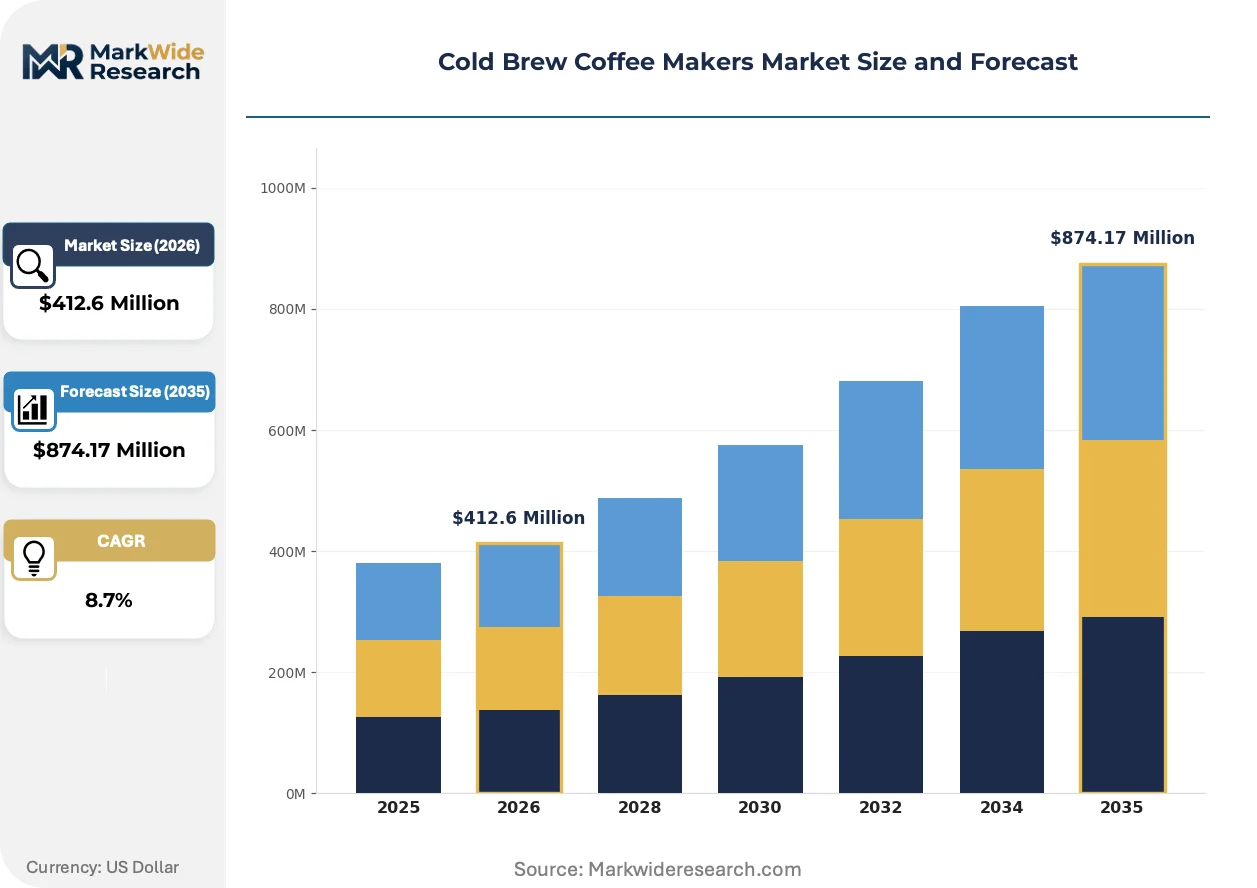
Subscription-based equipment leasing is compressing capital barriers for foodservice operators, while California's CEC Title 20 standards force redesign cycles for electric brewing systems. These dual pressures are restructuring competitive access and product development pipelines simultaneously.
Growth Catalysts
- Third-wave coffee culture:Japan's metropolitan retail corridors are driving premium equipment uptake as specialty cafes expand cold brew programs. Consumer education around lower-acidity extraction methods accelerates household penetration.
- California CEC Title 20:Appliance efficiency standards are tightening energy requirements for electric brewing systems, creating compliance-driven replacement cycles among existing installed bases.
- WiFi-enabled connectivity:Smart brewing features are expanding addressable market through programmable steep cycles and remote monitoring capabilities in automatic technology segments.
Market Restraints
- Silicone and plastic input volatility:FDA food-contact material regulations govern component specifications, constraining supplier flexibility and compressing margin structures for domestic manufacturers.
- Manual non-electric substitution:Enthusiast subcultures retain durable share through low-cost immersion chambers, limiting price realization for premium automatic systems.
- Standby power constraints:California's appliance standards limit design flexibility for connected features, forcing trade-offs between energy compliance and smart functionality.
Strategic Opportunities
- Hotel and university channels:Institutional accounts represent underpenetrated deployment vectors for commercial-grade systems through equipment leasing arrangements.
- FCC certification tailwinds:WiFi-enabled smart models face clearer regulatory pathways, enabling feature differentiation in specialty retail positioning.
- Multi-function convergence:Countertop designs integrating cold brew with other brewing methods are capturing kitchen-counter presence in compact-footprint households.
Industry Challenges
- Filtration engineering talent scarcity:Precision-engineered mesh systems require specialized design capabilities that concentrate among limited supplier networks.
- FCC certification timelines:Smart model approvals create launch delays that compress competitive windows for connected product cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Brew Coffee Makers Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Portable, Single-Serve, Commercial Technology: Automatic, Manual, Electric, Non-Electric End User: Households, Cafes, Restaurants, Office Size: Small, Medium, Large, Extra Large |
| Companies Covered | BUNN, Cuisinart, OXO, Toddy, Primula Products, Takeya, KitchenAid, Hario Mizudashi, Ninja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Brew Coffee Makers Market Trends and Innovations
Technology convergence and regulatory compression are actively reshaping product architecture and go-to-market economics. Three distinct vectors are restructuring competitive positioning across household and commercial segments.
Precision-engineered filtration mechanisms are rendering obsolete traditional mesh designs in premium specialty retail. Specialty cafes and enthusiast households are adopting glass carafe systems with sealed immersion chambers at accelerating rates. This technology shift is compressing margin pools for conventional countertop units while elevating engineering barriers to entry.
California's CEC Title 20 appliance standards are forcing standby power reductions across electric brewing system portfolios. Manufacturers must redesign control boards and heating elements to meet constrained energy budgets. The automatic technology segment faces the steepest compliance costs, with product teams sacrificing connected features to maintain certification timelines.
Leasing-based access models are displacing outright purchase in foodservice procurement. Smaller operators deploy commercial-grade systems through subscription arrangements that bundle maintenance and filter replacement. This pattern concentrates most visibly in United States hotel and university accounts where capital budget constraints intersect with high-throughput operational requirements.
Cold Brew Coffee Makers Market Segmentation
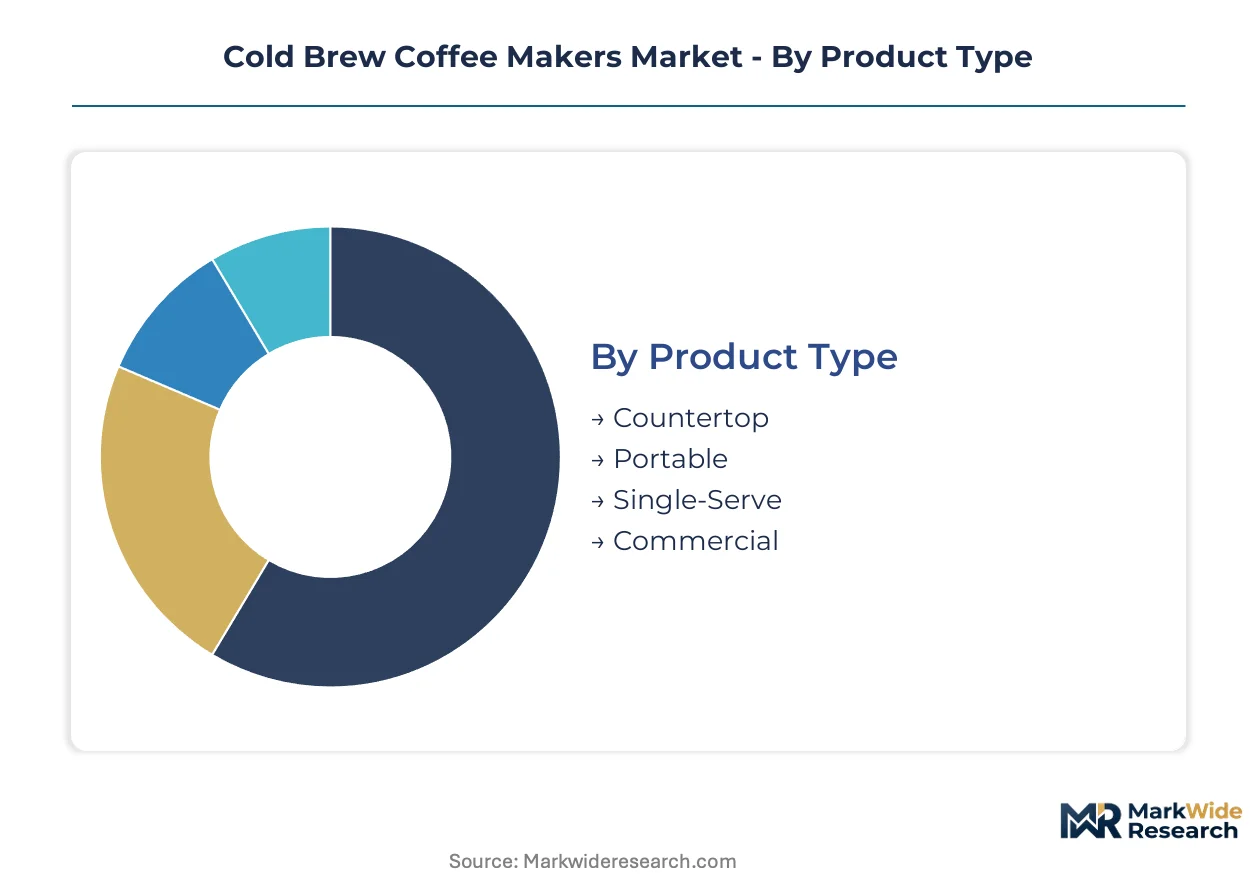
Cold brew coffee maker segmentation reveals distinct engineering requirements across deployment contexts. Product architecture, power dependencies, and capacity scaling each create separate competitive arenas with unique margin structures and regulatory exposures.
Product Type:
Mature countertop designs anchor household penetration through compact footprint optimization, while emerging commercial formats capture concentrated margin pools in high-throughput environments.
- Countertop:Glass carafe and sealed immersion chamber configurations dominate kitchen-counter presence. Demand concentrates in Japan's metropolitan retail corridors where third-wave coffee culture drives premium equipment uptake through lower-acidity extraction education.
- Commercial:High-capacity systems with programmable steep cycles serve hotel and university accounts through subscription-based equipment leasing arrangements. California's CEC Title 20 standards force redesign cycles for electric units in this segment, compressing design flexibility for manufacturers.
- Portable:Compact immersion chambers target travel and outdoor use cases with manual non-electric operation.
- Single-Serve:Individual portion systems integrate precision-engineered filtration for concentrate production at reduced batch scale.
Commercial handles the majority of throughput; Countertop is the fastest mover on share.
Technology:
Cost tier separation runs deepest in power-dependent versus power-agnostic architectures, with premium positioning accruing to connected automatic systems and value concentration in manual enthusiast formats.
- Automatic:Programmable steep cycles and WiFi-enabled connectivity expand addressable market through remote monitoring capabilities. FCC certification applies to smart models, creating clearer regulatory pathways for feature differentiation in specialty retail positioning.
- Manual:Non-electric immersion chambers retain durable share among enthusiast subcultures through low-cost simplicity. FDA food-contact material regulations govern plastic and silicone components, constraining supplier flexibility.
- Electric:Powered brewing systems with heating elements face California CEC Title 20 standby power constraints, forcing trade-offs between energy compliance and smart functionality.
- Non-Electric:Ambient water steeping vessels eliminate power dependencies entirely, appealing to off-grid and sustainability-focused users.
Automatic commands the steepest price realization; Non-Electric is climbing the fastest on volume.
End User:
Application context determines equipment specification intensity, with foodservice procurement prioritizing throughput durability and household selection emphasizing footprint and intuitive operation.
- Households:Compact countertop units with intuitive controls dominate penetration. Consumer education around lower-acidity extraction methods accelerates adoption of glass carafe systems with sealed immersion chambers.
- Cafes:Specialty cafes in the United States are expanding cold brew programs as consumer preference shifts toward premium extraction methods, driving commercial-grade system deployment.
- Restaurants:High-throughput operations require concentrate production at scale with consistent output quality.
- Office:Workplace deployment favors single-serve and medium-capacity automatic systems for shared amenity spaces.
Cafes handle the majority of throughput; Households are gaining share fastest.
Size:
Volume tier alignment with end-use scale creates natural segmentation boundaries, with capacity specifications directly mapping to batch frequency and operational throughput requirements.
- Large:Extra-capacity chambers serve commercial foodservice with extended steep cycles and concentrate storage. Demand concentrates in United States hotel and university accounts where capital budget constraints intersect with high-throughput requirements.
- Small:Individual portion systems minimize footprint for single-user households and trial adoption. FDA food-contact material regulations constrain design flexibility for plastic and silicone components at this scale.
- Medium:Balanced capacity targets multi-person households and small office environments.
- Extra Large:Industrial-scale systems for roasting operations and beverage manufacturing integration.
Large handles the majority of throughput; Small is expanding most quickly on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium equipment commands pricing power in Japan's metropolitan corridors while value-tier products dominate volume flows through United States mass retail channels. This asymmetry concentrates manufacturer R&D investment in precision filtration engineering for Asian markets while North American operations optimize for kitchen-counter footprint efficiency.
United States
Specialty cafes in California and New York are expanding cold brew programs as consumer preference shifts toward lower-acidity extraction methods. The FDA governs food-contact materials for plastic and silicone components in domestic systems, constraining supplier flexibility. Los Angeles and San Francisco anchor third-wave coffee equipment distribution, with BUNN leveraging institutional channel relationships across hotel and university accounts.
Japan
Third-wave coffee culture drives premium equipment uptake through consumer education around extraction quality. METI appliance standards shape energy efficiency requirements for electric brewing systems. Tokyo and Osaka metropolitan retail corridors concentrate demand for glass carafe systems with sealed immersion chambers.
Germany
Engineering-focused households prioritize precision-engineered filtration mechanisms in specialty retail positioning. CE marking requirements apply to WiFi-enabled smart models entering the European market. Munich and Berlin anchor commercial-grade system deployment through foodservice equipment distributors.
China
Manufacturing scale advantages support component supply for global cold brew system assembly. GB standards and SAMR oversight apply to domestic appliance certification. Shenzhen and Guangzhou industrial clusters concentrate plastic and silicone component fabrication for export markets.
United Kingdom
Cafe culture adoption accelerates commercial system deployment in London and Manchester metropolitan areas. UKCA marking transitions continue for post-Brexit appliance compliance. Specialty retail channels in Southeast England drive premium countertop unit penetration among enthusiast households.
Cold Brew Coffee Makers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration and sealing technologies. The market exhibits moderate concentration with tiered positioning across mass-market, specialty, and commercial verticals. Three archetypes dominate: institutional channel specialists leveraging long-term service contracts, kitchen-appliance conglomerates optimizing for countertop presence, and precision-engineering boutiques serving enthusiast subcultures. Competitive moves center on subscription-based equipment leasing arrangements and multi-function product convergence.
Among United States-based institutional specialists, BUNN occupies a position exemplifying channel density strategies, while Cuisinart anchors the multi-function countertop tier through kitchen-appliance ecosystem integration. OXO represents the precision-engineering archetype with filtration-focused premium positioning. These three companies collectively illustrate how divergent strategic postures—service bundling, ecosystem lock-in, and technical differentiation—can coexist within the same market structure without direct feature-for-feature competition.
| Leading Market Players |
|---|
| BUNN |
| Cuisinart |
| OXO |
| Toddy |
| Primula Products |
| Takeya |
| KitchenAid |
| Hario Mizudashi |
| Ninja |
| Others |
Pricing and Supply Chain Analysis
The Trans-Pacific container corridor from Shenzhen to Long Beach anchors cost dynamics for cold brew system manufacturers, compressing margin structures for plastic and silicone component suppliers while amplifying price differentiation between mass-market countertop units and precision-engineered filtration systems bound for Japanese specialty retail.
Pricing Analysis
The customization-premium spread separates configured-to-order commercial systems from standard countertop SKUs. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FDA food-contact certification grade and after-sales service bundling. Pricing pressure stems from California CEC Title 20 compliance costs forcing feature sacrifices in automatic segments. Household buyers exhibit highest price sensitivity, while Japanese specialty cafes accept premium positioning for precision filtration.
Supply Chain Analysis
Contract manufacturing concentration rests with Shenzhen and Guangzhou industrial clusters for plastic and silicone component fabrication. Raw material dependencies center on borosilicate glass from Germany, food-grade silicone from South Korea, and precision mesh filtration from Japan. Single-source vulnerability concentrates in specialized filtration engineering talent networks. Distribution runs through institutional channel partners for commercial-grade systems and mass retail for countertop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold brew coffee makers function as a service-attach opportunity where subscription-based equipment leasing and recurring filter replacement revenue expand faster than hardware sales alone. Filter replacement programs and maintenance contracts now outpace unit shipment growth in commercial segments.
For Market Incumbents: Insulate core margin pools by deepening backward integration into precision filtration component production and securing exclusive channel control across hotel and university accounts. The threat of manual non-electric substitution from enthusiast subcultures demands certification investment in FDA food-contact tier differentiation. Vertical integration into sealed immersion chamber engineering concentrates technical capability in-house. For New Entrants and Emerging Players: Establish a beachhead in portable and single-serve segments where brand loyalty remains undeveloped and price elasticity permits rapid share capture. The most penetrable white space sits in workplace office deployment through medium-capacity automatic systems. A direct-to-foodservice-operator go-to-market angle bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: California CEC Title 20 appliance standard evolution reshapes the acquisition landscape by forcing compliance-driven consolidation among electric system specialists. Long-term viability over the next decade hinges on regulatory navigation capability and connected feature development. Target acquisition archetypes include precision filtration engineering boutiques with METI or FCC certification pathways already cleared. The signal to watch is WiFi-enabled smart model shipment acceleration as inflection indicator for premium segment health.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Equipment Leasing | Bundles maintenance and filter replacement for hotel and university accounts in California and New York. |
| Precision Filtration Engineering Investment | Elevates technical barriers against manual non-electric substitution in Japanese metropolitan retail corridors. |
| Multi-Function Product Convergence | Captures kitchen-counter presence through cold brew integration with other brewing methods in compact-footprint households. |
| Regulatory Certification Fast-Tracking | Accelerates FCC pathways for WiFi-enabled smart models and FDA food-contact tier compliance. |
| Backward Integration into Component Supply | Secures captive supply of borosilicate glass and food-grade silicone from German and South Korean sources. |
Research Methodology
A standing panel of specialty cafe operations directors, foodservice equipment procurement managers, appliance retail category buyers, and filtration engineering specialists provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against FDA food-contact material filings, FCC equipment authorization databases, California CEC Title 20 appliance standards, and Japanese METI regulatory notices. Bottom-up shipment data triangulated against top-down market sizing across product type, technology, and end user segmentation dimensions.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases without year-specific anchoring. The analytical framework modeled countertop, commercial, portable, and single-serve product types alongside automatic, manual, electric, and non-electric technologies across the projection horizon. CAGRs derived from installed base replacement cycles, regulatory compliance-driven upgrade patterns, and third-wave coffee culture penetration rates. Inputs included steep cycle duration preferences, connectivity feature adoption curves, and regional appliance efficiency mandate trajectories.
Stress conditions across silicone and plastic input cost volatility, California standby power constraint tightening, and Japanese yen exchange rate fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and consumer education progression around lower-acidity extraction benefits. Quarterly review of FCC smart model certification volumes, METI energy standard revision notices, and specialty cafe cold brew program expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Take Out Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Coffee Fruit Extract Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
GCC Instant Coffee Market
Coffee
Cafix Market
Coffee
Global Professional Coffee Machine Market
Coffee
Adaptogen Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Coffee Crystal Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
Green Coffee Market
Coffee
Australia Coffee Market