
 Decaffeinated Coffee Market | 2026-2036
Decaffeinated Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Decaffeinated Coffee Market Intelligence
Demand within the decaffeinated coffee sector is rotating from price-sensitive retail consumers towards quality-focused food service providers and specialty cafés. Starbucks Corporation leverages its extensive café network to promote premium decaffeinated espresso beverages. Nestlé S.A. competes by offering a wide portfolio of instant and capsule products across multiple price points. Swiss Water Decaffeinated Coffee Inc. specializes in providing chemical-free decaffeinated beans to roasters globally.
Decaffeinated coffee refers to coffee beans from which at least 97% of the caffeine has been removed prior to roasting and grinding. The process often involves using solvents like methylene chloride, or non-solvent methods such as CO2 or water processing. While ground coffee sold through supermarkets remains the largest segment by volume, whole bean and capsule formats show higher growth rates. Sales through online retail channels are expanding, driven by direct-to-consumer brands and subscription models.
Regulations from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate permissible residual solvent levels in decaffeinated coffee. These rules influence production methods and require clear labeling, which shapes consumer purchasing decisions in markets like the United States and Germany. Navigating the diverse regional definitions of 'natural' and 'chemical-free' is a central strategic challenge for brand positioning and market access.
Market Dynamics
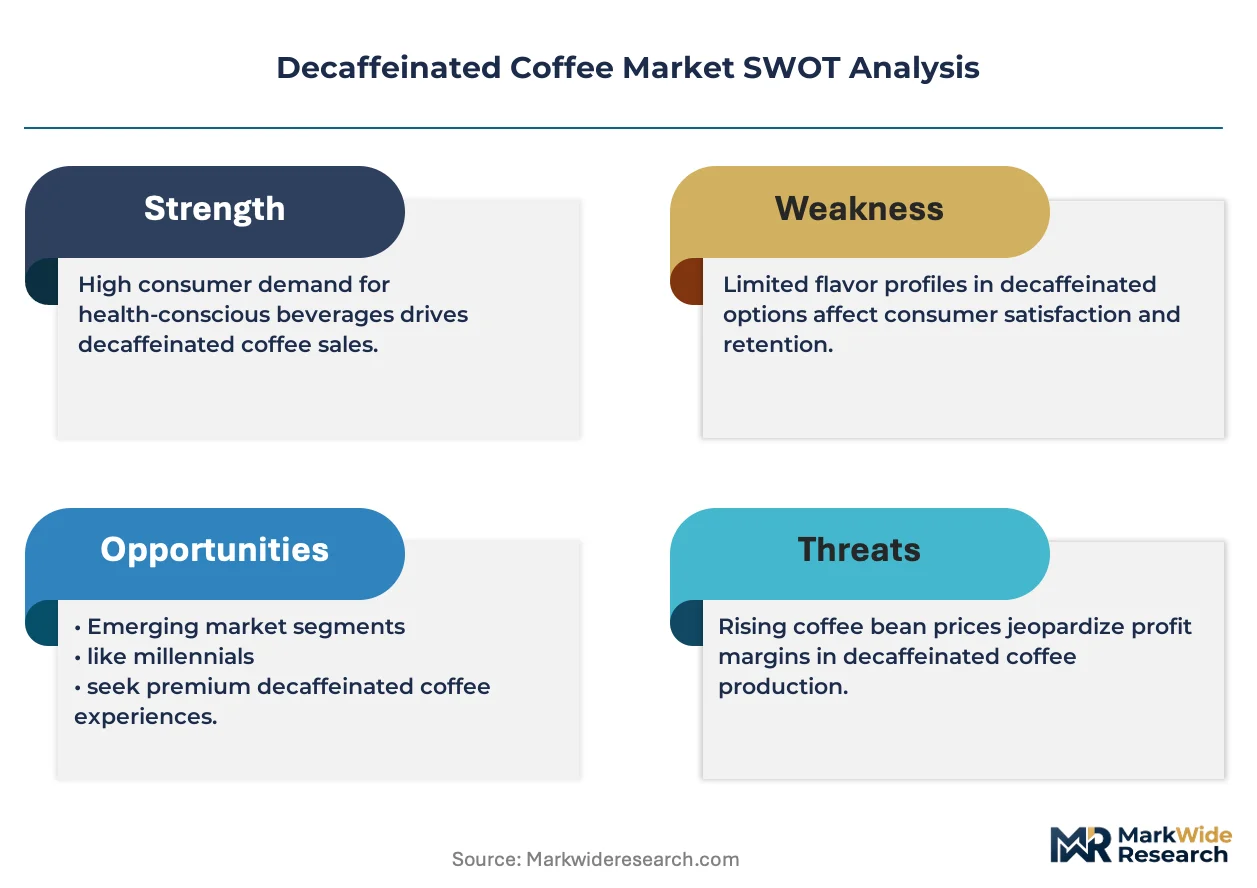
The market's central dynamic is a demand-side rotation toward premium, health-oriented products, driven by food service providers and discerning consumers. This shift is compelling a move away from solvent-based decaffeination methods toward more expensive but marketable solvent-free processes.
Growth Catalysts
- Solvent-Free Processes:The adoption of methods like the Swiss Water Process and supercritical CO2 extraction provides a strong marketing advantage, appealing directly to health-conscious consumers and justifying premium price points.
- Food Service Expansion:Specialty cafés and restaurant chains are expanding their premium beverage menus, creating consistent, high-volume demand for high-quality decaffeinated beans suitable for espresso and other craft drinks.
- European Health-Consciousness:Heightened consumer awareness regarding food processing chemicals in markets like Germany and Scandinavia creates a significant pull for products explicitly labeled as "chemical-free," favoring non-solvent decaffeination.
Market Restraints
- Processing Cost Disparity:Solvent-free methods like the Swiss Water Process have a higher per-pound processing cost than conventional methylene chloride-based methods, creating a price barrier for mass-market brands.
- Specialized Supplier Concentration:The technology and certification for leading solvent-free processes are concentrated among a few key suppliers, such as Swiss Water Decaffeinated Coffee Inc., creating potential supply bottlenecks.
- Regulatory Ambiguity:Navigating differing definitions of "natural" under FDA and EFSA guidelines creates labeling and marketing complexities for brands operating across North America and Europe.
Strategic Opportunities
- Ready-to-Drink (RTD) Formats:Developing and marketing premium decaffeinated RTD beverages, such as cold brews and lattes, can capture new consumption occasions and appeal to convenience-oriented younger demographics.
- Subscription and DTC Channels:Building direct-to-consumer subscription models allows brands to bypass retail gatekeepers, cultivate customer loyalty, and capture higher margins on specialty whole bean decaffeinated coffee.
- Emerging Market Entry:Introducing premium decaffeinated options in urban centers across Asia-Pacific can cater to a rising middle class with growing health awareness and disposable income for premium food products.
Industry Challenges
- Certification Management:Maintaining and communicating the validity of multiple certifications, such as organic, Fair Trade, and specific process patents, across different markets is a complex and continuous operational burden.
- Consumer Education Costs:Significant marketing investment is required to educate consumers on the benefits of different decaffeination processes to justify the price premium over conventional solvent-based products.
- Supply Chain Transparency:Establishing fully traceable supply chains to validate solvent-free claims from farm to cup requires significant investment in logistics and verification systems, posing a challenge for smaller roasters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decaffeinated Coffee Market |
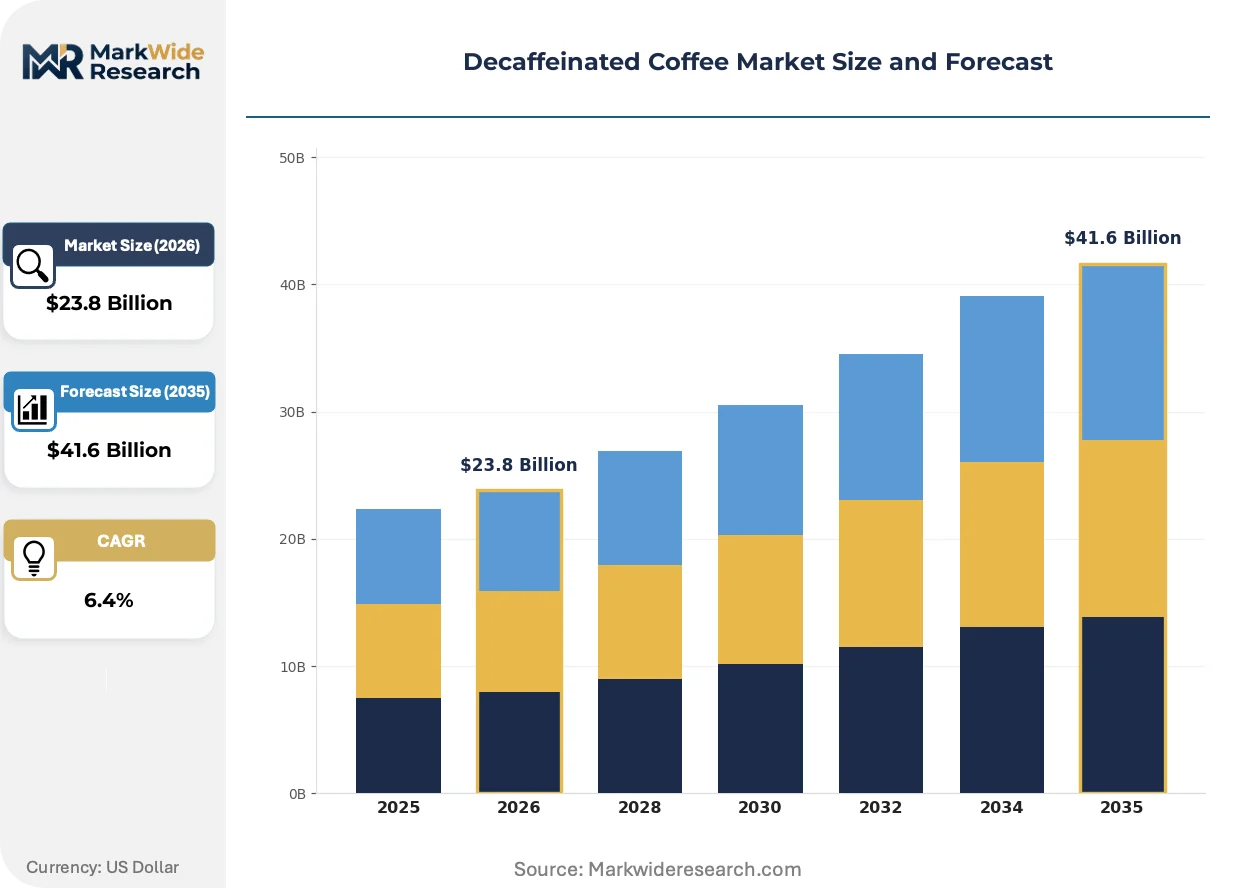
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant, Ground, Whole Bean, Capsule Distribution Channel: Supermarket, Online Retail, Specialty Stores, Convenience Stores Customer Type: Retail Consumers, Food Service Providers, Cafés, Offices Packaging Type: Bag, Canister, Pods, Bulk |
| Companies Covered | Nestlé S.A., JDE Peet's, Starbucks Corporation, The J.M. Smucker Company, Keurig Dr Pepper, The Kraft Heinz Company, Swiss Water Decaffeinated Coffee Inc., Tata Consumer Products Limited, Lavazza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decaffeinated Coffee Market Strategic Shifts & Innovations
Technological refinement in decaffeination and evolving regulatory standards are reshaping product development. These forces are converging with a behavioral shift in how consumers discover and purchase coffee, favoring transparency and direct engagement with brands.
Supercritical CO2 extraction provides a highly selective method for removing caffeine without using harsh chemical solvents. Specialty roasters and premium brands are increasingly adopting this technology to meet demands for "clean label" products. This process is miniaturizing the presence of any residual, non-coffee compounds, helping brands achieve a purer flavor profile that aligns with premium consumer expectations.
Regulatory scrutiny from bodies like the European Food Safety Authority (EFSA) on residual solvent levels in food products is influencing processing choices. This pressure incentivizes a move away from methods using methylene chloride, forcing producers to adopt and validate alternative processes. Brands exporting to the European Union are most affected, often reformulating to meet the bloc's stringent consumer protection and food safety standards.
Consumer purchasing behavior is pivoting from intermittent retail buys to recurring direct-to-consumer (DTC) subscription models. This shift disintermediates traditional supermarkets, enabling specialty roasters to build brand loyalty and gather valuable customer data. The trend is most pronounced in major North American and UK metropolitan areas, where a culture of coffee connoisseurship and e-commerce is well-established.
Decaffeinated Coffee Market Segmentation
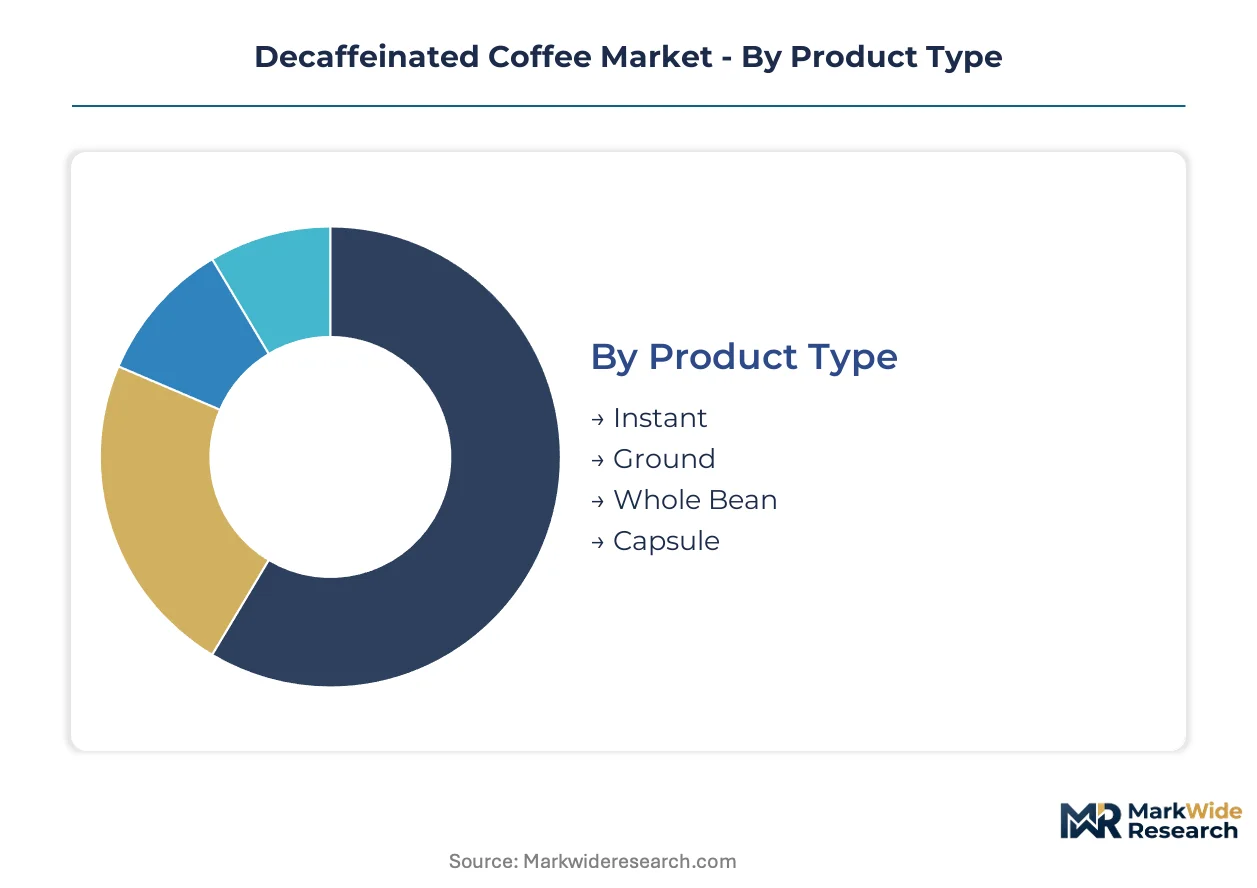
Understanding the segmentation of the decaffeinated coffee market is essential for brands to align product development and distribution strategies with evolving consumer preferences. This analysis highlights the distinct characteristics and commercial significance of various product forms, distribution channels, customer types, and packaging solutions.
Product Type:
Segments within product type face varying degrees of substitution pressure, influencing pricing power and market share.
- Ground:Pre-ground coffee beans, ready for brewing in various methods. This format remains a significant volume driver, with demand concentrating in supermarkets across Europe due to its convenience for daily consumption.
- Whole Bean:Unroasted or roasted coffee beans, requiring grinding before brewing. Food service providers and specialty cafés in the United States increasingly demand these for fresh, premium espresso beverages.
- Instant:Coffee processed into soluble powder or granules for quick preparation.
- Capsule:Pre-portioned coffee sealed in individual pods for single-serve machines.
Ground decaffeinated coffee anchors the volume base while capsule formats gain share at the steepest rate.
Distribution Channel:
Customer preferences for convenience and curated experiences dictate the performance of different distribution channels.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate sales of decaffeinated coffee. This channel expands rapidly in North American and UK metropolitan areas, driven by subscription models and direct brand engagement.
- Supermarket:Traditional grocery stores offering a wide range of decaffeinated coffee products. This channel remains a primary volume driver for retail consumers, particularly for conventional ground coffee.
- Specialty Stores:Boutiques and dedicated coffee shops providing premium decaffeinated options.
- Convenience Stores:Small retail outlets offering quick grab-and-go decaffeinated coffee products.
Supermarkets are optimized for mass-market accessibility, while online retail channels cultivate direct consumer relationships.
Customer Type:
Each customer type presents distinct margin potential and purchasing patterns for decaffeinated coffee products.
- Food Service Providers:Restaurants, hotels, and catering businesses purchasing decaffeinated coffee for on-premise consumption. Demand from these providers for premium options expands in European markets, particularly for specialty blends.
- Retail Consumers:Individuals purchasing decaffeinated coffee for home consumption through various channels. This segment increasingly seeks health-oriented products, influencing purchasing decisions towards solvent-free options.
- Cafés:Dedicated coffee shops, including chains like Starbucks, offering a range of decaffeinated beverages.
- Offices:Workplaces providing decaffeinated coffee options for employees and visitors.
Food service providers significantly influence product development towards premium decaffeinated offerings.
Packaging Type:
Packaging type reflects consumer priorities, balancing convenience with sustainability considerations.
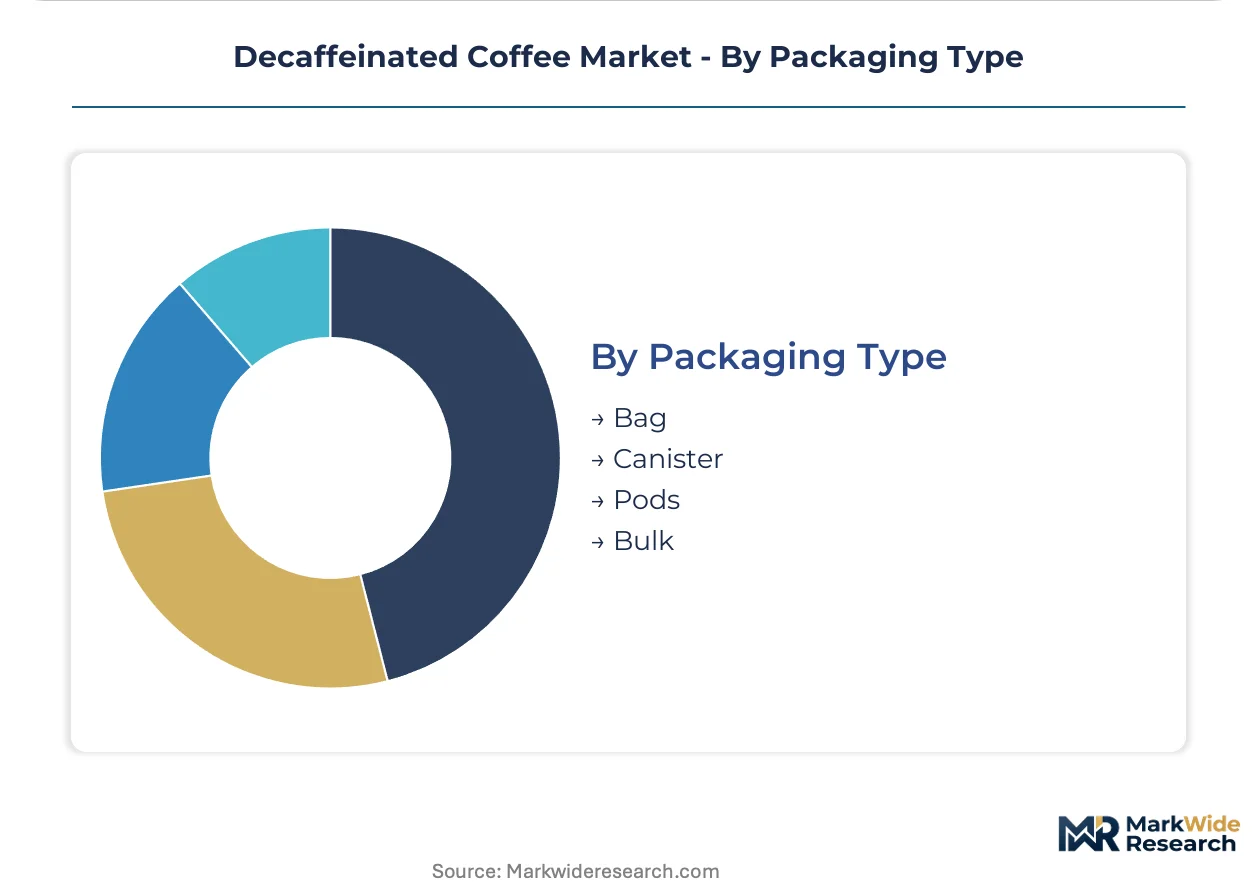
- Pods:Single-serve capsules designed for specific brewing systems, offering convenience and consistent portioning. This format aligns with the growing demand for single-serve decaffeinated options in residential settings.
- Bag:Flexible packaging, often resealable, commonly used for ground and whole bean decaffeinated coffee. This cost-effective solution is prevalent in supermarket sales for retail consumers.
- Canister:Rigid containers, typically metal or plastic, providing protection and extended freshness for decaffeinated coffee.
- Bulk:Large-volume packaging for decaffeinated coffee, primarily supplied to food service providers and industrial users.
Innovation in packaging focuses on enhancing user convenience and minimizing environmental impact.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of decaffeinated coffee from processing hubs in Switzerland to European markets underscores the global nature of this specialized sector. Demand for premium, health-oriented products is driving regional market dynamics. Consumer preferences and regulatory frameworks significantly shape market growth across diverse geographies.
Germany
Demand for chemical-free decaffeinated coffee is strong, driven by heightened consumer awareness regarding food processing chemicals. EFSA regulations on residual solvent levels significantly influence product availability and labeling in Germany. Hamburg serves as a major port and distribution hub, facilitating the import of specialty decaffeinated beans for roasters.
United States
Retail consumers and food service providers increasingly seek premium decaffeinated options, particularly whole bean and capsule formats. FDA regulations dictate permissible residual solvent levels and require clear labeling, impacting market access for various products. Major metropolitan areas like New York and Los Angeles exhibit high demand for specialty decaffeinated espresso beverages.
United Kingdom
Online retail and direct-to-consumer subscription models are expanding rapidly, catering to convenience-oriented consumers in major cities. The UK's Food Standards Agency (FSA) aligns with EFSA guidelines on food safety and labeling for decaffeinated products. London's vibrant coffee culture and e-commerce infrastructure support the growth of specialty decaffeinated brands.
Japan
Health-conscious consumers are driving interest in solvent-free decaffeinated options, aligning with a broader trend towards wellness products. Japan's Ministry of Health, Labour and Welfare (MHLW) sets food additive standards and caffeine limits for various beverages. Tokyo's sophisticated culinary scene and convenience stores offer a diverse range of premium decaffeinated coffee products.
Brazil
A rising middle class in urban centers is beginning to explore premium decaffeinated coffee, moving beyond traditional instant formats. ANVISA, Brazil's health surveillance agency, regulates food safety and labeling requirements for imported and domestically produced coffee. São Paulo, as a major economic hub, shows emerging demand for specialty decaffeinated offerings in cafes and restaurants.
Decaffeinated Coffee Market Key Industry Players
Player mix skews toward established global food and beverage conglomerates alongside specialized decaffeination service providers. The market structure exhibits a tiered consolidation, with large players leveraging extensive distribution networks to reach mass markets and smaller, agile firms targeting niche premium segments. Strategic archetypes include diversified consumer goods giants, coffee-focused brands with strong café presence, and technology specialists providing solvent-free processing methods. Companies are primarily pursuing portfolio diversification, geographic expansion, and strategic partnerships to capture market share in evolving consumer preference landscapes.
Within the diverse market, Nestlé S.A., a prominent global food and beverage conglomerate, exemplifies the broad portfolio archetype, offering a wide range of instant and capsule products across multiple price points. Starbucks Corporation, with its extensive café network, represents a key player in promoting premium decaffeinated espresso beverages to a discerning consumer base. Swiss Water Decaffeinated Coffee Inc. occupies a distinct position as a technology specialist, providing chemical-free decaffeinated beans to roasters globally and anchoring the solvent-free processing segment with its patented methods.
| Leading Market Players |
|---|
| Nestlé S.A. |
| JDE Peet's |
| Starbucks Corporation |
| The J.M. Smucker Company |
| Keurig Dr Pepper |
| The Kraft Heinz Company |
| Swiss Water Decaffeinated Coffee Inc. |
| Tata Consumer Products Limited |
| Lavazza |
Cost & Logistics Intelligence
Long-term offtake agreements for specialty beans lock in both supply access and price visibility for premium decaffeinated coffee producers. This contract-based approach mitigates raw material price volatility, particularly for solvent-free processed beans.
Pricing Analysis
The technology-generation pricing gap between solvent-free and solvent-based decaffeination methods remains significant. Pricing stratifies across premium, standard, and economy tiers, with quality grade and certification level, such as Swiss Water Process, serving as key differentiation drivers. Pricing softness reflects intense competition for mass-market ground coffee, while premium whole bean formats command higher margins. Retail consumers demonstrate higher price sensitivity for ground decaffeinated coffee, whereas food service providers prioritize consistent quality and process transparency.
Supply Chain Analysis
Just-in-time inventory strategies for green coffee beans are common, but strategic stockpiling of specialty decaffeinated green beans ensures consistent supply for premium roasters. Geographic supply concentration for decaffeinated green coffee centers on processing hubs in Switzerland and Canada, which then distribute globally. Raw material dependencies include high-quality green coffee beans and specialized processing chemicals or proprietary filtration systems. Regulatory restriction on solvent use represents a structural risk, particularly for brands exporting to the European Union. Distribution runs through a fragmented network of importers, roasters, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as traditional caffeinated coffee remains a formidable, lower-cost alternative for many consumers. Incumbents must innovate to highlight the unique health and flavor benefits of decaffeinated options.
For Market Incumbents:
Consolidate strategic partnerships with solvent-free decaffeination specialists like Swiss Water Decaffeinated Coffee Inc. This secures access to premium processing capacity and defends against the threat of regulatory changes impacting solvent-based methods. Invest in consumer education campaigns to justify the price premium for chemical-free products, leveraging certification investment as a key lever. Expand premium decaffeinated espresso beverage offerings within existing café networks, targeting discerning consumers.
For New Entrants and Emerging Players:
Anchor in direct-to-consumer (DTC) subscription models for specialty whole bean decaffeinated coffee. This strategy bypasses established retail gatekeepers and cultivates brand loyalty among health-conscious consumers in North American and UK metropolitan areas. Target the underpenetrated ready-to-drink (RTD) decaffeinated segment with innovative cold brew and latte formats. Focus on clear "clean label" messaging and transparent sourcing as a primary go-to-market angle.
For Investors and Strategic Acquirers:
Capital is best deployed toward technology specialists offering proprietary solvent-free decaffeination processes or brands with strong DTC penetration in premium decaffeinated segments. The long-term viability for this market depends on sustained consumer demand for health-oriented products and increasing regulatory scrutiny on food processing. Acquisition targets should possess robust supply chain transparency and verifiable chemical-free certifications. The signal to watch is the rate of adoption of solvent-free methods by major food service chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Cultivates customer loyalty and captures higher margins for specialty decaffeinated coffee brands. |
| Solvent-Free Processing Capacity Investment | Secures supply of premium, health-oriented decaffeinated beans, meeting evolving consumer preferences. |
| Premium RTD Decaf Product Launch | Captures new consumption occasions and appeals to convenience-oriented younger demographics. |
| Geographic Expansion in Asia-Pacific Urban Centers | Accesses a rising middle class with growing health awareness and disposable income for premium food products. |
| Certification Management System Upgrade | Ensures compliance with diverse regional regulations and enhances brand trust among health-conscious consumers. |
Research Approach
Operator-level perspectives from roasters, food service procurement managers, decaffeination technology providers, and retail buyers anchored the qualitative base of this study. Primary interviews with these industry stakeholders were triangulated with extensive secondary research, including regulatory filings, trade association reports, and academic literature. This approach ensured a comprehensive understanding of market dynamics, validated by both top-down and bottom-up data points.
Sensitivity analysis formed the core of the forecast framework, modeling market behavior across the analysis window under various economic and regulatory scenarios. Segmentation dimensions modeled included product type, distribution channel, customer type, and packaging type, alongside the specific decaffeination process employed. Compound annual growth rates were derived from historical data trends, projected demand shifts, and anticipated technological advancements. Key forecast inputs included consumer health consciousness indices and regional regulatory enforcement levels.
Material uncertainties — shifts in green coffee bean prices, unforeseen regulatory changes, or rapid technological disruption — sit outside the modeled envelope, reflecting inherent market complexities. These forecasts reflect assumptions regarding stable macroeconomic conditions and consistent consumer preference evolution. Revision becomes warranted when significant shifts in processing technology adoption or major regulatory frameworks cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Canned Coffee Market
Coffee
Global Cafe Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Espresso Powder Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Italy Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Green Coffee Extract Market
Coffee
Caffeine Market
Coffee
Instant Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Cold Brew Coffee Pots Market