
 Dysphagia Management Market | 2026-2036
Dysphagia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Dysphagia Management Market Analysis
Medical-grade thickening agent specifications are redrawing competitive boundaries in dysphagia nutrition. Nestlé Health Science leverages its clinical nutrition heritage to sustain premium positioning across hospital formularies. Abbott Nutrition anchors its portfolio with enteral delivery systems that integrate swallowing safety protocols. Danone Nutricia differentiates through specialized texture-modified products for neurological patient populations.
Dysphagia management encompasses clinical interventions, nutritional formulations, and assistive devices designed to ensure safe swallowing and adequate hydration for patients with impaired deglutition. Thickening agents function by altering liquid rheology to slow bolus transit, typically achieving nectar-like or honey-like viscosities measured in centipoise. The primary commercial purpose centers on reducing aspiration risk while maintaining palatability and caloric delivery. Nutritional supplements occupy the deepest margin pools as patients require long-term specialized feeding. Tube feeding delivery modes represent the fastest-growing structural segment as home-based enteral nutrition expands. Texture modifiers remain mature with stable hospital procurement volumes but limited pricing flexibility.
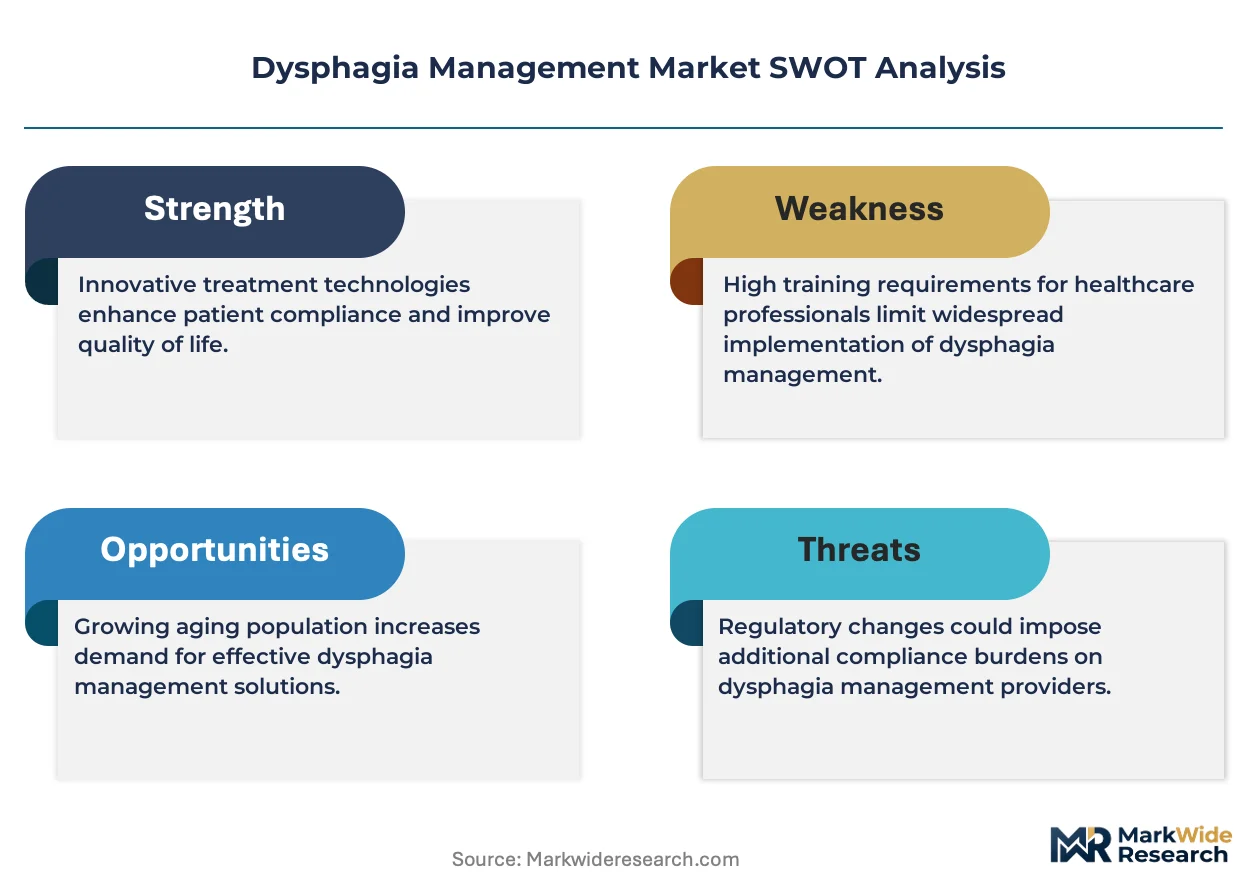
FDA medical food regulations and EMA borderline product classifications shape how thickening agents and nutritional supplements enter clinical channels. The EU F-Gas Regulation and REACH chemical safety standards constrain formulation options for certain viscosity-modifying compounds. Japan's PMDA and METI oversight of functional foods creates additional compliance layers for multinational suppliers. Stakeholders must monitor evolving reimbursement codes for home enteral nutrition across Medicare, NHS England, and Japan's long-term care insurance system to anticipate volume shifts between institutional and residential care settings.
Market Dynamics
Hospital procurement consolidation is compressing pricing power for thickening agents while simultaneously elevating technical specification requirements for viscosity stability across temperature ranges.
Growth Catalysts
- Japan's long-term care insurance expansion:METI reimbursement reforms for home enteral nutrition are shifting patient volume from institutional to residential settings, expanding addressable demand for portable thickening systems.
- EMA medical food purity standards:Tightened EFSA specifications for xanthan gum and modified starch purity are creating certification barriers that favor established clinical nutrition suppliers over commodity ingredient providers.
- Neurological patient population concentration:Parkinson's and stroke rehabilitation protocols in Germany and the United States are embedding texture-modified nutrition into standard discharge planning, institutionalizing recurring purchase patterns.
Market Restraints
- Guar gum price volatility:Indian monsoon dependency and speculative commodity trading create input cost instability for natural gum-based thickeners, compressing margin predictability for formulators.
- Single-source cellulose ether supply:Pharmaceutical-grade hydroxyethylcellulose production concentrates among three European chemical manufacturers, creating vulnerability to plant outages or REACH compliance disruptions.
- Enteral tube feeding substitution:Percutaneous endoscopic gastrostomy placement rates are rising among severe dysphagia cases, bypassing oral thickening agents entirely in favor of direct intestinal delivery.
Strategic Opportunities
- Underpenetrated home care channel in France:ANSM reimbursement pathway simplification for domiciliary thickening agents remains incomplete, leaving white space for direct-to-patient distribution models.
- AI-assisted swallowing assessment convergence:Integration of videofluoroscopic analysis software with automated viscosity recommendation engines enables personalized thickening protocols tied to individual patient biomechanics.
- PMDA functional food category expansion:Japan's regulatory framework for FOSHU-designated products is broadening to include texture-modified beverages with added nutritional claims, creating premium positioning potential.
Industry Challenges
- Speech-language pathologist workforce scarcity:Specialized deglutition assessment expertise concentrates in academic medical centers, creating bottlenecks for community hospital dysphagia program expansion.
- ISO 17025 laboratory certification timelines:Third-party validation of viscosity measurement methodologies for medical food claims requires 12-18 month accreditation cycles, delaying product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysphagia Management Market |
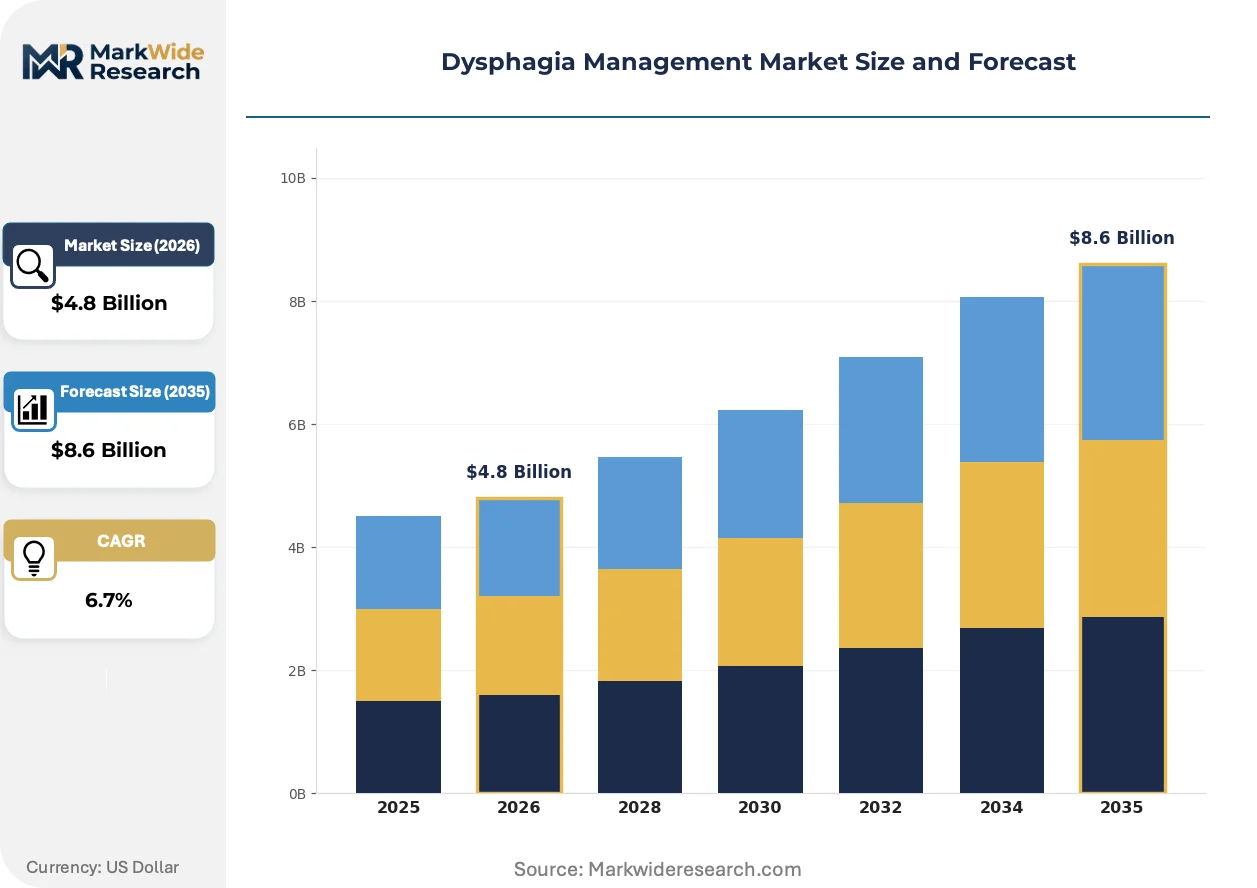
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickening Agents, Texture Modifiers, Swallowing Aids, Nutritional Supplements Delivery Mode: Oral, Enteral, Parenteral, Tube Feeding End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Application: Pediatric, Adult, Geriatric, Neurological Conditions |
| Companies Covered | Nestlé Health Science, AstraZeneca, Abbott Nutrition, Eisai Co. Ltd, Becton, Dickinson and Company, Hormel Health Labs, Danone Nutricia, Kent Precision Foods, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysphagia Management Market Emerging Trajectories
Digital health integration is reconfiguring how swallowing safety is monitored outside clinical settings, while regulatory precision around medical food classifications is sharpening competitive differentiation criteria.
Plant-based hydrocolloid blends are fragmenting the thickening agent landscape. These formulations combine locust bean gum with tapioca starch to achieve nectar-consistency viscosities without the metallic aftertaste associated with traditional cornstarch products. Home care distributors and long-term care facilities are adopting these alternatives at accelerating rates. The technology is fragmenting procurement patterns by enabling private-label positioning that bypasses established hospital formularies.
REACH microplastic restrictions are forcing reformulation of certain synthetic viscosity modifiers. The ECHA restriction proposal targeting microplastic additives in consumer and professional products is compelling suppliers to phase out specific polymer-based thickeners by 2027. Medical food manufacturers serving EU markets are accelerating natural hydrocolloid substitution programs. German and Dutch clinical nutrition suppliers are most exposed given their reliance on cellulose derivative portfolios.
Hospital-at-home programs are unbundling traditional enteral nutrition service models. Medicare's expanded reimbursement for acute-level care in residential settings is decoupling product supply from institutional purchasing contracts. Durable medical equipment suppliers are capturing thickening agent volume previously locked into hospital group purchasing organizations. The United States exhibits the most pronounced channel disruption, with Texas and Florida health systems piloting direct-to-patient logistics for texture-modified products.
Dysphagia Management Market Segmentation
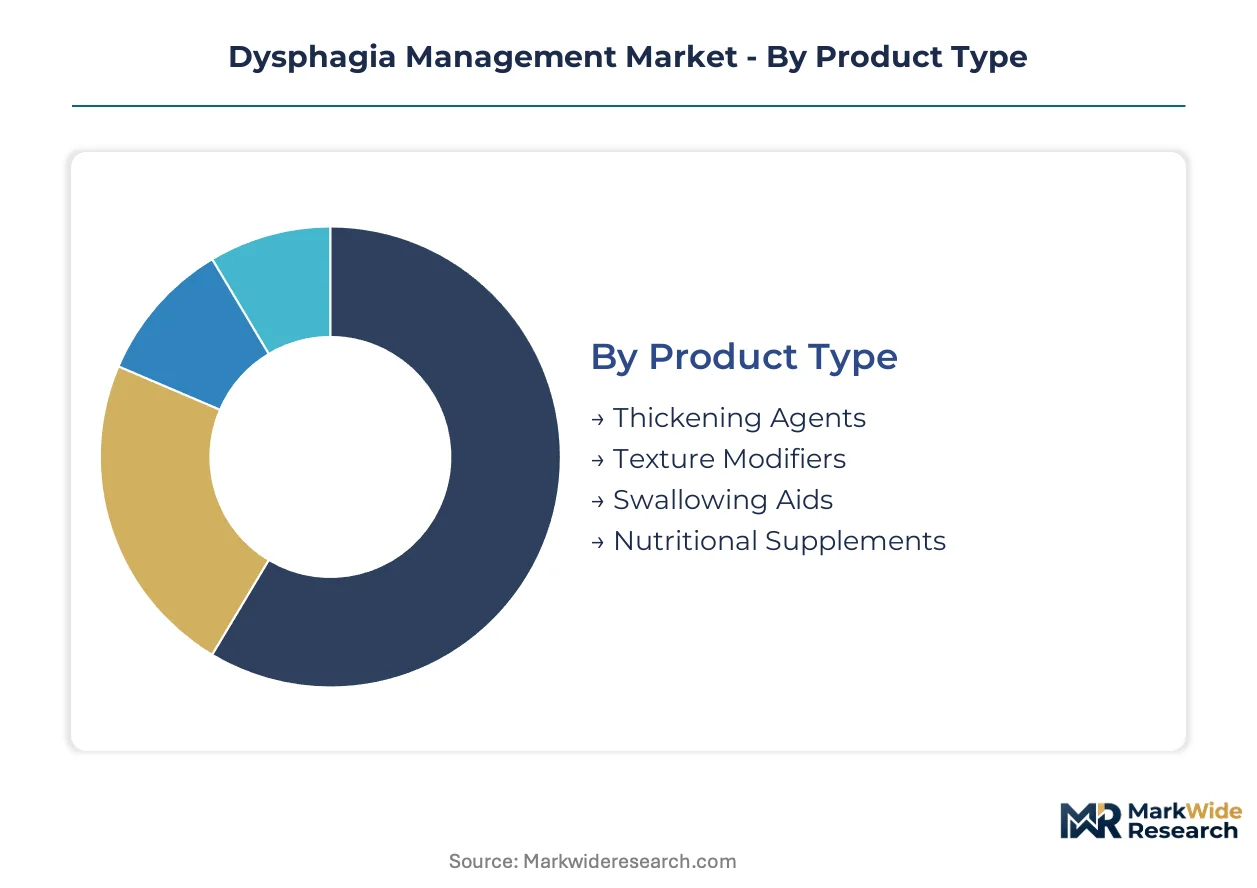
Dysphagia management products serve distinct clinical workflows, from acute hospital protocols to long-term residential care. Understanding segment boundaries reveals where procurement consolidation and regulatory scrutiny are reshaping competitive dynamics.
Product Type:
Margin pools concentrate in formulations requiring ongoing patient compliance rather than single-use devices.
- Thickening Agents:Xanthan gum and modified starch formulations alter liquid viscosity to slow bolus transit and reduce aspiration risk. Hospital procurement teams in the United States and Germany are tightening specifications for temperature-stable viscosity performance across serving conditions.
- Nutritional Supplements:Texture-modified beverages and fortified foods deliver caloric density with modified rheology for safe swallowing. Home care channels in Japan are expanding METI-reimbursed volumes as long-term care insurance shifts patients toward residential settings.
- Texture Modifiers:Pre-thickened products and instant thickening powders target institutional foodservice operations with standardized preparation protocols.
- Swallowing Aids:Positioning devices and adaptive utensils support compensatory swallowing techniques during rehabilitation therapy.
The dominant share belongs to Thickening Agents, while Nutritional Supplements are climbing the fastest as home-based care models expand.
Delivery Mode:
Volume distribution reflects the severity gradient of dysphagia conditions and corresponding intervention intensity.
- Tube Feeding:Percutaneous endoscopic gastrostomy and nasogastric delivery bypass oral intake entirely for severe aspiration risk cases. Medicare reimbursement expansion for home enteral nutrition in Texas and Florida health systems is accelerating residential volume.
- Oral:Thickened liquids and texture-modified solids maintain physiological swallowing for mild-to-moderate impairment. Speech-language pathologists in academic medical centers concentrate prescribing authority for these protocols.
- Enteral:Formula delivery via feeding tubes supports patients with functional gastrointestinal tracts but unsafe oral intake.
- Parenteral:Intravenous nutrition addresses cases where enteral access is contraindicated or insufficient.
Tube Feeding commands the largest volume commitment per patient, though Oral delivery reaches the broadest patient population.
End User:
Procurement authority fragments across institutional purchasing departments, durable medical equipment suppliers, and direct-to-patient channels.
- Hospitals:Group purchasing organizations negotiate multi-year contracts for thickening agents and enteral formulas. EMA medical food purity standards and FDA medical food regulations shape formulary inclusion criteria.
- Home Care:Durable medical equipment suppliers and specialty pharmacies manage direct-to-patient logistics for texture-modified products. ANSM reimbursement pathway simplification in France remains incomplete, constraining channel development.
- Long-term Care Facilities:Nursing homes and assisted living centers maintain standing orders for standardized thickening protocols across resident populations.
- Rehabilitation Centers:Post-acute facilities integrate texture-modified nutrition into stroke and Parkinson's discharge planning in Germany and the United States.
Hospitals retain the deepest contract value, though Home Care is expanding its share as residential care models displace institutional stays.
Application:
Patient demographics and underlying etiology determine product specification requirements and reimbursement pathways.
- Neurological Conditions:Stroke, Parkinson's disease, and amyotrophic lateral sclerosis produce progressive dysphagia requiring adaptive thickening protocols. PMDA functional food category expansion in Japan is creating premium positioning for texture-modified beverages with added nutritional claims.
- Geriatric:Age-related sarcopenia and presbyphagia drive institutional volume in aging populations across the United States, Germany, and Japan.
- Pediatric:Congenital anomalies and developmental disorders necessitate specialized formulation palatability and caloric density.
- Adult:Traumatic injury, oncology, and critical illness produce acute dysphagia requiring temporary intervention.
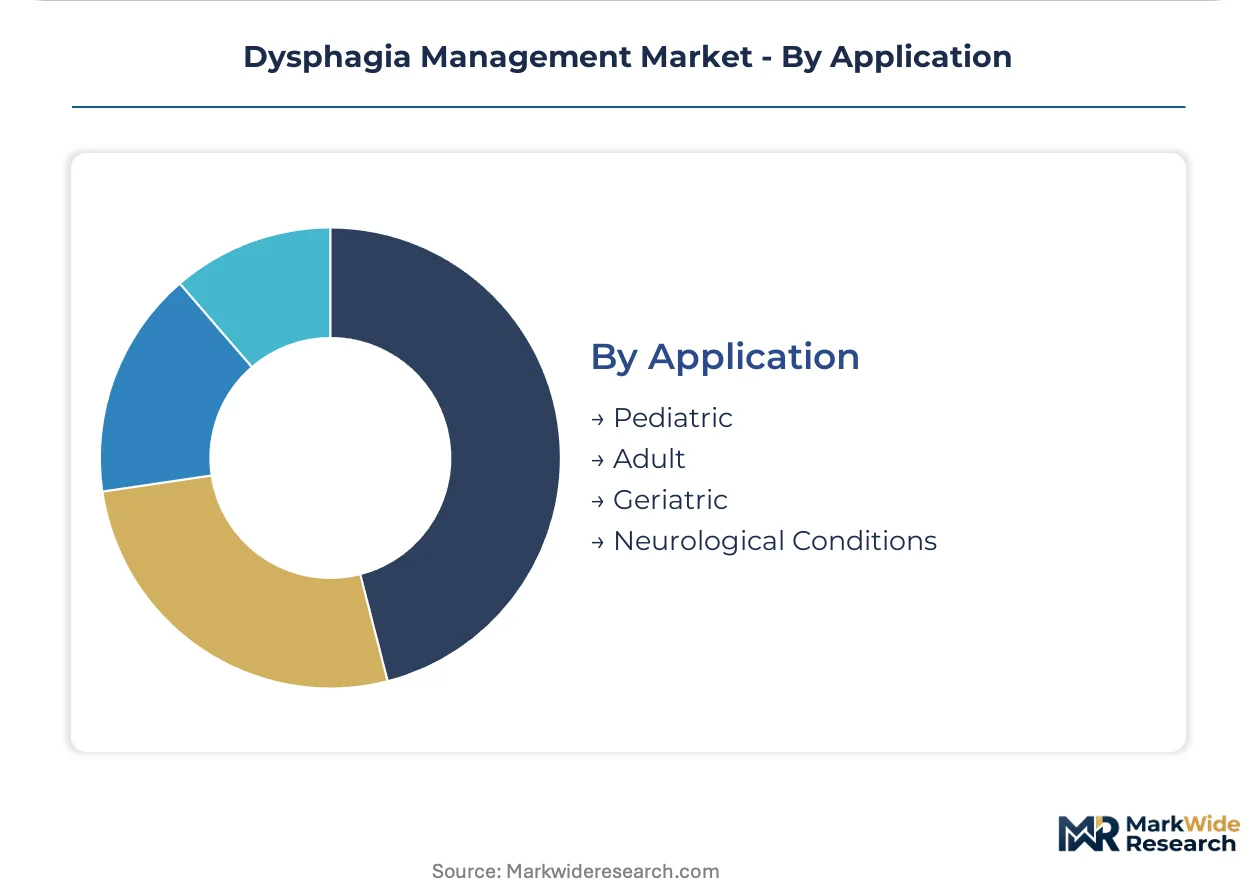
Neurological Conditions anchor clinical protocol development, while Geriatric applications are expanding most quickly with demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clinical nutrition suppliers export specialized thickening agents to hospital systems across the United States and Japan, establishing the primary trade-flow corridor for medical-grade hydrocolloids.
United States
Medicare reimbursement expansion for home enteral nutrition drives residential care volume shifts. FDA medical food regulations tighten purity specifications for xanthan gum formulations. Texas and Florida health systems pilot direct-to-patient logistics for texture-modified products, decoupling supply from institutional purchasing contracts.
Germany
Parkinson's and stroke rehabilitation protocols institutionalize texture-modified nutrition in discharge planning. EMA medical food standards and REACH chemical safety constraints reshape formulation options for cellulose derivatives. The North Rhine-Westphalia cluster hosts pharmaceutical-grade hydroxyethylcellulose production concentrated among specialized chemical manufacturers.
Japan
METI reimbursement reforms for home enteral nutrition shift patient volume from hospitals to residential settings. PMDA functional food category expansion creates premium positioning pathways for texture-modified beverages with added nutritional claims. The Kanto region around Tokyo concentrates aging demographics and long-term care insurance utilization.
France
ANSM reimbursement pathway simplification for domiciliary thickening agents remains incomplete, constraining channel development. EFSA specifications for modified starch purity create certification barriers favoring established clinical nutrition suppliers. The Île-de-France region maintains academic medical center concentration for speech-language pathologist expertise.
United Kingdom
NHS England reimbursement codes for home enteral nutrition anticipate volume shifts between institutional and residential care. EMA borderline product classifications shape how thickening agents enter clinical channels. The Greater London health economy concentrates procurement authority through group purchasing organizations.
Dysphagia Management Market Vendor Landscape
Listed leaders compete with private specialists across hospital formulary access and home care channel penetration. The vendor base concentrates around clinical nutrition heritage players and medical device specialists, with tiered positioning across premium certified and standard commodity offerings. Three archetypes dominate: diversified nutrition conglomerates with hospital GPO relationships, specialized dysphagia product houses with SLP prescriber networks, and medical device suppliers with enteral delivery integration. Competitive moves center on M&A for regional formulary expansion and strategic partnerships for AI-assisted swallowing assessment convergence.
Within the diversified nutrition tier, Nestlé Health Science and Abbott Nutrition exemplify archetypes leveraging clinical nutrition heritage for premium hospital positioning. Danone Nutricia occupies a specialist position focused on neurological patient populations. Among medical device-integrated players, Becton, Dickinson and Company represents the enteral delivery systems segment. Kent Precision Foods sits within the private specialist tier serving institutional foodservice operations with standardized preparation protocols.
| Leading Market Players |
|---|
| Nestlé Health Science |
| AstraZeneca |
| Abbott Nutrition |
| Eisai Co. Ltd |
| Becton, Dickinson and Company |
| Hormel Health Labs |
| Danone Nutricia |
| Kent Precision Foods |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Plant-based hydrocolloid substitution for synthetic cellulose derivatives is redrawing procurement geography and compressing margin structures for European formulators exposed to REACH microplastic restrictions. Buyers in Germany and the Netherlands face reformulation costs that favor natural gum suppliers in India and Southeast Asia, while hospital group purchasing organizations in the United States exploit this supplier fragmentation to extract price concessions on temperature-stable viscosity formulations.
Pricing Analysis
Next-generation AI-assisted viscosity recommendation engines command substantial premiums over conventional protocol-based systems, while legacy cornstarch thickeners face commoditization pressure. Three-tier pricing structure across premium certified, standard medical-grade, and economy food-service levels separates hospital formulary products from long-term care bulk procurement. Cost compression in the standard tier is intensifying because EMA purity certification timelines stretch 12-18 months, constraining qualified supplier pools. Home care distributors exhibit the highest price sensitivity due to Medicare reimbursement caps, while academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Indian monsoon-dependent guar gum harvests create a chokepoint that propagates volatility through natural thickener pricing across European and North American manufacturing. Pharmaceutical-grade xanthan gum production concentrates in China, Austria, and the United States, with modified starch processing anchored in Germany and Thailand. Formulation chemistry draws from locust bean gum sourced in Mediterranean countries, tapioca starch from Southeast Asia, and cellulose ethers from specialized European chemical manufacturers. Single-source vulnerability pervades pharmaceutical-grade hydroxyethylcellulose, where three European producers control capacity. Distribution runs through hospital group purchasing organizations in the United States, regional clinical nutrition distributors in Europe, and long-term care insurance channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dysphagia management operates as a regulatory-moat market where EMA medical food purity standards and FDA certification pathways create switching costs that entrench incumbent clinical nutrition suppliers. Network effects concentrate in hospital formulary relationships and speech-language pathologist prescriber networks, reinforcing established positions.
For Market Incumbents: Fortify hospital formulary lock-in by accelerating ISO 17025 laboratory certification for next-generation plant-based hydrocolloid blends before REACH microplastic restrictions fully phase out synthetic alternatives. Deepen backward integration into Indian guar gum supply through long-term offtake agreements that neutralize monsoon-driven price volatility threatening margin predictability.
For New Entrants and Emerging Players: PMDA functional food fast-track certification in Japan opens white-space positioning for texture-modified beverages with added nutritional claims, bypassing entrenched hospital procurement channels entirely. Target France's underpenetrated home care channel where ANSM reimbursement simplification remains incomplete, deploying direct-to-patient distribution models that decouple from institutional group purchasing organizations.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors diversified clinical nutrition conglomerates with existing EMA and FDA certification infrastructure over commodity ingredient suppliers facing compliance barriers. Long-term viability hinges on home care channel capture as residential care models displace institutional stays. Acquisition targets should demonstrate established PMDA or EMA medical food approvals with underutilized capacity. Watch METI reimbursement reform velocity in Japan as the signal indicating whether home enteral nutrition volume shifts accelerate or stall.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Medical Food Certification Investment | Establishes formulary access barriers that exclude commodity ingredient competitors from hospital procurement. |
| Backward Integration into Natural Gum Supply | Captures Indian and Southeast Asian hydrocolloid sources to stabilize input costs against monsoon volatility. |
| AI-Assisted Swallowing Assessment Partnership | Integrates videofluoroscopic analysis with automated viscosity engines for personalized protocol differentiation. |
| PMDA Functional Food Category Entry | Unlocks premium positioning in Japan's expanding texture-modified beverage market with nutritional claims. |
| Direct-to-Patient Distribution Buildout | Decouples product volume from hospital group purchasing organizations in Medicare-expanded states. |
Methodological Framework
A spread of perspectives from hospital procurement managers, speech-language pathologists, clinical nutrition formulators, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with GPO contract administrators and biomedical engineers alongside secondary validation through FDA medical food filings, EMA borderline product classifications, and CMS Medicare reimbursement code databases. Bottom-up patient volume modeling and top-down clinical nutrition market sizing were triangulated to establish segment boundaries.
Segmentation dimensions modeled include product type, delivery mode, end user, and application severity across the projection horizon. CAGRs were derived from patient population epidemiology, reimbursement policy trajectories, and technology substitution curves. Forecast inputs incorporated METI long-term care insurance utilization data, ECHA REACH compliance timelines, and ISO 17025 laboratory certification pipeline status.
Underlying assumptions cover regulatory pathway stability, raw material supply continuity, and reimbursement code maintenance, with deviation risk concentrated in Indian monsoon patterns affecting guar gum availability and EMA purity standard enforcement intensity. Practitioners should keep alternative scenarios live as REACH microplastic restriction implementation and PMDA functional food category expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Global IVF Devices Market
Medical Devices
APAC AMH Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Global Robotic Endoscopy Devices Market