
 United Kingdom Hospitality Market | 2026-2036
United Kingdom Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Hospitality Market Insights
Unbundled room amenities and modular service tiers is shifting how UK hospitality buyers configure stays, stripping traditional packages into selectable components. Whitbread Group leverages its Premier Inn scale to anchor budget-standard consistency across provincial England. InterContinental Hotels Group differentiates through loyalty-integrated direct booking channels that reduce third-party commission exposure. Travelodge competes on asset-light expansion, prioritizing roadside and suburban locations with standardized build costs.
United Kingdom hospitality encompasses lodging, food service, event hosting, and travel coordination delivered through fixed and transient physical assets with service intensity measured by RevPAR, occupancy rates, and food cost ratios. Accommodation commands the largest revenue pool, though food and beverage operations capture disproportionate margin where local sourcing and kitchen labor efficiency are optimized. Event management represents the fastest-expanding segment as corporate retreat demand and festival programming concentrate in regional cities beyond London. Budget and mid-range price tiers dominate room-night volume, while luxury properties extract premium rates through experience bundling and concierge depth.
UK Hospitality Limited, the industry's self-regulatory standards body, works alongside the Food Standards Agency and Health and Safety Executive to enforce hygiene, fire safety, and allergen disclosure protocols that shape operational compliance costs. The UK government's Environment Act targets and local authority licensing regimes constrain site expansion and refurbishment timelines, particularly in conservation areas. Stakeholders must monitor evolving short-term rental regulations in Edinburgh, Belfast, and Manchester, where planning authorities are tightening conversion rules that affect competitive supply dynamics.
Market Dynamics
The UK Environment Act's waste reduction mandates are compressing operating margins across food service operations while accelerating capital deployment into circular supply infrastructure. Serviced apartment formats are capturing extended-stay business travelers who previously filled traditional hotel inventory.
Growth Catalysts
- Extended-stay serviced apartments:Business travelers are extending average length of stay in apartment-style inventory, pulling demand from conventional hotel room stock.
- Corporate retreat programming:Regional cities outside Greater London are capturing festival and corporate event demand as planners seek lower venue costs.
- UK Environment Act compliance infrastructure:Food waste tracking systems and circular packaging investments are qualifying operators for preferential licensing timelines.
Market Restraints
- Conservation area planning friction:Local authority licensing regimes in Edinburgh, Belfast, and Manchester are tightening conversion rules that delay site expansion timelines.
- Kitchen labor cost volatility:Food and beverage operations face margin compression where local sourcing premiums intersect with skilled chef wage inflation.
- Short-term rental supply substitution:Unregulated accommodation platforms in Greater London's premium corridor are absorbing price-sensitive leisure demand.
Strategic Opportunities
- Modular service tier unbundling:Selectable amenity configurations are enabling budget and mid-range operators to capture premium rate tiers on specific nights.
- Roadside and suburban location gaps:Standardized build-cost roadside properties in provincial England remain underpenetrated relative to corridor traffic density.
- Loyalty-integrated direct booking channels:Commission reduction through owned digital platforms is expanding net revenue per available room for scaled operators.
Industry Challenges
- Fire safety and allergen disclosure compliance:UK Hospitality Limited protocols alongside Food Standards Agency enforcement are extending refurbishment certification timelines.
- RevPAR optimization across fragmented demand:Operators must balance occupancy rate targets against food cost ratio discipline in volatile corporate travel cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Hospitality Market |
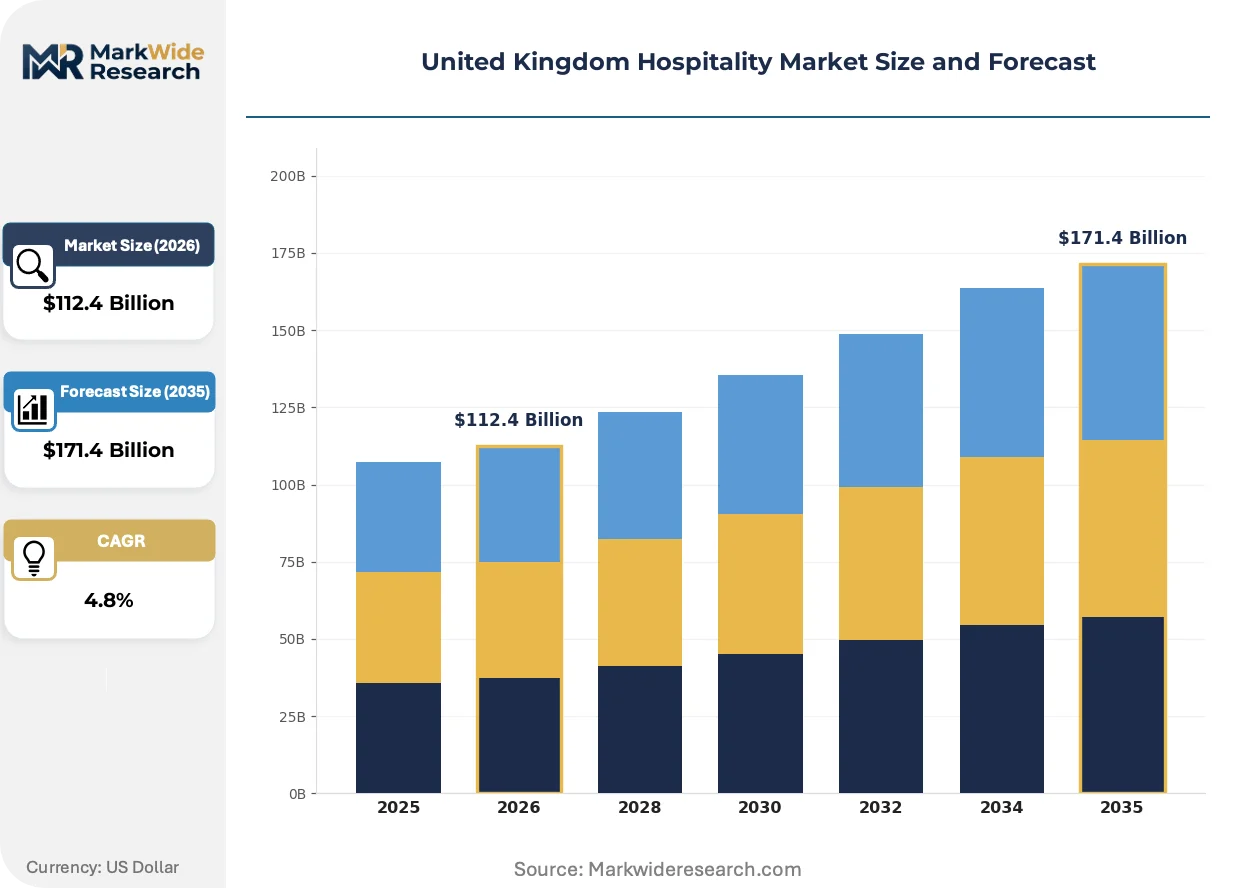
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Food & Beverage, Event Management, Travel Services Customer Type: Leisure Travelers, Business Travelers, Corporate Clients, Event Organizers Price Tier: Luxury, Mid-Range, Budget, Economy Delivery Model: Online Booking, Direct Sales, Travel Agencies, Third-Party Platforms |
| Companies Covered | Whitbread Group, InterContinental Hotels Group, Travelodge, Accor SA, Marriott International, Hilton Worldwide, Best Western Hotels and Resorts, Britannia Hotels, Wyndham Hotels and Resorts, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Hospitality Market Trends and Innovations
Digital check-in infrastructure and predictive revenue management systems are compressing front-desk labor models while expanding dynamic pricing granularity. Property technology investments are shifting from guest-facing amenities to back-of-house automation.
Smart building energy management systems are rewriting how mid-scale properties balance carbon reporting obligations against utility cost control. Whitbread Group and Travelodge are deploying sensor-based HVAC optimization across provincial England portfolios. The structural consequence is compressing the payback period for green refurbishment capex.
The UK Environment Act's mandatory food waste tracking is forcing kitchen operations to adopt inventory prediction software. Pubs and restaurant chains must submit quarterly waste audits to local authorities. Full-service hotels with complex banquet operations face the steepest compliance cost escalation.
Extended-stay corporate bookings are fragmenting traditional Monday-Thursday business travel patterns. Procurement teams now negotiate apartment-format blocks through serviced accommodation platforms rather than hotel sales desks. This shift is most visible in Greater London's corporate corridor and Manchester's media district.
United Kingdom Hospitality Market Segmentation
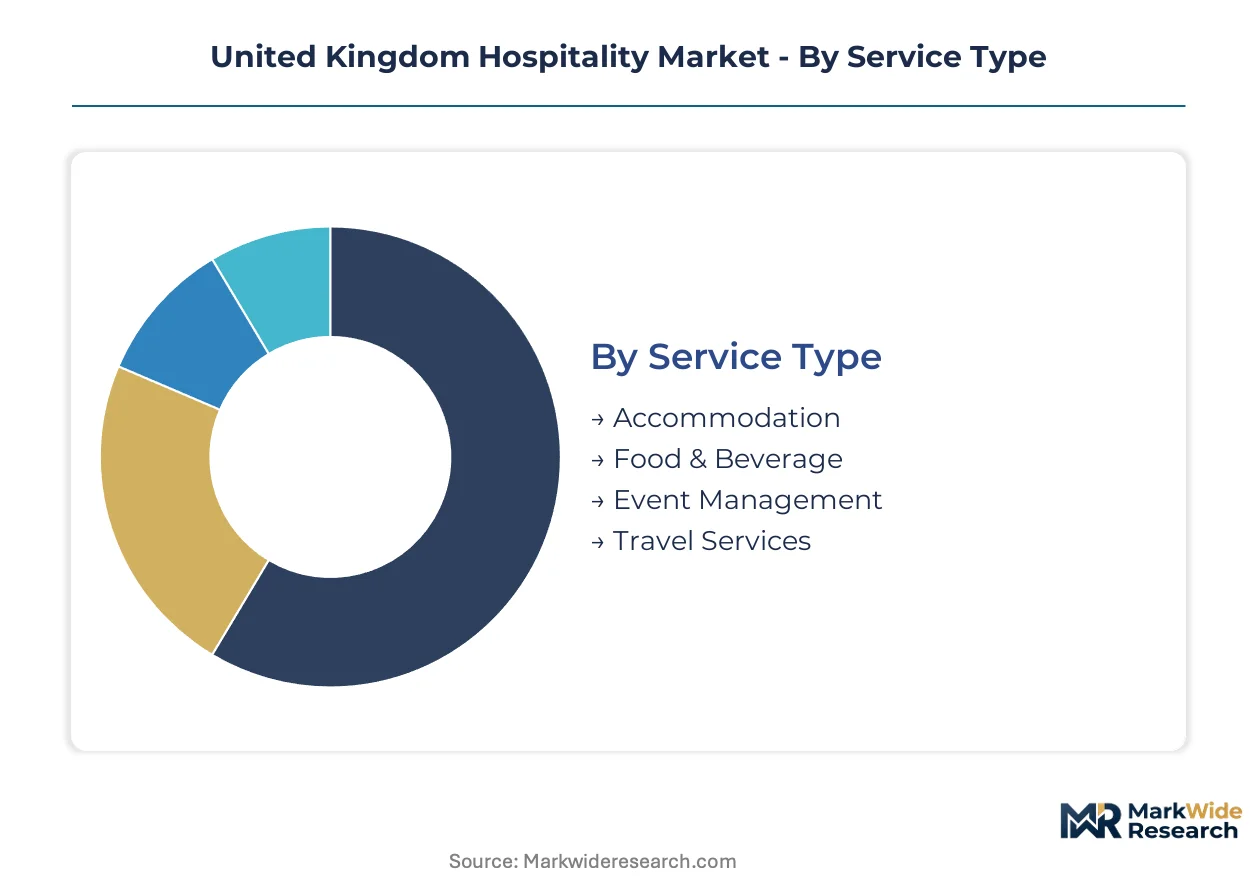
Segmentation in UK hospitality reveals how operators must balance standardized efficiency against tailored service configurations. Each category exposes different pressure points between cost control and revenue capture across Greater London's premium corridor and provincial England's roadside networks.
Service Type:
Customization intensity varies sharply across this category, from rigidly standardized accommodation to highly bespoke event programming.
- Accommodation:Physical room inventory spanning serviced apartments, hotels, and short-term rental formats. Demand concentrates in Greater London's corporate corridor where extended-stay business travelers are displacing traditional hotel bookings.
- Food & Beverage:Kitchen operations, banquet services, and standalone restaurant concepts governed by Food Standards Agency allergen protocols. Margin pressure intensifies where local sourcing premiums intersect with chef wage inflation in Edinburgh and Manchester conservation areas.
- Event Management:Corporate retreats and festival programming.
- Travel Services:Coordination and itinerary planning functions.
Leading the category by volume: Accommodation. Expanding most quickly: Event Management.
Customer Type:
Procurement authority and booking lead times create distinct service requirements across this category.
- Leisure Travelers:Individual and family demand segments with high price sensitivity and platform-driven discovery patterns.
- Business Travelers:Road-warrior and extended-stay segments with corporate travel policy constraints. Procurement teams in Manchester's media district now negotiate apartment-format blocks through serviced accommodation platforms rather than hotel sales desks.
- Corporate Clients:Volume-contracted accounts with negotiated rate tiers and loyalty program integration. Direct booking channel investments by scaled operators target this segment to reduce third-party commission exposure.
- Event Organizers:Planners sourcing regional venues outside Greater London for cost arbitrage on festival and retreat programming.
Dominant by spend: Corporate Clients. Gaining share fastest: Event Organizers.
Price Tier:
Asset intensity and labor depth separate operational models across this category.
- Luxury:Concierge-heavy properties with experience bundling and premium rate extraction through amenity depth. RevPAR optimization depends on occupancy rate discipline against food cost ratio volatility in volatile corporate travel cycles.
- Mid-Range:Standardized service tiers with modular amenity configurations. Whitbread Group's Premier Inn scale anchors consistency across provincial England through repeatable build costs and brand recognition.
- Budget:Limited-service roadside and suburban locations. Travelodge competes on asset-light expansion with standardized construction timelines and corridor traffic density targeting.
- Economy:Minimal-service formats with stripped amenity packages and price-driven positioning.
Highest room-night volume: Budget and Mid-Range combined. Steepest margin pressure: Economy.
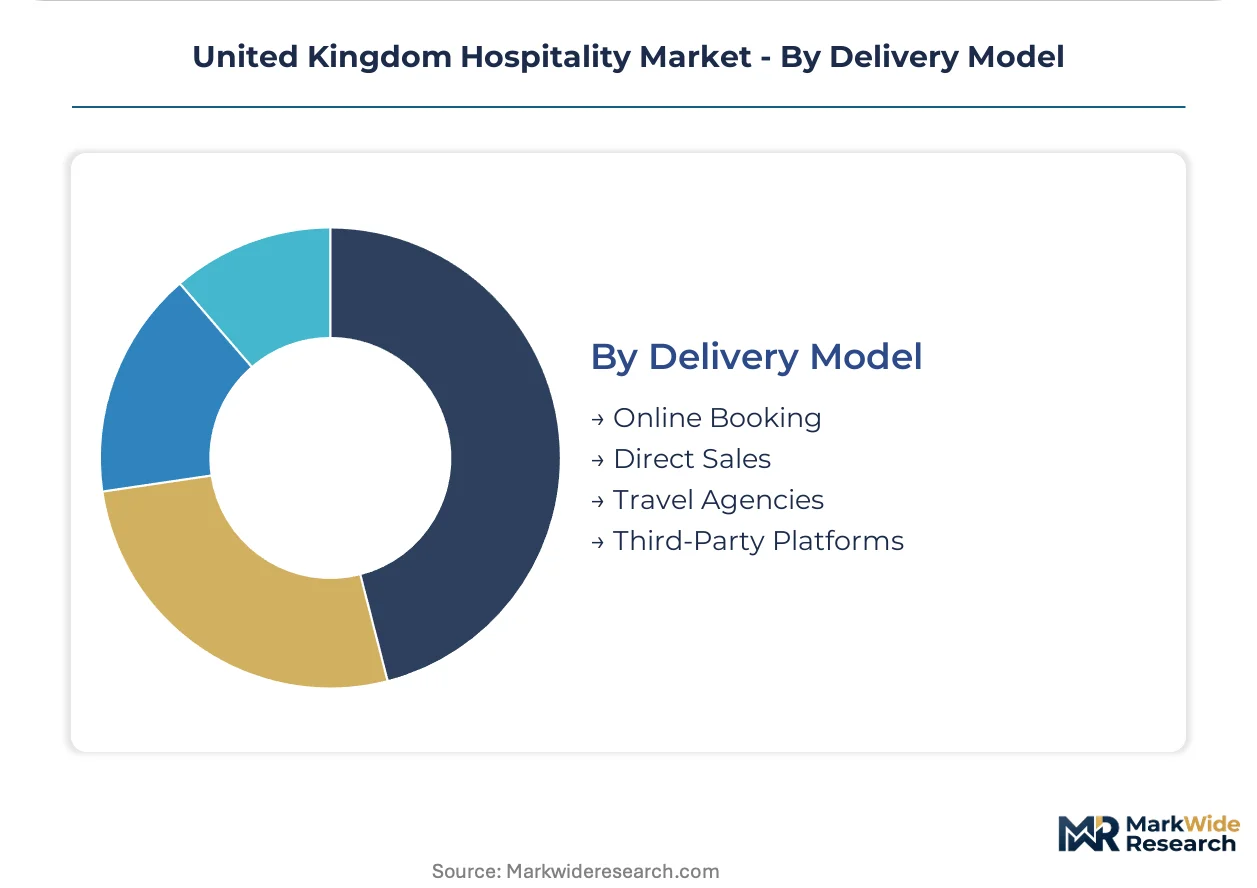
Delivery Model:
Channel ownership and commission structures define competitive positioning across this category.
- Online Booking:Proprietary digital platforms with loyalty integration. InterContinental Hotels Group differentiates through owned channels that expand net revenue per available room.
- Direct Sales:Corporate contracting and group negotiation functions with relationship-based account management.
- Travel Agencies:Traditional intermediary networks with negotiated override commissions.
- Third-Party Platforms:Aggregator and metasearch channels with 15-25% commission exposure. Unregulated short-term rental supply in Greater London's premium corridor absorbs price-sensitive leisure demand through this channel.
Largest transaction volume: Third-Party Platforms. Fastest channel shift: Online Booking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK hospitality sector concentrates supply in Greater London while consumption disperses across provincial England, Scotland, and Wales. Regional divergence shapes investment priorities and regulatory compliance burdens.
Greater London
Corporate corridor demand drives serviced apartment absorption and premium accommodation rates. The Environment Agency enforces waste reduction mandates that reshape food service operations in Westminster and Canary Wharf clusters. Extended-stay business travelers now displace traditional hotel bookings in the Square Mile.
North England
Manchester's media district and Leeds corporate hubs capture festival programming and retreat demand. Local authority licensing regimes in Manchester tighten conversion rules that delay site expansion timelines. Whitbread Group anchors budget-standard consistency across Yorkshire and Lancashire roadside networks.
Scotland
Edinburgh's conservation area planning friction constrains refurbishment certification timelines for historic properties. The Food Standards Agency enforces allergen disclosure protocols that extend kitchen compliance costs. Festival demand concentrates in Glasgow's event venues as planners seek cost arbitrage.
Wales
Coastal leisure corridors and Cardiff corporate accounts generate seasonal occupancy volatility. Welsh Government tourism infrastructure programs target standardized build-cost properties in underpenetrated roadside locations. Travelodge competes on asset-light expansion in suburban Cardiff and Swansea.
Northern Ireland
Belfast's tightening short-term rental regulations reshape competitive supply dynamics in the city center. Health and Safety Executive fire safety protocols extend refurbishment timelines for heritage properties. Tourism Northern Ireland programs concentrate demand in Belfast's premium accommodation corridor.
United Kingdom Hospitality Market Competitive Landscape
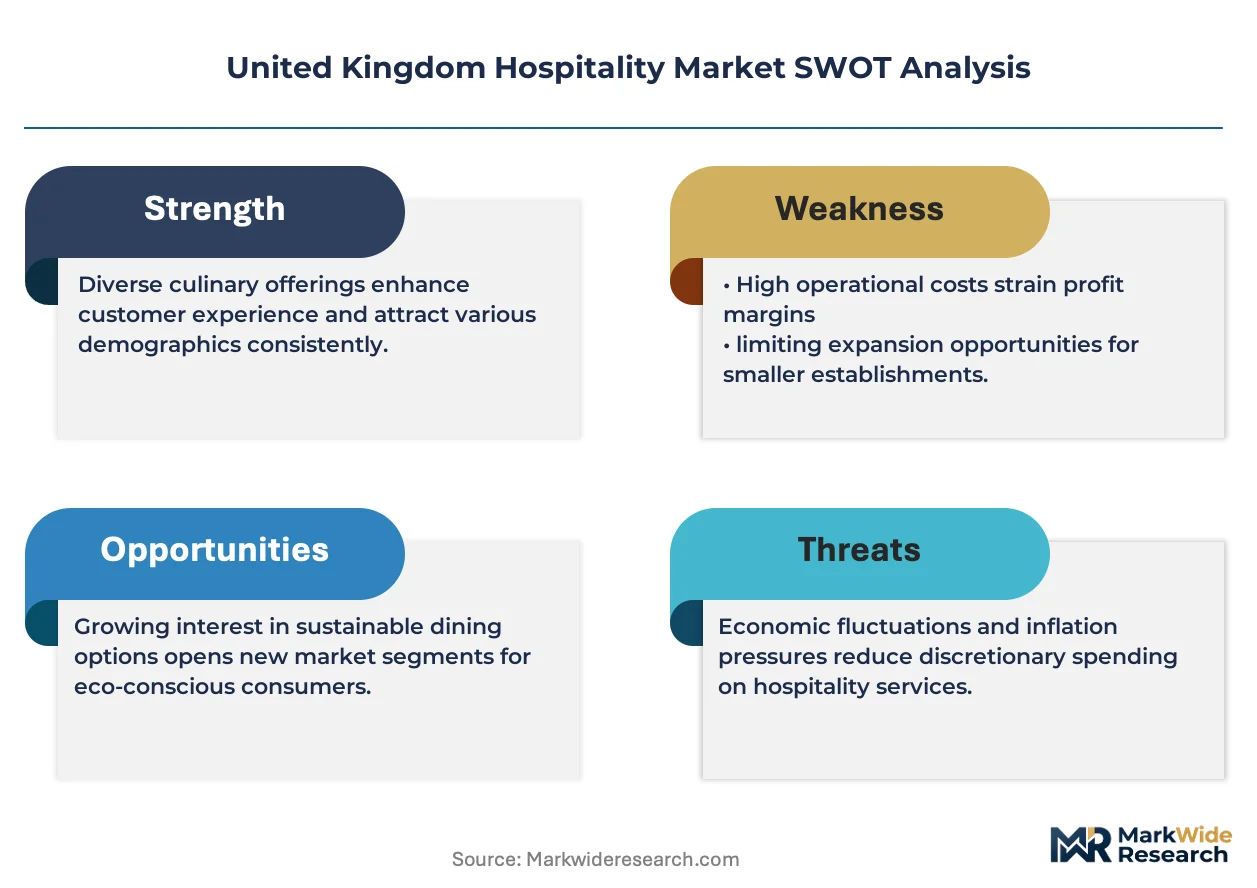
The competitive structure tilts toward scaled budget-midrange operators with repeatable build costs and brand recognition. Three archetypes dominate: national-scale budget chains with standardized construction timelines, mid-range loyalty-integrated platforms reducing third-party commission exposure, and global luxury operators extracting premium through experience bundling. Dominant competitive moves include modular service tier unbundling to capture rate premiums on specific nights, and loyalty-integrated direct booking channel investments to expand net revenue per available room.
Among UK-based operators, Whitbread Group occupies a position exemplifying scale-driven budget-standard consistency across provincial England. InterContinental Hotels Group represents the loyalty-integrated archetype with owned digital platforms. Travelodge anchors the asset-light expansion model targeting roadside and suburban gaps with standardized build costs.
| Leading Market Players |
|---|
| Whitbread Group |
| InterContinental Hotels Group |
| Travelodge |
| Accor SA |
| Marriott International |
| Hilton Worldwide |
| Best Western Hotels and Resorts |
| Britannia Hotels |
| Wyndham Hotels and Resorts |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap hotel groups across provincial England anchor supply discipline through generational ownership horizons that resist short-term rate cutting. Their patient capital structure buffers pricing power against private-equity-rolled-up competitors chasing quarterly yield, while concentrated site ownership in conservation areas constrains competitive entry.
Pricing Analysis
Margin tightening in budget tiers reflects Travelodge's standardized build-cost expansion across roadside corridors. Three-tier pricing structure across premium, standard, and economy levels dominates accommodation, with differentiation driven by loyalty program depth and direct booking channel ownership. Cost compression accelerates as unregulated short-term rental platforms absorb price-sensitive leisure demand in Greater London. Corporate clients exhibit lowest price sensitivity through negotiated volume contracts, while individual leisure travelers drive platform-driven rate discovery.
Supply Chain Analysis
Dual-sourcing requirements for food and beverage operations mandate multi-supplier qualification across UK produce networks and European protein supply chains. Geographic supply concentration centers on domestic agricultural regions, Dutch horticultural hubs, and Irish dairy corridors. Raw material dependencies span fresh produce, sustainable packaging substrates, and energy-efficient kitchen equipment. Single-source vulnerability intensifies where Brexit customs friction intersects with just-in-time inventory models. Distribution runs through regional wholesale networks into property-level preparation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics intensify as scaled operators pursue captive control over direct booking channels to capture commission savings. Backward integration into loyalty platform technology represents the decisive upstream lever separating margin leaders from followers.
For Market Incumbents: To counter unregulated short-term rental supply substitution in Greater London's premium corridor, Whitbread Group and InterContinental Hotels Group must deepen proprietary channel investments while accelerating modular service tier unbundling. Certification investment in UK Hospitality Limited fire safety protocols extends competitive moats against asset-light entrants. Capacity addition in underpenetrated provincial England roadside locations captures corridor traffic density. For New Entrants and Emerging Players: The mid-range price-point gap between Premier Inn's standardized consistency and Travelodge's stripped-back economy positioning offers white-space entry. Regional cities outside Greater London present the most penetrable geography where festival programming demand outpaces branded supply. Serviced apartment format specialization targets extended-stay corporate procurement teams in Manchester's media district. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light roadside specialists in Wales and Northern Ireland where tourism infrastructure programs subsidize standardized build costs. Long-term viability across the next decade hinges on circular supply infrastructure compliance with UK Environment Act mandates. Watch for tightening short-term rental regulations in Edinburgh and Belfast as inflection signals favoring licensed hotel inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Loyalty Platform Integration | Owned digital channels reduce third-party commission exposure for scaled operators like InterContinental Hotels Group. |
| Modular Service Tier Unbundling | Selectable amenity configurations capture premium rate tiers on high-demand nights across Whitbread Group's Premier Inn portfolio. |
| Circular Supply Infrastructure | Food waste tracking systems qualify operators for preferential licensing timelines under UK Environment Agency mandates. |
| Roadside Location Expansion | Standardized build-cost properties target underpenetrated corridor traffic density in provincial England and Wales. |
| Serviced Apartment Format Development | Apartment-style inventory captures extended-stay business travelers displacing traditional hotel bookings in Greater London. |
Research Methodology
Company filings, UK Hospitality Limited regulatory submissions, and Environment Agency waste audit data formed the secondary backbone. Primary interviews with hotel operations directors, procurement leads at corporate travel management companies, and local authority licensing officers validated demand patterns. Food Standards Agency allergen protocol documentation and Health and Safety Executive fire safety inspection records supplemented supply-side intelligence. Bottom-up property-level revenue analysis and top-down sector expenditure estimates enabled triangulation across Greater London and provincial England clusters.
Historical trendline analysis tracked RevPAR trajectories and occupancy rate patterns across budget, mid-range, and luxury tiers. The analytical framework modeled segmentation dimensions spanning service type, customer archetype, price tier, and delivery channel throughout the forecast period. CAGRs derived from weighted average growth assumptions across extended-stay corporate demand, festival programming expansion, and compliance-driven capital deployment. Industry-specific inputs incorporated serviced apartment absorption rates and circular packaging investment cycles.
Underlying measurement precision varies by segment; accommodation and food service operations carry tighter precision than event management forecasting. Forecasts reflect assumptions around corporate travel policy stability and short-term rental regulatory tightening. A model refresh is warranted upon material change in UK Environment Act enforcement intensity or local authority planning regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Youth Summer Camp Market
Accommodation
United States Online Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
France Online Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
India Student Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Switzerland Hospitality Market
Accommodation
Movie Theaters Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Croatia Hospitality Market
Accommodation
India Online Accommodation Market
Accommodation
Extended Stay Hotel Market
Accommodation
Alternative Accommodation Market