
 Switzerland Hospitality Market | 2026-2036
Switzerland Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Hospitality Market Insights
The capital-intensity gap between heritage palace hotels and modular alpine lodges is collapsing as both segments chase the same high-yield wellness traveler. SV Group leverages its integrated food-service and facility-management platform to control operating costs across multiple cantons. Bürgenstock Collection anchors its competitive position through lakeside real estate and medical-spa certification. Accor SA extends its reach via franchise-light models that reduce balance-sheet exposure in Swiss franc-denominated markets.
Switzerland hospitality encompasses lodging, food service, event coordination, and travel facilitation delivered through fixed and seasonal assets designed for guest occupancy cycles exceeding four hours. Properties must meet cantonal fire-safety, noise, and energy-efficiency codes while maintaining operational readiness across variable alpine seasons. Accommodations and Food & Beverage together occupy the core revenue pool, though Wellness Retreats within Activity Type are capturing disproportionate margin expansion as travelers extend average length of stay. Business Travelers within Customer Type face structural pressure from hybrid work norms, while Vacation Rentals under Accommodation Type are fragmenting pricing power in non-peak weeks.
Swissmedic oversees spa-medical claims and therapeutic service standards, while cantonal energy offices enforce Minergie building certifications that raise retrofit costs for pre-1990 structures. The Swiss Hotel Association's quality grading system shapes rate premiums and online visibility, effectively gatekeeping market access for unaffiliated properties. Stakeholders must decide whether to absorb certification costs for medical-grade wellness positioning or compete on volume through standardized urban inventory.
Market Dynamics
The Switzerland hospitality sector is experiencing a structural compression between heritage asset appreciation and modular construction economics, as both segments pursue identical wellness-oriented traveler cohorts with divergent capital structures.
Growth Catalysts
- Minergie certification mandates:Cantonal energy offices in Zurich and Vaud now require building envelope standards that favor new construction over retrofit, accelerating greenfield lodge development in Graubünden.
- Medical-spa service integration:Swissmedic's clarified therapeutic claims framework allows properties to bill wellness procedures through supplemental health insurance channels, expanding addressable guest spend.
- Alpine corridor demand clustering:Lake Geneva's year-round accessibility and Zermatt's rail-only access model concentrate high-yield visitors in geographies with constrained room supply.
Market Restraints
- Swiss franc denomination risk:Revenue streams in CHF face purchasing power erosion for euro and dollar-denominated source markets, compressing real yields for international operators.
- Heritage structure retrofit costs:Pre-1990 palace properties in Lucerne and Interlaken face Minergie-P compliance expenses exceeding 40% of replacement value for thermal envelope upgrades.
- Seasonal labor pool fragmentation:Jura and Ticino cantons lack sufficient hospitality-trained workforce to match peak winter and summer demand surges, forcing wage premiums or service reductions.
Strategic Opportunities
- Ticino underdevelopment gap:Mediterranean-climate lodging inventory south of the Alps remains below demand from German and Benelux retirees seeking winter sun alternatives to Spanish coasts.
- Telemedicine-spa convergence:Remote diagnostic partnerships with Zurich and Basel university hospitals enable properties to offer pre-arrival health screening and personalized regimen design.
- Rail-accessible micro-lodges:Swiss Federal Railways' expanded regional line electrification opens 800-1200 meter elevation sites previously unreachable for daily service staff.
Industry Challenges
- Cross-canton licensing complexity:Therapeutic practitioner credentials valid in Bern require separate cantonal registration in Valais, fragmenting spa staffing flexibility.
- Legacy PMS integration friction:Family-owned properties in Appenzell and Uri operate on 1990s-era property management systems that resist cloud-based channel manager connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Hospitality Market |
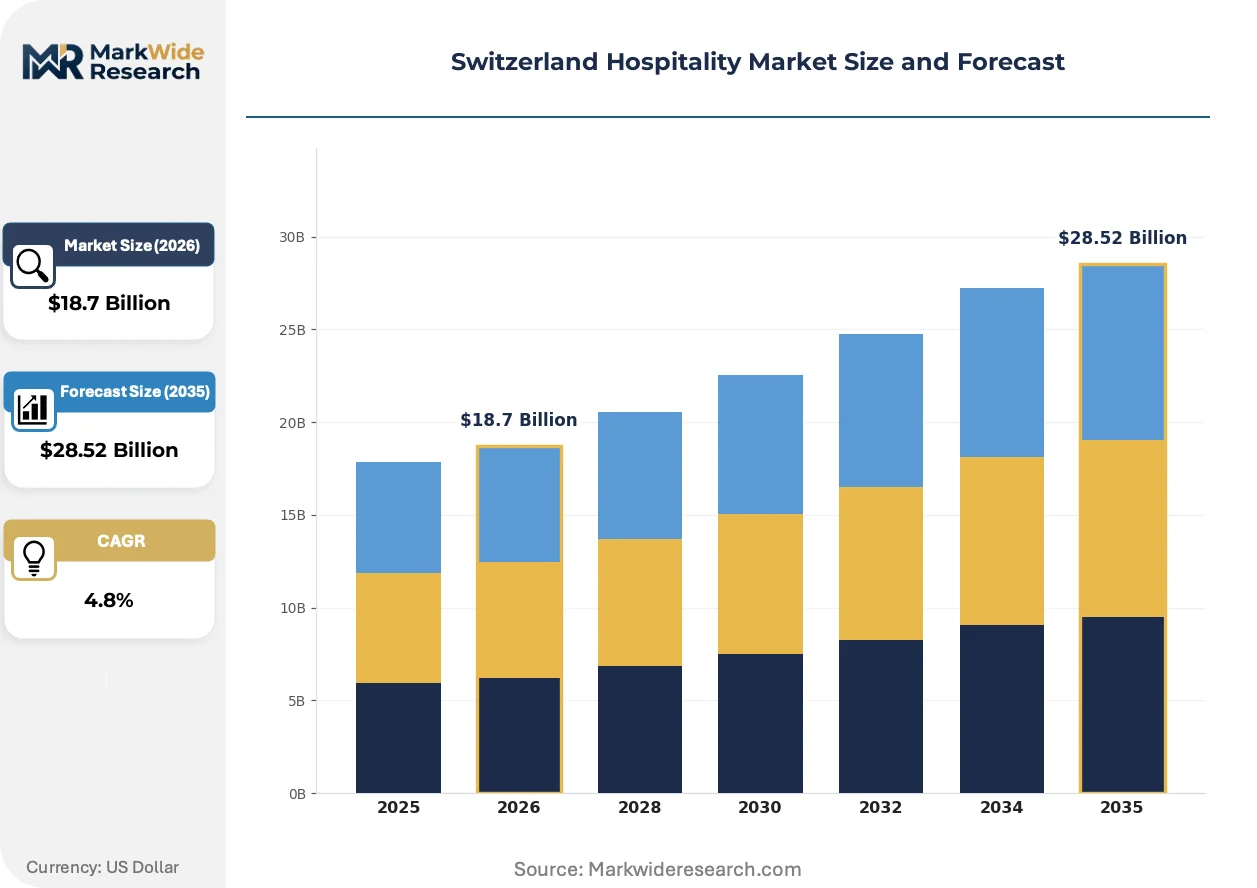
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodations, Food & Beverage, Event Management, Travel Services Customer Type: Leisure Travelers, Business Travelers, Group Bookings, Local Residents Accommodation Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfasts Activity Type: Adventure Tourism, Culinary Experiences, Wellness Retreats, Cultural Explorations |
| Companies Covered | SV Group, Sorell Hotels, MRH Switzerland AG, Bürgenstock Collection, Swiss Deluxe Hotels, Andermatt Swiss Alps AG, Accor SA, Marriott International, InterContinental Hotels Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Hospitality Market Trends and Innovations
Digital distribution platforms and building-integrated wellness systems are restructuring how Swiss properties acquire guests and deliver services, compressing traditional intermediaries while elevating certification-driven rate premiums.
Smart room automation using IoT-enabled climate and lighting controls is fragmenting the traditional front-of-house staffing model. Mid-scale properties in Basel and Lausanne deploy sensor networks that adjust room conditions pre-arrival based on guest biometrics from wearable devices. This capability is fragmenting competitive differentiation between full-service and limited-service segments, as technology cost curves flatten.
Swissmedic's 2023 clarification of spa-medical advertising standards tightens therapeutic claim substantiation requirements. Properties must now maintain clinical trial documentation or physician oversight for procedures marketed as "medical wellness." Lake Geneva corridor operators have responded by partnering with Hôpitaux Universitaires de Genève for credentialing, while smaller Graubünden lodges retreat to "wellness" terminology without medical positioning.
Guest booking behavior is compressing advance reservation windows from 90-day averages toward 21-day horizons. Urban business properties in Zurich and Geneva face the steepest compression, as hybrid work normalization eliminates predictable corporate block patterns. Properties are responding with dynamic rate engines that capture last-minute wellness traveler willingness to pay premium rates for guaranteed lake-view or south-facing alpine inventory.
Switzerland Hospitality Market Segmentation
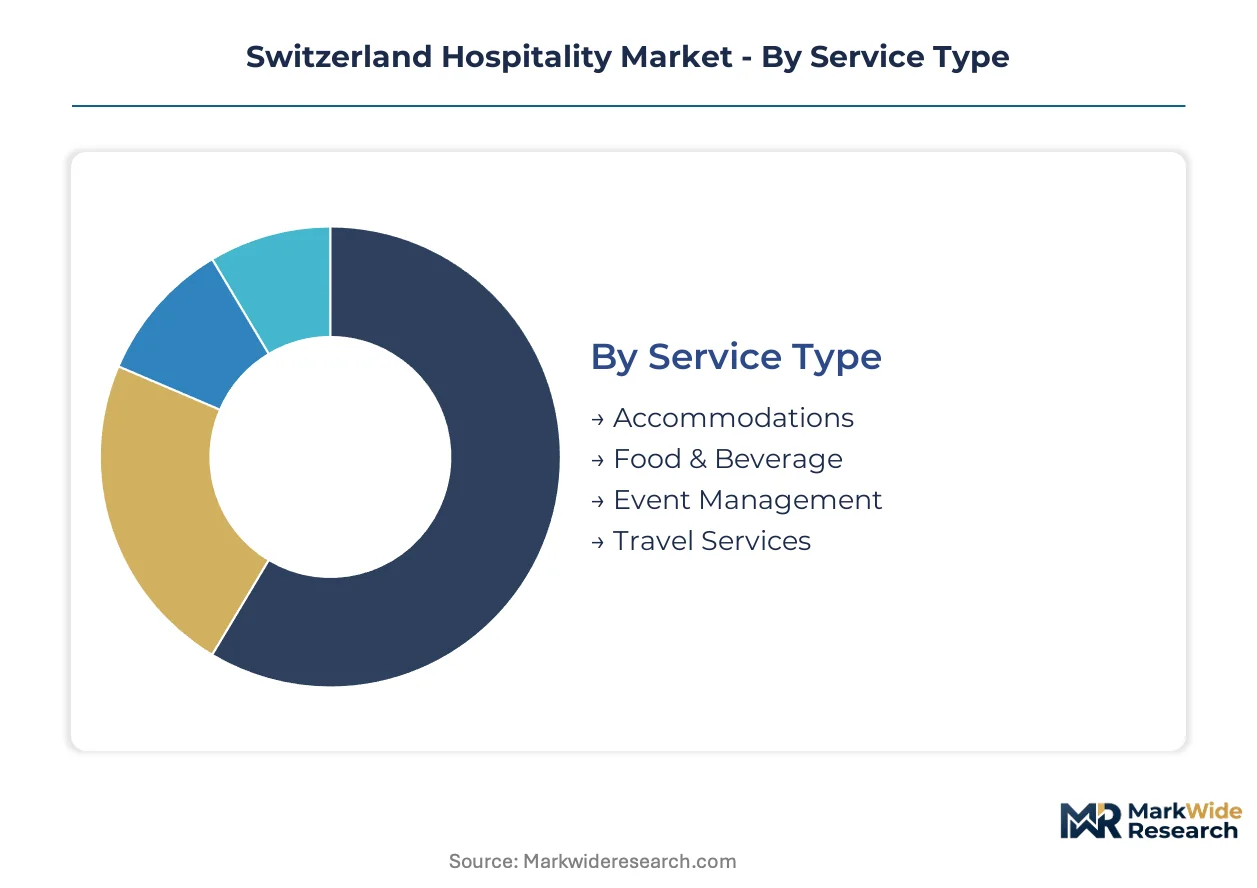
Swiss hospitality segmentation reflects divergent capital intensities and regulatory exposure across service delivery models. Cantonal licensing frameworks and Minergie building codes create asymmetric compliance burdens that reshape competitive positioning within each category.
Service Type:
Swissmedic therapeutic claims oversight and cantonal food safety enforcement differentiate margin structures across service delivery modes.
- Accommodations:Fixed-asset lodging operations spanning palace hotels to modular alpine lodges. Lake Geneva corridor properties capture premium rate positioning through medical-spa certification, while Graubünden operators leverage constrained supply in rail-accessible zones.
- Food & Beverage:Integrated restaurant and banquet operations governed by cantonal hygiene inspectors. SV Group's centralized procurement platform demonstrates how multi-canton scale offsets labor cost fragmentation in Jura and Ticino.
- Event Management:Corporate and social gathering coordination requiring municipal noise permits and fire-safety compliance. Demand concentrates in Zurich and Geneva convention infrastructure with year-round accessibility.
- Travel Services:Guest transportation and itinerary coordination bundled with lodging. Swiss Federal Railways partnerships enable properties to monetize remote alpine access previously unreachable for daily staff.
Established volume favors Accommodations; emerging adoption favors Travel Services.
Customer Type:
Booking window compression and hybrid work normalization are reallocating demand across traveler cohorts with divergent price elasticity.
- Leisure Travelers:Individual and family vacationers extending average length of stay through wellness programming. Graubünden and Valais properties capture extended-stay revenue through medical-spa regimen packaging.
- Business Travelers:Corporate account travelers facing structural demand pressure from remote work normalization. Urban properties in Zurich and Geneva face steepest advance-booking compression toward 21-day horizons.
- Group Bookings:Coordinated multi-room reservations for corporate retreats and wedding parties. Lake Geneva operators leverage year-round climate stability against alpine seasonality constraints.
- Local Residents:Domestic market for staycations and dining experiences. Ticino's Mediterranean climate attracts German and Benelux retirees seeking winter alternatives to Spanish coasts.
Margin stability favors Leisure Travelers; volume volatility defines Business Travelers.
Accommodation Type:
Building vintage and Minergie compliance status determine retrofit liability across physical asset categories.
- Hotels:Purpose-built lodging inventory ranging from urban business properties to alpine resorts. Heritage palace structures in Lucerne and Interlaken face thermal envelope upgrade costs exceeding replacement value thresholds.
- Hostels:Budget-oriented shared accommodation concentrated in urban transit corridors. Basel and Lausanne operators deploy IoT automation to compress front-of-house staffing models.
- Vacation Rentals:Privately owned short-term lodging inventory fragmenting pricing power in non-peak weeks. Digital distribution platforms compress traditional intermediary margins.
- Bed & Breakfasts:Small-scale family-operated lodging in Appenzell and Uri cantons. Legacy property management systems resist cloud-based channel manager connectivity.
Capital efficiency favors Vacation Rentals; regulatory insulation favors Hotels.
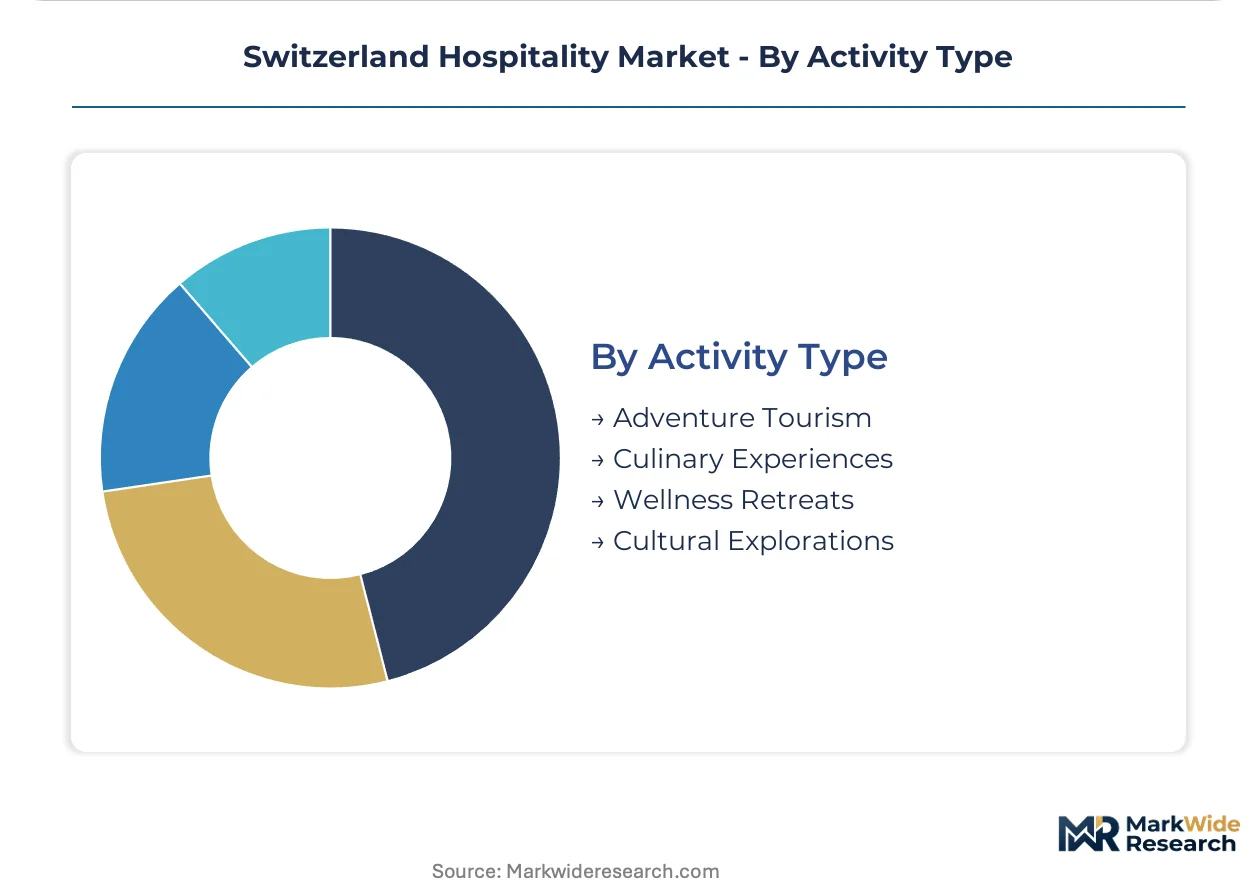
Activity Type:
Swissmedic certification tiers and therapeutic claim substantiation requirements stratify service margin potential.
- Adventure Tourism:Alpine skiing, hiking, and mountaineering experiences dependent on seasonal snowpack and trail accessibility. Zermatt's rail-only access model concentrates demand in supply-constrained geography.
- Culinary Experiences:Regional gastronomy programming leveraging Switzerland's protected designation products. Cantonal agricultural offices enforce origin labeling that supports rate premiums.
- Wellness Retreats:Medical-spa and therapeutic programming capturing disproportionate margin expansion. Properties partnering with Hôpitaux Universitaires de Genève bill procedures through supplemental health insurance channels.
- Cultural Explorations:Heritage site visits and museum programming concentrated in urban centers. Bern and Geneva operators leverage year-round demand stability against alpine seasonality.
Rate premium positioning favors Wellness Retreats; volume scalability defines Cultural Explorations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's hospitality sector generates substantial service export revenue from international wellness travelers, while importing specialized spa equipment and building materials for alpine lodge construction. The Lake Geneva corridor and Graubünden alpine zones concentrate demand from German, French, and Benelux source markets. Cantonal energy offices enforce asymmetric compliance burdens that reshape investment flows across sub-regions.
Lake Geneva Corridor
Medical-spa certification drives premium rate positioning for properties along Lake Geneva. Swissmedic's clarified therapeutic claims framework enables billing through supplemental health insurance channels. Hôpitaux Universitaires de Genève partnerships cluster in Geneva and Lausanne, where operators capture extended-stay wellness travelers.
Graubünden Alpine Zone
Rail-accessible supply constraints concentrate high-yield visitors in Zermatt and St. Moritz. Minergie certification mandates from cantonal energy offices accelerate greenfield lodge development over heritage retrofits. Andermatt Swiss Alps AG anchors investment in the Urseren Valley through integrated resort infrastructure.
Zurich Metropolitan Area
Hybrid work normalization compresses corporate advance-booking windows toward 21-day horizons. The canton's noise and fire-safety enforcement shapes event management venue economics. Urban properties deploy IoT-enabled room automation to fragment traditional front-of-house staffing models.
Ticino Mediterranean Zone
German and Benelux retiree demand for winter sun alternatives outpaces lodging inventory south of the Alps. The canton's hospitality-trained workforce scarcity forces wage premiums during peak seasons. Lugano and Locarno operators leverage microclimate advantages against Spanish coastal competitors.
Central Switzerland
Heritage palace properties in Lucerne and Interlaken face Minergie-P compliance costs exceeding replacement value thresholds. Pre-1990 thermal envelope upgrades strain family-owned balance sheets in Uri and Schwyz. Swiss Hotel Association quality grading gatekeeps online visibility for unaffiliated properties.
Switzerland Hospitality Market Competitive Landscape
Concentration sits with integrated hospitality platforms and international franchise operators that control multi-canton scale. The market structure spans heritage palace collections, modular alpine specialists, and asset-light global brands. Three archetypes dominate: domestic integrated operators with facility-management platforms, international luxury collections with medical-spa certification, and franchise-heavy global chains minimizing CHF-denominated balance-sheet exposure. Competitive moves center on rail-accessible real estate acquisition and telemedicine-spa partnerships with university hospitals.
Within the domestic integrated tier, SV Group leverages its food-service and facility-management platform across multiple cantons. Bürgenstock Collection anchors lakeside positioning through medical-spa certification and constrained supply geography. Among international franchise operators, Accor SA exemplifies asset-light models that reduce currency exposure in Swiss franc-denominated markets.
| Leading Market Players |
|---|
| SV Group |
| Sorell Hotels |
| MRH Switzerland AG |
| Bürgenstock Collection |
| Swiss Deluxe Hotels |
| Andermatt Swiss Alps AG |
| Accor SA |
| Marriott International |
| InterContinental Hotels Group |
| Others |
Pricing and Supply Chain Analysis
Modular timber-frame construction displacing heritage stone retrofitting simultaneously concentrates procurement in Baltic and Austrian engineered-wood suppliers while collapsing the per-key development cost spread between Graubünden greenfield sites and Lucerne palace renovations. This substitution dynamic compresses rate premiums historically commanded by vintage properties while elevating pricing power for rail-adjacent new builds with Minergie-P certification.
Pricing Analysis
The customization-premium spread between configured-to-order wellness programming and standardized room-night rates defines revenue capture across Swiss hospitality. Three-tier pricing structure across medical-certified, standard wellness, and economy alpine inventory segments the market by Swissmedic credential tier and thermal envelope grade. Pricing pressure stems from vacation rental platform fragmentation in non-peak weeks, compressing shoulder-season yields for unaffiliated properties. Corporate business travelers exhibit highest price sensitivity as hybrid work normalization eliminates predictable block commitments, while medical-spa extended-stay guests demonstrate lowest elasticity due to supplemental health insurance reimbursement channels.
Supply Chain Analysis
Inbound logistics costs for Italian marble finishes and Austrian cross-laminated timber fluctuate with Brenner Pass congestion and container availability at Genoa and Trieste ports. Switzerland draws hospitality FF&E from Germany, Italy, and Austria, with specialized spa equipment sourcing concentrated in German and Italian manufacturing clusters. Single-source vulnerability sits with Swiss Federal Railways' monopoly on alpine site accessibility, where electrification delays strand development timelines. Distribution runs through cantonal procurement cooperatives for multi-property operators and direct manufacturer relationships for independent family-owned lodges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland hospitality is approaching a platform-economics inflection as telemedicine-spa interoperability with university hospital systems restructures guest acquisition and service delivery around health data portability rather than physical asset loyalty.
For Market Incumbents: Shield heritage palace rate positioning by accelerating Minergie-P certification completion before 2030 regulatory deadlines harden competitive moats. Consolidate control over rail-adjacent development parcels in Graubünden to preempt modular lodge entrants from capturing constrained supply premiums. Vertical integration into telemedicine credentialing partnerships with Hôpitaux Universitaires de Genève and University Hospital Zurich defends margin capture against asset-light franchise competitors.
For New Entrants and Emerging Players: Service-layer gaps in Ticino winter-sun programming for German and Benelux retirees offer white-space penetration below incumbent radar. Target Mediterranean-climate lodging inventory south of the Alps where workforce scarcity has suppressed development response to demand. Partner with Swiss Federal Railways on micro-lodge concepts at 800-1200 meter electrified line stations previously unreachable for daily staffing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic integrated operators carrying facility-management platform scale but limited medical-spa certification depth. Long-term viability across the analysis window favors properties with dual revenue streams from lodging and billable therapeutic services. Watch Swissmedic clarifications on supplemental insurance reimbursement eligibility as the signal indicating margin expansion or compression for wellness-retreat positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Spa Certification Investment | Swissmedic credentialing unlocks supplemental health insurance billing channels for extended-stay revenue. |
| Rail-Adjacent Real Estate Acquisition | Swiss Federal Railways electrification expansion opens previously inaccessible alpine development sites. |
| Telemedicine Partnership Formation | University hospital collaborations enable pre-arrival health screening and personalized regimen design. |
| Minergie-P Retrofit Completion | Cantonal energy offices mandate thermal envelope standards that gatekeep rate premium eligibility. |
| Integrated Facility-Management Platform | Multi-canton scale offsets labor cost fragmentation in Jura and Ticino seasonal peaks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hotel development executives, cantonal energy office officials, Swissmedic regulatory leads, and spa operations directors; and secondary validation against Swiss Hotel Association grading databases, cantonal building permit records, SEC filings from listed international operators, and Swiss Federal Railways infrastructure investment disclosures. Bottom-up property-level revenue modeling triangulated against top-down cantonal hospitality GDP contributions.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service type, customer type, accommodation type, and activity type with specific weighting for medical-spa certification tiers and Minergie compliance grades. CAGRs derived from historical lodging stock growth rates, wellness traveler spend trajectories, and regulatory mandate implementation timelines. Forecast inputs incorporated cantonal workforce availability indices and supplemental health insurance penetration rates.
Forecasts assume regulatory continuity in Swissmedic therapeutic claims frameworks and cantonal energy efficiency regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
UAE Hospitality Market
Accommodation
Capsule Hotels Market
Accommodation
France Online Accommodation Market
Accommodation
United States Online Accommodation Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
France Hospitality Market
Accommodation
Hotel Market
Accommodation
Youth Summer Camp Market
Accommodation
Sweden Hospitality Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Glamping Market
Accommodation
Africa Hotel Market
Accommodation
UK Student Accommodation Market
Accommodation
US Student Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
Austria Hospitality Market