
 Youth Summer Camp Market | 2026-2036
Youth Summer Camp Market Size, Share, and Industry Trends Forecast 2026-2036
Youth Summer Camp Market Insights
The gap between traditional outdoor programming and technology-integrated curricula is narrowing as hybrid camp models gain operational traction. Camp Galileo leverages its STEAM-focused curriculum to differentiate across day camp and specialty camp formats. YMCA anchors its market position through extensive facility networks and nonprofit pricing structures that compete with for-profit operators. iD Tech specializes in technology-intensive programming, occupying a premium niche within the science and technology activity focus segment.
Youth summer camps are supervised recreational and educational programs delivered during school vacation periods, typically operating from late May through August with structured daily schedules spanning six to ten hours. These programs combine physical activity, skill development, and socialization objectives across outdoor and indoor facilities, with staff ratios and safety protocols governed by state childcare regulations. Overnight camp and specialty camp formats command higher per-session revenue due to residential infrastructure and specialized instructor requirements. Science and technology programming represents the fastest-expanding activity focus as parental prioritization of future workforce skills reshapes enrollment patterns.
State childcare licensing agencies, the American Camp Association accreditation framework, and COPPA compliance requirements collectively elevate operational barriers for new entrants while mandating staff background checks, health protocols, and data privacy safeguards. ACA accreditation functions as a de facto market access credential for premium-priced programs serving affluent households. Stakeholders must monitor evolving staff compensation mandates and technology infrastructure investments as competitive differentiators rather than discretionary costs.
Market Dynamics
Parental prioritization of workforce-relevant skills is compressing enrollment cycles toward STEAM-intensive curricula, forcing operators to reconfigure instructor hiring and facility allocation away from traditional outdoor recreation.
Growth Catalysts
- K-12 enrichment demand:Dual-income households in suburban Texas, California, and North Carolina clusters are channeling discretionary spending into structured experiential programs that supplement academic calendars.
- ACA accreditation signaling:The American Camp Association's credential framework creates de facto market access for premium-priced programs serving affluent households seeking verified safety protocols.
- Hybrid curriculum models:Technology-integrated programming combining physical activity with digital skill-building is capturing enrollment from families previously segmented between outdoor and indoor options.
Market Restraints
- Specialized instructor scarcity:Qualified STEAM educators command wage premiums that compress margins for mid-tier operators without endowment backing or scale economies.
- Residential infrastructure costs:Overnight camp formats require capital-intensive lodging, dining, and medical facilities that limit geographic expansion to established property holdings.
- COPPA compliance burden:The Children's Online Privacy Protection Act mandates data handling protocols that increase technology infrastructure costs and legal exposure for digital engagement components.
Strategic Opportunities
- Underpenetrated rural markets:Secondary metropolitan zones in North Carolina and inland California lack premium camp density relative to household formation rates.
- Corporate partnership channels:Employer-sponsored childcare benefits represent emerging distribution pathways as HR departments expand family support offerings.
- State licensing harmonization:Converging childcare standards across multiple jurisdictions create operational templates for multi-state expansion without full regulatory reconstruction.
Industry Challenges
- Background check pipeline delays:State-level certification timelines for staff screening create onboarding bottlenecks that compress pre-season hiring windows.
- Legacy reservation system integration:Camp management software migration encounters data migration friction with decades-old participant tracking databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Youth Summer Camp Market |
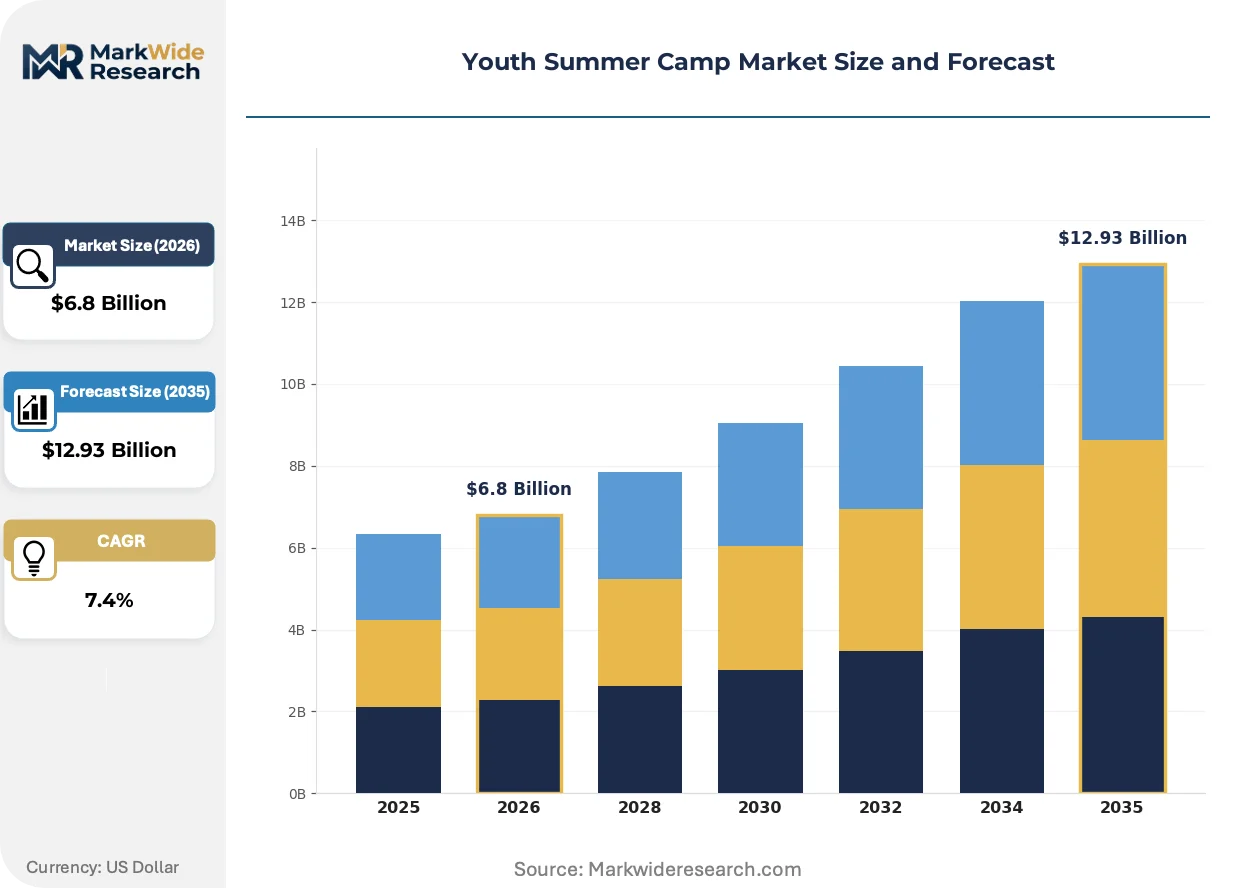
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camp Type: Day Camp, Overnight Camp, Specialty Camp, Adventure Camp Activity Focus: Arts & Crafts, Sports, Nature Exploration, Science & Technology Age Group: 6-8 Years, 9-12 Years, 13-15 Years, 16-18 Years Program Duration: Weekly Program, Two-Week Program, Month-Long Program, Seasonal Program |
| Companies Covered | Camp Galileo, American Summer Camps, Youth Enrichment Brands, The Invention Factory (Camp Invention), Miniwanca, YMCA, KinderCare Learning Companies, Right At School, iD Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Youth Summer Camp Market Trends and Innovations
Curriculum delivery methods are bifurcating between immersive technology labs and rewilding-focused outdoor programs, with hybrid formats capturing intermediate demand segments previously served by single-focus operators.
AI-assisted personalized learning pathways are rendering obsolete the one-size-fits-all activity rotation models that dominated twentieth-century camp scheduling. K-12 enrichment buyers are adopting these adaptive curricula at accelerating rates during pilot programs. The technology is compressing instructor-to-camper ratios while maintaining perceived individual attention quality.
COPPA enforcement actions by the FTC are elevating data governance to core operational competency, requiring dedicated privacy officers and audited consent workflows. Camps with digital components face structural compliance costs that disadvantage smaller operators. Texas and California programs are responding by segregating online and offline activity streams to limit regulatory exposure.
Subscription-based enrollment models are displacing single-session bookings as primary revenue architecture. Affluent suburban households are locking in multi-year commitments through membership structures that guarantee placement. This pattern concentrates most visibly in North Carolina's Research Triangle and Austin-San Antonio corridor camps serving technology sector employees.
Youth Summer Camp Market Segmentation
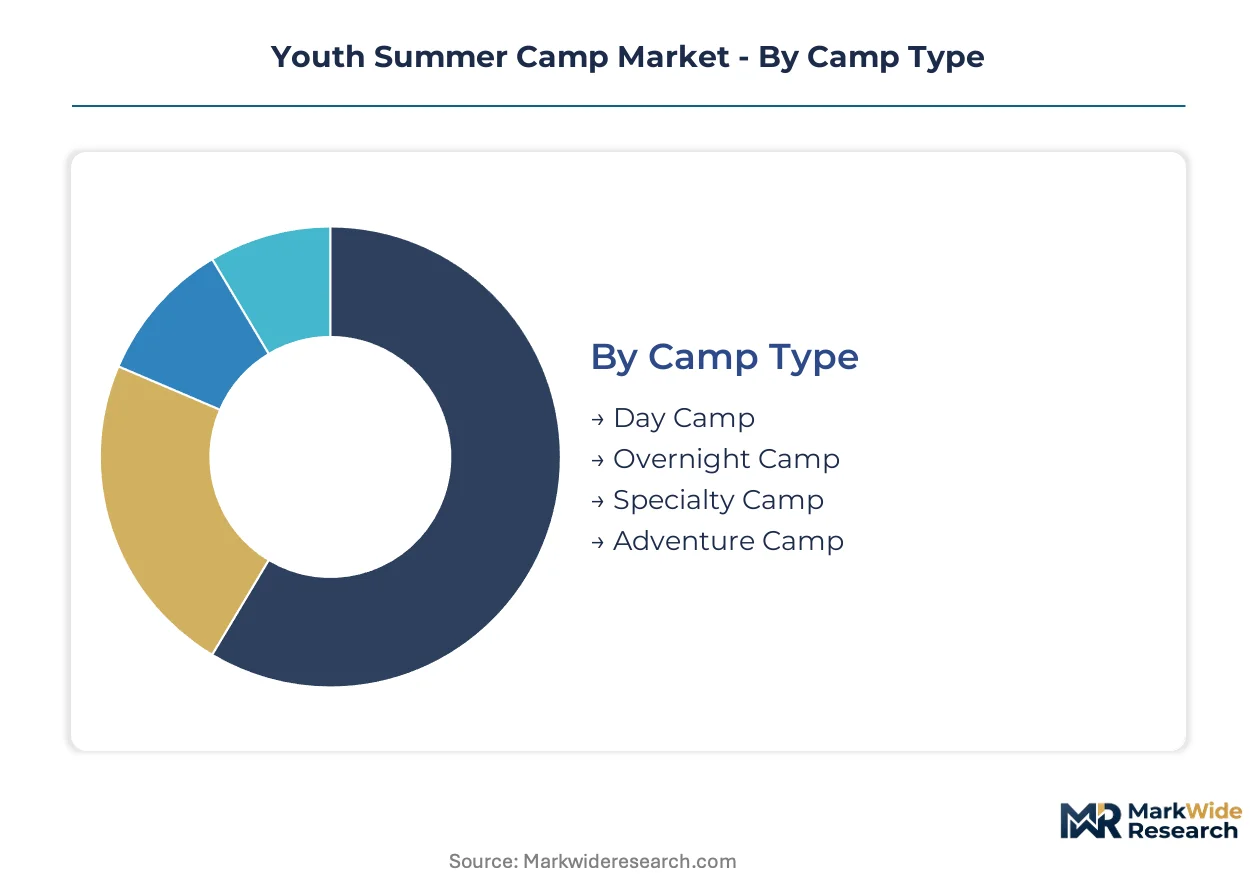
Youth summer camp operators configure program portfolios across four distinct segmentation dimensions that determine pricing architecture, staffing models, and facility requirements. Each dimension captures different parental decision criteria, from logistical constraints to developmental priorities. Understanding cross-segment demand patterns enables targeted capacity allocation and curriculum investment decisions.
Camp Type:
Cost tier differentiation separates commuter-based accessibility from residential immersion experiences, with infrastructure intensity driving margin structure variation across formats.
- Day Camp:Non-residential programs operating 6-10 hour daily schedules without overnight accommodation requirements. Demand concentrates in suburban Texas and California clusters where dual-income households prioritize convenience and lower per-session cost exposure. The format dominates total enrollment volume due to minimal capital barriers and flexible site requirements.
- Overnight Camp:Residential programs spanning multiple nights with integrated lodging, dining, and medical facilities. Premium pricing in North Carolina's mountain and coastal regions reflects higher staff-to-camper ratios and property maintenance burdens. The segment commands loyalty through identity formation and multi-year camper retention.
- Specialty Camp:Intensive single-focus programs emphasizing skill mastery in defined domains. Arts, sports, and technology concentrations attract motivated campers seeking portfolio-building experiences.
- Adventure Camp:Outdoor expedition formats incorporating wilderness travel, challenge courses, and environmental immersion. Higher liability insurance and certified guide requirements limit operator density.
Day camp commands the established base. The steepest expansion runs through specialty camp formats.
Activity Focus:
Application orientation shapes parental willingness to pay, with future workforce relevance now outweighing traditional recreation value in enrollment decisions.
- Science & Technology:Coding, robotics, and laboratory-based inquiry curricula occupying premium positioning. STEAM-intensive programming in Austin-San Antonio corridor camps reflects technology sector parental employment concentration. The segment attracts highest per-camper revenue through specialized instructor premiums and equipment depreciation.
- Sports:Athletic skill development across individual and team disciplines with certified coaching requirements. Traditional demand strength in suburban North Carolina supports stable enrollment against technology-focused alternatives.
- Arts & Crafts:Creative expression programming spanning visual, performing, and applied arts. Portfolio preparation for secondary school admissions drives selective demand concentration.
- Nature Exploration:Environmental science and outdoor skills curricula emphasizing conservation ethics. California operators leverage coastal and mountain access for differentiated positioning.
Sports programming commands the established base. The steepest expansion runs through science and technology.
Age Group:
Customer type progression determines curriculum complexity, supervision ratios, and transition pathways between camp formats as developmental needs evolve.
- 9-12 Years:Peak enrollment bracket where independent participation coincides with structured skill acquisition readiness. Texas operators report highest household spending intensity as parents invest in foundational enrichment.
- 6-8 Years:Entry-level segment requiring highest staff supervision densities and foundational socialization curricula. California's Research Triangle camps specialize in transition programming from daycare dependencies.
- 13-15 Years:Adolescent programming emphasizing leadership development and advanced technical tracks. Peer social dynamics dominate format preferences.
- 16-18 Years:Pre-college segment incorporating internship structures, counselor-in-training pathways, and resume-building specializations. Narrowest operator participation due to summer employment competition.
The 6-8 year bracket commands the established base. The steepest expansion runs through 9-12 year programming.
Program Duration:
Volume commitment depth structures revenue predictability, with extended formats enabling curriculum sequencing unavailable in compressed schedules.
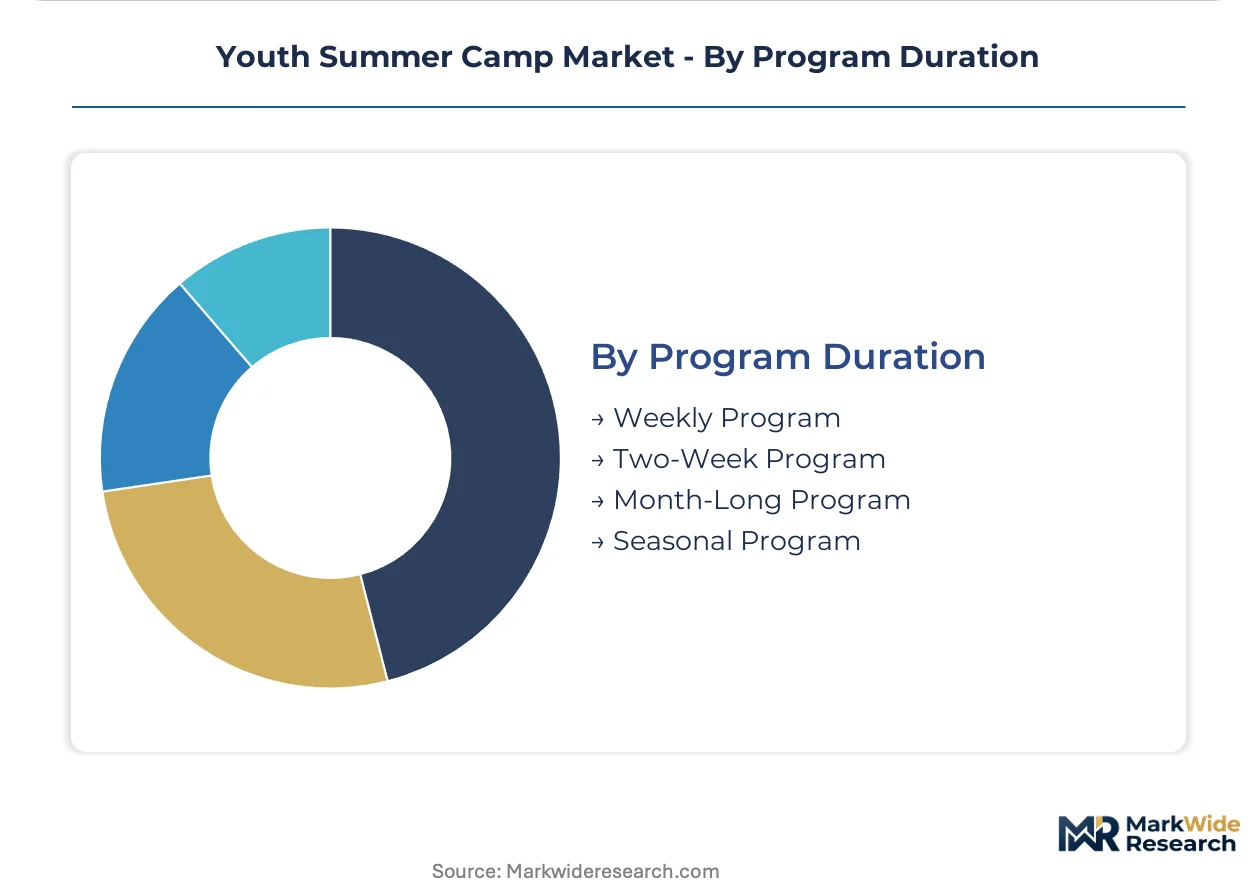
- Weekly Program:Standardized seven-day modules permitting flexible enrollment combinations. North Carolina camps deploy weekly architecture to accommodate vacation scheduling fragmentation among dual-income households.
- Two-Week Program:Intermediate commitment enabling skill progression without full-season displacement. Texas operators report highest conversion from trial weekly bookings.
- Month-Long Program:Intensive immersion supporting substantial project completion and social cohort formation. Premium residential camps in California coastal markets specialize in this architecture.
- Seasonal Program:Full-summer enrollment spanning 8-12 weeks with progressive curriculum arcs. Subscription-based membership models concentrate demand in affluent suburban clusters.
Weekly programming commands the established base. The steepest expansion runs through seasonal program memberships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income suburban households concentrate demand in metropolitan clusters where structured experiential programming commands premium enrollment fees. Texas, California, and North Carolina anchor North American volume through technology sector employment density and population growth corridors. Regulatory fragmentation across state childcare licensing regimes shapes operational scalability for multi-state operators.
United States
The FTC enforces COPPA compliance requirements that elevate data governance costs for camps with digital engagement components. Texas suburban clusters around Austin and Dallas-Fort Worth report highest household spending intensity on STEAM-intensive curricula. California operators leverage coastal and mountain access for differentiated nature exploration positioning against technology-focused alternatives.
Canada
Provincial childcare licensing harmonization creates operational templates for operators expanding from US markets into Ontario and British Columbia. Health Canada guidelines govern medical facility requirements for overnight residential formats. Toronto and Vancouver metropolitan areas concentrate enrollment demand among technology sector dual-income households.
United Kingdom
Ofsted inspection frameworks for childcare providers elevate operational barriers for new market entrants seeking premium positioning. GDPR compliance requirements parallel COPPA burdens for digital curriculum components. London commuter belt and Manchester suburban clusters show strongest household formation rates supporting camp enrollment growth.
Germany
Jugendschutz youth protection regulations govern staff certification and supervision ratio requirements for residential programs. Baden-Württemberg and Bavaria industrial regions concentrate technology sector employment driving STEAM curriculum demand. Berlin-Brandenburg corridor operators specialize in hybrid outdoor-technology formats.
Australia
State-level Working with Children Check requirements create background screening bottlenecks compressing pre-season hiring timelines. New South Wales and Victoria metropolitan clusters concentrate dual-income household density supporting premium day camp enrollment. Sydney and Melbourne operators report strongest subscription-based membership adoption rates.
Youth Summer Camp Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented market tiers defined by accreditation status and curriculum intensity. The vendor base spans nonprofit facility networks, for-profit specialty operators, and enrichment brand portfolios with varying capital backing. Three archetypes dominate: ACA-accredited premium residential camps, technology-intensive specialty operators, and community-anchored nonprofit networks. Competitive moves concentrate on multi-state licensing harmonization and subscription-based enrollment model adoption.
Within the technology-specialist tier, iD Tech occupies a premium positioning exemplifying STEAM-intensive curriculum architecture. Camp Galileo represents the hybrid-format archetype combining outdoor activity with structured skill-building. YMCA anchors the nonprofit network tier through extensive facility infrastructure and community-based pricing structures. These three operators illustrate divergent strategic paths for capturing suburban household discretionary spending.
| Leading Market Players |
|---|
| Camp Galileo |
| American Summer Camps |
| Youth Enrichment Brands |
| The Invention Factory (Camp Invention) |
| Miniwanca |
| YMCA |
| KinderCare Learning Companies |
| Right At School |
| iD Tech |
| Others |
Pricing and Supply Chain Analysis
Specialized STEAM instructor scarcity in the United States concentrates wage premiums in Texas and California suburban clusters, compressing margins for mid-tier operators while ACA-accredited premium camps capture disproportionate margin pools through verified safety signaling and subscription-based enrollment lock-in.
Pricing Analysis
Cost-plus contracts with wage indexation to state childcare certification requirements dominate instructor compensation structures. Three-tier pricing structure across premium, standard, and economy levels separates ACA-accredited residential programs from unaccredited day camps and municipal nonprofit offerings. Price differentiation hinges on certification tier and geographic delivery cost, with overnight formats commanding substantial premiums due to residential infrastructure. Cost compression in mid-tier day camps is intensifying because specialized STEAM educator wage premiums outpace tuition pricing flexibility. Municipal and community-based nonprofit segments exhibit highest price sensitivity, while technology sector dual-income households in Austin and Research Triangle corridors show lowest sensitivity to enrollment fees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates technology equipment procurement risk for STEAM curriculum operators. Supply concentration spans the United States for ACA accreditation services and instructor certification pipelines, China for robotics kits and coding hardware, and Canada for outdoor equipment and camping infrastructure. Raw material dependencies include specialized educational technology components, liability insurance coverage, and seasonal food service provisioning. Single-source vulnerability concentrates in certified STEAM instructor labor markets where state-level background check pipelines create pre-season hiring bottlenecks. Distribution runs through direct-to-parent digital enrollment platforms, employer-sponsored childcare benefit channels, and community-based referral networks anchored in school district partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-committed affluent households as dual-income technology sector employees consolidate enrollment decisions through multi-year membership structures, fragmenting price-taking behavior among uncommitted single-session buyers.
For Market Incumbents: Pre-empt emerging hybrid-format competitors by accelerating proprietary curriculum development in AI-assisted personalized learning pathways. Defend against margin compression from specialized instructor wage premiums through backward integration into counselor training academies. Channel control through employer-sponsored childcare benefit partnerships represents the critical lever for locking in enrollment visibility.
For New Entrants and Emerging Players: Pursue underpenetrated rural markets in inland California and secondary North Carolina metropolitan zones where premium camp density lags household formation rates. Target corporate partnership channels as the most penetrable distribution pathway, leveraging HR department expansion of family support benefits. Position through ACA accreditation investment as the essential go-to-market credibility signal for affluent suburban household access.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-intensive specialty operators with established STEAM curriculum IP and scalable instructor training infrastructure. Long-term viability across the five-to-ten year window rests on adaptive curriculum capabilities that compress instructor-to-camper ratios while maintaining perceived individual attention quality. Monitor state-level childcare licensing harmonization progress as the critical inflection signal for multi-state operational scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| ACA Accreditation Investment | Unlocks premium pricing tiers in Texas and California suburban clusters through verified safety protocol signaling. |
| Subscription Enrollment Model | Converts fragmented single-session bookings into predictable multi-year revenue streams with guaranteed placement guarantees. |
| Corporate Partnership Channel | Captures employer-sponsored childcare benefit expansion as HR departments prioritize family support infrastructure. |
| Hybrid Curriculum Development | Combines outdoor activity with digital skill-building to capture demand segments previously split between format types. |
| Instructor Training Academy | Addresses specialized STEAM educator scarcity through captive supply of certified staff reducing wage premium exposure. |
Research Methodology
The analysis maps day camp, overnight camp, specialty camp, and adventure camp formats, each validated through camp operations directors, curriculum development leads, parent enrollment decision-makers, and state childcare licensing officials. Primary interviews with these stakeholders combined with secondary validation against ACA accreditation databases, state regulatory filing records, and municipal recreation department enrollment disclosures. Bottom-up enrollment volume triangulation across camp type, activity focus, age group, and program duration dimensions converged with top-down household discretionary spending analysis.
Assumptions held fixed include prevailing state childcare licensing requirements and COPPA compliance frameworks, while variables included technology integration penetration rates and subscription model adoption curves across the projection horizon. Segmentation dimensions modeled encompass camp format infrastructure intensity, curriculum application orientation, developmental age progression, and enrollment commitment depth. CAGRs were derived from enrollment volume trajectories and per-camper revenue evolution across these dimensions. Industry-specific forecast inputs incorporated technology sector employment concentration and dual-income household formation rates in target metropolitan clusters.
Sensitivities concentrate around state-level staff certification timeline delays, COPPA enforcement action intensity, and technology equipment procurement cost volatility. Forecasts reflect documented assumptions regarding regulatory stability and household discretionary spending patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Japan Hospitality Market
Accommodation
France Hospitality Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Extended Stay Hotel Market
Accommodation
India Online Accommodation Market
Accommodation
Hostel Market
Accommodation
UAE Hospitality Market
Accommodation
Switzerland Hospitality Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
United States Online Accommodation Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
Movie Theaters Market
Accommodation
Europe Student Accommodation Market