
 Bed and Breakfast Accommodation Market | 2026-2036
Bed and Breakfast Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Bed and Breakfast Accommodation Market Insights
Direct booking channels between property owners and guests is narrowing as platform intermediaries consolidate control. Airbnb leverages its host network density to sustain organic inventory growth in heritage districts. Booking.com anchors European market visibility through localized property certification programs. Expedia Group competes via bundled packaging that merges boutique stays with experiential add-ons.
Bed and breakfast accommodation denotes small-scale lodging establishments typically offering overnight stays and morning meals in residential or converted historic properties, with inventory rarely exceeding ten guest rooms and operations emphasizing personalized hospitality over standardized hotel protocols. The segment serves travelers prioritizing cultural immersion, architectural authenticity, and host-curated local knowledge over amenity density. Luxury service tier properties command premium positioning through chef-prepared breakfasts and bespoke concierge arrangements, while themed properties differentiate via narrative-driven design tied to regional heritage. Victorian property types dominate established markets where preservation incentives protect architectural character, though modern conversions attract design-conscious urban segments.
FDA food safety protocols, EU GDPR data handling mandates, and local zoning boards collectively shape operational compliance burdens across jurisdictions. GDPR enforcement specifically constrains how platforms process guest preference data for personalized marketing. Stakeholders must monitor evolving short-term rental caps in municipal jurisdictions and adapt inventory strategies accordingly.
Market Dynamics
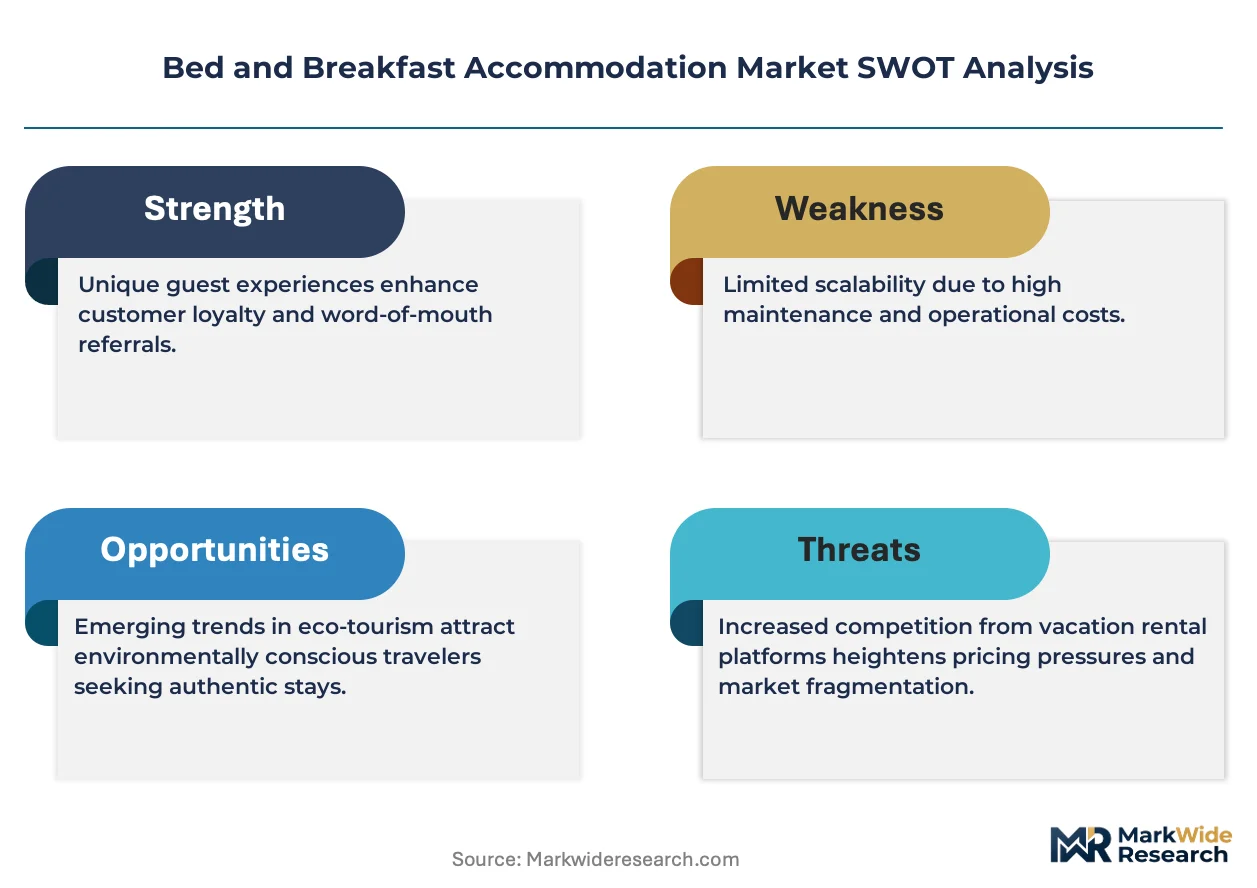
Platform intermediaries now control guest acquisition pipelines, compressing direct booking margins for independent operators while GDPR and the EU AI Act impose data governance costs that favor scaled platform compliance infrastructure over fragmented owner-managed systems.
Growth Catalysts
- Rural tourism corridors:Italy's agriturismo incentive programs channel infrastructure grants toward historic farmhouse conversions, expanding experiential inventory in underutilized agricultural zones.
- GDPR-compliant personalization:Booking platforms investing in privacy-preserving machine learning retain guest preference data within regulatory boundaries, enabling targeted marketing that smaller operators cannot replicate.
- Heritage preservation tax credits:Municipal zoning boards in France and Spain offer property tax abatements for certified historic renovations, lowering capital barriers to boutique lodging entry.
Market Restraints
- Input cost volatility:Artisanal breakfast provisioning faces fluctuating dairy and specialty grain prices, squeezing margin at luxury service tier properties where chef-prepared meals anchor positioning.
- Supply concentration risk:Platform algorithmic visibility determines occupancy rates, creating dependency on Airbnb and Booking.com traffic allocation systems with opaque ranking mechanics.
- Regulatory friction:Short-term rental caps in Barcelona, Amsterdam, and Lisbon constrain inventory expansion in high-demand urban cores where zoning enforcement intensified.
Strategic Opportunities
- Underpenetrated secondary cities:Portugal's interior Alentejo region and Spain's Extremadura corridor offer low-competition positioning for themed properties tied to wine heritage and medieval architecture.
- EU Green Deal alignment:Energy retrofit subsidies for listed buildings enable carbon-neutral certification that commands premium positioning among sustainability-conscious leisure travelers.
- Direct channel innovation:WhatsApp Business API integration allows operators to bypass platform commissions while maintaining GDPR-compliant guest communication workflows.
Industry Challenges
- Certification timeline compression:Historic property safety approvals from local heritage boards and fire inspection authorities create six-to-twelve month pre-opening delays that strain operator liquidity.
- Skill scarcity in hospitality-tech hybrid roles:Property managers must simultaneously execute personalized guest services and revenue management analytics, a dual competency rare in traditional accommodation labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed and Breakfast Accommodation Market |
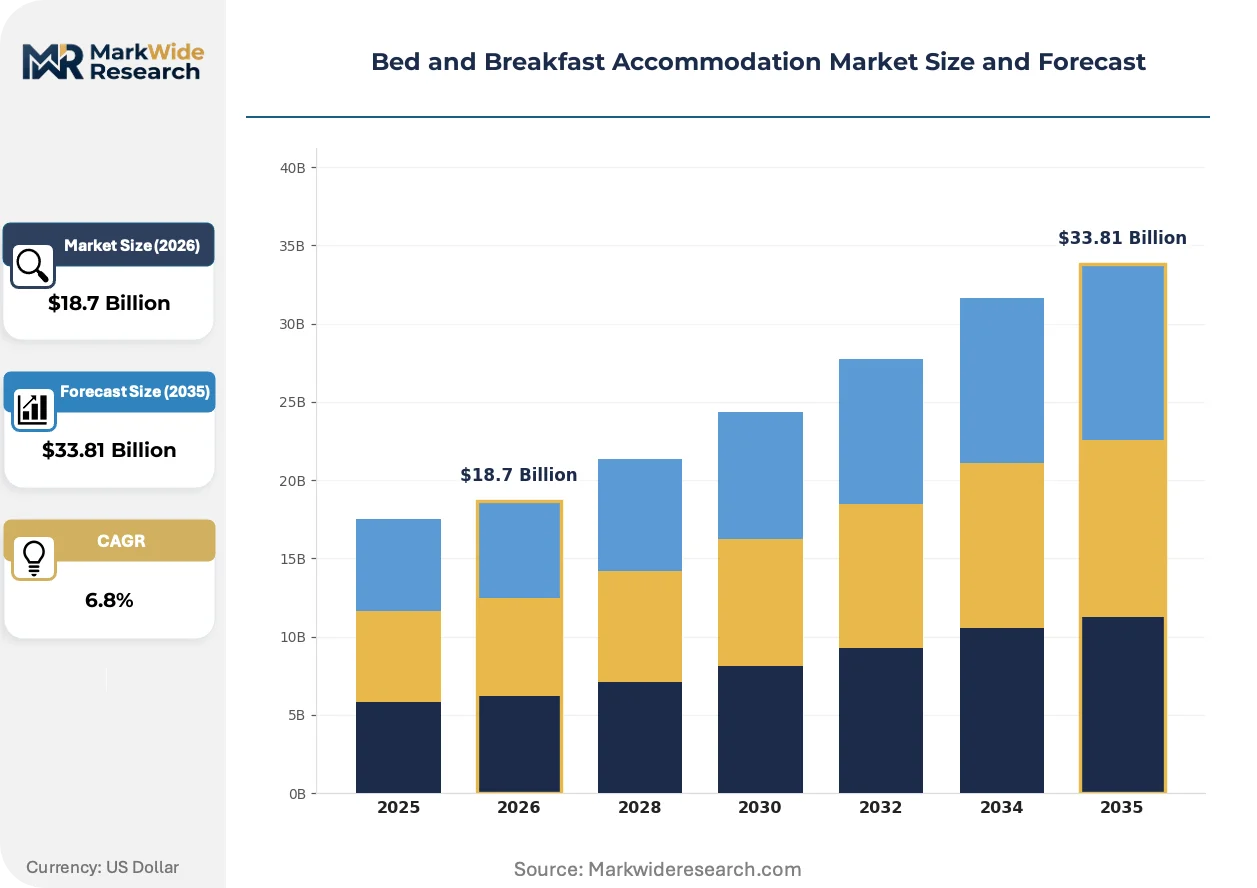
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Victorian, Colonial, Modern, Rustic Service Type: Standard, Luxury, Boutique, Themed Room Features: Ensuite Bathroom, Balcony, Sea View, Fireplace Guest Type: Families, Couples, Solo Travelers, Business Travelers |
| Companies Covered | Airbnb, Booking.com, Expedia Group, OYO Hotels & Homes, Marriott International, InterContinental Hotels Group, Hilton Worldwide Holdings, Accor, Wyndham Hotels & Resorts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed and Breakfast Accommodation Market Trends and Innovations
Digital infrastructure is collapsing the distance between property discovery and booking confirmation, while regulatory frameworks and traveler expectations simultaneously pull operators toward transparency and hyper-local curation.
Property management software is virtualizing operational workflows previously requiring on-site staff presence. Mid-scale operators across Italy and France adopt cloud-based channel managers and automated check-in systems to reduce labor dependency. This technology compression enables single-host management of multiple dispersed properties, restructuring competitive economics toward portfolio scale rather than single-location hospitality intensity.
The EU AI Act imposes algorithmic transparency requirements on booking platforms deploying recommendation engines and dynamic pricing systems. Industrial consequence includes mandatory documentation of training data provenance and guest profiling logic, increasing compliance overhead. Small-platform operators and independent booking cooperatives in Germany and the Netherlands face disproportionate adaptation costs relative to scaled intermediaries, accelerating market consolidation toward entities with dedicated regulatory technology teams.
Traveler sourcing behavior now prioritizes host-curated experiential packages over standalone room reservations. Boutique operators in Tuscany and Provence respond by unbundling accommodation from guided vineyard access, cooking instruction, and artisan studio visits. This pattern is most visible in secondary markets where differentiation through architectural character alone proves insufficient against urban luxury hotel competition.
Bed and Breakfast Accommodation Market Segmentation
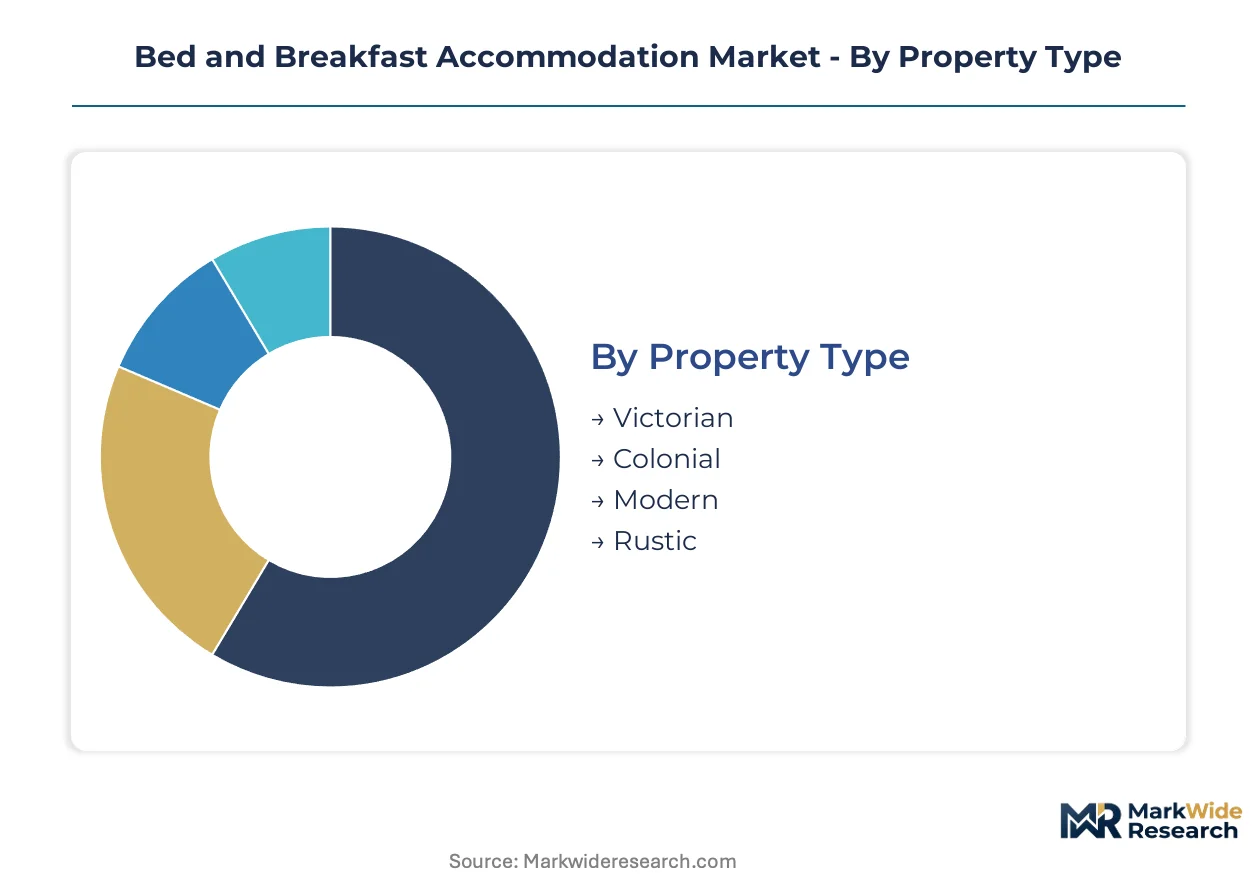
Segmentation in the bed and breakfast accommodation market reveals how property characteristics, service tiers, and guest profiles create distinct competitive arenas. Each dimension shapes capital requirements, operational complexity, and pricing power differently across the value chain.
Property Type:
Architectural heritage and construction era determine renovation costs, regulatory burden, and guest positioning potential across the inventory base.
- Victorian:Ornate period detailing with high ceilings and original staircases commands premium positioning in heritage districts. Demand concentrates in England's Cotswolds and Scotland's Edinburgh New Town where preservation tax incentives offset structural maintenance costs.
- Colonial:Symmetrical facades with wraparound porches dominate New England and Mid-Atlantic corridors. Portuguese azulejo-adorned colonial properties in Porto and Lisbon attract design-conscious European travelers seeking architectural authenticity over amenity density.
- Modern:Purpose-built or converted contemporary structures emphasize energy efficiency and accessibility compliance. Urban infill projects in Barcelona and Amsterdam navigate strict short-term rental caps through long-stay licensing arrangements.
- Rustic:Timber-framed farmhouses and stone barn conversions leverage agricultural zoning flexibility. Italy's agriturismo program channels infrastructure grants toward these properties in Tuscany and Umbria.
Victorian properties command the established base. The steepest expansion runs through Rustic conversions in rural tourism corridors.
Service Type:
Service intensity tiers separate properties competing on operational efficiency from those investing in experiential differentiation and staff-to-guest ratios.
- Standard:Owner-operated properties with continental breakfast service and limited concierge function. These dominate secondary markets in Portugal's Alentejo and Spain's Extremadura where labor scarcity constrains service complexity.
- Luxury:Chef-prepared morning meals, bespoke concierge arrangements, and turndown service justify rate premiums of two to three times standard tier levels. Properties in France's Provence and Italy's Lake Como corridor anchor positioning through gastronomic credentials.
- Boutique:Design-forward interiors with curated art collections and limited room counts emphasize aesthetic coherence over standardized hospitality protocols. Copenhagen and Stockholm host dense clusters targeting Scandinavian design tourism.
- Themed:Narrative-driven concepts tied to regional heritage—wine-making, literary history, or maritime tradition—create booking urgency through scarcity and story. Irish castle stays and Scottish whisky trail properties exemplify this model.
Standard service commands the established base. The steepest expansion runs through Luxury tier properties capturing post-pandemic preference for high-touch hospitality.
Room Features:
Amenity differentiation within properties creates rate stratification and occupancy yield management opportunities for revenue optimization.
- Ensuite Bathroom:Private facilities have shifted from premium to baseline expectation across all markets except heritage-listed properties where structural constraints limit retrofit feasibility. GDPR-compliant booking platforms use this attribute as a primary filter in search algorithms.
- Balcony:Outdoor private space commands rate premiums of fifteen to twenty-five percent in Mediterranean coastal markets. Greek island properties and Croatia's Dalmatian coast leverage this feature for direct channel conversion.
- Sea View:Unobstructed coastal sightlines justify the highest rate premiums within a property's inventory mix. Properties in Cornwall, Normandy, and the Algarve differentiate through floor-level and orientation tiering.
- Fireplace:Working hearths in guest rooms drive seasonal demand concentration in winter leisure markets. Scottish Highlands and Alpine properties in France and Switzerland emphasize this feature for off-peak occupancy stabilization.
Ensuite Bathroom commands the established base. The steepest expansion runs through Sea View inventory as coastal positioning intensifies.
Guest Type:
Customer composition shapes booking lead times, cancellation patterns, ancillary revenue potential, and platform channel preferences.
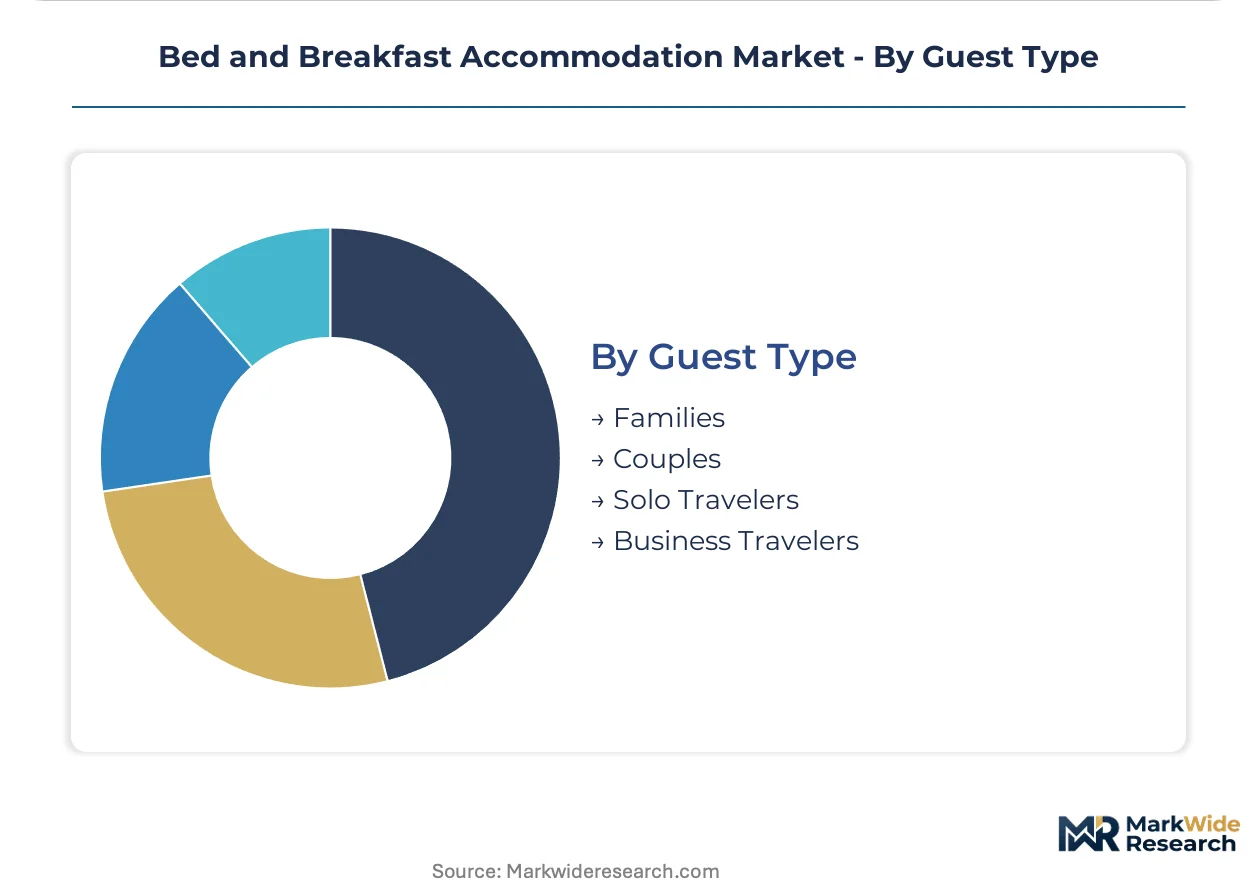
- Families:Multi-room bookings with kitchenette requirements and child safety specifications drive shoulder-season demand. Properties in Ireland's Kerry County and Wales' Pembrokeshire optimize for this segment through interconnected room configurations.
- Couples:Romance-oriented travelers generate highest ancillary attachment rates for experiential packages and private dining. Tuscany's vineyard properties and Santorini's caldera-view inventory target this segment through adult-only policies.
- Solo Travelers:Single occupancy with communal breakfast tables and host-curated social programming. Urban properties in Berlin, Lisbon, and Edinburgh capture this demand through location density and safety positioning.
- Business Travelers:Midweek bookings requiring reliable WiFi, early breakfast service, and flexible cancellation terms. Properties near secondary city business districts in Manchester, Lyon, and Milan compete with extended-stay hotel chains.
Couples command the established base. The steepest expansion runs through Solo Travelers as remote work flexibility extends bleisure trip duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's high-speed rail network connecting Milan, Florence, and Rome underwrites the country's dominance in experiential lodging corridors. France's TGV infrastructure links Paris to Provence and the Loire Valley, enabling weekend leisure migration patterns. Spain's AVE network has compressed travel times between Madrid and Andalusian heritage clusters.
Italy
Agriturismo conversion demand and culinary tourism anchor property development in Tuscany and Umbria. The EU Green Deal channels retrofit subsidies toward carbon-neutral certification of historic farmhouses. Florence's Oltrarno district and Siena's Val d'Orcia corridor concentrate luxury-tier inventory expansion.
France
Heritage preservation tax credits from ANSM-registered local authorities reduce capital barriers for château conversions in the Loire Valley. GDPR-compliant booking platforms invest in privacy-preserving personalization to retain guest data within regulatory boundaries. Provence's Luberon region and Normandy's coastal towns drive themed-property development tied to wine and maritime heritage.
Spain
Short-term rental caps in Barcelona and Madrid redirect investor attention toward Extremadura and Galicia's underpenetrated secondary cities. The EU AI Act imposes algorithmic transparency requirements on Madrid-based booking cooperatives deploying recommendation engines. Seville's historic center and Granada's Albaicín district face zoning enforcement intensification that constrains new inventory.
United Kingdom
Cotswolds conservation area designations protect Victorian architectural character while enabling premium-rate positioning. The Information Commissioner's Office enforces GDPR mandates on London-based platform operators processing guest preference data. Edinburgh's New Town and Cornwall's coastal villages concentrate rustic-property conversions targeting domestic leisure travelers.
Portugal
Alentejo's wine heritage corridors and Porto's azulejo-adorned colonial properties attract design-conscious European travelers. The country's national tourism regulator monitors compliance with EU-wide data handling mandates for small-scale operators. Lisbon's Alfama district and the Douro Valley's quinta conversions exemplify narrative-driven themed lodging development.
Bed and Breakfast Accommodation Market Competitive Landscape
On the supply side, the industry is bifurcated between platform intermediaries controlling guest acquisition pipelines and fragmented independent operators managing single or small property portfolios. Scaled digital marketplaces leverage host network density and compliance infrastructure to consolidate booking volume. Two strategic archetypes dominate: algorithmic platforms optimizing search visibility and inventory aggregation, and hospitality conglomerates extending brand architecture into boutique segments. Competitive moves center on portfolio diversification into experiential packaging and geographic expansion through host acquisition programs.
Within the platform intermediary tier, Airbnb and Booking.com occupy positions as dominant traffic allocation systems with opaque ranking mechanics that determine independent operator occupancy rates. Among hospitality conglomerates, Marriott International exemplifies brand architecture extension into curated collection tiers that compete with independent boutiques on service intensity. Expedia Group sits within the bundled packaging archetype, merging boutique stays with experiential add-ons to differentiate against standalone accommodation marketplaces.
| Leading Market Players |
|---|
| Airbnb |
| Booking.com |
| Expedia Group |
| OYO Hotels & Homes |
| Marriott International |
| InterContinental Hotels Group |
| Hilton Worldwide Holdings |
| Accor |
| Wyndham Hotels & Resorts |
| Others |
Pricing and Supply Chain Analysis
Platform algorithmic dependency risk determines both pricing tier spreads and supply chain shape in bed and breakfast accommodation. Operators tethered to Airbnb and Booking.com ranking systems face compressed direct-booking margins that reshape procurement priorities toward commission-absorbing efficiency rather than experiential investment.
Pricing Analysis
Volume-discount tiering structures separate luxury service tier properties from standard owner-operated inventory. Three-tier pricing stratifies across chef-prepared gastronomic experiences, continental breakfast baseline offerings, and economy conversions in secondary markets. Price differentiation hinges on heritage certification status and host-curated experiential bundling. Cost compression in standard tier properties is intensifying because platform commission structures absorb fifteen to twenty percent of gross booking value. Corporate bleisure travelers demonstrate lowest price sensitivity while domestic leisure segments in Portugal's interior regions exhibit highest elasticity.
Supply Chain Analysis
Supplier-financing facilities from Italian agricultural cooperatives and French heritage renovation lenders extend payment terms for farmhouse conversion materials. Artisanal provisioning draws from Spain's Extremadura grain cooperatives, Portugal's Alentejo wine consortiums, and Dutch specialty dairy distributors. Raw material dependencies center on heritage-grade timber, azulejo ceramic restoration supplies, and carbon-neutral insulation systems. Single-source vulnerability concentrates in GDPR-compliant booking platform technology where scaled intermediaries control guest acquisition pipelines. Distribution runs through platform-mediated discovery systems with direct-channel bypass via WhatsApp Business API emerging as secondary pathway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act algorithmic transparency mandates constitute a regulatory inflection that accelerates market consolidation toward compliance-capable scaled platforms. This disruption compresses competitive timelines for independent operators and cooperative intermediaries.
For Market Incumbents: Harden platform dependency defenses through WhatsApp Business API direct-channel infrastructure and GDPR-compliant guest data retention systems. Independent operators should pursue carbon-neutral certification via EU Green Deal retrofit subsidies to escape algorithmic visibility commoditization. Portfolio scale economics now dominate single-location hospitality intensity as cloud-based property management virtualizes operational workflows.
For New Entrants and Emerging Players: Underpenetrated secondary cities in Spain's Extremadura corridor and Portugal's interior Alentejo region represent the most penetrable entry points for themed properties tied to wine heritage and medieval architecture. Narrative-driven design concepts anchored in regional storytelling bypass urban luxury hotel competition. Go-to-market execution should leverage agriturismo infrastructure grant programs for capital-efficient farmhouse conversion entry.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward platform intermediaries with dedicated regulatory technology teams and privacy-preserving machine learning capabilities. Long-term viability favors portfolio-scale operators capable of single-host multi-property management through cloud-based channel managers. Monitor short-term rental cap enforcement intensity in Barcelona, Amsterdam, and Lisbon as early signals of inventory expansion constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Direct Channel Development | WhatsApp Business API integration bypasses platform commissions while preserving guest communication workflows. |
| EU Green Deal Retrofit Certification | Carbon-neutral historic farmhouse status commands premium positioning among sustainability-conscious leisure travelers. |
| Themed Property Narrative Development | Wine heritage and medieval architecture storytelling creates booking urgency through scarcity and regional authenticity. |
| Portfolio Scale Technology Adoption | Cloud-based channel managers enable single-host management of multiple dispersed properties restructuring competitive economics. |
| Secondary City Geographic Expansion | Extremadura and Alentejo corridors offer low-competition positioning outside enforcement-capped urban cores. |
Research Methodology
A standing panel of bed and breakfast property owners, platform revenue management specialists, heritage preservation architects, and agriturismo program administrators provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from EU tourism statistics, national heritage board certification records, GDPR enforcement case databases, and short-term rental regulatory filings. Bottom-up property inventory modeling and top-down platform transaction estimates were triangulated for convergence.
Scenario-bracketing framed projections across the analysis window with segmentation dimensions spanning property type, service tier, guest composition, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating rail infrastructure expansion timelines and agriturismo grant program allocations. Forecast inputs included platform algorithmic visibility coefficients and heritage preservation tax credit renewal probabilities.
Practitioners should monitor platform commission structure revisions and municipal short-term rental enforcement intensity for early signals of margin compression or inventory constraint. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and EU Green Deal subsidy continuity. Macroeconomic downturn in leisure travel expenditure, accelerated algorithmic transparency enforcement, or retroactive heritage zoning restrictions would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
United States Online Accommodation Market
Accommodation
Canada Hospitality Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Hotel Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
China Tourism and Hotel Market
Accommodation
Airport Lounges Market
Accommodation
Underwater Hotels Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Japan Hospitality Market
Accommodation
India Online Accommodation Market
Accommodation
Croatia Hospitality Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
France Online Accommodation Market
Accommodation
Airport Sleeping Pods Market
Accommodation
France Hospitality Market