
 United States Business Travel Market | 2026-2036
United States Business Travel Market Size, Share, and Industry Trends Forecast 2026-2036
United States Business Travel Market Intelligence
Artificial intelligence-driven itinerary optimization is reconfiguring how corporate travel programs manage spend and traveler experience. American Express Global Business Travel leverages proprietary machine-learning algorithms to predict price volatility and enforce policy compliance across enterprise accounts. SAP Concur anchors its position through deep ERP integration that automates expense reconciliation from booking to reimbursement. Navan competes aggressively on user experience, offering instant mobile-first booking that bypasses traditional approval bottlenecks.
United States business travel encompasses the commercial movement of employees and executives for meetings, client engagements, training, and incentive programs, typically involving air transportation, hotel accommodation, ground transport, and ancillary services booked through corporate platforms or managed travel agencies. The sector operates on negotiated corporate rates, dynamic fare structures, and centralized billing systems designed to balance traveler satisfaction with cost control mandates. Transportation and accommodation capture the dominant share of spend, though corporate travel platforms represent the fastest-growing booking channel as enterprises abandon fragmented email-and-phone workflows. Government agencies constitute a mature, compliance-heavy client segment with rigid per-diem structures and federal travel regulation requirements.
The FAA regulates air carrier operations and route accessibility that directly determines viable business travel corridors, while the Department of Transportation enforces consumer protection standards affecting ticket flexibility and refund policies. Corporate travel managers must navigate IRS substantiation rules for deductible travel expenses alongside state-level lodging tax variations that alter total trip cost calculations. Stakeholders should monitor how NHTSA autonomous vehicle guidelines reshape ground transport economics and whether TSA credentialing programs accelerate airport throughput for frequent business travelers.
Market Dynamics
The FAA's NextGen airspace modernization is compressing flight delays and reconfiguring route economics for high-frequency business corridors. Corporate travel managers now prioritize schedule reliability over base fare in vendor negotiations.
Growth Catalysts
- Technology firm expansion:Enterprise software and cloud computing companies are enlarging client-facing travel budgets to secure multi-year service contracts. Field engineering teams require sustained air access to customer data centers.
- FAA NextGen deployment:Precision navigation capabilities are reducing weather-related cancellations on business-heavy routes. Dallas-Fort Worth and Houston hubs report improved on-time performance for connecting itineraries.
- Energy sector concentration:Texas-based oilfield services and renewable energy developers generate sustained premium cabin demand for remote site inspections. Midland-Odessa and Corpus Christi routes maintain year-round load factors.
Market Restraints
- Jet fuel price volatility:Crude oil fluctuations compress carrier margins on corporate contract routes. Airlines pass cost uncertainty through to enterprise accounts via fuel surcharge clauses.
- Hub concentration risk:Dallas-Fort Worth and Atlanta handle disproportionate business volume. Weather or operational disruptions at these nodes cascade through national corporate travel networks.
- IRS substantiation complexity:Documentation requirements for deductible travel expenses create administrative friction. Finance teams must reconcile per-diem receipts against federal rate tables for audit defense.
Strategic Opportunities
- Secondary city penetration:Austin and Nashville host expanding technology and healthcare headquarters. These markets lack sufficient direct corporate air service relative to resident enterprise demand.
- Sustainable aviation fuel mandates:The IRA provides tax credits for low-carbon jet fuel production. Corporate travel programs can secure verified emission reductions for ESG reporting requirements.
- Ground transport electrification:NHTSA guidelines on autonomous vehicle deployment are reshaping airport-to-downtown economics. Fleet operators can reduce per-mile costs below traditional black car services.
Industry Challenges
- Travel manager talent scarcity:Professionals capable of negotiating complex airline and hotel contracts command premium compensation. Enterprises struggle to retain expertise against technology vendor recruitment.
- Legacy platform integration:ERP systems from prior decades require custom middleware to connect with modern booking tools. IT departments face extended timelines for unified expense management deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Business Travel Market |
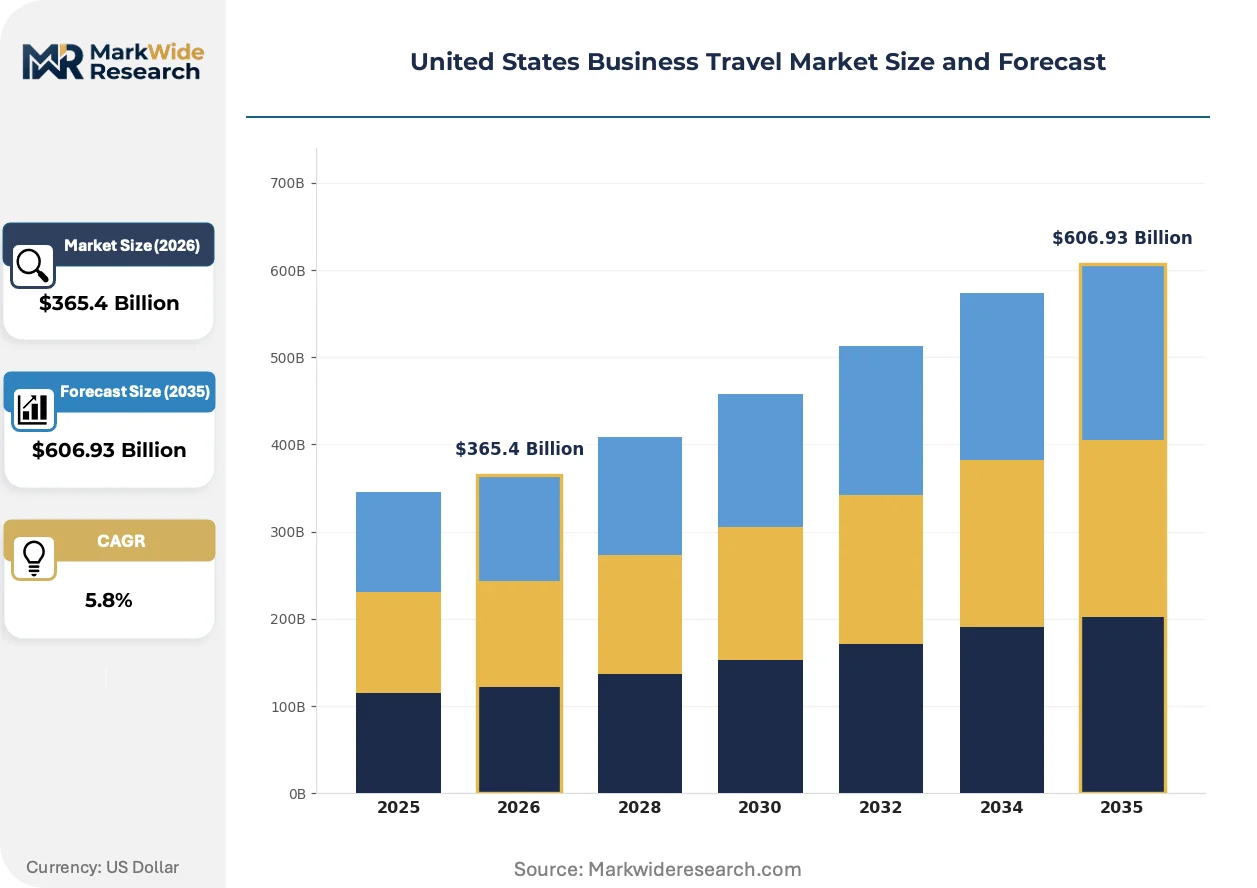
| Market Size in 2026 | $365.4 Billion |
| Market Size in 2035 | $606.93 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Accommodation, Food & Beverage, Meeting Services Client Type: Corporations, SMEs, Freelancers, Government Agencies Booking Channel: Online Travel Agents, Direct Booking, Travel Management Companies, Corporate Travel Platforms Travel Purpose: Meetings, Conferences, Incentive Travel, Training |
| Companies Covered | Internova Travel Group, Reed & Mackay, Navan, FCM Travel, Perk, American Express Global Business Travel, SAP Concur, Sabre Corporation, Expedia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Business Travel Market Strategic Shifts & Innovations
Artificial intelligence is compressing the gap between traveler preference and policy compliance. Machine learning now predicts price movements and automates rebooking decisions without human intervention.
Generative AI itinerary assistants are migrating from experimental pilots to core enterprise deployments. Fortune 500 travel programs are adopting these tools for instant policy-aware booking suggestions. The technology is migrating from cost-center automation to strategic traveler satisfaction management, reducing helpdesk call volume by handling routine change requests.
The FAA's ongoing NextGen implementation is mandating performance-based navigation standards for commercial operators. Airlines must upgrade avionics to maintain access to preferred business routes. Carriers serving Texas energy corridors are prioritizing equipage to capture high-yield corporate volume.
Corporate procurement departments are consolidating travel spend under fewer, larger agency relationships. Mid-market enterprises previously using fragmented booking tools are migrating to integrated platforms with embedded policy engines. This concentration is most visible in financial services, where compliance requirements favor centralized data capture over traveler convenience.
United States Business Travel Market Segmentation
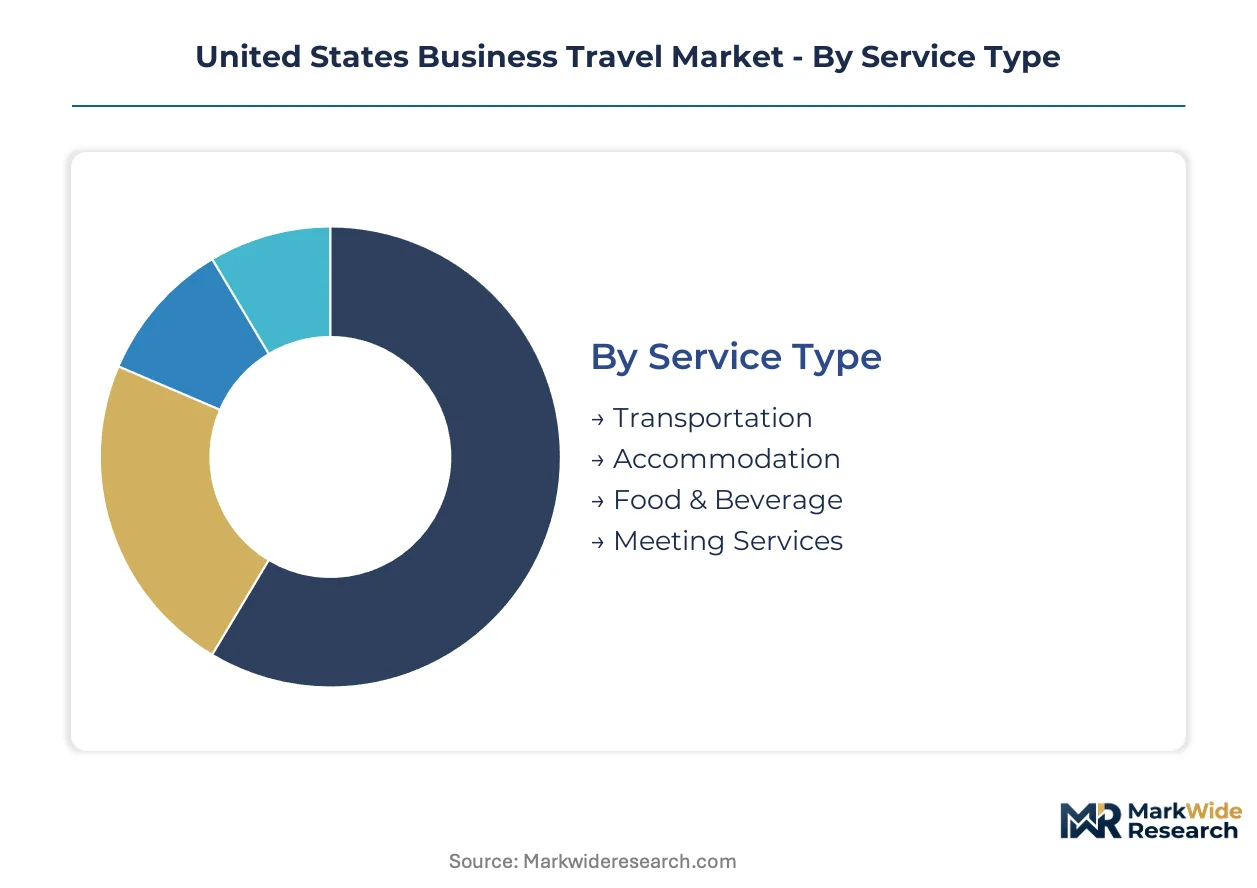
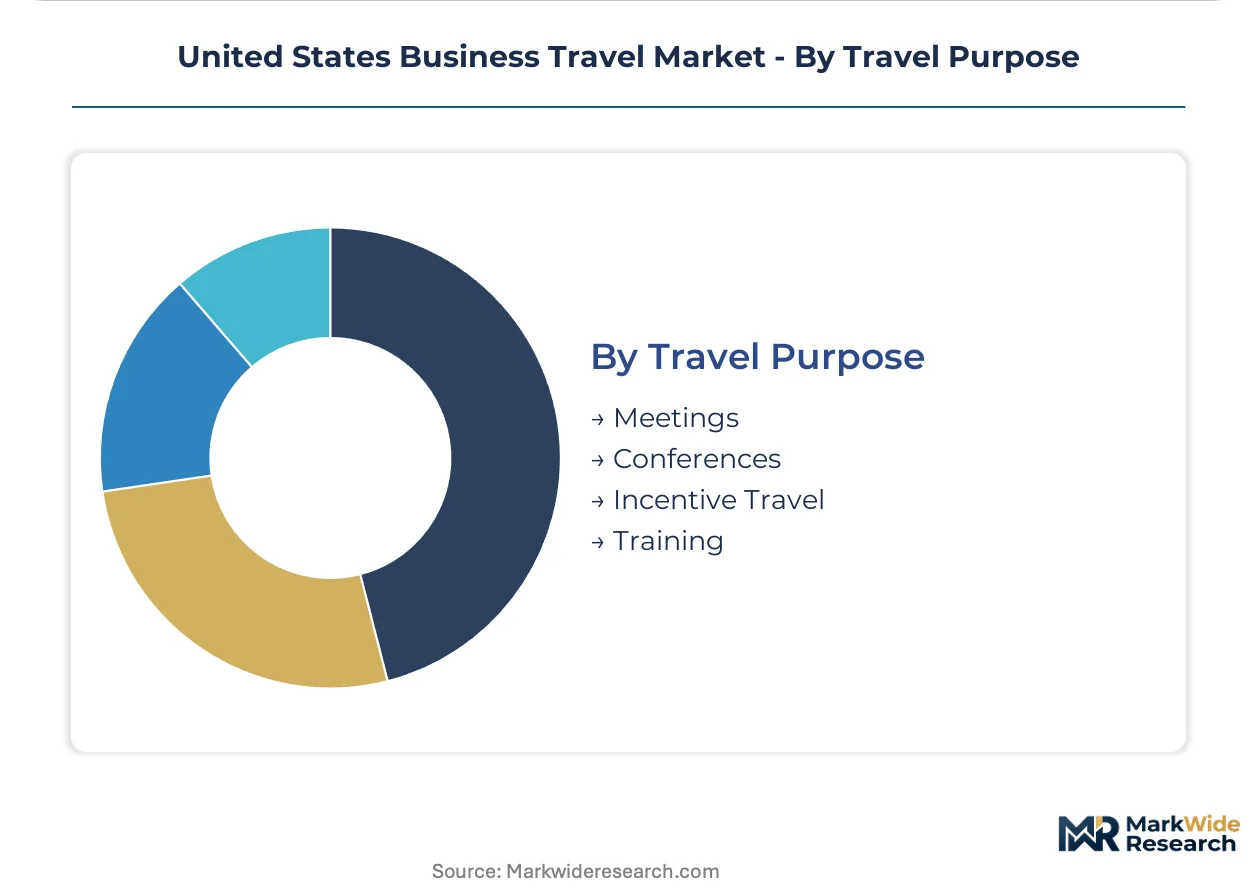
Corporate travel managers structure procurement around service economics, client scale, booking technology, and trip purpose. Each dimension reveals distinct vendor strategies and cost control priorities across the United States market.
Service Type:
Cost tier determines vendor negotiation leverage and policy enforcement complexity within enterprise programs.
- Transportation:Air carriers and ground transport providers command the largest share of managed spend. Texas energy corridors generate sustained premium cabin demand for remote site access, with Houston and Dallas-Fort Worth serving as dominant hubs.
- Accommodation:Hotel inventory concentrates in downtown financial districts and airport submarkets. Negotiated corporate rates with major chains anchor enterprise programs, though extended-stay properties capture field engineering deployments.
- Food & Beverage:Per-diem structures and receipt substantiation requirements create administrative overhead. IRS rate tables govern deductible thresholds across metropolitan statistical areas.
- Meeting Services:Conference facilities and event logistics support training and incentive programming. Procurement teams bundle these with accommodation contracts for volume leverage.
Transportation commands the established base. The steepest expansion runs through Corporate Travel Platforms as enterprises abandon fragmented booking workflows.
Client Type:
Customer scale shapes contract structure, policy rigidity, and technology adoption timelines.
- Corporations:Fortune 500 enterprises negotiate multi-year managed travel agreements with dedicated account management. Field engineering teams at cloud computing firms require sustained air access to customer data centers.
- SMEs:Mid-market companies migrate from fragmented email-and-phone workflows toward integrated platforms with embedded policy engines. Compliance requirements favor centralized data capture.
- Freelancers:Independent contractors book through consumer channels without corporate rate access. Reimbursement friction limits their participation in formal programs.
- Government Agencies:Federal, state, and local entities operate under rigid per-diem structures and federal travel regulation requirements. The General Services Administration negotiates government-wide contracts.
Corporations anchor volume concentration. SMEs are gaining share fastest as platform economics democratize managed travel capabilities.
Booking Channel:
Technology maturity determines traveler experience, policy compliance rates, and finance team reconciliation burden.
- Online Travel Agents:Consumer-facing platforms capture unmanaged and incidental travel bookings outside corporate programs. Policy leakage through these channels frustrates travel managers.
- Direct Booking:Supplier websites and call centers bypass intermediary fees but fragment data capture. Enterprises sacrifice visibility for rate transparency in specific scenarios.
- Travel Management Companies:Traditional agencies retain government and compliance-heavy accounts requiring human intervention. Agent-assisted rebooking handles complex itinerary disruptions.
- Corporate Travel Platforms:Integrated tools with ERP connectivity automate expense reconciliation from booking to reimbursement. Machine-learning algorithms now predict price volatility and enforce policy compliance.
Travel Management Companies retain legacy accounts. Corporate Travel Platforms climb the fastest as procurement departments consolidate spend under fewer technology relationships.
Travel Purpose:
Application type drives destination selection, duration patterns, and ancillary service bundling.
- Meetings:Client-facing engagements justify premium cabin bookings and flexible fare structures. Technology firms are enlarging these budgets to secure multi-year service contracts.
- Conferences:Industry events concentrate demand in specific cities during narrow date windows. Hotel inventory compression in Austin and Nashville strains corporate rate availability.
- Incentive Travel:Reward programming operates outside standard policy frameworks with elevated experience requirements. Procurement exercises limited cost control leverage.
- Training:Internal capability development follows predictable schedules enabling advance purchase discounts. Extended-stay accommodation patterns reduce per-night costs.
Meetings anchor revenue stability. Conferences expand most quickly as technology and healthcare sector events proliferate in secondary city markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic business travel corridors connect Texas energy hubs to coastal technology centers, with corporate spend concentrating in metropolitan statistical areas where federal infrastructure investment intersects with sector-specific demand.
Texas
Houston and Dallas-Fort Worth anchor the national market through energy sector field operations and financial services headquarters. FAA NextGen precision navigation upgrades at both hubs compress weather-related delays for connecting corporate itineraries. Midland-Odessa routes sustain year-round premium cabin demand from oilfield services deployment.
California
San Francisco Bay Area technology firms expand client-facing travel budgets to secure enterprise software contracts. State-level carbon disclosure mandates push corporate travel managers toward verified sustainable aviation fuel procurement. Los Angeles International serves as the primary Pacific gateway for Asia-Pacific executive routes.
New York Metro
Financial services concentration generates high-frequency shuttle demand to Washington DC and Boston corridors. IRS substantiation requirements for deductible travel expenses create administrative complexity for firms with multi-state employee bases. Newark Liberty's slot-controlled capacity limits peak-hour corporate schedule flexibility.
Illinois
Chicago O'Hare functions as the dominant Midwest connecting hub for manufacturing sector travel to coastal markets. TSA credentialing programs for frequent travelers accelerate throughput at Terminal 3 business-heavy checkpoints. Downtown hotel inventory concentrates along the Loop financial district.
Florida
Miami and Orlando capture conference and incentive travel demand from healthcare and technology sectors. State-level lodging tax variations alter total trip cost calculations for corporate finance teams. Tampa's expanding fintech presence generates new origin-destination demand absent sufficient direct air service.
United States Business Travel Market Key Industry Players
Channel-controlling players compete with product-specialist players across three structural tiers. Integrated travel management companies with legacy airline relationships anchor the premium segment, while technology-native platforms capture mid-market share through embedded policy engines. Consolidation pressure intensifies as procurement departments reduce supplier counts. Dominant competitive moves include strategic partnerships between booking platforms and expense management systems, plus portfolio diversification into meetings and events services.
Among legacy travel management specialists, Internova Travel Group and Reed & Mackay occupy positions emphasizing agent-assisted service for compliance-heavy accounts. Within the technology-native tier, Navan exemplifies mobile-first user experience design, while American Express Global Business Travel represents the hybrid model combining proprietary machine-learning algorithms with established corporate relationships. SAP Concur anchors the ERP-integrated segment through automated expense reconciliation capabilities.
| Leading Market Players |
|---|
| Internova Travel Group |
| Reed & Mackay |
| Navan |
| FCM Travel |
| Perk |
| American Express Global Business Travel |
| SAP Concur |
| Sabre Corporation |
| Expedia Group |
| Others |
Cost & Logistics Intelligence
Houston and Dallas-Fort Worth hub concentration compresses carrier margins on corporate contract routes while amplifying airline pricing power during peak energy sector travel windows. Enterprise travel managers face fuel surcharge pass-through clauses that index directly to crude oil futures, eroding budget predictability.
Pricing Analysis
Fuel-plus contracts with jet fuel indexation dominate corporate airline agreements, exposing enterprise accounts to crude volatility pass-through. Price differentiation separates premium cabin corporate rates from restricted economy inventory through negotiated volume commitments and last-seat availability guarantees. Cost compression in mid-tier accommodation runs through extended-stay property expansion near airport submarkets. SMEs exhibit highest price sensitivity due to fragmented booking workflows lacking volume leverage, while Fortune 500 accounts secure fixed-rate multi-year blocks.
Supply Chain Analysis
Export-control restrictions on aviation software and navigation technology limit avionics supplier flows to certified vendors. Aircraft manufacturing concentrates in the United States, France, and Brazil, with engine production anchored in the United Kingdom and United States. Supply chain risk centers on single-source vulnerability for precision navigation components required under FAA NextGen mandates. Distribution runs through global distribution systems connecting carriers to corporate travel platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
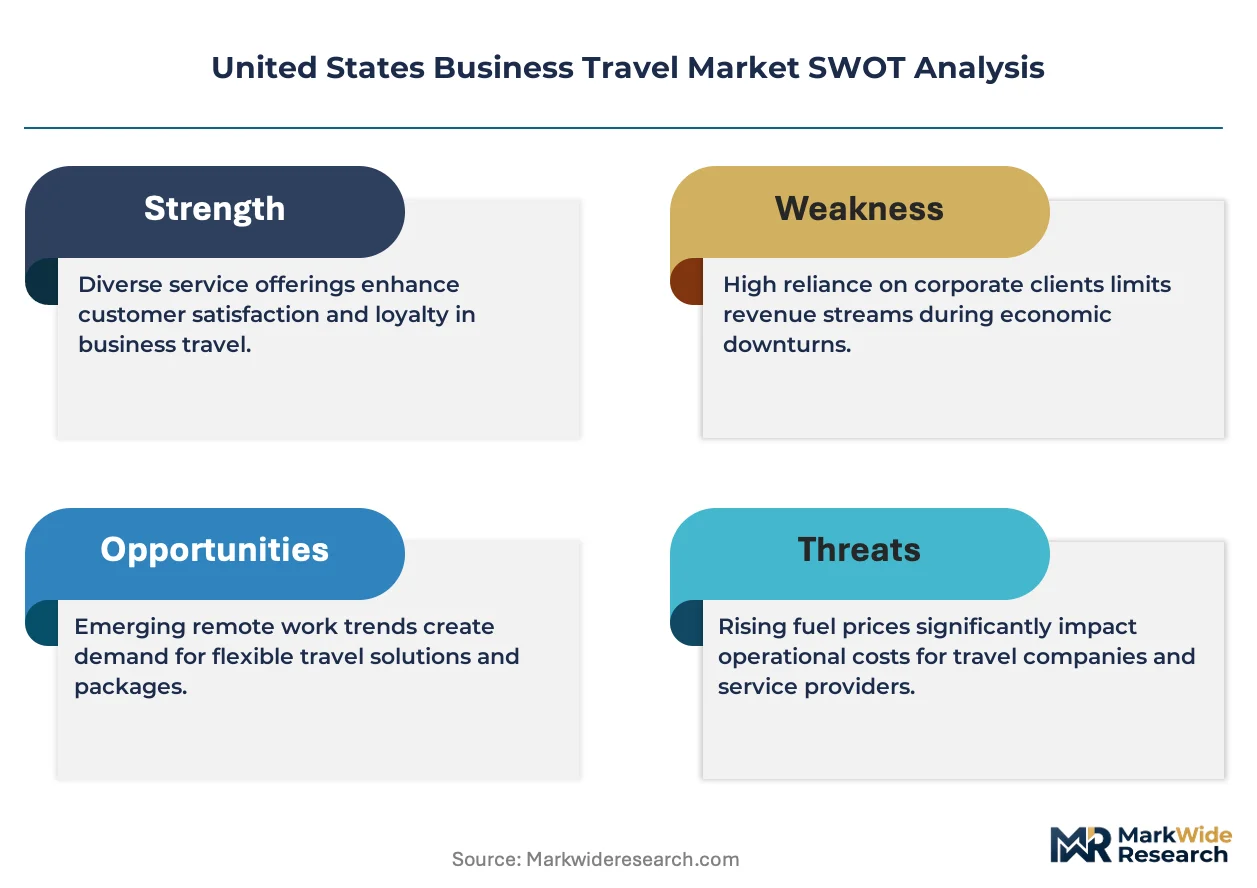
Fragmentation across the United States business travel market creates niche opportunities as procurement departments abandon fragmented email-and-phone workflows for integrated platforms. Technology-native entrants capture mid-market share while legacy agencies defend compliance-heavy government accounts.
For Market Incumbents: Build data moats through ERP integration depth that automates expense reconciliation from booking to reimbursement. Incumbents should deepen machine-learning algorithm investment to predict price volatility before emerging platforms match capability. Threat from Navan-style mobile-first entrants demands accelerated user experience parity. Channel control through exclusive airline content agreements anchors defensive positioning. For New Entrants and Emerging Players: Pursue secondary city corporate air service gaps in Austin and Nashville where technology headquarters expansion outpaces direct route availability. White-space targets include sustainable aviation fuel verification services for ESG reporting and autonomous ground transport fleet economics below traditional black car rates. Go-to-market through SME procurement departments consolidating fragmented spend under single platform relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ERP-integrated travel management platforms with automated policy enforcement over agent-assisted legacy models. Long-term viability hinges on AI-driven itinerary optimization becoming table stakes rather than differentiator. Acquisition targets include expense management middleware specialists bridging legacy systems to modern booking tools. Signal to watch is TSA credentialing program expansion accelerating airport throughput for frequent business travelers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP connectivity automates expense reconciliation from booking through reimbursement for enterprise accounts. |
| Strategic Partnership | Airline content agreements with United and American secure last-seat availability for corporate volume commitments. |
| Product Launch | Generative AI itinerary assistants reduce helpdesk call volume by handling routine change requests instantly. |
| Acquisition of Specialist Firm | Middleware providers bridge legacy systems to modern booking tools, accelerating unified deployment timelines. |
| Geographic Expansion | Secondary city penetration in Austin and Nashville captures technology sector demand absent sufficient direct air service. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC airline filings, GSA contract databases, and FAA operational performance data. Primary interviews engaged corporate travel managers, airline revenue management executives, enterprise procurement officers, and travel technology platform engineers. Secondary sources included Department of Transportation consumer protection standards, IRS substantiation guidelines, and NextGen implementation progress reports. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs incorporate service type segmentation, client scale tiers, booking channel migration patterns, and travel purpose economics across the projection horizon. Modeled dimensions span transportation versus accommodation spend, corporate versus SME versus government agency profiles, and platform versus agency booking flows. CAGRs derive from trend extrapolation of technology firm travel budget expansion and FAA infrastructure deployment schedules. Industry-specific inputs include jet fuel price trajectory assumptions and sustainable aviation fuel tax credit utilization rates.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands or corporate capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on NextGen equipage timelines and TSA throughput program expansion. Material shifts in federal travel regulation requirements or airline consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
Latin America Business Travel Market
Business Travel Services
Business Travel Lodging Market
Business Travel Services
Brazil Business Travel Lodging Market
Business Travel Services
Bleisure Travel Market
Business Travel Services
Business Travel Market
Business Travel Services
Europes Golden Generation Travel Market
Business Travel Services
Europe Business Travel Market
Business Travel Services
Airline a-La-Carte Services Market