
 US Recreational and Vacation Camp Market | 2026-2036
US Recreational and Vacation Camp Market Size, Share, and Industry Trends Forecast 2026-2036
US Recreational and Vacation Camp Market Insights
All-inclusive pricing bundling lodging, meals, and structured activities is rebalancing buyer choice toward simplified booking decisions. Kampgrounds of America leverages its franchise network to sustain roadside accessibility across interstate corridors. Great Wolf Lodge anchors indoor water park resort concepts that compete with traditional seasonal camps year-round. YMCA operates nonprofit community camps that differentiate through subsidized access and urban outreach programs.
US recreational and vacation camps are supervised outdoor facilities providing temporary accommodation, programmed activities, and communal dining across natural settings, typically operating on leased or owned rural land with capacity ranging from fifty to five hundred participants per session. These camps serve child development, family leisure, and corporate retreat functions through structured immersion in wilderness or recreation-focused environments. Overnight camps command premium pricing due to extended supervision requirements and dedicated cabin infrastructure, while specialized camps in STEM and adaptive programming represent the fastest-expanding category as parents prioritize skill-building outcomes. Family camps occupy a mature but stable position with repeat-booking loyalty, whereas day camps capture volume through municipal partnerships and school district summer programming.
American Camp Association accreditation standards, state health department licensing frameworks, and USDA summer food service program compliance collectively shape operational viability and parent trust in camp selection. OSHA workplace safety rules and state environmental agency permits for waterfront activities further constrain site expansion and program design. Stakeholders must monitor evolving state childcare licensing thresholds and ACA outcome-measurement requirements to maintain competitive positioning.
Market Dynamics
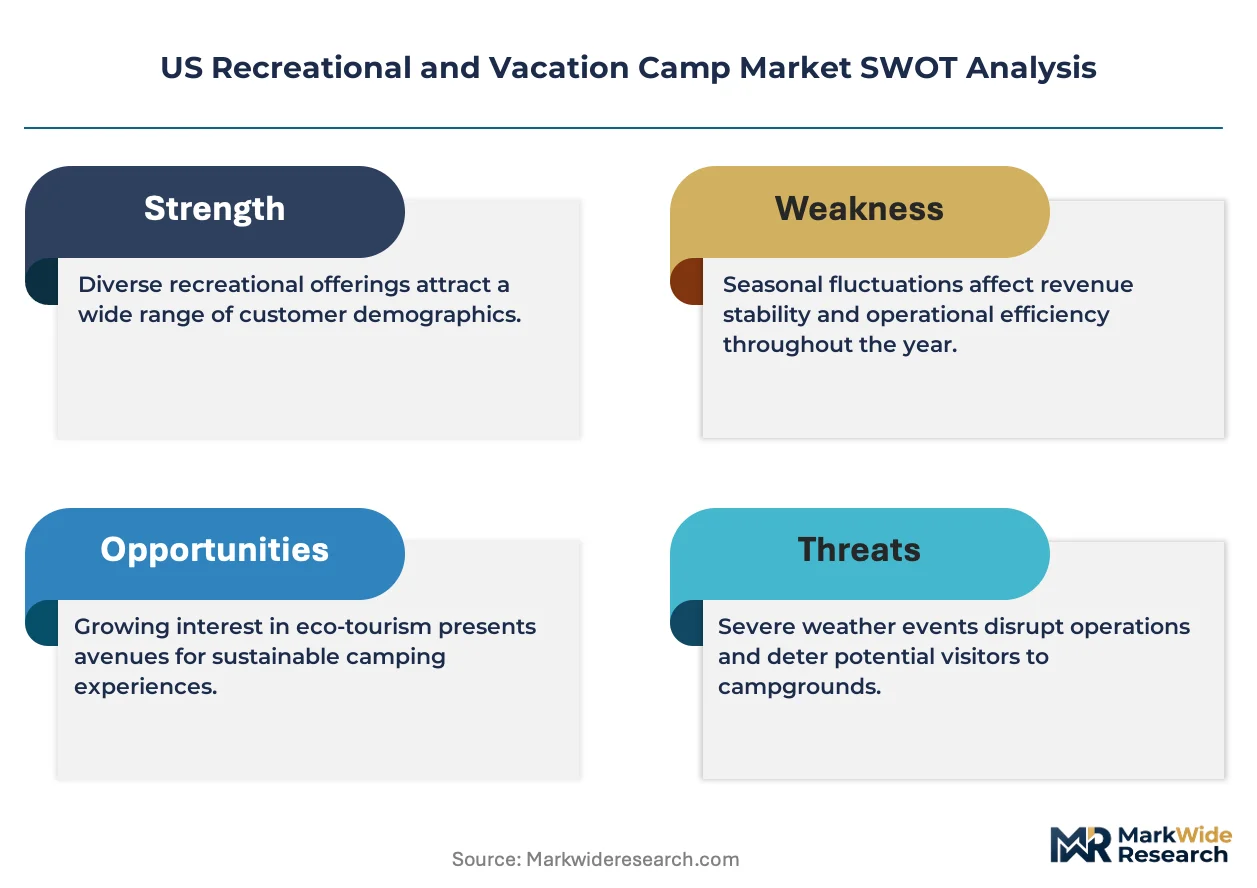
ACA accreditation standards are compressing the operational gap between established camps and marginal operators, forcing capital reinvestment in waterfront safety infrastructure and outcome-measurement systems that reshape competitive viability across state licensing jurisdictions.
Growth Catalysts
- OSHA workplace safety enforcement:Heightened inspection protocols for seasonal staff housing and activity equipment are elevating baseline operational standards that parents now expect as table stakes for enrollment decisions.
- STEM programming integration:Robotics and environmental science curricula are attracting dual-income households seeking structured skill-building outcomes during summer breaks.
- Mountain West seasonal density:Concentrated camp infrastructure across Colorado, Utah, and Montana generates network effects in staff recruitment and shared emergency response systems.
Market Restraints
- USDA summer food service compliance costs:Nutritional documentation and meal pattern requirements impose fixed administrative burdens that scale poorly for camps under one hundred participants.
- Limited waterfront permit availability:State environmental agency caps on lake access and dock construction in the Northeast corridor constrain site expansion for established operators.
- Seasonal labor supply volatility:J-1 visa processing delays and competing hospitality wages compress staffing reliability for eight-week operating windows.
Strategic Opportunities
- Adaptive programming for neurodiverse children:Specialized sensory-friendly cabins and trained behavioral staff address underserved demand from families excluded from traditional camp structures.
- Corporate retreat vertical:Off-site team-building contracts with technology and professional services firms extend revenue into shoulder seasons with higher per-capita yields.
- Interstate franchise corridor networks:Roadside accessibility along I-70, I-80, and I-90 corridors enables multi-site booking loyalty and shared inventory management systems.
Industry Challenges
- Specialized aquatics certification timelines:American Red Cross lifeguard and wilderness first responder credentials require six-month lead times that misalign with February-April hiring cycles.
- Cabin infrastructure modernization:ADA-compliant lodging upgrades and climate resilience investments demand capital deployment that exceeds depreciation schedules for family-owned operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Recreational and Vacation Camp Market |
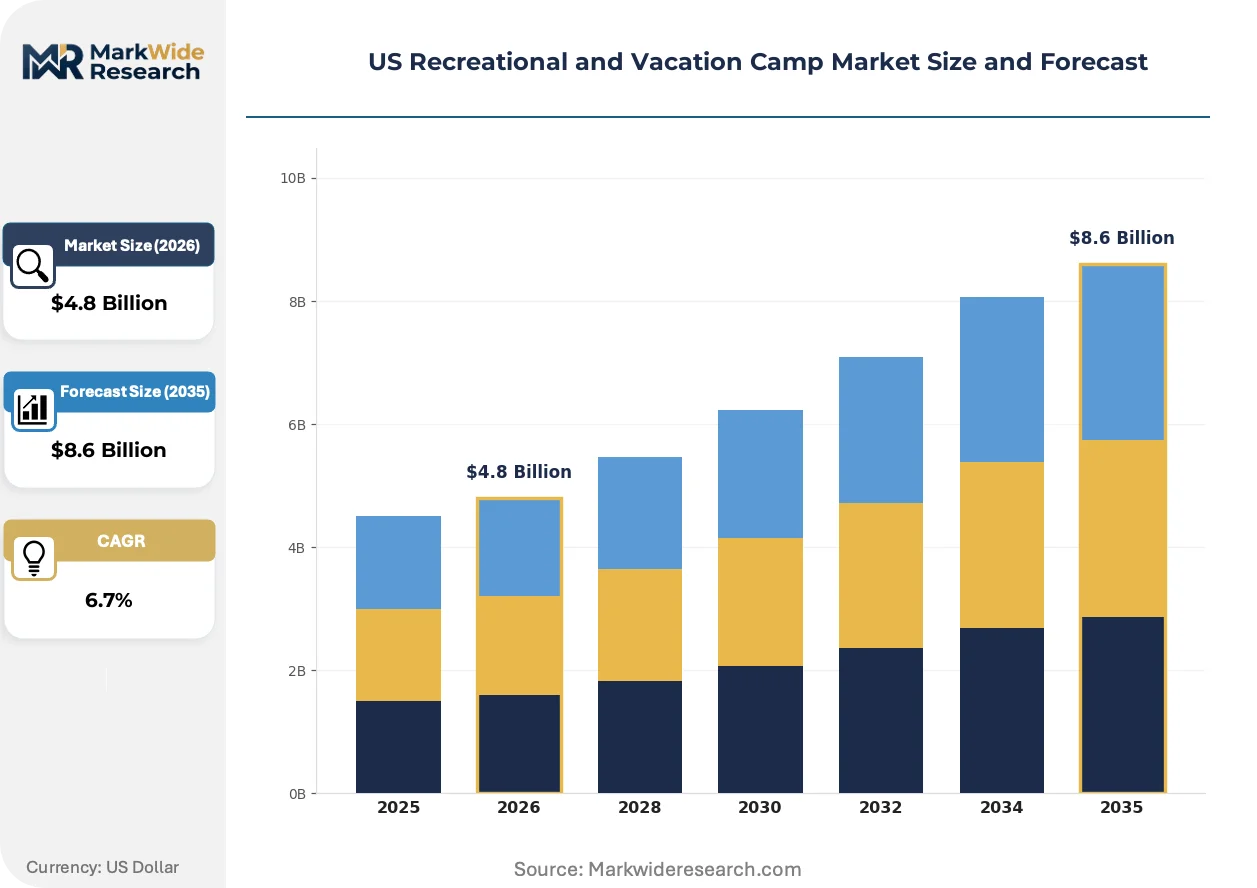
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camp Type: Day Camps, Overnight Camps, Specialized Camps, Family Camps Activity Focus: Adventure, Sports, Arts & Crafts, Nature Exploration Target Audience: Children, Teens, Families, Adult Retreats Facilities: Lodging, Dining Halls, Activity Centers, Nature Trails |
| Companies Covered | American Camp Association, YMCA, Outward Bound USA, Camp Bow Wow, Kampgrounds of America, Girl Scouts of the USA, Great Wolf Lodge, CampGroup, Galileo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Recreational and Vacation Camp Market Trends and Innovations
Digital registration and parent communication platforms are compressing the information asymmetry that historically separated camp operators from enrollment decision-makers, while biometric check-in systems and real-time activity tracking reshape safety accountability expectations.
Cloud-based camp management software is decentralizing administrative control from central offices to individual program directors, enabling same-day schedule adjustments based on weather and participant energy levels. Millennial parents accustomed to real-time visibility into childcare settings are adopting these platforms at rates exceeding eighty percent for camps offering mobile dashboard access. This capability compression is flattening the operational advantage that large multi-site operators previously held over independent single-location camps.
State health department licensing frameworks are tightening staff-to-camper ratio requirements for overnight programs, particularly for waterfront and ropes course activities. The industrial consequence is accelerated consolidation as sub-scale operators exit rather than absorb compliance infrastructure costs. Northeast corridor states including New York and Massachusetts are experiencing the most aggressive enforcement, prompting established camps to acquire distressed assets for permit transfer value rather than greenfield development.
All-inclusive pricing bundling lodging, meals, and structured activities is displacing à-la-carte enrollment models that previously dominated family camp segments. Parents facing decision fatigue in fragmented leisure markets are gravitating toward simplified booking experiences with transparent total cost disclosure. This pattern is most visible in Colorado and California markets where dual-income households prioritize time efficiency over customization flexibility.
US Recreational and Vacation Camp Market Segmentation
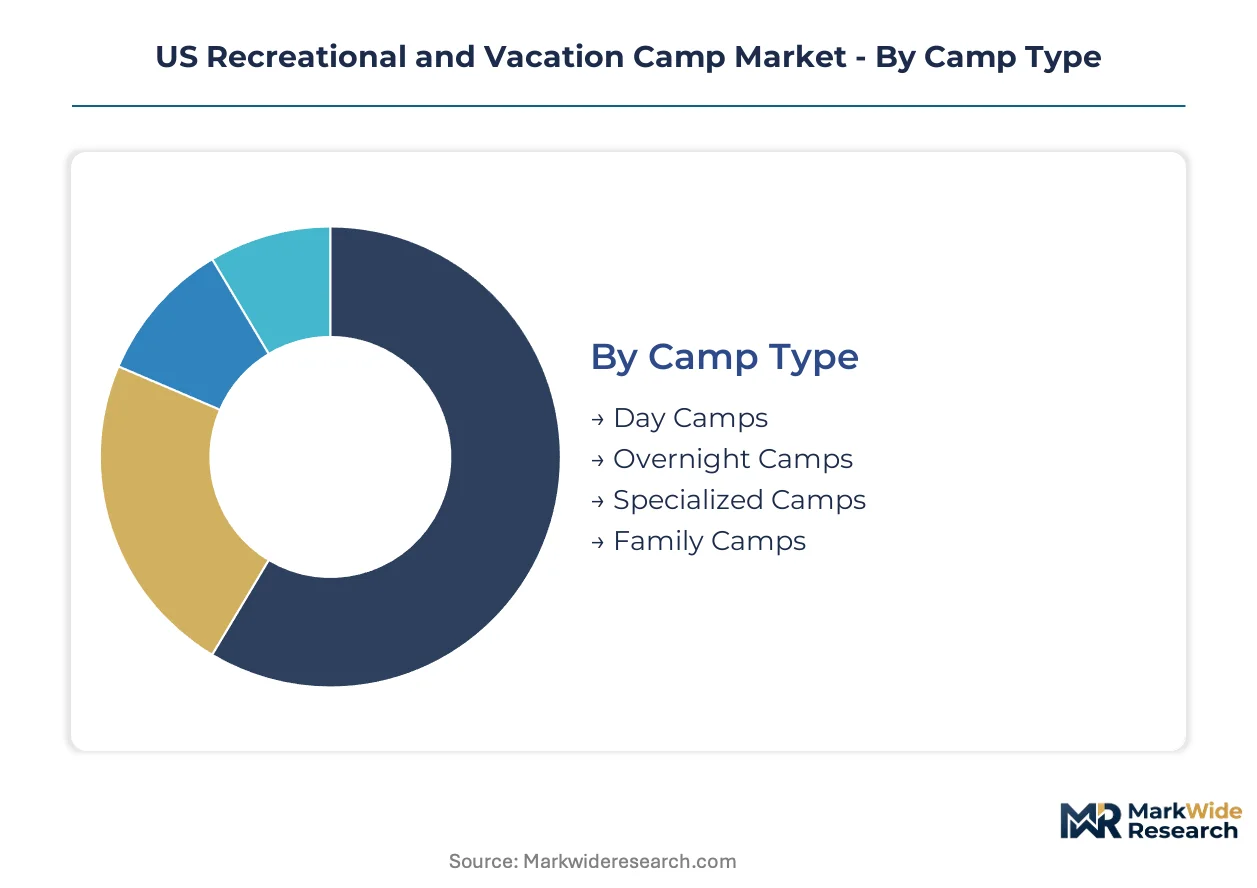
Segmentation reveals how ACA accreditation standards and state licensing frameworks create divergent compliance burdens across camp configurations. Operators must align capital deployment with segment-specific certification timelines and infrastructure requirements.
Camp Type:
ACA accreditation and state health department licensing impose tiered certification burdens: overnight programs face the most stringent staff-to-camper ratios and waterfront safety mandates, while day camps navigate municipal partnerships with lighter oversight.
- Overnight Camps:Extended supervision requirements and dedicated cabin infrastructure command premium pricing. Colorado and Utah operators concentrate investment here due to Mountain West seasonal density and established emergency response networks.
- Specialized Camps:STEM and adaptive programming segments attract dual-income households seeking measurable skill-building outcomes. These camps require specialized instructor certifications and sensory-friendly infrastructure that reshape hiring timelines.
- Day Camps:Municipal partnerships and school district summer programming drive volume. Fixed costs scale efficiently across larger participant pools, though USDA summer food service compliance imposes administrative burdens.
- Family Camps:Repeat-booking loyalty sustains mature market position. All-inclusive pricing bundling lodging, meals, and activities simplifies booking decisions for time-constrained parents.
Leading the category by volume: Day Camps. Growing fastest: Specialized Camps.
Activity Focus:
Activity specialization determines permit requirements and insurance underwriting: adventure programming triggers OSHA workplace safety enforcement for equipment and ropes courses, while nature exploration operates under state environmental agency waterfront caps.
- Adventure:Ropes courses, climbing walls, and high-element programming demand specialized equipment inspection protocols. Northeast corridor operators face constrained site expansion due to limited waterfront permit availability.
- Sports:Traditional athletic programming requires certified coaching staff and dedicated field infrastructure. Municipal partnerships in the Mountain West generate stable enrollment through school district relationships.
- Arts & Crafts:Lower capital barriers attract independent operators and nonprofit community programs. YMCA camps leverage subsidized access to differentiate in urban outreach verticals.
- Nature Exploration:Environmental science curricula align with STEM programming integration trends. State environmental agency permits for lake access constrain dock construction and waterfront expansion.
Dominating enrollment share: Sports. Expanding most quickly: Nature Exploration.
Target Audience:
Audience segmentation maps directly to pricing power and season length: children and teens drive eight-week summer concentration, while adult retreats extend revenue into shoulder seasons with higher per-capita yields.
- Children:Core summer programming segment with highest enrollment volume. Millennial parents seeking structured nature experiences prioritize ACA-accredited facilities with real-time parent communication platforms.
- Teens:Leadership development and counselor-in-training programs extend engagement. J-1 visa processing delays compress staffing reliability for specialized teen programming.
- Families:All-inclusive pricing models reduce decision fatigue. Repeat-booking loyalty concentrates in Colorado and California markets among dual-income households.
- Adult Retreats:Corporate team-building contracts with technology and professional services firms generate off-season revenue. Higher per-capita yields justify dedicated conference infrastructure investment.
Highest enrollment concentration: Children. Steepest expansion trajectory: Adult Retreats.
Facilities:
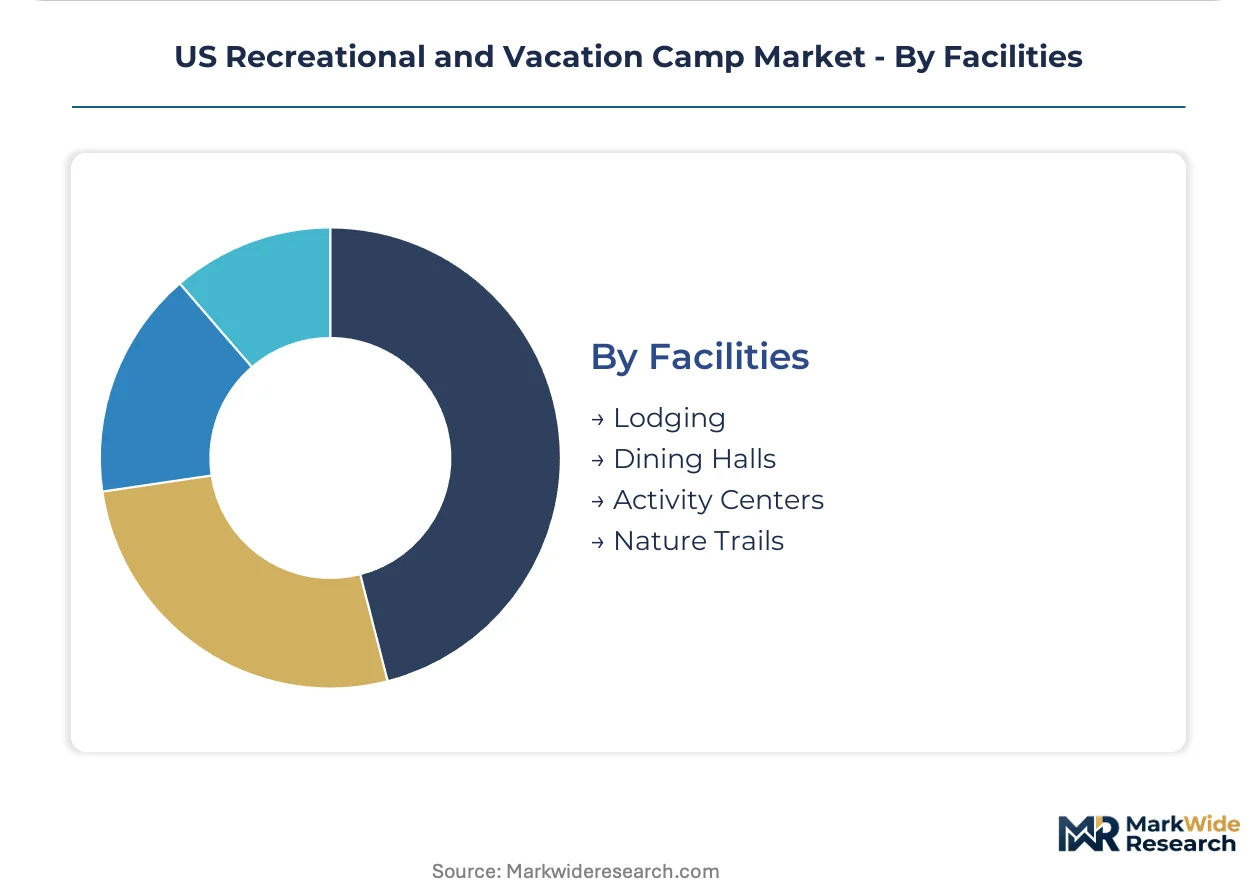
Facility type dictates capital intensity and depreciation schedules: lodging infrastructure requires ADA-compliant upgrades and climate resilience investments that exceed family-owned operator capacity, while dining halls trigger USDA nutritional documentation requirements.
- Lodging:Cabin infrastructure modernization demands capital deployment for ADA compliance and climate resilience. Sub-scale operators exit rather than absorb these infrastructure costs.
- Dining Halls:USDA summer food service program compliance requires nutritional documentation and meal pattern adherence. Fixed administrative burdens scale poorly for camps under one hundred participants.
- Activity Centers:Indoor programming infrastructure enables year-round operation and weather-independent revenue. Great Wolf Lodge anchors competing indoor water park resort concepts.
- Nature Trails:Lower capital requirements support independent and nonprofit camp viability. State environmental agency permits constrain trail expansion in protected watershed areas.
Largest capital allocation: Lodging. Gaining operational priority: Activity Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed rural counties concentrate camp development through federal tax incentives, channeling investment toward Mountain West and Northeast corridor states where seasonal infrastructure already clusters.
Mountain West
Colorado and Utah operators leverage established emergency response networks and shared staff recruitment pools across the Rocky Mountain region. State environmental agencies in both states impose strict waterfront permit caps that limit dock expansion but protect existing operator market positions. Denver and Salt Lake City serve as logistics hubs for equipment procurement and seasonal worker housing.
Northeast Corridor
New York and Massachusetts enforce the most aggressive ACA accreditation compliance timelines, accelerating consolidation as sub-scale camps exit rather than absorb certification costs. State health departments in these jurisdictions tightened staff-to-camper ratios for overnight programs beginning in 2024. The Adirondack and Berkshire regions concentrate distressed asset acquisition activity as established operators purchase permits from failing competitors.
Southeast
Florida and Georgia camps extend operating seasons through mild winter climates, capturing corporate retreat demand during traditional shoulder months. State childcare licensing thresholds remain lower than Northeast benchmarks, enabling faster program launches for new entrants. The North Georgia mountains and Central Florida lake districts attract franchise network expansion from roadside accessibility operators.
Pacific Coast
California dual-income households drive all-inclusive pricing adoption, prioritizing booking efficiency over customization flexibility in fragmented leisure markets. State environmental regulations through the California Coastal Commission constrain waterfront development in high-demand coastal zones. The Sierra Nevada foothills and Lake Tahoe basin concentrate family camp repeat-booking loyalty programs.
Southwest
Arizona and New Mexico operators target adaptive programming for neurodiverse children, addressing underserved demand from families excluded from traditional camp structures. USDA summer food service program compliance costs impose heavier administrative burdens in these states due to dispersed rural populations. The Flagstaff and Santa Fe metro areas anchor specialized STEM and arts programming clusters.
US Recreational and Vacation Camp Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated structure where nonprofit community networks hold volume positions against for-profit resort concepts. The vendor base spans franchise roadside operators, indoor water park resorts, and single-site independent camps with varying capital access. Three archetypes dominate: membership-based nonprofit federations, multi-site franchise networks, and specialized premium experience providers. Competitive moves center on distressed asset acquisition for permit transfer value and interstate corridor network expansion for booking loyalty.
Within the nonprofit federation tier, YMCA and Girl Scouts of the USA exemplify subsidized-access models that differentiate through urban outreach and membership-based enrollment pipelines. Kampgrounds of America anchors the franchise network archetype with roadside accessibility across interstate corridors, while Great Wolf Lodge occupies the premium indoor resort position competing year-round against traditional seasonal concepts. These three entities represent distinct capital structures and seasonality profiles that segment competitive rivalry across price points and geographic density.
| Leading Market Players |
|---|
| American Camp Association |
| YMCA |
| Outward Bound USA |
| Camp Bow Wow |
| Kampgrounds of America |
| Girl Scouts of the USA |
| Great Wolf Lodge |
| CampGroup |
| Galileo |
| Others |
Pricing and Supply Chain Analysis
Certified lifeguard and wilderness first responder concentration across the Mountain West and Northeast corridor compresses labor-cost differentials into pricing-tier spreads, with camps absorbing six-month credential lead times passing elevated staffing costs to premium overnight segments while day camps compete on municipal-subsidized economy positioning.
Pricing Analysis
Short lead-time premiums attach to last-minute family camp bookings in Colorado and California markets, while early-commitment discounts reward advance deposits secured before February hiring cycles. Three-tier pricing structure across premium overnight, standard day camp, and economy municipal-partnership levels separates ACA-accredited facilities from sub-scale independents. Price differentiation rests on certification grade and waterfront permit access, with Northeast corridor operators commanding premiums due to constrained dock construction approvals. Cost compression in economy tiers is intensifying because J-1 visa processing delays compress seasonal labor pools. Municipal-partnership day camps exhibit highest price sensitivity; corporate retreat clients show least.
Supply Chain Analysis
Seasonal workforce availability across rural Texas, Florida, and college-town corridors in the Midwest feeds camp staffing pipelines, with J-1 visa program participation rates determining labor pool depth. Supply concentrates in domestic labor markets for cabin construction materials, food service equipment, and adventure programming gear. Raw material dependencies include lumber for lodging infrastructure, specialized ropes course hardware, and kitchen equipment meeting USDA summer food service standards. Single-source vulnerability sits with Red Cross and ACA certification providers for specialized aquatics and wilderness credentials. Distribution runs through regional equipment cooperatives and franchise network procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as operators pursue backward integration into owned lodging infrastructure to escape permit-transfer dependency and capture distressed asset acquisition value.
For Market Incumbents: Anchor market position through distressed asset acquisition in the Adirondack and Berkshire regions, securing waterfront permit transfer value from failing competitors rather than greenfield development. Invest in climate-resilient cabin infrastructure to defend against ADA compliance mandates that force sub-scale exits. Threat: ACA accreditation standards compressing operational gaps. Lever: vertical integration into owned real estate. For New Entrants and Emerging Players: Municipal park departments represent the most penetrable channel partner type for day camp volume entry, offering subsidized facility access and established enrollment pipelines. Target adaptive programming for neurodiverse children in Arizona and New Mexico, where specialized sensory-friendly infrastructure remains underserved. Corporate retreat shoulder-season contracts provide highest-yield go-to-market angle with technology sector clients. For Investors and Strategic Acquirers: Re-rating potential sits with multi-site franchise networks given interstate corridor booking loyalty and shared inventory management systems as catalysts. Five-to-ten year viability favors operators with captive real estate positions and diversified revenue across summer camp and corporate retreat seasons. Acquisition target archetype: distressed single-site camps with transferable waterfront permits in restricted Northeast jurisdictions. Signal to watch: state health department staff-to-camper ratio enforcement intensity as consolidation inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Distressed Asset Acquisition | ACA-accredited operators secure waterfront permit transfer value from failing competitors in permit-constrained Northeast corridor states. |
| Adaptive Programming Infrastructure | Sensory-friendly cabin construction and behavioral staff certification address excluded neurodiverse family demand in Southwest markets. |
| Corporate Retreat Vertical Expansion | Technology and professional services firm contracts extend revenue into shoulder seasons with higher per-capita yields than summer programming. |
| Interstate Franchise Network Extension | Roadside accessibility along I-70, I-80, and I-90 corridors enables multi-site booking loyalty and centralized procurement economies. |
| Climate-Resilient Lodging Modernization | ADA-compliant cabin upgrades exceed depreciation schedules for family-owned operations, accelerating consolidation toward capitalized multi-site players. |
Research Methodology
Document review covered ACA accreditation standards, state health department licensing frameworks, USDA summer food service program guidelines, and OSHA workplace safety enforcement records, complemented by interviews with camp operators, municipal recreation directors, seasonal staffing agencies, and franchise network executives. Secondary validation drew from American Camp Association outcome measurement databases, state environmental agency permit filings, and trade association operational surveys. Bottom-up enrollment data triangulated against top-down market sizing across camp type, activity focus, target audience, and facility configuration segments.
Segment-level value and volume outputs emerged from enrollment capacity modeling, pricing tier analysis, and seasonal utilization rate assumptions across the projection horizon. Modeled dimensions included overnight versus day camp configuration, STEM and adaptive programming specialization, family versus child-only audience targeting, and lodging versus activity center facility priority. CAGRs derived from historical enrollment trend extrapolation, demographic cohort projections, and regulatory compliance cost trajectory analysis. Industry-specific forecast inputs incorporated J-1 visa program participation rates and state childcare licensing threshold evolution.
Several conditions sit outside the modeled scope, including federal immigration policy shifts affecting seasonal worker visa availability, catastrophic weather events disrupting Mountain West operating seasons, and state-level minimum wage legislation compressing staffing economics. Forecasts reflect assumptions regarding ACA accreditation adoption rates and parent preference evolution toward real-time digital communication platforms. Material deviation in J-1 visa processing timelines, waterfront permit issuance velocity, or state health department enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
China Tourism and Hotel Market
Accommodation
Extended Stay Hotel Market
Accommodation
India Student Accommodation Market
Accommodation
India Online Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
China Online Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
France Casino Tourism Market
Accommodation
Africa Hotel Market
Accommodation
Europe Student Accommodation Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Canada Hospitality Market
Accommodation
Luxury Hotel Market
Accommodation
France Online Accommodation Market
Accommodation
Underwater Hotels Market
Accommodation
Alternative Accommodation Market