
 Croatia Hospitality Market | 2026-2036
Croatia Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Croatia Hospitality Market Insights
Seasonal labor availability in coastal Croatia is reorganizing operational models across the hospitality sector. Valamar Riviera leverages its year-round wellness properties to reduce dependency on peak-summer staffing. Aminess Hospitality Group anchors its competitive position through extended-season camping and glamping formats. Maistra Hospitality Group dominates in Istria with integrated resort-town developments that sustain local employment through shoulder months.
Croatia hospitality comprises lodging, food service, and guest experience operations delivered through fixed and mobile accommodation assets, typically rated by star classification and amenity depth. Properties range from historic urban boutique hotels to purpose-built coastal resorts with marina, spa, and conference infrastructure. Luxury and upscale service levels capture disproportionate margin pools in Dubrovnik and Hvar where supply restrictions limit new entrants. Vacation rentals compete aggressively through online travel agencies, compressing rate parity for mid-range hotels in Split and Zadar. Direct booking channels regain traction where loyalty programs and experiential packaging reduce platform commission exposure.
Croatia's Ministry of Tourism enforces construction and classification standards under the Tourist Land Act, while EU Ecolabel and Green Key certification requirements shape renovation investment priorities. The country's national tourism board coordinates with coastal municipalities to manage carrying capacity limits in protected zones like Plitvice Lakes and Kornati Islands. Stakeholders must monitor how EU cohesion fund allocations for sustainable tourism infrastructure redirect development gravity toward lesser-known counties.
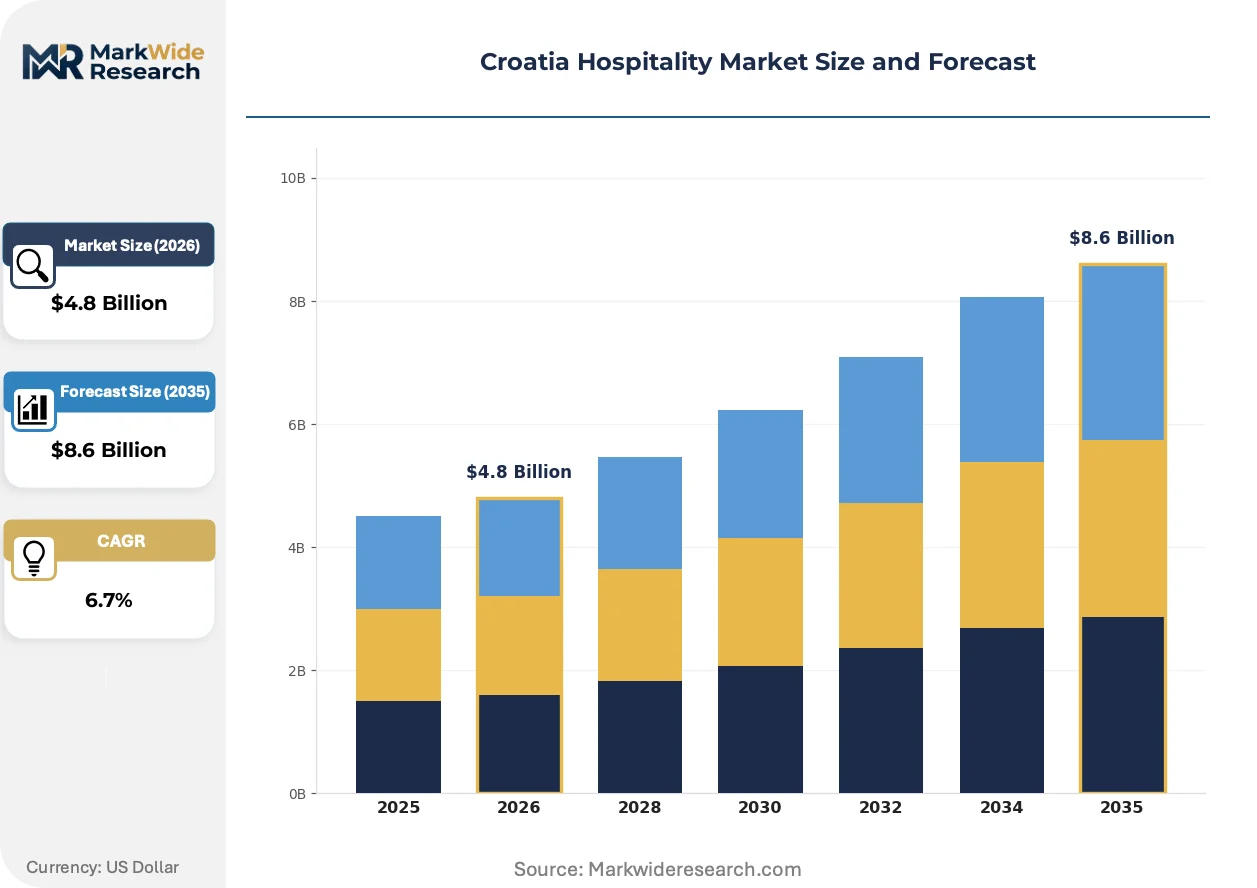
Market Dynamics
EU Green Deal tourism sustainability criteria are compressing investment timelines for coastal properties while rerouting capital toward certified renovation pipelines. The regulatory pressure is accelerating obsolescence of non-compliant assets in Dalmatia and Istria.
Growth Catalysts
- EU Ecolabel certification:Properties achieving this standard access preferential financing through national tourism development funds and command rate premiums in Split-Dalmatia County marina clusters.
- Wellness tourism infrastructure:Year-round thermal and spa facilities extend operational calendars beyond the traditional June-September window, stabilizing revenue streams.
- Glamping format expansion:Elevated camping accommodations with fixed amenities capture demand from experience-seeking segments priced out of boutique hotels.
Market Restraints
- Seasonal labor scarcity:The Adriatic coast faces acute shortages of certified hospitality staff during peak months, forcing wage inflation and service compression.
- Construction input volatility:Maritime-grade materials and specialized coastal engineering expertise concentrate in limited supplier networks, inflating development costs.
- Carrying capacity limits:Protected zone regulations in Kornati Islands and Plitvice Lakes restrict room stock expansion regardless of demand signals.
Strategic Opportunities
- EU cohesion fund redirection:Sustainable tourism infrastructure allocations are shifting development gravity toward lesser-known counties like Lika-Senj and Karlovac.
- Direct booking channel recovery:Loyalty program investments and experiential packaging reduce commission exposure to online travel agencies.
- Extended-season formats:Conference and MICE infrastructure integration enables shoulder-month occupancy in historic urban properties.
Industry Challenges
- Green Key compliance timelines:Retrofit schedules for existing properties must synchronize with EU Ecolabel audit windows, compressing construction seasons.
- Digital integration complexity:Legacy property management systems require costly middleware to connect with modern distribution platforms and guest experience applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croatia Hospitality Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Hotels, Resorts, Hostels, Vacation Rentals Service Level: Luxury, Upscale, Mid-range, Budget Customer Segment: Tourists, Business Travelers, Family Groups, Backpackers Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Group Tours |
| Companies Covered | Plava Laguna, Aminess Hospitality Group, Valamar Riviera, Amadria Park, Falkensteiner Hotels & Residences, Maistra Hospitality Group, Sunce Hotels (Bluesun), Liburnia Riviera Hoteli, Arena Hospitality Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croatia Hospitality Market Trends and Innovations
Operational technology is reshaping guest service delivery and back-of-house efficiency across Croatia's hospitality base. Three developments are compressing competitive differentiation timelines.
Smart room control systems using IoT sensors and mobile key integration are miniaturizing the front-desk footprint in boutique properties. Independent hoteliers in Dubrovnik and Hvar are adopting these platforms faster than branded chains, enabling staff redeployment toward experiential concierge functions. The technology is compressing fixed-cost structures in sub-50-room properties where traditional staffing models previously blocked margin recovery.
EU Green Deal tourism sustainability criteria are mandating energy performance disclosures and carbon accounting for properties above 50 rooms. The Tourist Land Act amendments require coastal municipalities to integrate carrying capacity assessments into development permits. Dalmatia County authorities are responding with stricter wastewater treatment pre-conditions for marina-adjacent projects.
Experience-driven booking patterns are displacing rate-comparison behavior among high-value segments. Direct channel investments with loyalty program tiers and localized activity packaging are recapturing margin from online travel agency intermediation. This shift concentrates in Split and Zadar where vacation rental competition previously compressed hotel rate parity.
Croatia Hospitality Market Segmentation
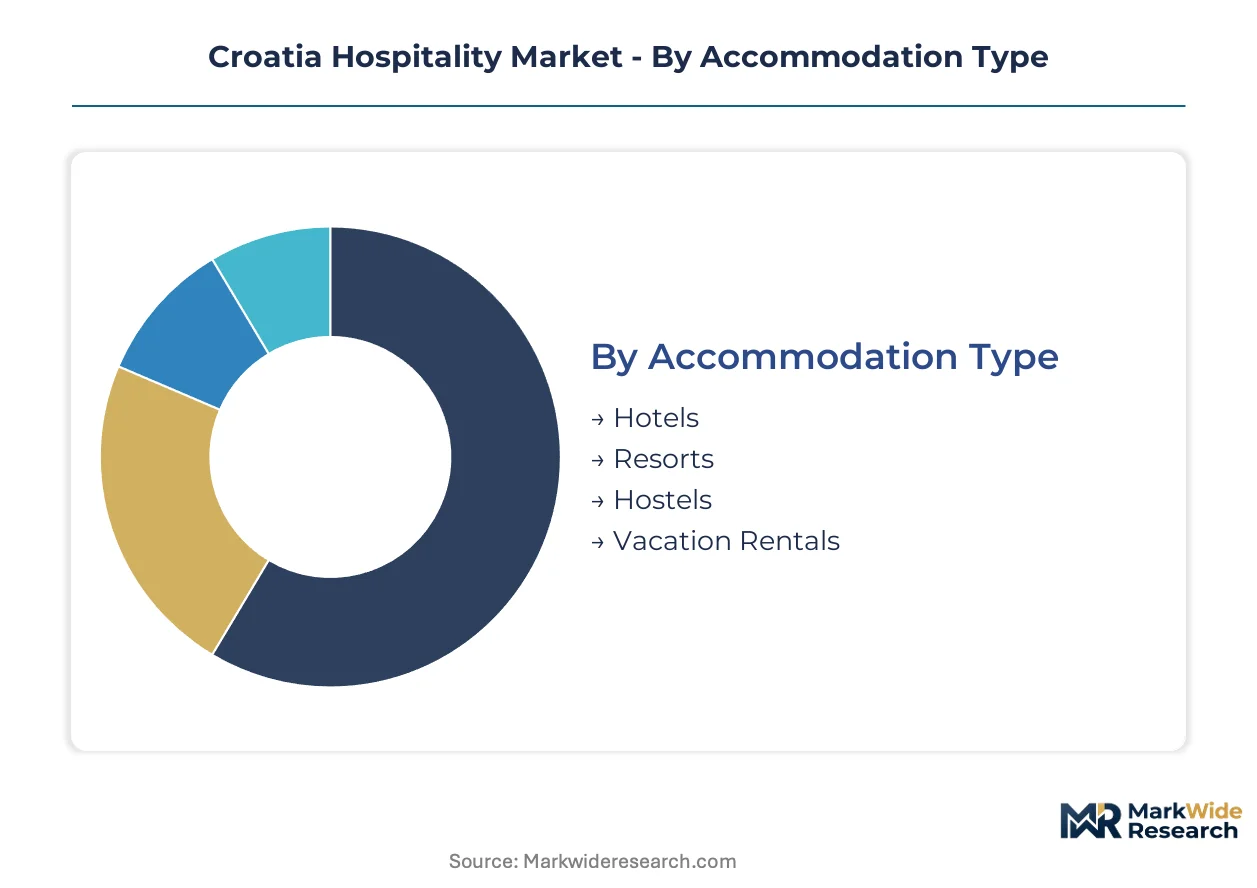
Segmentation in Croatia hospitality reveals how substitute formats erode traditional property economics. Operators must calibrate asset positioning against vacation rental platforms, glamping expansions, and wellness-focused alternatives reshaping demand allocation across the Adriatic coast.
Accommodation Type:
Vacation rentals exert the strongest substitution pressure on fixed-asset hospitality, compressing rate parity in Split and Zadar urban cores.
- Hotels:Fixed-asset properties with star-classified infrastructure including front-desk services, housekeeping, and on-site food and beverage. Demand concentrates in Dubrovnik and Hvar where supply restrictions under the Tourist Land Act limit new entrants and protect existing rate structures.
- Resorts:Integrated hospitality complexes with marina, spa, and conference infrastructure spanning multiple accommodation buildings. Properties in Split-Dalmatia County marina clusters command premium positioning through EU Ecolabel certification and extended-season wellness programming.
- Hostels:Shared-accommodation formats with minimal private room inventory and communal facilities targeting price-sensitive segments. Backpacker demand flows through online travel agency platforms with thin direct booking penetration.
- Vacation Rentals:Privately owned apartments and villas distributed through digital platforms, competing aggressively on space and kitchen amenities. Istria and Dalmatia coastal municipalities face enforcement challenges against unregistered inventory under national tourism board coordination protocols.
Hotels retain volume leadership across the Adriatic coast; vacation rentals hold the steepest expansion curve.
Service Level:
Margin distribution follows certification depth and amenity intensity rather than room count alone.
- Luxury:Five-star and boutique properties with personalized concierge, thermal spa infrastructure, and marina-adjacent positioning. Dubrovnik's walled-city properties and Hvar island resorts capture disproportionate margin pools where development moratoria constrain competitive entry.
- Upscale:Four-star properties with conference facilities, wellness programming, and Green Key certification compliance. Istria's integrated resort-town developments sustain year-round employment through shoulder-month MICE and thermal tourism demand.
- Mid-range:Three-star properties and serviced apartments competing on location proximity to historic cores and transport nodes. Split and Zadar operators face rate compression from vacation rental substitution in peak summer windows.
- Budget:Two-star and unclassified properties with minimal amenity infrastructure and seasonal operational calendars. Lika-Senj and Karlovac counties attract EU cohesion fund allocations redirecting development gravity toward underserved interior markets.
Luxury commands the highest revenue per available room; upscale properties are climbing the fastest through certified renovation pipelines.
Customer Segment:
Experience-driven booking patterns displace rate-comparison behavior most sharply among high-value tourist segments.
- Tourists:Leisure travelers seeking cultural, coastal, and nature-based experiences across the Adriatic corridor. Demand concentrates in Split-Dalmatia County where marina-adjacent hospitality clusters integrate nautical and hinterland activity packaging.
- Business Travelers:Corporate and MICE participants requiring conference infrastructure, transport connectivity, and compressed stay formats. Historic urban properties in Zagreb and Split extend operational calendars through shoulder-month business event programming.
- Family Groups:Multi-generational travelers prioritizing space, kitchen facilities, and activity proximity over hotel service density. Glamping and camping formats in Istria capture this segment through Aminess Hospitality Group's extended-season elevated accommodation assets.
- Backpackers:Price-sensitive independent travelers with minimal service expectations and platform-mediated booking behavior. Hostel inventory in Zadar and coastal transit hubs competes against vacation rental private rooms on digital distribution platforms.
Tourists retain volume leadership across all accommodation types; family groups are gaining share fastest through alternative format adoption.
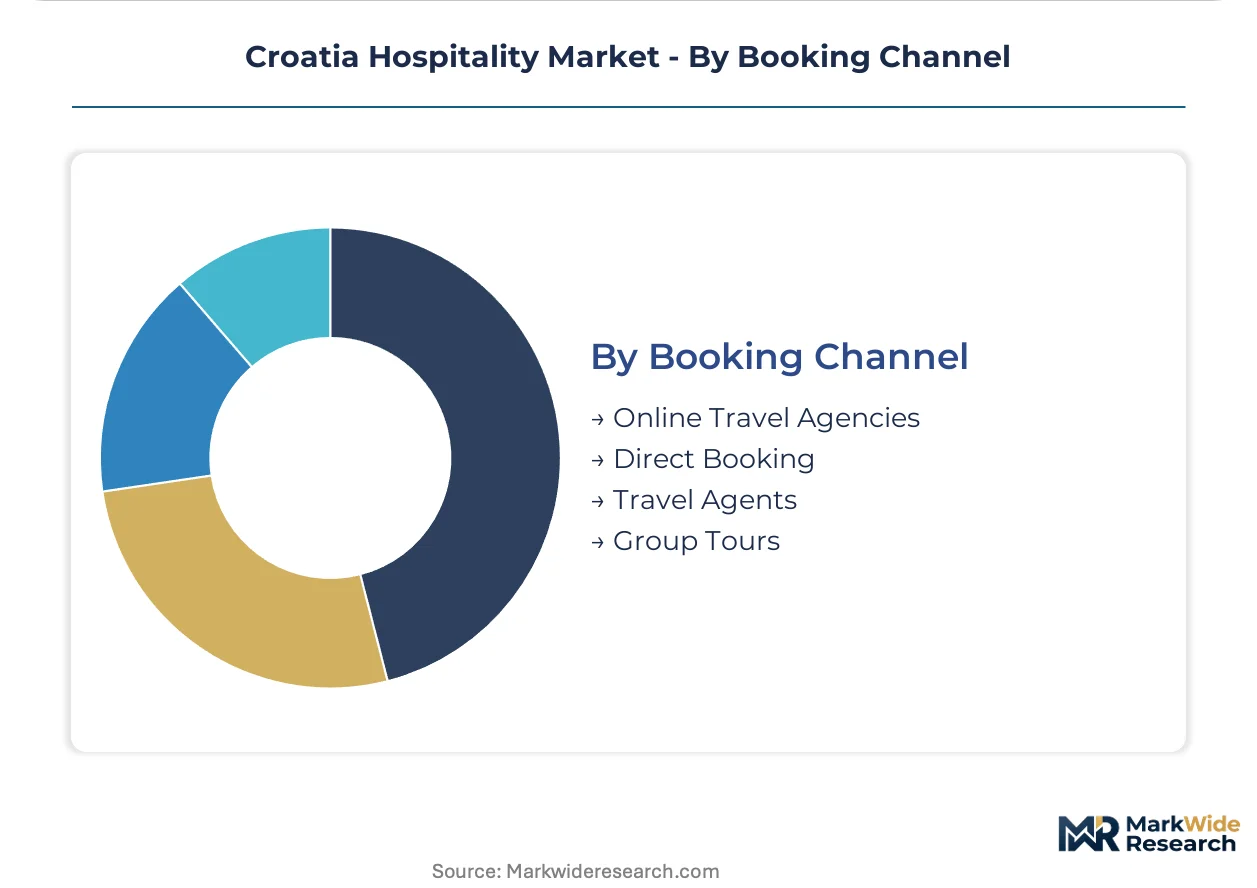
Booking Channel:
Commission exposure to intermediary platforms varies sharply by property scale and loyalty program maturity.
- Online Travel Agencies:Digital platforms aggregating inventory comparison and instant booking confirmation. Mid-range hotels in Split and Zadar suffer margin compression from platform dependency where vacation rental competition erodes rate parity.
- Direct Booking:Property-controlled reservation systems with loyalty program tiers and experiential packaging. Independent hoteliers in Dubrovnik and Hvar recapture margin through localized activity bundling and repeat-guest incentives.
- Travel Agents:Intermediary professionals packaging transportation, accommodation, and guided experiences for complex itineraries. Group and MICE segments in Istria maintain this channel through integrated resort-town development relationships.
- Group Tours:Organized travel products with block room commitments and fixed programming for cultural and nature-based itineraries. Kornati Islands and Plitvice Lakes protected zones channel this demand through carrying capacity limits managed by Dalmatia County authorities.
Online travel agencies retain volume leadership; direct booking channels are expanding most quickly among certified boutique properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium rate capture in Dubrovnik-Neretva County diverges sharply from compression pressures in Split-Dalmatia County's oversupplied urban cores. This pricing asymmetry reflects supply restrictions, certification depth, and marina-adjacent positioning across Croatia's coastal hospitality corridor.
Split-Dalmatia County
Marina-adjacent hospitality clusters command rate premiums through EU Ecolabel certification and integrated nautical infrastructure. Dalmatia County authorities enforce stricter wastewater treatment pre-conditions under Tourist Land Act amendments. Split's historic urban properties face vacation rental substitution compressing mid-range hotel parity.
Dubrovnik-Neretva County
Walled-city boutique properties capture disproportionate margin pools where development moratoria constrain competitive entry. The national tourism board coordinates carrying capacity limits with coastal municipalities in protected zones. Konavle and Župa dubrovačka sub-regions anchor luxury resort expansion through thermal spa programming.
Istria County
Integrated resort-town developments sustain year-round employment through shoulder-month MICE and thermal tourism demand. EU Green Deal tourism sustainability criteria compress retrofit timelines for existing properties. Poreč and Rovinj hospitality clusters leverage Green Key compliance to access preferential national tourism development financing.
Primorje-Gorski Kotar County
Opatija Riviera wellness infrastructure extends operational calendars beyond traditional June-September windows. The Ministry of Tourism enforces construction standards that redirect renovation investment toward certified pipelines. Kvarner Bay properties anchor competitive positioning through conference infrastructure integration.
Zadar County
Mid-range hotel operators face acute rate compression from vacation rental platforms during peak summer demand windows. Carrying capacity assessments for Kornati Islands protected zones restrict room stock expansion regardless of demand signals. Zadar's historic core properties recapture margin through direct booking channel investments with localized activity packaging.
Croatia Hospitality Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Croatia's hospitality base. The market structures around three tiers: integrated resort-town developers with year-round wellness assets, marina-adjacent operators leveraging EU Ecolabel premiums, and seasonal mid-range properties vulnerable to vacation rental substitution. Scale-driven consolidation concentrates in Istria and Dalmatia through property portfolio expansion, while certification differentiation and loyalty program investments represent the dominant competitive vectors.
Within the integrated resort archetype, Valamar Riviera and Maistra Hospitality Group exemplify year-round operational models that reduce dependency on peak-summer staffing through wellness and MICE infrastructure. Aminess Hospitality Group occupies a position in the elevated outdoor accommodation segment, anchoring competitive position through extended-season glamping formats. These three players represent distinct strategic responses to seasonal labor scarcity and EU sustainability compliance pressures.
| Leading Market Players |
|---|
| Plava Laguna |
| Aminess Hospitality Group |
| Valamar Riviera |
| Amadria Park |
| Falkensteiner Hotels & Residences |
| Maistra Hospitality Group |
| Sunce Hotels (Bluesun) |
| Liburnia Riviera Hoteli |
| Arena Hospitality Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal tourism sustainability criteria gate both supplier qualification and price differentiation simultaneously. Properties achieving EU Ecolabel certification access preferential national tourism development financing while commanding rate premiums in marina-adjacent clusters. Non-compliant assets face accelerated obsolescence, compressing their pricing power regardless of location quality.
Pricing Analysis
Dubrovnik-Neretva County maintains rate premiums of forty to sixty percent above Split-Dalmatia County urban cores. Three-tier pricing structure across luxury, upscale, and mid-range levels stratifies by certification depth and amenity intensity rather than room count alone. Cost compression in mid-range tiers is intensifying because vacation rental platforms erode rate parity during peak summer windows. Backpacker segments exhibit highest price sensitivity; luxury wellness tourists demonstrate lowest elasticity.
Supply Chain Analysis
Maritime-grade construction materials concentrate in Italian, German, and Austrian supplier networks. Croatian hospitality development draws from specialized coastal engineering expertise, thermal spa equipment, and certified sustainable timber inputs. Single-source vulnerability runs through wastewater treatment system providers facing Dalmatia County authority pre-conditions. Distribution runs through project-based procurement with extended lead times for custom marina infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Croatia hospitality operates as a service-attach opportunity where experiential packaging and loyalty program tiers expand faster than fixed-asset room stock. Recurring revenue from wellness memberships and activity bundling outpaces transactional accommodation sales.
For Market Incumbents: Consolidate through certified renovation pipelines that synchronize Green Key compliance with EU Ecolabel audit windows. Acquire distressed non-compliant assets in Istria and Dalmatia before regulatory obsolescence accelerates. Vertical integration into thermal spa operations and MICE infrastructure reduces seasonal staffing dependency.
For New Entrants and Emerging Players: Extended-season conference infrastructure in historic urban cores represents the most penetrable white-space where incumbents under-serve shoulder-month demand. Target Zagreb and Split business event programming with hybrid hospitality-workspace formats. Go-to-market leverage rests on direct booking channel investments with localized activity packaging.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across marina-adjacent developments due to stricter wastewater treatment pre-conditions. Long-term viability favors integrated resort-town developers with year-round wellness assets over seasonal mid-range properties. Acquisition target archetype: upscale properties with Green Key certification and existing MICE infrastructure. Watch EU cohesion fund allocation shifts toward Lika-Senj and Karlovac as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Ecolabel Certification Pipeline | Unlocks preferential national tourism development financing and rate premiums in Split-Dalmatia marina clusters. |
| Extended-Season Wellness Infrastructure | Stabilizes revenue streams beyond June-September through thermal spa and MICE programming. |
| Direct Booking Channel Investment | Reduces commission exposure to online travel agencies where vacation rental competition compresses parity. |
| Glamping Format Expansion | Captures family group demand through elevated camping accommodations with fixed amenities. |
| EU Cohesion Fund Location Shift | Redirects development gravity toward underserved interior counties with sustainable tourism infrastructure allocations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of national tourism board statistics, EU cohesion fund allocation records, and property classification databases. Primary interviews engaged hospitality operations directors, municipal tourism officers, marina infrastructure planners, and EU certification auditors. Secondary validation drew from Tourist Land Act amendments, Dalmatia County wastewater treatment regulations, and EU Green Deal tourism sustainability criteria documentation. Bottom-up property-level capacity assessment triangulates against top-down national tourism revenue estimates.
Segmentation dimensions modeled include accommodation type, service level tier, customer segment, and booking channel across the projection horizon. Accommodation type captures hotels, resorts, hostels, and vacation rentals with substitution elasticity parameters. Service level stratification incorporates certification depth and amenity intensity. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporate seasonal labor availability indices and EU Ecolabel certification penetration curves.
Underlying assumptions cover sustained EU Green Deal compliance timelines, with deviation risk concentrated in accelerated retrofit schedules or cohesion fund reallocation delays. Forecasts reflect these assumptions without scenario weighting. Practitioners should keep alternative scenarios live as EU Ecolabel audit window timing and national tourism development fund access criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Switzerland Hospitality Market
Accommodation
Sweden Hospitality Market
Accommodation
China Tourism and Hotel Market
Accommodation
UK Student Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
Europe Student Accommodation Market
Accommodation
Airport Sleeping Pods Market
Accommodation
Global Travel Accommodation Market
Accommodation
Underwater Hotels Market
Accommodation
US Student Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
Austria Hospitality Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Glamping Market
Accommodation
In-Flight Catering Services Market