
 Alternative Accommodation Market | 2026-2036
Alternative Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Accommodation Market Intelligence
The shift toward professionally managed properties with standardized amenities is reorganizing the market's structure. This move addresses consumer demand for reliability, a segment where Sonder specializes by offering tech-enabled, hotel-like apartments. Airbnb leverages its global brand to integrate these professional offerings alongside its core individual host inventory. Expedia Group's Vrbo platform competes directly by focusing on whole-home rentals for families and groups.
Alternative accommodation encompasses lodging options outside of traditional hotels, including private homes, apartments, and unique structures. These properties are defined by self-service amenities and are booked for variable durations, offering travelers localized and flexible stays. Vacation rentals constitute the largest property type, driven by demand from tourists and families. Booking channels are dominated by online travel agencies, though direct booking is gaining traction for luxury and serviced apartment providers.
Market access is shaped by a complex web of local regulations, such as the strict short-term rental ordinances in cities like Barcelona and New York. In parallel, Japan's Minpaku Act and the EU's proposed data-sharing framework create standardized compliance requirements for hosts and platforms. Navigating this fragmented regulatory environment remains a central challenge for scaling operations and maintaining inventory.
Market Dynamics
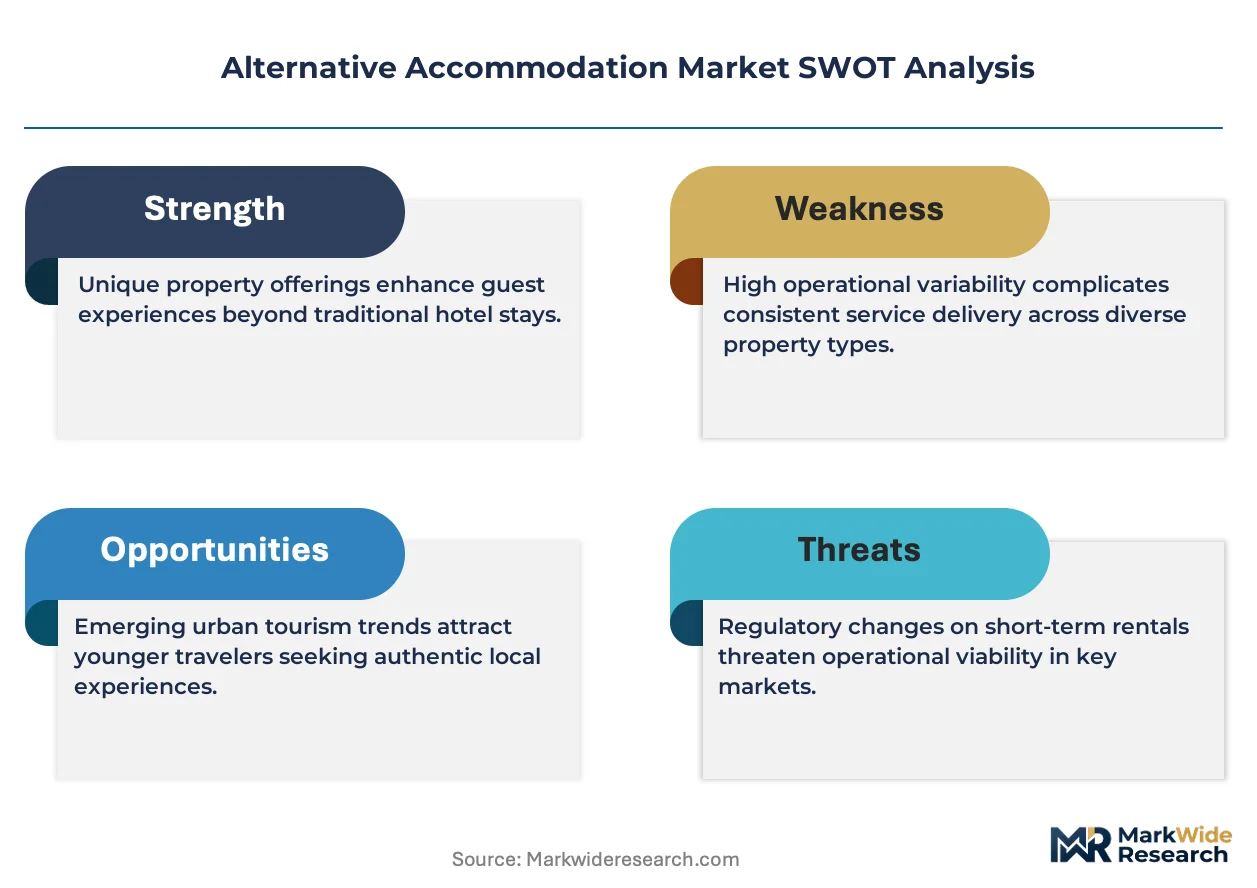
The central dynamic shaping the alternative accommodation market is the push for professionalization and standardization colliding with a deeply fragmented and localized regulatory landscape. This tension defines the strategic challenges for platforms and operators seeking to build scalable, consistent brands in a sector traditionally defined by variability.
Growth Catalysts
- Mobile Technology Adoption:The proliferation of mobile booking applications and sophisticated dynamic pricing algorithms simplifies the discovery, comparison, and booking process for consumers, increasing accessibility and stimulating demand.
- Corporate Travel Integration:Business travelers are increasingly utilizing serviced apartments and private homes for extended assignments and project-based work, seeking more space, autonomy, and a local experience than traditional hotels offer.
- Secondary City Expansion:Demand is concentrating in secondary cities across destinations like the United States and Spain, offering new growth frontiers for operators beyond saturated and highly regulated primary metropolitan centers.
Market Restraints
- Restrictive Local Ordinances:Aggressive short-term rental regulations in major tourist destinations, such as the licensing caps in Barcelona and registration mandates in New York City, severely limit inventory growth and increase compliance costs.
- Hotel Industry Substitution:Traditional hotel chains are launching and expanding their own apartment-style and extended-stay brands, creating a direct substitution threat by offering similar amenities with the backing of established loyalty programs.
- Inconsistent Quality Standards:A significant portion of the market's inventory consists of properties managed by individual hosts, leading to variability in cleanliness, safety, and service that can erode consumer trust.
Strategic Opportunities
- Regulatory Harmonization:The EU's proposed data-sharing framework presents an opportunity to streamline compliance across member states, reducing administrative burdens and creating a more predictable operating environment for platforms.
- Purpose-Built Developments:Designing and developing buildings specifically for short-term rental use allows for optimized layouts, integrated technology, and standardized amenities, addressing consumer demand for reliability and professional quality.
- Niche Travel Segments:Targeting underserved traveler niches, such as digital nomads or families seeking multi-generational travel options, with tailored properties and amenities creates a path for differentiation and higher margins.
Industry Challenges
- Navigating Compliance Complexity:Operators face significant operational hurdles in tracking and adhering to a patchwork of local registration, taxation, and safety rules, exemplified by Japan's detailed Minpaku Act requirements.
- Service Standardization:Achieving a consistent guest experience and level of service across a geographically dispersed and architecturally diverse portfolio of properties remains a core operational challenge for scaling brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Accommodation Market |
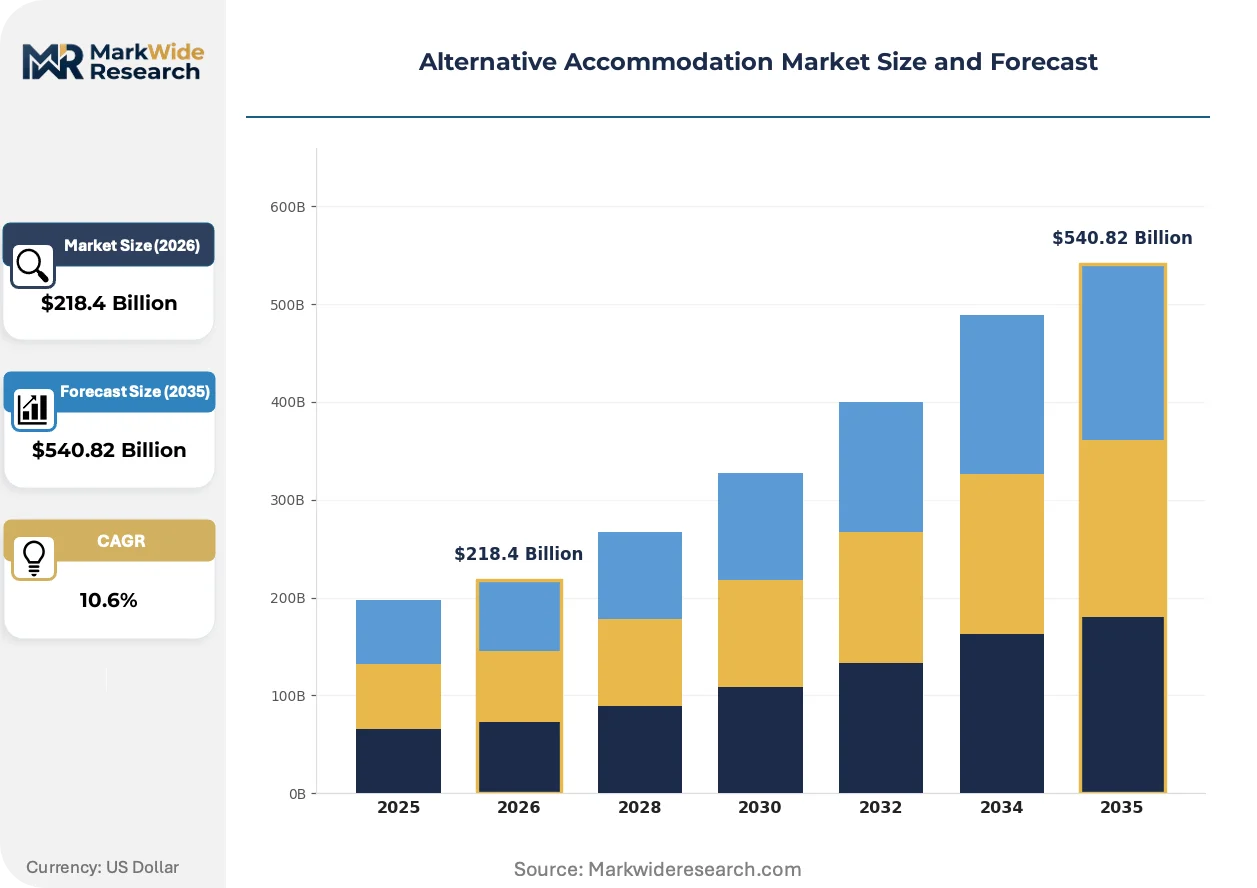
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $540.82 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Vacation Rentals, Hostels, Serviced Apartments, Treehouses Customer Type: Business Travelers, Tourists, Families, Students Booking Channel: Online Travel Agencies, Direct Booking, Corporate Partnerships, Mobile Apps Price Tier: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | Expedia Group, AvantStay, Airbnb, AltoVita, Blueground, Vrbo, Sonder, Llivo, Booking.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Accommodation Market Strategic Shifts & Innovations
Professionalization is reorganizing the market, shifting its center of gravity from a peer-to-peer exchange to a more industrialized model. This evolution is driven by the convergence of property technology, data-driven management, and emerging regulatory frameworks that favor standardized operations.
Smart home technology, including IoT-enabled locks, thermostats, and noise sensors, provides tools for remote property management. Professional operators are rapidly adopting these systems to improve operational efficiency and guest security. This technology is miniaturizing the need for on-site staff, enabling management companies to oversee a larger and more geographically distributed portfolio with fewer personnel.
The European Union's proposed regulation on data collection and sharing for short-term rental services aims to increase market transparency. This framework compels platforms to report host activity data to public authorities, which simplifies enforcement of local rules and tax collection. Online travel agencies and large property managers are most affected, as they must now build and maintain compliant data reporting systems across all EU jurisdictions in which they operate.
A significant behavioral shift toward blended "bleisure" travel is altering accommodation demand. Consumers are increasingly extending business trips for personal leisure, creating demand for properties that offer both productive workspaces and vacation amenities. This trend disrupts the clear divide between corporate housing and holiday rentals, favoring well-equipped apartments in dynamic urban neighborhoods, a pattern visible in major North American and European tech hubs.
Alternative Accommodation Market Segmentation
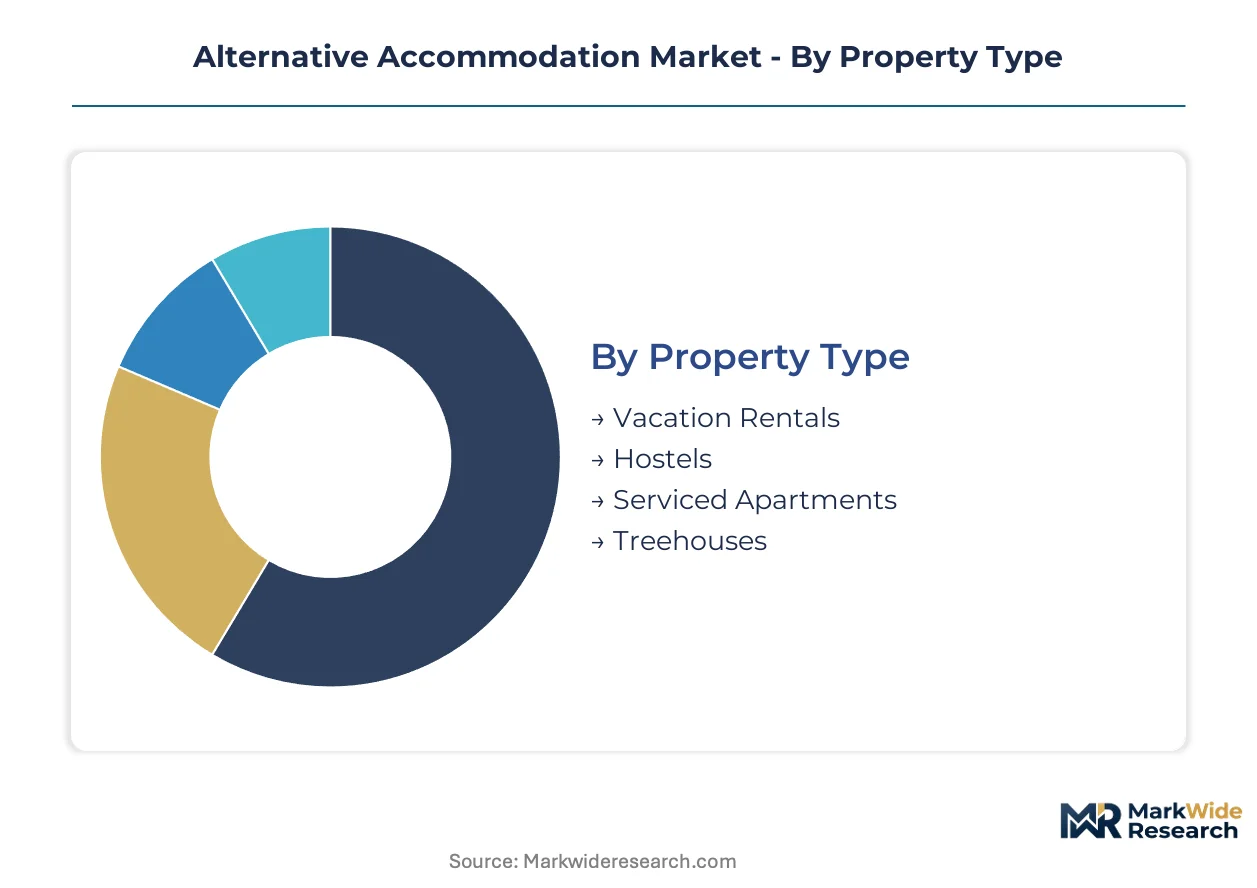
Market segmentation provides a critical lens for understanding the diverse offerings and consumer preferences within the alternative accommodation sector. This analysis delineates how different property types, customer profiles, booking channels, and price points shape competitive strategies and operational models for platforms and providers.
Property Type:
The distribution of property types significantly influences booking channel selection and operational complexity across the market.
- Vacation Rentals:These properties, often whole homes or apartments, cater primarily to leisure travelers and families seeking privacy and self-catering amenities for longer stays. Demand for vacation rentals is concentrating in secondary cities across Spain and the United States, driven by a desire for localized experiences.
- Serviced Apartments:Professionally managed units offering hotel-like amenities and services, designed for extended stays by business travelers or individuals. Corporate travel integration is expanding the demand for serviced apartments in major business hubs, offering more space than traditional hotels.
- Hostels:Budget-friendly accommodation characterized by shared dormitory-style rooms and communal facilities, typically appealing to solo travelers and younger demographics. Hostels maintain a consistent presence in urban centers and popular backpacker routes.
- Treehouses:Unique, often luxury, accommodation built among trees, providing a distinctive and experiential stay, primarily targeting niche adventure tourism.
Vacation Rentals dominate the installed base, while Serviced Apartments are where expansion concentrates.
Customer Type:
Customer profiles dictate the specific amenities, location preferences, and service levels that alternative accommodation providers must offer to capture demand.
- Business Travelers:Individuals traveling for work, often seeking extended-stay options with reliable internet, dedicated workspaces, and convenient locations near corporate centers. Corporate travel integration is increasing demand for serviced apartments among business travelers.
- Families:Groups traveling with children, prioritizing spacious accommodations, multiple bedrooms, kitchen facilities, and family-friendly amenities. Families are increasingly utilizing whole-home rentals for group travel to destinations like the US and Spain.
- Tourists:Leisure travelers exploring new destinations, seeking authentic local experiences, and often valuing properties with unique character or central locations. Mobile booking applications simplify discovery for tourists seeking diverse accommodation options.
- Students:Individuals requiring affordable, flexible, and often longer-term housing solutions, particularly during academic terms or study abroad programs.
Meeting diverse customer needs requires adaptable property configurations and tailored service packages.
Booking Channel:
The concentration of supply within specific booking channels determines platform reach and operator visibility in the fragmented market.
- Online Travel Agencies:Digital platforms like Airbnb and Vrbo that aggregate a vast inventory of alternative accommodations, offering wide consumer choice and simplified booking processes. Online travel agencies remain the dominant booking channel for vacation rentals globally.
- Direct Booking:Reservations made directly through a property's website or management company, often favored by luxury providers and serviced apartments for brand control and higher margins. Direct booking is gaining traction among serviced apartment providers seeking to build customer loyalty.
- Corporate Partnerships:Agreements between accommodation providers and businesses to house employees for extended assignments or project work, often involving negotiated rates and specialized services. Corporate partnerships are critical for scaling serviced apartment operations.
- Mobile Apps:Dedicated applications offering seamless discovery, comparison, and booking functionalities directly from smartphones, enhancing accessibility for spontaneous and on-the-go travelers. Mobile booking applications stimulate demand by simplifying the booking process for consumers.
Efficiency in booking defines competitive advantage for platforms and property managers.
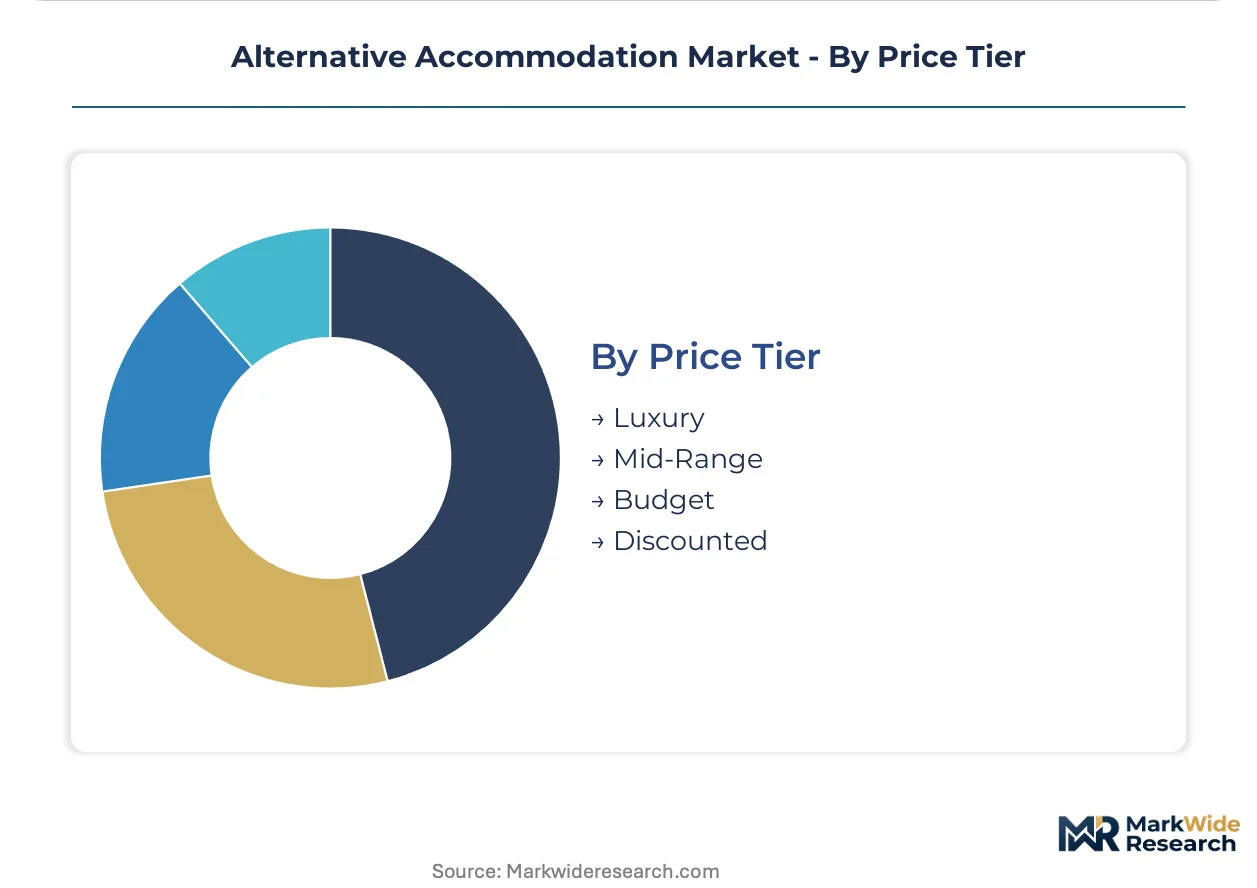
Price Tier:
The cost tier segmentation reflects varying service levels, property quality, and target demographics, influencing market positioning and profitability.
- Luxury:High-end properties offering premium amenities, bespoke services, and exclusive locations, targeting affluent travelers seeking exceptional experiences. Luxury alternative accommodations are often found in prime urban locations and unique natural settings.
- Mid-Range:Accommodations balancing comfort, quality, and affordability, appealing to a broad spectrum of travelers seeking good value without sacrificing essential amenities. Mid-range properties represent a significant portion of the professionally managed inventory.
- Budget:Cost-effective options providing basic amenities at lower price points, primarily catering to price-sensitive travelers and backpackers. Budget accommodations thrive in high-density tourist areas and student-centric cities.
- Discounted:Properties offered at reduced rates, often through promotions, last-minute deals, or off-peak season pricing to maximize occupancy.
Differentiation through service quality supports premium pricing across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The alternative accommodation market exhibits varied regional dynamics, with strong demand centers emerging in areas traditionally known for tourism and business. While some regions act as significant demand generators, others are supply hubs, particularly for professionalized short-term rentals. This interplay shapes local inventory and operational strategies for platforms.
United States
Demand for alternative accommodations in the United States is driven by family vacations and corporate travel seeking extended stays. Restrictive local ordinances in cities like New York City mandate strict registration for short-term rentals. Growth is concentrating in secondary cities such as Nashville and Austin, attracting both leisure and business travelers.
Spain
Spain sees substantial demand from tourists and bleisure travelers, particularly for vacation rentals. Cities like Barcelona have implemented licensing caps to manage short-term rental inventory. Concentrated growth is evident in coastal regions and secondary cities like Valencia, offering diverse accommodation options.
Japan
Business travelers and cultural tourists drive demand for both serviced apartments and unique stays in Japan. The Minpaku Act provides a national framework for short-term rentals, ensuring compliance and safety standards. Major urban centers like Tokyo and Kyoto are seeing increased professional management of properties.
Germany
Corporate travel integration and leisure tourism fuel demand for alternative accommodations across Germany. Local regulations in cities like Berlin impose strict limits on short-term rental operations. Munich and Hamburg are experiencing a rise in professionally managed apartment offerings catering to both segments.
France
Leisure travel and event-driven tourism contribute significantly to France's alternative accommodation demand. Cities like Paris have introduced measures to control short-term rental availability. The French Riviera and other popular tourist destinations are seeing an expansion of luxury vacation rentals.
Alternative Accommodation Market Key Industry Players
Listed leaders compete with private specialists across market segments and operational models within the alternative accommodation sector. The market exhibits a tiered structure, from global online travel agencies to specialized property management companies and localized niche providers. Three strategic archetypes define this landscape: large-scale booking platforms, professionalized apartment operators, and unique experiential stay providers. Companies actively pursue geographic expansion, technology development, and strategic partnerships to enhance their market presence and efficiency.
At the scale-driven end, Expedia Group and Airbnb represent the dominant online travel agencies, aggregating vast inventories and connecting diverse property types with global travelers. Expedia Group, through its Vrbo platform, emphasizes whole-home rentals for families, while Airbnb integrates professional offerings alongside its individual host inventory. Sonder exemplifies the specialized professional apartment operator, focusing on tech-enabled, hotel-like accommodations to meet demand for standardized reliability. These entities shape market access and consumer choice through their extensive networks and service differentiation.
| Leading Market Players |
|---|
| Expedia Group |
| AvantStay |
| Airbnb |
| AltoVita |
| Blueground |
| Vrbo |
| Sonder |
| Llivo |
| Booking.com |
| Others |
Cost & Logistics Intelligence
Operational efficiencies from scale economies shape the alternative accommodation market's supply concentration and price floors. Large platforms leverage extensive networks to negotiate distribution terms, influencing property visibility and booking rates. This scale also supports investment in property technology, driving down per-unit management costs for professional operators.
Pricing Analysis
Corporate travel buyers anchor contract-based pricing for serviced apartments, seeking negotiated rates and consistent quality for extended stays. Price differentiation stems from property location within urban centers or tourist hotspots and the level of professional management and amenities provided. Pricing pressure stems from the increasing competition from traditional hotel chains expanding into extended-stay formats. Tourists exhibit the highest price sensitivity, often seeking budget-friendly vacation rentals through mobile booking applications.
Supply Chain Analysis
Spain and the United States anchor the vacation rental inventory, particularly in secondary cities, while Japan and Germany contribute significantly to professionally managed serviced apartments. The supply chain draws from property owners, real estate developers, and technology providers for smart home integration. A structural supply chain risk is the fragmented and localized regulatory landscape, increasing compliance costs and limiting inventory growth in key markets. Distribution runs through dominant online travel agencies and direct booking channels, with corporate partnerships securing inventory for business travel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternative accommodation market is undergoing a cyclical recovery, driven by a post-pandemic surge in leisure travel and the sustained demand for flexible work arrangements.
For Market Incumbents: Consolidate fragmented inventory by acquiring smaller regional operators with strong local compliance records. Invest in advanced property technology platforms to standardize operations and enhance guest experience, mitigating the threat from inconsistent quality standards. Control distribution channels by strengthening direct booking capabilities and loyalty programs, reducing reliance on online travel agencies.
For New Entrants and Emerging Players: A service-layer gap exists for professionally managed, tech-enabled properties in underserved secondary cities within the United States and Spain. Target niche segments like digital nomads or multi-generational families seeking tailored amenities and reliable connectivity. Develop a direct-to-consumer go-to-market strategy focusing on community building and personalized experiences to build brand loyalty.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms and operators that leverage data-driven management and smart home technology for operational efficiency. Long-term viability hinges on the continued shift towards flexible work models and experiential travel, driving demand for non-traditional lodging. Monitor regulatory harmonization efforts, such as the EU's proposed data-sharing framework, as a key inflection indicator for scalable investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Property Technology Integration | Enhances operational efficiency and standardizes guest experiences across diverse portfolios. |
| Secondary City Expansion | Captures new demand in less saturated markets with fewer regulatory restrictions. |
| Direct Booking Channel Development | Increases margin capture and strengthens brand loyalty by reducing OTA dependency. |
| Regulatory Compliance Automation | Mitigates legal risks and reduces administrative burdens in complex regulatory environments. |
| Niche Segment Specialization | Differentiates offerings and secures higher margins by targeting specific traveler needs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with property managers, platform executives, local tourism officials, and real estate developers. This primary data was then validated against extensive secondary research, including government tourism reports, company annual reports, and academic studies. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy across all market segments.
The analytical framework models market dynamics across the analysis window, segmenting by property type, customer profile, booking channel, and price tier. Industry-specific dimensions, such as regulatory impact and technology adoption rates, were also integrated into the model. Compound annual growth rates were derived from historical data analysis and projected market trends, reflecting the interplay of supply, demand, and regulatory forces.
Forecasts assume regulatory continuity in the EU, Japan, and the United States; material policy shifts would require re-modeling. These projections reflect assumptions regarding economic stability, consumer travel patterns, and technological advancements within the alternative accommodation sector. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Sweden Hospitality Market
Accommodation
China Online Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
Canada Hospitality Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
UAE Hospitality Market
Accommodation
Croatia Hospitality Market
Accommodation
Luxury Hotel Market
Accommodation
Extended Stay Hotel Market
Accommodation
China Tourism and Hotel Market
Accommodation
Africa Hotel Market
Accommodation
US Student Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
Switzerland Hospitality Market