
 France Online Accommodation Market | 2026-2036
France Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
France Online Accommodation Market Foresight
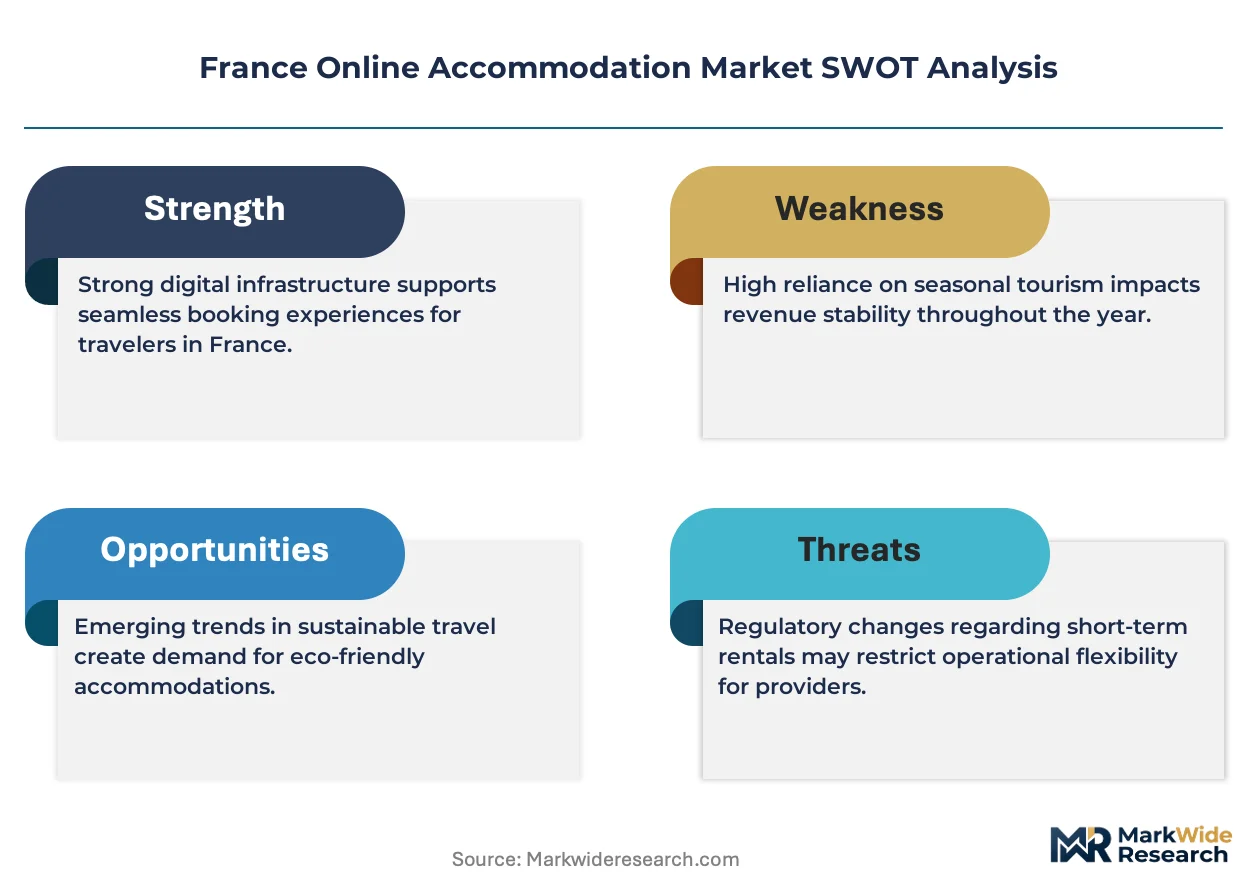
Paris-based hotel inventory management is shifting toward algorithmic pricing and direct-channel incentives. Booking.com leverages its global supply network to secure rate parity advantages across French urban centers. AccorHotels sustains its domestic dominance through a hybrid model that combines owned properties with franchised distribution. Airbnb differentiates by expanding its Experiences overlay and boutique inventory in secondary French cities.
France online accommodation encompasses digitally intermediated lodging reservations where platforms match travelers with property inventory through real-time availability engines, dynamic pricing algorithms, and secure payment tokenization. The ecosystem serves both inventory holders seeking yield optimization and travelers demanding instant confirmation with flexible cancellation terms. OTA websites anchor transaction volume through bundled flight-hotel packages and loyalty currency redemption, while mobile apps capture impulse bookings from same-day leisure travelers. Vacation rentals within the accommodation type split attract extended-stay corporate clients seeking kitchen-equipped alternatives to traditional hotels.
France's national digital services tax framework intersects with EU platform transparency regulations to elevate compliance costs for foreign-domiciled intermediaries. The country's competition authority scrutinizes most-favored-nation clauses in platform-hotel contracts, reshaping rate distribution economics. ANSM and CNIL oversight of consumer data handling adds a privacy-compliance layer to guest identity verification workflows. Stakeholders must monitor evolving national enforcement patterns around algorithmic pricing transparency and short-term rental registration mandates.
Market Dynamics
Algorithmic pricing engines and EU platform transparency mandates are compressing commission margins while forcing property aggregators to restructure data-sharing workflows with French inventory holders.
Growth Catalysts
- Mobile booking penetration:Smartphone-native leisure travelers now complete same-day reservations through app-based interfaces, expanding addressable demand beyond traditional advance-planning segments.
- France's digital services tax framework:The 3% levy on platform revenues is accelerating domestic operator consolidation as smaller intermediaries exit rather than absorb compliance overhead.
- Extended-stay corporate demand:Kitchen-equipped vacation rentals attract project-based consultants seeking alternatives to extended hotel stays in Paris and Lyon business districts.
Market Restraints
- Peak-season inventory scarcity:Physical room stock constraints in Provence-Alpes-Côte d'Azur corridors limit platform transaction volume during July-August high-demand windows.
- CNIL data-handling requirements:France's data protection authority mandates explicit consent protocols for guest identity verification, adding friction to instant-confirmation booking flows.
- Short-term rental registration mandates:Municipal registration requirements in Paris, Bordeaux, and Marseille create administrative barriers for individual property listers.
Strategic Opportunities
- Secondary city boutique inventory:Underserved accommodation supply in Nantes, Strasbourg, and Toulouse offers first-mover positioning for curated collection platforms.
- EU platform transparency rules:Mandatory disclosure of ranking algorithm parameters creates competitive opening for challengers to differentiate through explainable recommendation systems.
- Experiences overlay bundling:Convergence of lodging reservations with localized activity bookings enables commission stacking beyond room-night margins.
Industry Challenges
- Algorithmic pricing talent scarcity:Yield optimization specialists capable of building dynamic pricing models for fragmented vacation rental supply remain concentrated within Paris-based hospitality technology clusters.
- Rate parity enforcement complexity:France's competition authority scrutiny of most-favored-nation clauses demands continuous contract renegotiation with hotel chains and independent property owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Online Accommodation Market |
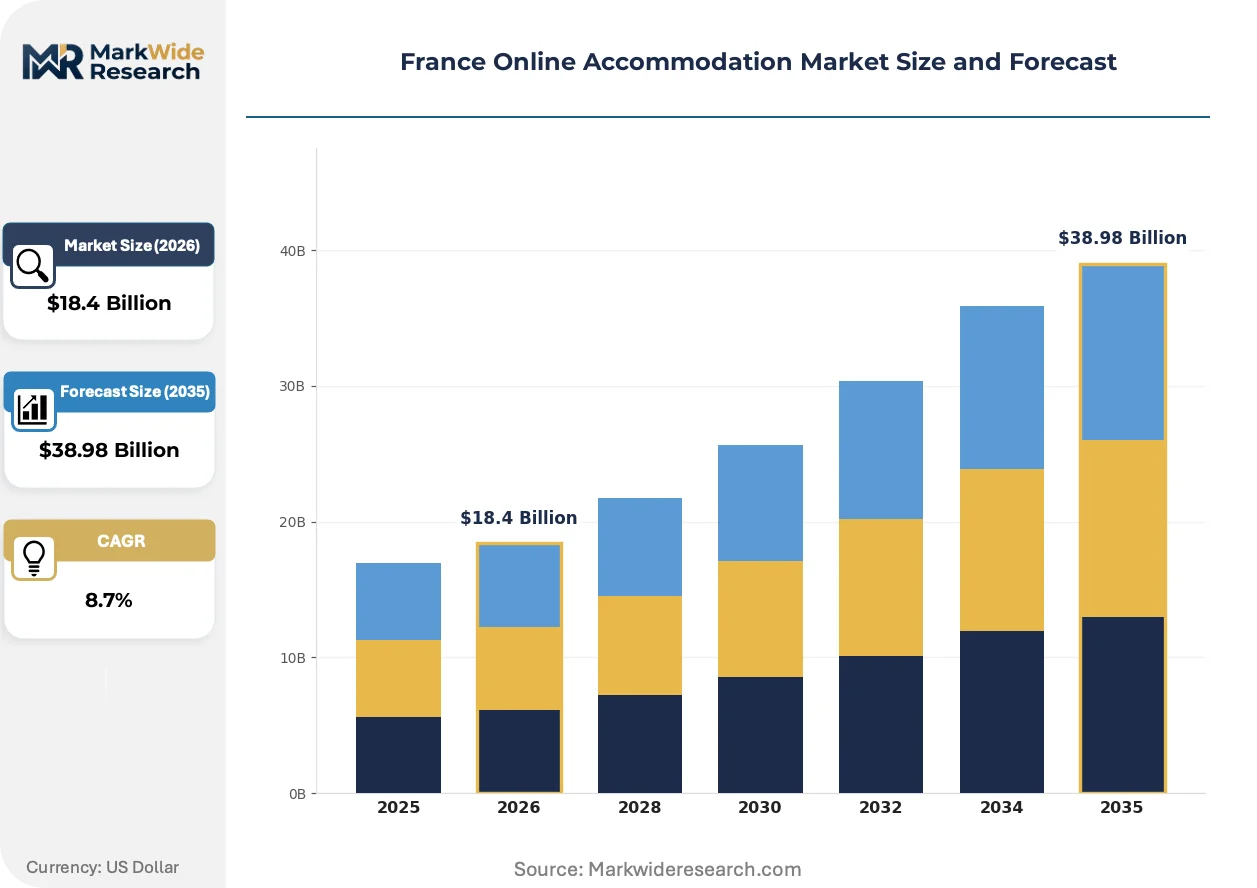
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Booking Platform: OTA Websites, Meta-Search Engines, Mobile Apps, Direct Supplier Portals, Affiliate Networks Accommodation Type: Hotels, Serviced Apartments, Hostels, Vacation Rentals, Boutique Inns, Guesthouses Customer Type: Leisure Travelers, Corporate Clients, Group Bookers, Solo Travelers, Family Vacationers Payment Method: Prepaid, Pay at Property, Partial Payment, Mobile Wallets, Credit Cards |
| Companies Covered | Booking.com, AccorHotels, Airbnb, Expedia, Hotels.com, TripAdvisor, Trip.com Group, Trivago, Lastminute.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Online Accommodation Market Shifts & Advancements
Real-time availability engines and guest verification protocols are undergoing rapid recalibration as French regulators tighten oversight of platform-hotel contractual relationships and short-term rental compliance.
Dynamic pricing algorithms are converging with machine learning-driven demand forecasting to enable micro-interval rate adjustments based on local event calendars, weather patterns, and competitive inventory positioning. Mid-scale hotel operators in Lyon and Nice are adopting these systems fastest, compressing the pricing response window from daily to hourly increments and eroding traditional revenue management team structures.
France's national digital services tax intersects with EU-wide platform transparency regulations to elevate compliance architecture requirements for foreign-domiciled intermediaries. The ANSM and CNIL oversight layers add privacy-verification steps to guest onboarding workflows, most acutely affecting platforms targeting Paris luxury inventory where high-value transactions trigger enhanced due diligence thresholds.
Corporate travel procurement patterns are fragmenting as distributed project teams book non-traditional extended-stay inventory through consumer-grade platforms rather than negotiated corporate rate programs. Procurement departments in pharmaceutical and consulting verticals now reconcile employee-direct bookings against policy, with the Rhône-Alpes and Occitanie regions showing the highest leakage rates from managed travel programs.
France Online Accommodation Market Segmentation
Platform architecture and accommodation format choices determine commission economics and guest acquisition costs for French intermediaries. Segmentation reveals where mobile-first interfaces displace legacy web bookings and which property types capture extended-stay corporate leakage from traditional hotel programs.
Booking Platform:
Real-time inventory aggregation technology separates high-frequency transaction engines from static listing repositories.
- OTA Websites:Browser-based booking interfaces dominate bundled flight-hotel package sales and loyalty currency redemption workflows. Paris and Lyon business districts generate the highest average booking values through these channels, though mobile apps are displacing same-day leisure reservations.
- Mobile Apps:Native smartphone applications capture impulse bookings through push-notification price alerts and one-tap payment tokenization. Provence-Alpes-Côte d'Azur leisure corridors show the deepest app penetration among last-minute bookers seeking instant confirmation.
- Meta-Search Engines:Comparison aggregators redirect traffic to supplier direct channels or OTAs through rate parity monitoring.
- Direct Supplier Portals:Hotel chain proprietary sites bypass platform commissions through member-rate incentives.
- Affiliate Networks:Content publisher partnerships drive referral traffic through blog and review site integrations.
Mature deployment sits with OTA Websites. Newer deployment is concentrated in Mobile Apps.
Accommodation Type:
Physical inventory characteristics shape cancellation policy flexibility and length-of-stay economics for platform matchers.
- Hotels:Standardized room stock with 24-hour reception and daily housekeeping supports algorithmic yield management systems. Paris arrondissements and Nice seafront zones concentrate branded chain inventory where dynamic pricing responds to convention calendars.
- Vacation Rentals:Kitchen-equipped apartments and villas attract project-based consultants seeking alternatives to extended hotel stays. Rhône-Alpes and Occitanie regions show the highest corporate leakage into this category from managed travel programs.
- Serviced Apartments:Hybrid inventory combining hotel services with residential amenities targets multi-week business assignments.
- Hostels:Shared dormitory and private room formats serve budget-conscious solo travelers and student groups.
- Boutique Inns:Small-format properties with localized design differentiation appeal to experience-seeking leisure segments.
- Guesthouses:Owner-operated rural properties capture seasonal demand in secondary French destinations.
Revenue concentration remains with Hotels. Inventory expansion is climbing the fastest in Vacation Rentals.
Customer Type:
Booking behavior patterns and cancellation risk profiles vary sharply across traveler motivation categories.
- Leisure Travelers:Price-sensitive holiday bookers drive peak-season demand compression in coastal and alpine zones. Mobile app interfaces capture their same-day reservation behavior most effectively.
- Corporate Clients:Policy-constrained business travelers generate midweek demand in Lyon and Marseille financial districts. Procurement departments now reconcile employee-direct platform bookings against negotiated rate programs.
- Group Bookers:Multi-room coordinators seek block availability with flexible attrition terms.
- Solo Travelers:Individual bookers prioritize location density and review volume over price alone.
- Family Vacationers:Multi-generational units require connecting rooms or apartment-style space configurations.
Volume leadership sits with Leisure Travelers. Policy leakage is expanding most quickly among Corporate Clients.
Payment Method:
Settlement timing and fraud risk allocation determine platform working capital requirements and host cash flow predictability.
- Credit Cards:Card-present and card-not-present transactions dominate high-value bookings through 3D Secure authentication protocols. Paris luxury inventory segments show the highest authorization value thresholds triggering enhanced due diligence.
- Mobile Wallets:Apple Pay and Google Pay integration reduces checkout friction for app-native demographics. Younger leisure travelers in Bordeaux and Nantes urban centers adopt these methods fastest.
- Prepaid:Full advance payment secures inventory commitment and reduces no-show risk.
- Pay at Property:Post-stay settlement preserves guest flexibility but increases cancellation exposure.
- Partial Payment:Deposit structures balance commitment with refundable security for extended stays.
Transaction dominance sits with Credit Cards. Adoption momentum is gaining share fastest in Mobile Wallets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's data center infrastructure and hospitality technology clusters anchor France's online accommodation distribution architecture. The country's platform economy concentrates in Paris, Lyon, and coastal leisure corridors where inventory scarcity shapes competitive dynamics.
Île-de-France
Paris arrondissements generate the highest transaction densities through corporate travel leakage and luxury inventory aggregation. ANSM and CNIL oversight layers mandate enhanced due diligence protocols for high-value bookings. The Paris-Saclay technology cluster houses yield optimization specialists building dynamic pricing engines for fragmented supply.
Auvergne-Rhône-Alpes
Lyon's financial districts drive midweek corporate demand into both branded hotels and extended-stay vacation rentals. Municipal short-term rental registration requirements create administrative friction for individual property listers. The Lyon-Grenoble corridor concentrates algorithmic pricing talent among hospitality technology startups.
Provence-Alpes-Côte d'Azur
Coastal leisure corridors experience peak-season inventory scarcity that compresses platform transaction volumes during July-August windows. EU platform transparency rules reshape contractual relationships between aggregators and independent hoteliers. Nice and Cannes seafront zones deploy hourly dynamic pricing responding to convention calendars and yachting events.
Nouvelle-Aquitaine
Bordeaux's urban center shows fastest mobile wallet adoption among younger leisure demographics booking last-minute inventory. France's digital services tax accelerates domestic operator consolidation as smaller intermediaries exit. The Bordeaux-Toulouse axis attracts boutique inventory platforms targeting underserved secondary city supply.
Occitanie
Project-based consultants in pharmaceutical and consulting verticals book kitchen-equipped vacation rentals through consumer-grade platforms. Procurement departments reconcile employee-direct bookings against negotiated corporate rate programs. Montpellier and Toulouse business districts exhibit highest leakage rates from managed travel programs into alternative accommodation formats.
France Online Accommodation Market Competitive Landscape
Global majors compete with regional champions across commission structures and inventory access dimensions. The market exhibits tiered consolidation where scale-driven platforms command rate parity advantages while specialized aggregators capture niche supply segments. Three archetypes dominate: global OTA networks with bundled service ecosystems, hybrid hotel chains combining owned properties with franchised distribution, and experience-overlay platforms integrating lodging with localized activities. Dominant competitive moves include direct-channel incentive programs and algorithmic pricing capability acquisitions.
Within the global OTA tier, Booking.com and Expedia occupy positions defined by supply network breadth and loyalty currency integration. AccorHotels anchors the hybrid chain archetype through its Paris-based owned-franchise model. Airbnb exemplifies the experience-overlay vector with its boutique inventory expansion in secondary French cities. These three represent the strategic poles around which smaller intermediaries cluster.
| Leading Market Players |
|---|
| Booking.com |
| AccorHotels |
| Airbnb |
| Expedia |
| Hotels.com |
| TripAdvisor |
| Trip.com Group |
| Trivago |
| Lastminute.com |
| Others |
Supply & Pricing Matrix
EU platform transparency rules gate access to premium-tier commission structures and qualified inventory partnerships for France-based intermediaries. Properties demonstrating algorithmic pricing compliance and CNIL-aligned data protocols command rate parity advantages that unverified independent listers cannot match.
Pricing Analysis
Service-bundling differentiation separates platforms offering instant-confirmation guarantees and flexible cancellation from bare-listing aggregators. Commission structures stratify across premium inventory with yield-optimization support, standard properties with basic distribution, and economy-tier hosts absorbing self-service onboarding costs. Price differentiation hinges on algorithmic pricing sophistication and cancellation policy flexibility. Pricing pressure stems from France's digital services tax compressing margins on cross-border transactions. Leisure travelers in Provence-Alpes-Côte d'Azur corridors show highest price sensitivity, while corporate clients in Paris business districts prioritize policy compliance over rate minimization.
Supply Chain Analysis
CNIL certification and ANSM-aligned verification protocols gate access to high-value Paris luxury inventory segments. Supply concentrates in France, Spain, and Portugal for Mediterranean leisure corridors, with Amsterdam and London serving as yield-optimization technology hubs. Raw material dependencies include cloud compute infrastructure, payment tokenization APIs, and identity verification services. Single-source vulnerability sits with dominant OTA platforms controlling rate parity enforcement mechanisms. Distribution runs through platform-owned mobile applications, browser-based OTA portals, and direct-chain proprietary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's online accommodation market represents a consolidation play as digital services tax compliance costs force smaller intermediaries toward exit or acquisition. Platform transparency mandates and algorithmic pricing talent scarcity accelerate this concentration dynamic.
For Market Incumbents: Hedge against regulatory fragmentation by diversifying supply relationships across multiple French regions beyond Paris-Ile-de-France dominance. Acquire Lyon-based hospitality technology clusters to secure scarce yield-optimization talent before competitors lock in exclusive arrangements. Channel control through direct-booking incentive programs offsets commission margin pressure from rate parity scrutiny. For New Entrants and Emerging Players: Boutique hotel collection partnerships in Nantes, Strasbourg, and Toulouse offer white-space positioning with lower competitive density than saturated Paris arrondissements. Secondary city inventory aggregation avoids direct confrontation with Booking.com's supply network breadth. A curated-experience go-to-market angle leveraging localized activity bundling differentiates against commoditized room-night intermediation. For Investors and Strategic Acquirers: Municipal short-term rental registration mandate enforcement acceleration is the leading indicator that compliance-architecture capabilities will command acquisition premiums. Mid-scale platforms with CNIL-aligned verification workflows and algorithmic pricing engines represent viable targets over pure inventory aggregators lacking technology differentiation. Watch for ANSM enforcement patterns around guest identity protocols as the signal for regulatory compliance valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Pricing Engine Acquisition | Secures scarce Lyon-Grenoble talent clusters before competitor lock-in. |
| Direct-Channel Incentive Program Launch | Reduces OTA commission exposure under France's rate parity scrutiny. |
| CNIL-Aligned Verification Protocol Investment | Unlocks Paris luxury inventory segments with enhanced due diligence thresholds. |
| Secondary City Boutique Inventory Expansion | Captures underserved supply in Nantes, Strasbourg, and Toulouse corridors. |
| Experiences Overlay Bundling Integration | Enables commission stacking beyond room-night margins through localized activity partnerships. |
Research Methodology
Independent corroboration across platform revenue disclosures, municipal short-term rental registration databases, and ANSM compliance filings underwrites the qualitative findings. Primary interviews with hospitality technology executives, revenue management directors at Paris-based hotel chains, CNIL compliance officers, and yield-optimization specialists at Lyon-Grenoble startups combined with secondary validation from EU platform transparency regulatory texts, France's digital services tax implementation guidelines, and competition authority rulings on most-favored-nation clauses. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored the quantitative framework.
Comparable-period anchoring used historical booking volume patterns across pre-pandemic, recovery-phase, and stabilization windows to calibrate projection assumptions. Segmentation dimensions modeled include booking platform architecture, accommodation type, customer motivation category, and payment method across the analysis window. CAGRs derived from algorithmic pricing adoption curves, mobile penetration trajectories, and corporate policy leakage rates into alternative accommodation formats. Forecast inputs incorporated CNIL enforcement intensity indices and municipal registration mandate rollout timelines.
Caveats apply where ANSM or CNIL enforcement pattern shifts, algorithmic pricing talent migration, or EU platform transparency rule amendments could materially shift the outlook. Forecasts reflect documented assumptions about regulatory stability and technology adoption continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Youth Summer Camp Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Europe Student Accommodation Market
Accommodation
Italy Online Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Movie Theaters Market
Accommodation
In-Flight Catering Services Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Africa Hotel Market
Accommodation
Extended Stay Hotel Market
Accommodation
Canada Hospitality Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
US Student Accommodation Market
Accommodation
Luxury Hotel Market