
 India Online Accommodation Market | 2026-2036
India Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
India Online Accommodation Market Foresight
Multi-source property aggregation is broadening supply access beyond traditional hotel chains. MakeMyTrip leverages its consolidated inventory to dominate metropolitan corridors. OYO Rooms anchors its position through standardized budget accommodations across secondary cities. Booking.com competes by extending its global loyalty infrastructure into Indian leisure destinations.
India online accommodation denotes digitally intermediated lodging reservations encompassing hotels, hostels, vacation rentals, and bed-and-breakfast establishments, where real-time inventory APIs, dynamic pricing algorithms, and payment-gateway integration enable instantaneous confirmation. The primary commercial purpose is to reduce friction between fragmented lodging supply and dispersed consumer demand while capturing commission revenue. Hotels retain the largest transaction volume share, though vacation rentals command superior margin pools in coastal and hill-station markets. Mobile apps represent the fastest-growing booking channel, reflecting UPI-enabled payment flows and vernacular-language interfaces. Business travelers generate higher per-booking value, but leisure travelers produce greater frequency and seasonal volume concentration.
BIS data-localization mandates and RBI payment-aggregator guidelines shape platform architecture and escrow requirements for domestic operators. CDSCO and state-level tourism authorities enforce hospitality safety standards that filter supplier eligibility on major platforms. State excise and municipal lodging taxes in Maharashtra, Goa, and Rajasthan create compliance complexity that favors platforms with dedicated regulatory technology teams. Stakeholders must monitor how proposed centralized tourism-registration systems alter supplier onboarding economics and commission structures.
Market Dynamics
Smartphone penetration across tier-two Indian cities is compressing booking windows and forcing platforms to rebuild their supply acquisition around vernacular interfaces and UPI-native payment flows rather than English-first desktop experiences.
Growth Catalysts
- Digital India infrastructure:BharatNet fiber expansion and PMGDISHA digital literacy programs are onboarding first-time internet users in secondary cities, expanding the addressable traveler base beyond metropolitan corridors.
- ODF+ certification standards:Swachh Bharat Mission's hospitality sanitation protocols are filtering uncertified suppliers off major platforms, improving conversion rates for compliant properties in pilgrimage and heritage circuits.
- Dynamic pricing APIs:Real-time revenue management systems are enabling small independent hotels to yield-manage inventory against airline and railway booking patterns, capturing spillover demand from transport delays.
Market Restraints
- State lodging tax fragmentation:Maharashtra, Goa, and Rajasthan maintain divergent excise and municipal tax structures, forcing platforms to maintain state-specific escrow configurations that inflate compliance overhead.
- Supplier concentration in coastal belts:Kerala and Karnataka beach clusters host disproportionate vacation rental inventory, creating seasonal price volatility and cancellation cascade risks during monsoon compression.
- Payment aggregator licensing:RBI's PA/PG guidelines mandate capital reserves and data localization that exclude sub-scale fintech partners from platform integration, narrowing gateway diversity.
Strategic Opportunities
- Religious circuit digitization:Char Dham and temple town accommodations in Uttarakhand, Tamil Nadu, and Odisha remain underplatformed, presenting first-mover aggregation potential for devotional travel verticals.
- PLI scheme spillover:Production-linked incentives for electronics manufacturing are expanding business travel corridors around Chennai, Bengaluru, and Noida, driving sustained weekday demand for serviced apartments.
- Vernacular voice interfaces:Hindi, Tamil, and Telugu natural-language booking flows are collapsing friction for non-English speakers, opening demographic segments previously excluded from online self-service.
Industry Challenges
- CDSCO hospitality safety audits:State-level fire and hygiene certification backlogs are delaying supplier onboarding timelines, forcing platforms to absorb extended pre-listing verification costs.
- Legacy PMS integration:Small hotels in tier-three towns operate on offline or non-API property management systems, requiring manual inventory reconciliation that degrades real-time availability accuracy.
- Skill scarcity in revenue management:Trained yield analysts are concentrated in Mumbai and Delhi, leaving secondary city properties unable to optimize dynamic pricing without platform-managed tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Online Accommodation Market |
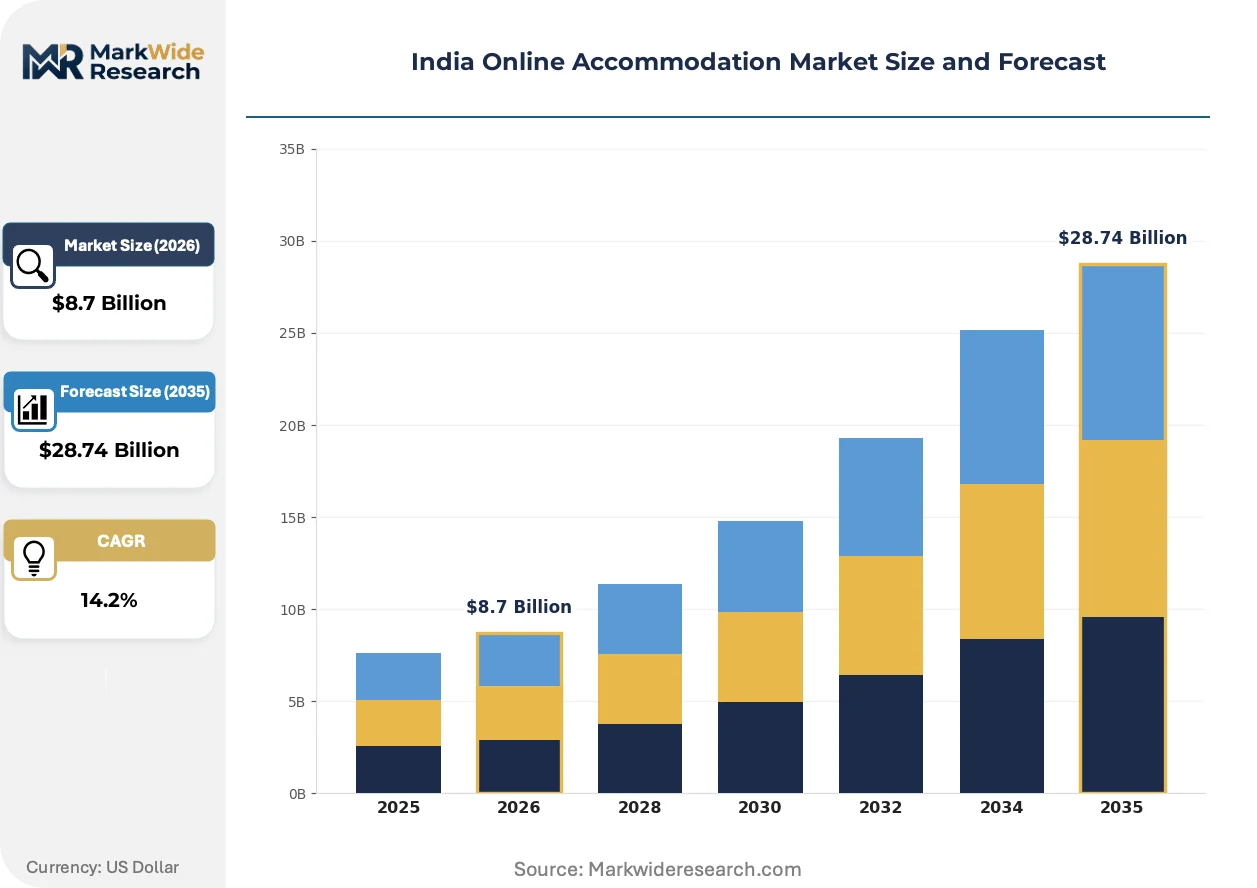
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfast Customer Type: Business Travelers, Leisure Travelers, Families, Solo Travelers Booking Channel: Online Travel Agencies, Direct Booking, Mobile Apps, Third-Party Websites Price Tier: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | Airbnb, Agoda, MakeMyTrip, AxisRooms, Treebo Hotels, OYO Rooms, Goibibo, eZee Reservation, Booking.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Online Accommodation Market Shifts & Advancements
Artificial intelligence is compressing the gap between traveler intent signals and inventory matching, while regulatory data-localization mandates and shifting booking-channel preferences are forcing architectural rebuilds across the value chain.
Conversational booking agents powered by large language models are unifying search, comparison, and payment into single-thread interactions. Domestic leisure travelers in Gujarat and Punjab are adopting these interfaces faster than business segments, drawn by voice-first vernacular support. This compression of the booking funnel is reducing platform abandonment rates and shifting competitive advantage toward AI-native operators over legacy form-based systems.
RBI's data-localization directives under the PA/PG framework are mandating domestic server storage for all transaction records. Platforms must now maintain India-resident infrastructure for payment flows, raising capex requirements for foreign operators while creating compliance moats for domestic incumbents. The regulatory friction falls heaviest on mid-scale vacation rental aggregators lacking dedicated regtech teams.
Same-day booking windows are displacing advance-planning norms among younger travelers in Bengaluru and Hyderabad. Mobile-native demand is replacing desktop pre-planning, with users expecting instant confirmation for tonight's stay. This behavioral compression is most visible in the unmarried professional segment, where flexible work arrangements enable spontaneous travel decisions that legacy cancellation policies fail to accommodate.
India Online Accommodation Market Segmentation
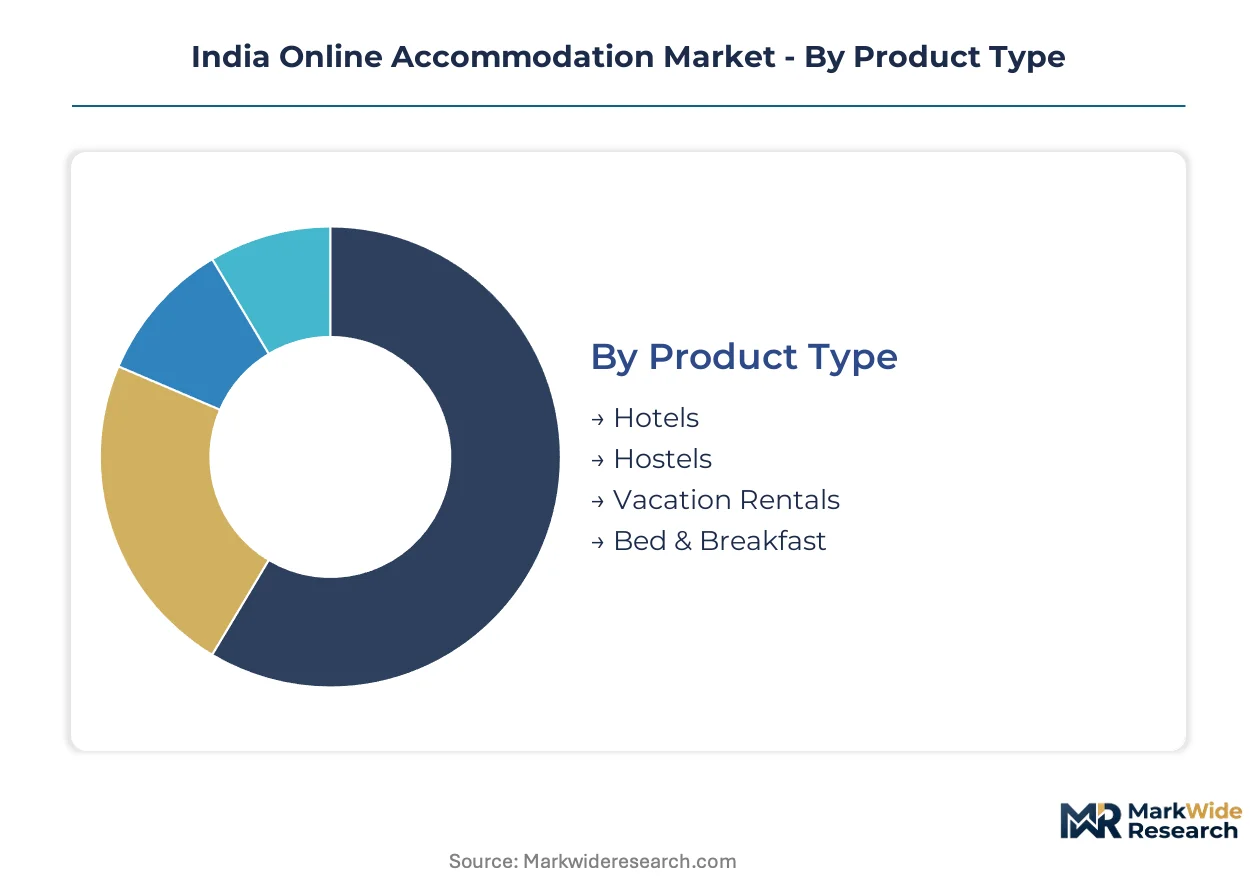
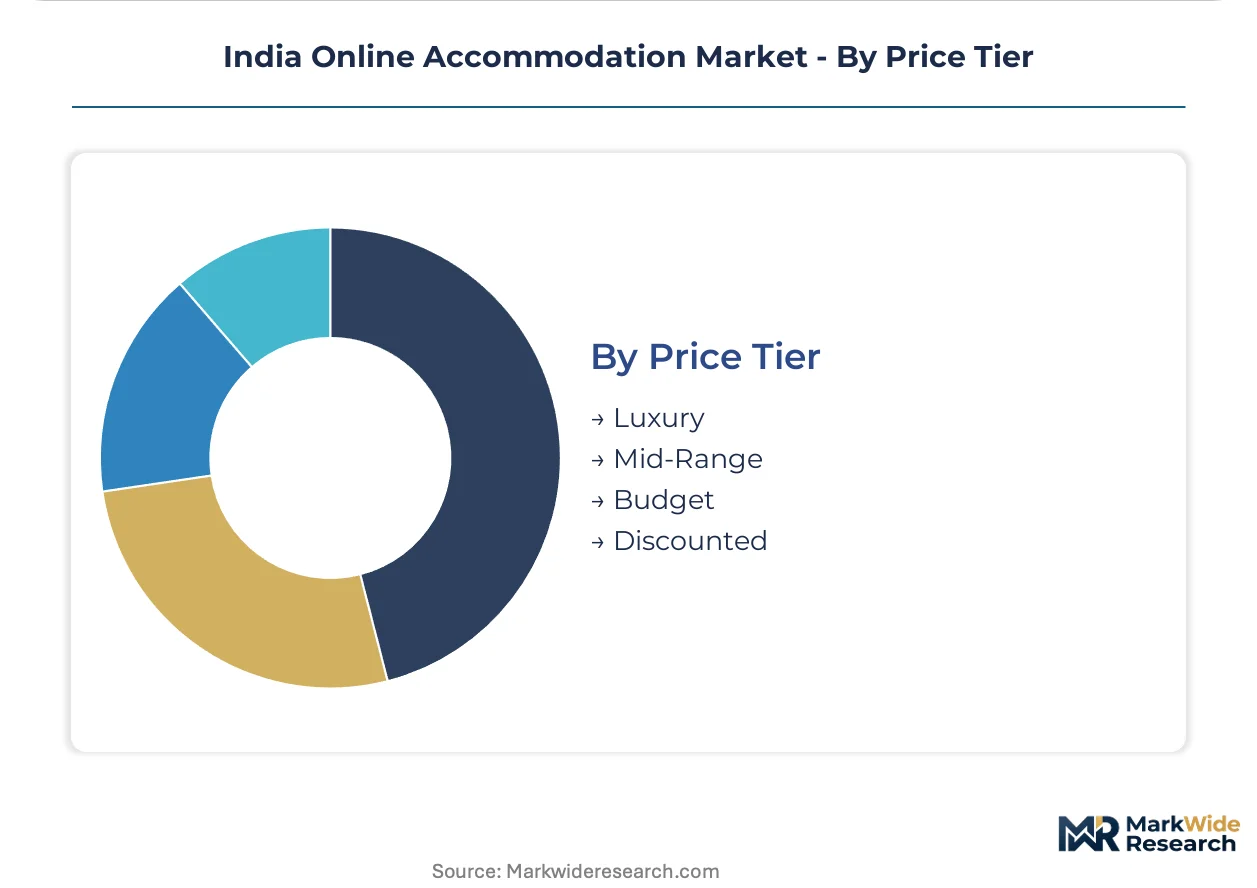
Segmentation in the India online accommodation market reveals how supply fragmentation and demand heterogeneity create distinct competitive arenas. Platform strategies diverge sharply across product types and price tiers, while booking channel preferences are compressing under mobile-first adoption.
Product Type:
Supply concentration in hotels dominates transaction volumes, though alternative lodging formats are capturing margin pools in specialized geographies.
- Hotels:Branded and independent properties with standardized amenities and front-desk services. Demand concentrates in Maharashtra and Karnataka business corridors, where corporate travel policies mandate invoice-ready accommodations with GST compliance.
- Vacation Rentals:Furnished apartments and private homes listed on aggregator platforms. Coastal Kerala and Goa beach clusters drive inventory growth, though monsoon seasonality creates utilization volatility that platforms address through dynamic discounting.
- Hostels:Dormitory and private-room formats targeting budget-conscious younger travelers. Pilgrimage circuits in Uttarakhand and Tamil Nadu absorb significant capacity during festival periods.
- Bed & Breakfast:Small-scale homestays with owner-operated hospitality. Heritage towns in Rajasthan and Madhya Pradesh leverage this format for experiential tourism differentiation.
Hotels absorb the bulk of installed capacity; vacation rentals are expanding most quickly.
Customer Type:
Travel purpose shapes booking behavior more than demographics, with business and leisure segments demanding incompatible platform features.
- Business Travelers:Corporate-account holders requiring centralized billing and flexible cancellation. Weekday demand concentrates in Bengaluru, Hyderabad, and Gurugram technology corridors where PLI scheme manufacturing investments sustain travel volume.
- Leisure Travelers:Domestic vacationers booking family and couple getaways. Weekend compression in Goa and Himachal Pradesh creates price spikes that platforms manage through advance-purchase incentives.
- Families:Multi-room bookings with kitchen and pooling preferences. Secondary city theme parks in Gujarat and Tamil Nadu anchor this segment's geographic concentration.
- Solo Travelers:Individual bookers prioritizing location and reviews over amenities. Work-from-anywhere professionals in Pune and Jaipur drive weekday hostel and co-living demand.
Business travelers generate the highest per-booking value; leisure travelers produce the steepest volume expansion trajectory.
Booking Channel:
Channel migration reflects smartphone penetration depth and payment infrastructure maturity across Indian states.
- Online Travel Agencies:Aggregator platforms consolidating inventory from fragmented supply. MakeMyTrip and Goibibo dominate this channel through vernacular interface investments and UPI-native checkout flows.
- Mobile Apps:Smartphone-native booking with push-notification pricing alerts. Tier-two cities in Uttar Pradesh and Bihar are migrating to this channel fastest as BharatNet connectivity expands.
- Direct Booking:Property-owned websites and call centers bypassing platform commissions. Luxury hotels in Mumbai and Delhi maintain this channel through loyalty program exclusives.
- Third-Party Websites:Affiliate and metasearch intermediaries without inventory control. Price comparison engines attract price-sensitive segments in competitive leisure markets.
Online travel agencies capture the majority of transaction flow; mobile apps are climbing the fastest.
Price Tier:
Price stratification maps directly to certification requirements and tax compliance burdens that filter supplier participation.
- Budget:Properties below INR 2,500 nightly with basic sanitation and security. OYO Rooms standardized this tier across tier-three towns, though CDSCO fire-safety certification backlogs constrain supply growth.
- Mid-Range:INR 2,500-7,500 segment with branded amenities and breakfast inclusion. This tier captures spillover demand from airline delays and railway cancellations in Chennai and Bengaluru.
- Luxury:Premium properties above INR 7,500 with concierge and spa services. Rajasthan palace hotels and Kerala backwater resorts anchor geographic concentration.
- Discounted:Flash sales and opaque inventory for distressed capacity. Same-day booking windows in Hyderabad and Pune activate this tier for perishable night inventory.
Budget tier absorbs the bulk of room nights; mid-range properties are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal tourism clusters and business corridor density anchor regional demand distribution across Indian states. Maharashtra, Karnataka, and Tamil Nadu concentrate platform investment due to urban infrastructure and transport connectivity advantages.
Maharashtra
Mumbai and Pune business travel sustains weekday hotel occupancy across mid-range and luxury tiers. The state's municipal lodging tax structure and GST compliance requirements filter supplier participation on major platforms. Navi Mumbai and Thane technology corridors absorb significant serviced apartment inventory from PLI scheme manufacturing investments.
Karnataka
Bengaluru's technology sector generates sustained corporate travel demand with centralized billing requirements. CDSCO fire-safety certification standards enforced by state tourism authorities delay supplier onboarding for independent properties. Coastal Karnataka beach clusters in Udupi and Mangalore drive vacation rental inventory expansion despite monsoon seasonality compression.
Tamil Nadu
Chennai's automotive and electronics manufacturing anchors business travel volume with invoice-ready accommodation demand. State-level hospitality sanitation protocols under Swachh Bharat Mission ODF+ certification improve conversion rates for compliant properties. Temple town circuits in Madurai and Rameswaram present underplatformed devotional travel aggregation opportunities.
Goa
Leisure travel concentration creates seasonal price volatility and weekend compression patterns across budget and mid-range inventory. Divergent excise and municipal tax structures compared to neighboring states force platforms to maintain dedicated escrow configurations. North Goa beach clusters host disproportionate vacation rental supply relative to year-round demand stability.
Rajasthan
Heritage tourism differentiation drives bed-and-breakfast format expansion in Jaipur and Udaipur palace-adjacent localities. State tourism authority registration systems and fire-safety audit backlogs constrain supply growth velocity. Jodhpur and Jaisalmer desert circuits absorb flash-sale inventory during festival periods with distressed capacity activation.
India Online Accommodation Market Competitive Landscape
Inventory aggregation partnerships dominate the current landscape as platforms compete for fragmented supply access. The market structures around three tiers: consolidated incumbents with vernacular interface investments, mid-scale aggregators with standardized budget formats, and global operators extending loyalty infrastructure. Strategic archetypes include supply-heavy consolidators, technology-native intermediaries, and asset-light aggregators. M&A activity and vernacular technology licensing represent the dominant competitive vectors reshaping positioning.
Among domestic consolidators, MakeMyTrip and Goibibo exemplify the supply-heavy archetype through consolidated inventory dominance and UPI-native payment flows. OYO Rooms occupies a position within the standardized budget tier, anchoring secondary city penetration through format consistency. Booking.com represents the global loyalty extension model, competing via international infrastructure deployment into Indian leisure destinations.
| Leading Market Players |
|---|
| Airbnb |
| Agoda |
| MakeMyTrip |
| AxisRooms |
| Treebo Hotels |
| OYO Rooms |
| Goibibo |
| eZee Reservation |
| Booking.com |
| Others |
Supply & Pricing Matrix
Same-day booking compression among unmarried professionals in Bengaluru and Hyderabad is forcing platforms to reconfigure inventory acquisition around perishable-night yield management, which intensifies margin pressure on mid-range properties unable to absorb cancellation risk.
Pricing Analysis
Warranty-like service bundling separates premium-tier properties with flexible cancellation and GST-compliant invoicing from budget inventory where these features remain unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels anchors on CDSCO fire-safety certification status and state lodging tax compliance rather than amenities alone. Pricing pressure stems from UPI-native payment flows compressing platform commission tolerance. Leisure travelers in Goa and Himachal Pradesh exhibit highest price sensitivity during weekend compression, while corporate account holders in Mumbai and Pune demonstrate lowest elasticity due to centralized billing mandates.
Supply Chain Analysis
Dual-sourcing requirements for payment gateway redundancy under RBI PA/PG guidelines force platforms to qualify multiple domestic aggregators, extending supplier onboarding timelines. Inventory acquisition concentrates in India, with secondary sourcing from Nepal and Sri Lanka for Himalayan and coastal pilgrimage circuits. Platform technology stacks draw from cloud infrastructure providers, vernacular NLP engines, and legacy PMS integration middleware. Single-source vulnerability sits with UPI infrastructure concentration under NPCI. Distribution runs through mobile app stores, vernacular social channels, and railway booking spillover partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RBI data-localization mandates and CDSCO certification requirements erect compliance moats that favor platforms with dedicated regtech teams, filtering sub-scale competitors from supplier aggregation economics.
For Market Incumbents: To counter same-day booking compression eroding cancellation revenue, deepen API integration with railway and airline delay feeds to capture spillover demand dynamically. Expand vernacular voice interface deployment across Hindi, Tamil, and Telugu markets to defend channel control against AI-native entrants. For New Entrants and Emerging Players: Direct-to-consumer religious circuit digitization in Uttarakhand temple towns offers the most penetrable white-space, where devotional travel verticals remain underplatformed. Target Char Dham aggregation through partnership with state tourism boards rather than competing for saturated coastal leisure inventory. For Investors and Strategic Acquirers: The window for entry favors domestic platforms with proven UPI-native checkout flows and existing BIS data-localization infrastructure. Monitor PLI scheme manufacturing corridor expansion around Chennai and Noida as the signal to watch for sustained business travel demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Vernacular Voice Interface Deployment | Hindi and Tamil NLP flows collapse booking friction for non-English speakers excluded from legacy platforms. |
| Religious Circuit Aggregation Partnership | Char Dham vertical capture opens devotional travel segments with lower competitive density than coastal leisure. |
| Regulatory Technology Team Buildout | CDSCO and RBI compliance automation accelerates supplier onboarding timelines against certification backlogs. |
| Dynamic Railway Spillover Integration | Real-time delay feed APIs capture distressed inventory demand from transport disruption patterns. |
| PLI Corridor Serviced Apartment Expansion | Electronics manufacturing investments around Bengaluru and Noida sustain weekday corporate account volume. |
Research Methodology
Independent corroboration across platform revenue executives, state tourism authority officials, hotel PMS vendors, and UPI gateway operators underwrites the qualitative findings. Primary fieldwork combined structured interviews with MakeMyTrip supply heads, OYO franchise operators, and Booking.com India market leads with secondary validation from BIS certification databases, RBI PA/PG licensing records, CDSCO hospitality safety filings, and state excise tax circulars. Bottom-up property inventory estimates triangulated against top-down digital payment flow data.
Comparable-period anchoring to pre-pandemic booking patterns and post-UPI adoption baselines structured the projection horizon. Segmentation modeling spanned product type, customer travel purpose, booking channel migration, and state-level regulatory cluster. CAGRs derived from logistic diffusion curves fitted to smartphone penetration depth and vernacular interface adoption rates. Forecast inputs incorporated BharatNet fiber rollout schedules and PLI scheme manufacturing investment announcements.
The model holds under stable UPI infrastructure and continued RBI data-localization enforcement; deviation in state lodging tax harmonization or CDSCO audit capacity would shift supplier onboarding economics materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Japan Hospitality Market
Accommodation
Casino Hotel Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Germany Student Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
In-Flight Catering Services Market
Accommodation
Africa Hotel Market
Accommodation
United States Online Accommodation Market
Accommodation
Europe Online Accommodation Market
Accommodation
Airport Sleeping Pods Market
Accommodation
China Tourism and Hotel Market
Accommodation
China Online Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
Extended Stay Hotel Market
Accommodation
UAE Hospitality Market
Accommodation
Asia-Pacific Student Accommodation Market