
 Movie Theaters Market | 2026-2036
Movie Theaters Market Size, Share, and Industry Trends Forecast 2026-2036
Movie Theaters Market Intelligence
The European Accessibility Act is rebalancing the cost-of-entry calculus for new cinema construction and major renovations across the EU. This regulatory pressure, mirrored by frameworks like the ADA in the United States, requires significant capital investment in infrastructure. AMC Theatres leverages its scale to absorb these costs while expanding premium formats. Cinépolis differentiates its brand through luxury VIP offerings in markets like Mexico and India, while Cineworld competes through its broad geographic footprint spanning Europe and North America.
Movie theaters are commercial venues designed for the public exhibition of motion pictures. These facilities employ specialized equipment, including high-lumen digital or laser projectors capable of 4K resolution and multi-channel sound systems, to deliver an immersive cinematic experience. While standard screenings form the base of ticket sales, premium formats such as IMAX and 3D movies generate higher per-ticket revenue. Within service offerings, the evolution of concession stands into elaborate in-theater dining is a significant trend for revenue enhancement.
Content exhibition is governed by national classification bodies, including the Motion Picture Association in the United States and India's Central Board of Film Certification (CBFC), which dictate audience ratings. Concurrently, operational standards for public venues are set by health and safety regulators like the US Occupational Safety and Health Administration (OSHA) and its European counterparts. For theater operators, the strategic allocation of capital between premium technology adoption and enhanced service offerings remains the central challenge.
Market Dynamics
The central dynamic in the movie theaters market is the strategic tension between funding capital-intensive technology upgrades, such as laser projection, and absorbing the significant costs associated with new accessibility mandates like the European Accessibility Act and the ADA.
Growth Catalysts
- Premium Formats:The adoption of premium large formats and immersive audio systems like Dolby Atmos allows theaters to command higher ticket prices, directly boosting per-patron revenue and justifying technology investments.
- Multiplex Expansion in Emerging Economies:Development of new, modern multiplexes in high-density urban centers within India and Brazil is capturing demand from a growing middle class with increasing disposable income for entertainment.
- Diversified Revenue Streams:Theaters are leveraging their physical spaces to host corporate events, private screenings, and e-sports tournaments, creating new income sources independent of the film release calendar.
Market Restraints
- Home Entertainment Competition:The availability of high-fidelity home theater systems and the vast content libraries of streaming services create a powerful substitution threat, particularly for films that are not major cinematic events.
- High Fixed Operating Costs:Substantial fixed costs from long-term property leases, energy consumption, and non-variable staffing levels make profitability highly sensitive to fluctuations in audience attendance and film slate quality.
- Content Licensing Complexity:Dependence on a concentrated number of film distributors and adherence to rigid theatrical release windows can constrain programming flexibility and negotiating power for theater operators.
Strategic Opportunities
- In-Theater Dining Expansion:Transforming basic concession stands into full-service restaurants or sophisticated bar-lounges provides a substantial opportunity to increase average revenue per customer and enhance the overall value proposition.
- Live and Interactive Events:Broadcasting live content, such as major sporting events, opera, and concerts, through digital cinema networks enables theaters to attract new demographics and utilize auditoriums during off-peak hours.
- Secondary City Development:Beyond saturated metropolitan hubs, opportunities exist for constructing modern cinema facilities in underserved secondary and tertiary cities in regions like Southeast Asia and Latin America.
Industry Challenges
- Accessibility Compliance Costs:Meeting the infrastructural requirements of regulations like the European Accessibility Act and the Americans with Disabilities Act during renovations or new builds requires significant, often non-revenue-generating, capital expenditure.
- Rapid Technology Obsolescence:The continuous evolution of projection and sound systems necessitates frequent and expensive upgrade cycles for theaters wishing to maintain a premium market position, posing a challenge for capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movie Theaters Market |
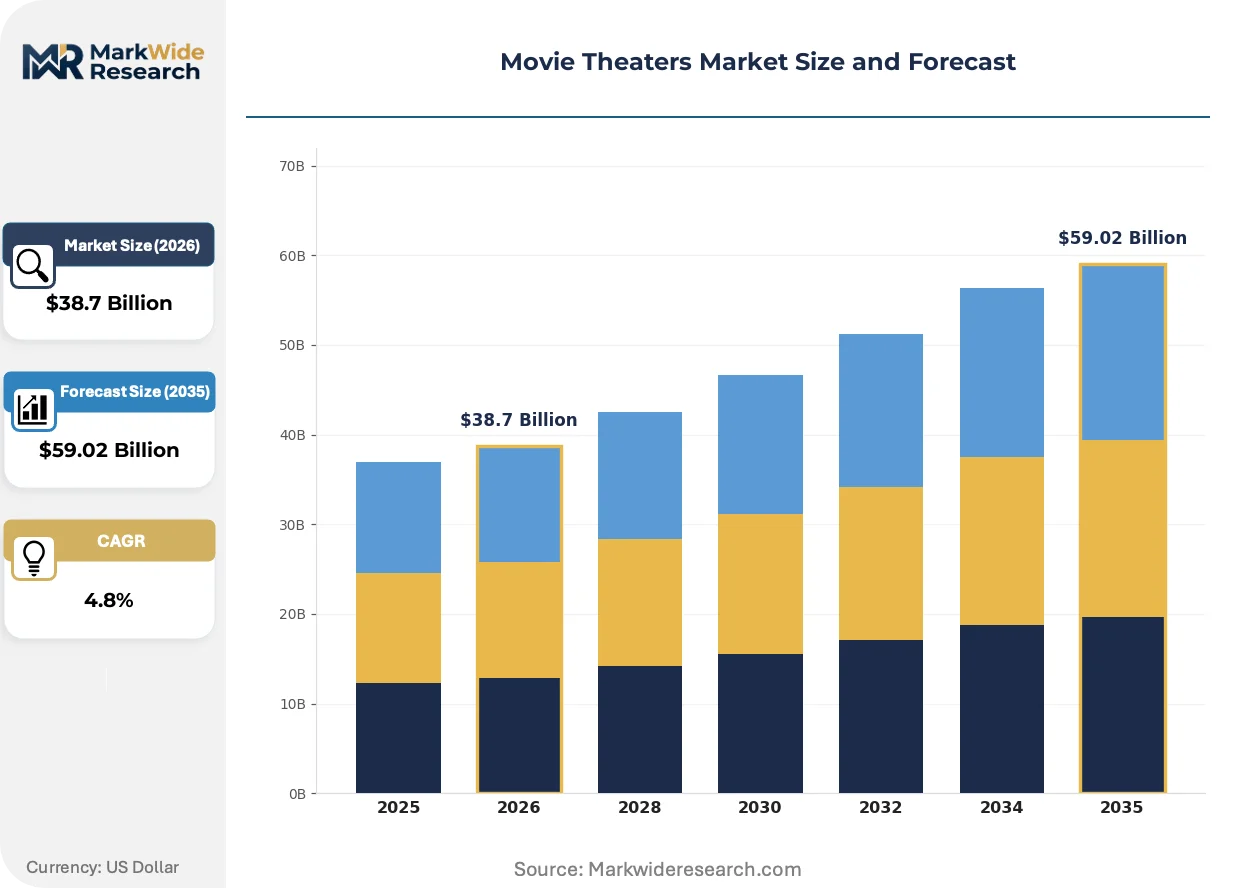
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Movie Type: 3D Movies, IMAX, Standard Screenings, Indie Films, Documentaries, Animation Service Offering: Concession Stands, VIP Seating, Private Screenings, Loyalty Programs, Online Booking, Event Hosting Projection Technology: Digital Projection, Laser Projection, Film Reel, LED Screens, 4K Projection, Dolby Atmos Customer Segment: Families, Students, Couples, Seniors, Movie Enthusiasts, Tourists |
| Companies Covered | AMC Theatres, Cinépolis, Cineworld, Cinemark, CGV, Cineplex, Regal, CGR Cinemas, Odeon Cinemas Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movie Theaters Market Strategic Shifts & Innovations
The experiential component of cinema is reshaping the market's value proposition, forcing operators to invest in both hyper-immersive technologies and differentiated service models. This pivot is a direct response to evolving consumer expectations and intense competition from at-home entertainment alternatives.
Laser projection technology offers superior brightness, color accuracy, and a longer operational life with lower maintenance compared to legacy xenon lamp systems. Major cinema circuits and premium format providers are leading the adoption for new constructions and flagship auditorium retrofits. Driven by a better total cost of ownership and enhanced visual performance, laser projection is overtaking lamp-based projectors as the new benchmark for a premium theatrical experience.
Implementation of the European Accessibility Act (EAA) sets a new baseline for cinema operations across the EU, mandating specific standards for physical access and digital services. The act compels theater owners to invest in features like accessible ticketing websites, audio description systems, and wheelchair-friendly layouts. This regulatory shift forces operators in Europe to integrate compliance into their financial planning, mirroring the long-standing impact of the ADA in the United States.
A pronounced shift in consumer spending towards experiences over goods is altering audience behavior. This trend disrupts the standard ticket model by increasing demand for luxury offerings like recliner seating, in-theater dining, and exclusive event screenings that carry a significant price premium. This demand-side evolution is most visible in developed markets across North America and Western Europe, where patrons demonstrate a willingness to pay more for a memorable outing.
Movie Theaters Market Segmentation
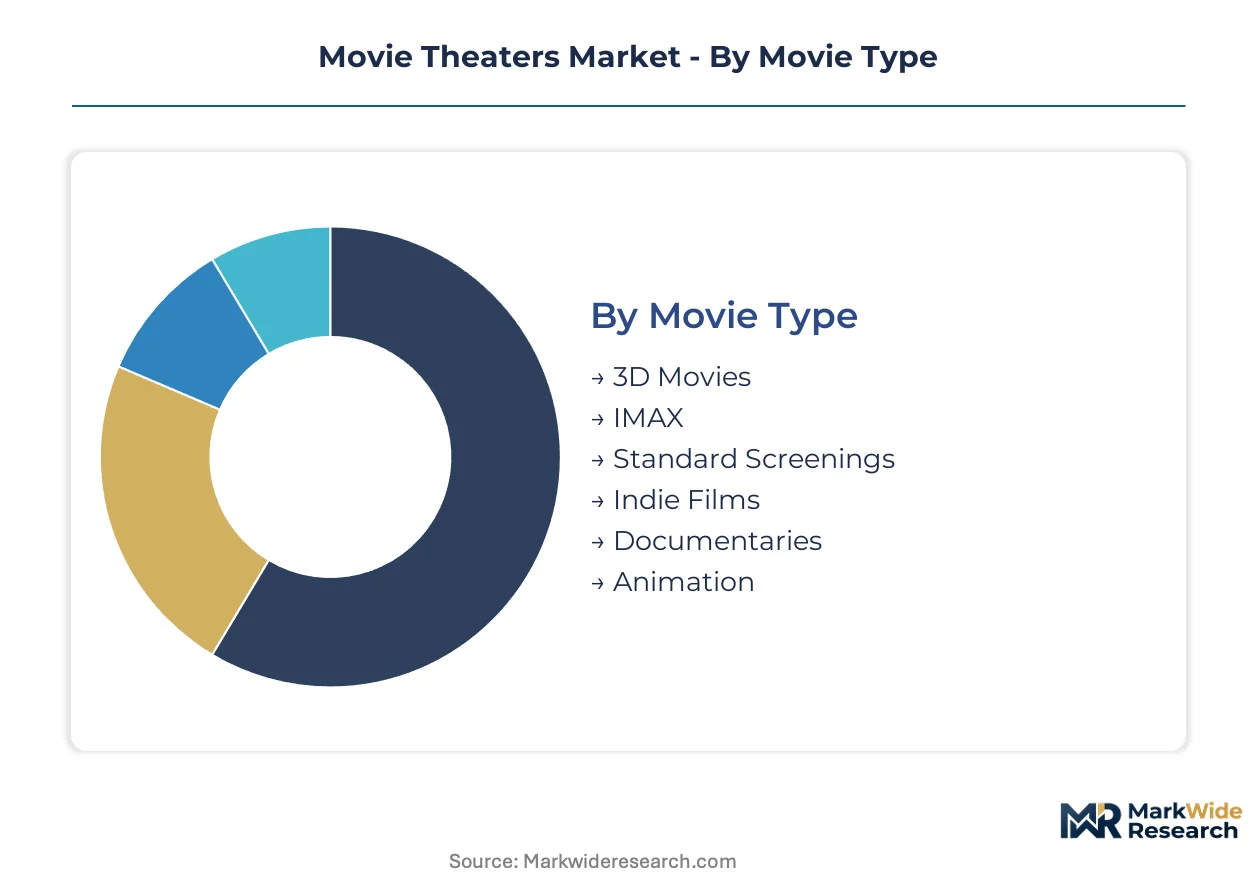
The Movie Theaters Market differentiates its offerings to capture diverse audience preferences and optimize revenue streams. Strategic segmentation allows operators to tailor experiences, from high-volume general admission to premium, immersive formats. This approach helps theaters adapt to evolving consumer demands and competitive pressures from home entertainment.
Movie Type:
The market's product differentiation relies heavily on the cinematic experience offered, ranging from mass-market appeal to niche artistic expressions.
- IMAX:This premium large format uses specialized cameras, projectors, and theater geometry to deliver a highly immersive visual and audio experience. Demand concentrates in major metropolitan areas globally, driven by blockbuster film releases and higher ticket price acceptance.
- Standard Screenings:These represent the foundational offering, utilizing conventional projection and sound systems for a broad range of film content. Volume demand remains consistent across all demographics, particularly in secondary cities within India and Brazil.
- 3D Movies:These films employ stereoscopic technology to create an illusion of depth, enhancing visual engagement for specific genres.
- Indie Films:This segment comprises independent productions, often appealing to niche audiences seeking diverse narrative and artistic styles.
- Documentaries:These non-fiction films provide educational or observational content, attracting viewers interested in real-world subjects.
- Animation:This category includes animated features and shorts, primarily targeting families and younger audiences with visually creative storytelling.
Mature deployment sits with Standard Screenings. Newer deployment is concentrated in IMAX.
Service Offering:
Service offerings differentiate the customer experience, moving beyond basic film exhibition to comprehensive entertainment packages.
- VIP Seating:This premium option provides enhanced comfort through recliners, additional space, and often in-seat food and beverage service. Demand for these luxury amenities is strong in developed markets like the United States and Western Europe.
- Event Hosting:Theaters leverage their auditoriums for non-film events such as corporate meetings, private parties, and e-sports tournaments. This diversifies revenue streams, particularly during off-peak hours.
- Concession Stands:These traditional outlets offer snacks, beverages, and other refreshments, forming a significant component of ancillary revenue.
- Private Screenings:Customers can rent entire auditoriums for exclusive viewing experiences with friends or colleagues.
- Loyalty Programs:These schemes reward frequent moviegoers with discounts, exclusive access, and special perks to encourage repeat visits.
- Online Booking:Digital platforms allow customers to purchase tickets and select seats remotely, enhancing convenience and reducing wait times.
The most established service offering is Concession Stands. The fastest-growing service offering is Event Hosting.
Projection Technology:
Investment in projection technology directly impacts the quality of the cinematic presentation, affecting both visual fidelity and operational efficiency.
- Laser Projection:This advanced technology provides superior brightness, contrast, and color accuracy with lower maintenance costs and a longer lifespan. Major cinema circuits in the United States and Europe are rapidly adopting laser systems for premium auditoriums.
- 4K Projection:This resolution standard delivers four times the detail of traditional 2K projectors, significantly enhancing visual clarity. Widespread adoption of 4K projection is seen in new multiplex developments in India and Brazil.
- Digital Projection:This broad category encompasses all non-film-based projection systems, replacing traditional film reels with digital files.
- Film Reel:This legacy technology uses physical celluloid prints for exhibition, now primarily found in arthouse cinemas or for specific archival screenings.
- LED Screens:These large-format displays offer high brightness and contrast, increasingly used for outdoor cinemas or specialized indoor venues.
- Dolby Atmos:This immersive audio technology creates a three-dimensional soundscape, complementing high-resolution visuals for a comprehensive sensory experience.
The most mature technology is Digital Projection. The technology expanding most quickly is Laser Projection.
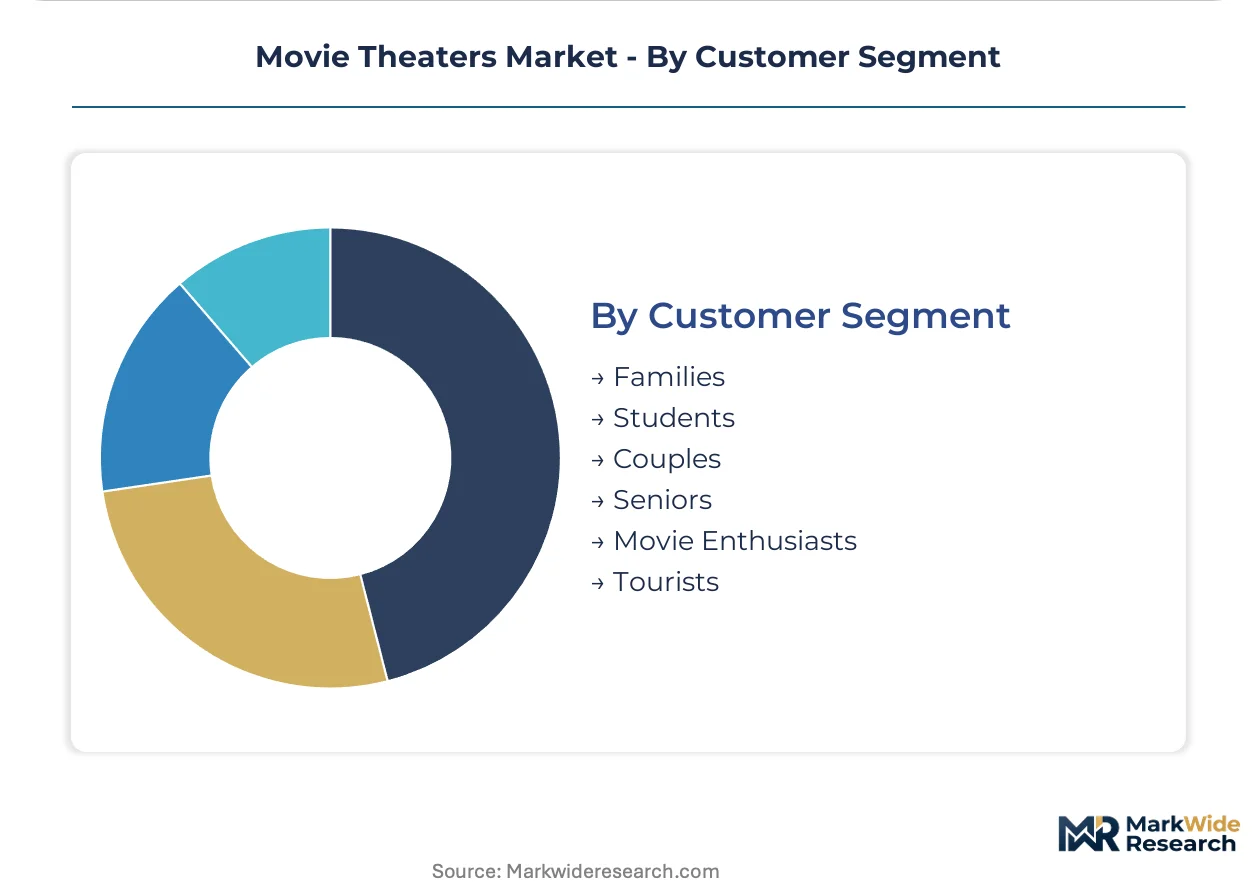
Customer Segment:
Understanding distinct customer segments enables theaters to tailor marketing efforts and service packages for maximum appeal.
- Families:This segment seeks entertainment options suitable for all ages, often prioritizing convenience, child-friendly amenities, and animated films. Families represent a consistent attendance base, particularly for weekend matinees.
- Movie Enthusiasts:These dedicated patrons follow film releases closely, often attending multiple screenings and seeking premium formats like IMAX or VIP experiences. This segment drives early box office performance and premium ticket sales.
- Students:This demographic often seeks affordable entertainment options, responding well to discounts and promotional offers.
- Couples:This segment values a comfortable and engaging social outing, often opting for evening shows and in-theater dining.
- Seniors:This group frequently attends weekday matinees, often appreciating accessible venues and value-oriented ticket pricing.
- Tourists:International visitors often seek unique cultural experiences, including attending films in prominent or historically significant theaters.
The segment with the broadest reach is Families. The segment gaining share fastest is Movie Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration is notable in key cities within India and Brazil, where new multiplexes are being developed to cater to a growing middle class. This regional expansion is supported by increasing disposable incomes and a cultural affinity for cinematic entertainment. Other developed markets continue to drive innovation through premium experiences and accessibility compliance.
United States
Movie enthusiasts and families drive consistent demand for both standard and premium format screenings across major metropolitan areas. The Americans with Disabilities Act (ADA) mandates significant capital investment for accessibility upgrades during renovations and new constructions. Major circuits in cities like Los Angeles and New York focus on integrating VIP seating and in-theater dining to enhance customer value.
India
Multiplex expansion in high-density urban centers across India captures significant demand from a rapidly expanding middle class. The Central Board of Film Certification (CBFC) governs content exhibition, influencing programming and audience ratings. New cinema facilities in Mumbai and Delhi-NCR are adopting 4K projection and immersive audio systems to attract discerning patrons.
Brazil
Growing disposable income fuels the development of modern multiplexes in major Brazilian cities, attracting a broad audience seeking entertainment options. Local urban development policies often guide the location and scale of new cinema projects, ensuring integration with commercial hubs. São Paulo and Rio de Janeiro are experiencing significant investment in new venues featuring premium large formats.
Germany
European Accessibility Act (EAA) implementation sets a new baseline for cinema operations, mandating specific standards for physical access and digital services across German theaters. Consumer spending patterns favor experiential outings, driving demand for luxury offerings like recliner seating and sophisticated bar-lounges. Berlin and Munich theaters are actively upgrading facilities to comply with EAA and enhance the overall customer experience.
Mexico
Cinépolis differentiates its brand through luxury VIP offerings in Mexico, catering to patrons seeking enhanced comfort and in-seat dining services. Urban planning regulations influence the construction of new cinema complexes, often integrating them into large shopping centers. Mexico City and Guadalajara see continuous development of modern cinemas focusing on premium amenities and diversified service offerings.
Movie Theaters Market Key Industry Players
Western operators anchor one tier, emphasizing premium formats and accessibility compliance in mature markets; expanding international groups hold another, focusing on new market penetration and luxury experiences. The market structure exhibits a blend of large, publicly traded chains and smaller, regionally focused independent operators. Strategic archetypes include global scale providers, luxury experience innovators, and regional volume players. Dominant competitive moves involve geographic expansion into emerging economies and continuous investment in premium technology adoption.
Among global scale providers, AMC Theatres represents a significant presence, leveraging its extensive network to absorb compliance costs while expanding premium formats. Cinépolis exemplifies the luxury experience innovator, actively differentiating its brand through VIP offerings in markets like Mexico and India. Cineworld occupies a broad geographic footprint across Europe and North America, competing through its widespread operational scale and diverse portfolio of cinema experiences.
| Leading Market Players |
|---|
| AMC Theatres |
| Cinépolis |
| Cineworld |
| Cinemark |
| CGV |
| Cineplex |
| Regal |
| CGR Cinemas |
| Odeon Cinemas Group |
| Others |
Cost & Logistics Intelligence
The European Accessibility Act mandates significant infrastructure investments, forcing cinema operators to absorb compliance costs and influencing technology procurement, which impacts pricing for premium experiences.
Pricing Analysis
The movie theaters market balances high-volume standard screenings with higher-margin premium formats like IMAX and VIP seating. Price differentiation stems from immersive technology adoption and luxury service offerings, such as in-theater dining. Pricing pressure stems from intense competition from home entertainment, particularly for non-blockbuster content. Movie enthusiasts exhibit lower price sensitivity for premium experiences, while families often seek value-oriented standard screenings.
Supply Chain Analysis
Specialized technical expertise for projection and audio system installation remains critical, particularly in manufacturing hubs like China and Japan. The supply chain for advanced cinema technology primarily draws from global electronics manufacturers. Key components include high-lumen laser light engines, 4K digital cinema servers, and multi-channel audio processors. Single-source vulnerability for specialized projection components poses a significant supply chain risk. Distribution runs through a network of specialized integrators and direct sales channels to cinema operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The movie theaters market is poised for consolidation, driven by the significant capital expenditure required for accessibility compliance and premium technology upgrades. Smaller, independent operators face immense pressure to adapt or exit.
For Market Incumbents: To counter the substitution threat from home entertainment, incumbents must accelerate investment in premium formats like IMAX and Dolby Atmos. Expanding in-theater dining options and event hosting diversifies revenue beyond traditional ticket sales. Leveraging scale allows absorption of accessibility compliance costs and secures favorable content licensing terms. This strategy enhances the experiential value, differentiating cinema from at-home viewing. For New Entrants and Emerging Players: A price-point gap exists between high-end VIP experiences and basic standard screenings, creating an opportunity for mid-tier luxury. Emerging players can target underserved secondary cities in regions like Southeast Asia with modern, amenity-rich multiplexes. Focus on a hybrid model offering comfortable seating and enhanced concessions without full VIP pricing. A strong go-to-market angle involves community engagement and localized content programming. For Investors and Strategic Acquirers: The window for entry favors well-capitalized entities seeking long-term growth through market consolidation. Acquisition targets include regional chains with strong local real estate positions or innovative technology providers. Focus on entities possessing differentiated service models or strong footholds in emerging economies like India and Brazil. A signal to watch is the sustained recovery of box office revenues post-pandemic, indicating consumer willingness to return to theaters.| Strategic Initiative | Industry Significance |
|---|---|
| Expand Premium Format Footprint | Enhances per-patron revenue and differentiates the cinematic experience from home viewing. |
| Diversify Event Hosting Services | Creates new income streams independent of film release schedules and utilizes off-peak hours. |
| Invest in Accessibility Upgrades | Ensures compliance with regulations like EAA and ADA, broadening audience reach and market access. |
| Develop In-Theater Dining Options | Increases average spend per customer and elevates the overall luxury perception of the venue. |
| Target Secondary City Development | Captures demand from growing middle classes in underserved regions like India and Brazil. |
Research Approach
Independent corroboration across industry association reports, financial filings of major cinema chains, and government cultural statistics underwrites the qualitative findings. This study combined primary interviews with cinema operators, technology vendors, and content distributors. Secondary validation involved public company reports and regulatory filings with the MPA and CBFC. A dual bottom-up and top-down triangulation approach ensured data consistency.
Rate-of-change decomposition modeled the market across the analysis window, considering historical trends and future projections. Segmentation dimensions included movie type, service offering, projection technology, and customer segment, alongside regional economic growth. Compound annual growth rates were derived from detailed analysis of market drivers. Key forecast inputs included disposable income trends and technology adoption rates.
Inputs from major cinema circuit financial reports were available through the study window; gaps in granular regional consumer spending data introduce uncertainty bands. Forecasts reflect assumptions regarding film slate quality and regulatory stability. Material deviation in film distribution or accessibility mandates warrants re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
France Casino Tourism Market
Accommodation
Russia Online Accommodation Market
Accommodation
Airport Sleeping Pods Market
Accommodation
Sri Lanka Hospitality Industry Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
France Hospitality Market
Accommodation
Extended Stay Hotel Market
Accommodation
Switzerland Hospitality Market
Accommodation
Underwater Hotels Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Germany Student Accommodation Market
Accommodation
Japan Online Accommodation Market
Accommodation
Asia-Pacific Travel Accommodation Market