
 Hong Kong Hospitality Industry Market | 2026-2036
Hong Kong Hospitality Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Hospitality Industry Market Insights
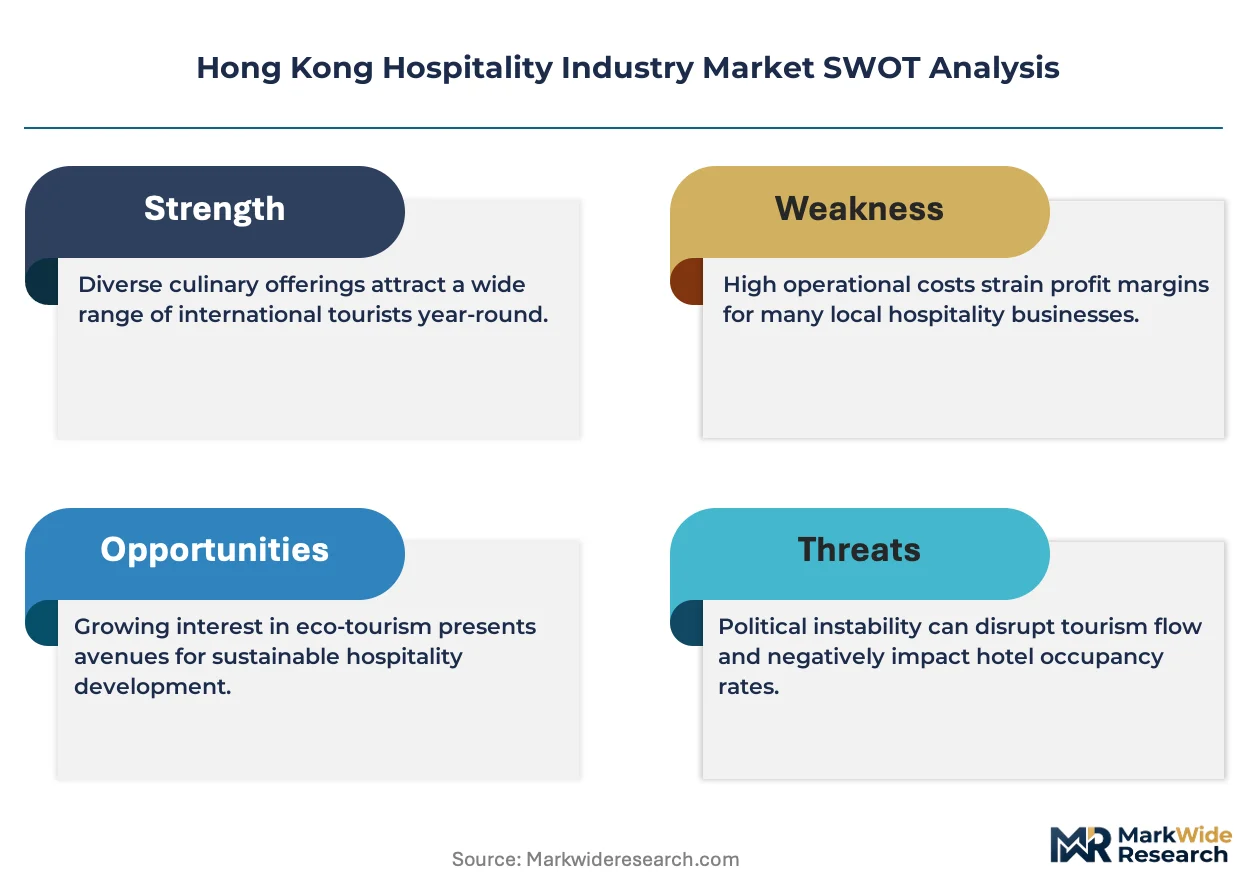
Food and beverage profit contribution within full-service hotels is narrowing as labor costs escalate and guest preferences shift toward experiential dining outside property walls. Marriott International leverages its global loyalty infrastructure to sustain repeat corporate bookings across its Hong Kong portfolio. Shangri-La Hotels & Resorts anchors its competitive stance through deep-rooted local banquet expertise and Chinese cuisine heritage. The Hongkong & Shanghai Hotels Ltd differentiates via heritage property restoration and Peninsula-branded retail integration.
The Hong Kong hospitality industry encompasses lodging, food service, and entertainment operations governed by strict fire safety, food hygiene, and building management ordinances, with properties typically achieving operational efficiency through centralized procurement and integrated property management systems. Hotels dominate revenue generation across the service type dimension, while the lodging offering captures the largest margin pool due to premium rate resilience in the luxury tier. Business travelers represent the highest-yield customer segment, though event attendees are expanding fastest as convention infrastructure matures.
The Food and Environmental Hygiene Department enforces licensing and sanitation protocols that shape restaurant and catering operational costs, while the Buildings Department's fire safety compliance mandates influence renovation cycles and capital expenditure timing for existing properties. The Hong Kong Tourism Board's quality tourism services accreditation creates tiered market access conditions that favor established operators with compliance resources. Stakeholders must monitor Greater Bay Area visa liberalization and cross-border infrastructure completion to anticipate demand migration patterns.
Market Dynamics
The Hong Kong Tourism Board's quality tourism services accreditation is compressing market access for smaller operators while concentrating revenue among established players with compliance infrastructure. Cross-border infrastructure completion in the Greater Bay Area is redrawing demand geography.
Growth Catalysts
- Greater Bay Area Integration:Visa liberalization and bridge-tunnel completion are extending Hong Kong's catchment radius into Guangdong province's manufacturing and technology corridors. Corporate event demand from Shenzhen and Dongguan enterprises is accelerating.
- Fire Safety Ordinance Compliance:The Buildings Department's mandatory sprinkler retrofitting timeline is forcing property upgrades that lift average daily rates across the luxury tier. Premium properties capture rate premiums from certified safety infrastructure.
- Wellness Infrastructure Investment:Integrated resort developments in Tung Chung are embedding medical tourism and longevity clinics within hospitality footprints. Lifestyle programming captures extended-stay revenue from affluent regional visitors.
Market Restraints
- Labor Cost Escalation:Food and Environmental Hygiene Department licensing requirements and minimum wage adjustments are compressing food and beverage margins. Full-service kitchen staffing consumes disproportionate operating expenditure.
- Land Supply Concentration:The government's controlled hotel site release schedule in Kai Tak and the New Territories limits supply growth to state-timed intervals. Developer competition for scarce commercial-zoned parcels inflates land premiums.
- Substitution by Short-Term Rentals:Unlicensed apartment conversions in Central and Tsim Sha Tsui divert price-sensitive leisure demand from formal hotel stock. Regulatory enforcement gaps perpetuate gray-market competition.
Strategic Opportunities
- New Territories Resort Corridors:Lantau Island's conservation zoning relaxations enable eco-tourism product development with lower land costs than urban core properties. Nature-integrated wellness programming targets weekend escape demand from Shenzhen.
- Heritage Asset Adaptive Reuse:The Antiquities and Monuments Office's revitalization incentives for Grade I and II historic buildings create differentiated boutique inventory. Tax depreciation advantages accelerate capital deployment into conservation hospitality.
- Digital Check-In Convergence:Biometric identity verification and mobile key technology are virtualizing front-desk operations. Labor reallocation from reception to guest experience roles improves service density per employee.
Industry Challenges
- Certified Chef Talent Scarcity:Chinese cuisine heritage requirements and Food and Environmental Hygiene Department food hygiene manager mandates create credential bottlenecks. Culinary school pipeline output lags banquet sector expansion.
- Legacy Property Management System Integration:Centralized procurement platforms and revenue management software require costly middleware to connect with 1990s-era building infrastructure. Staged capital deployment extends payback timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Hospitality Industry Market |
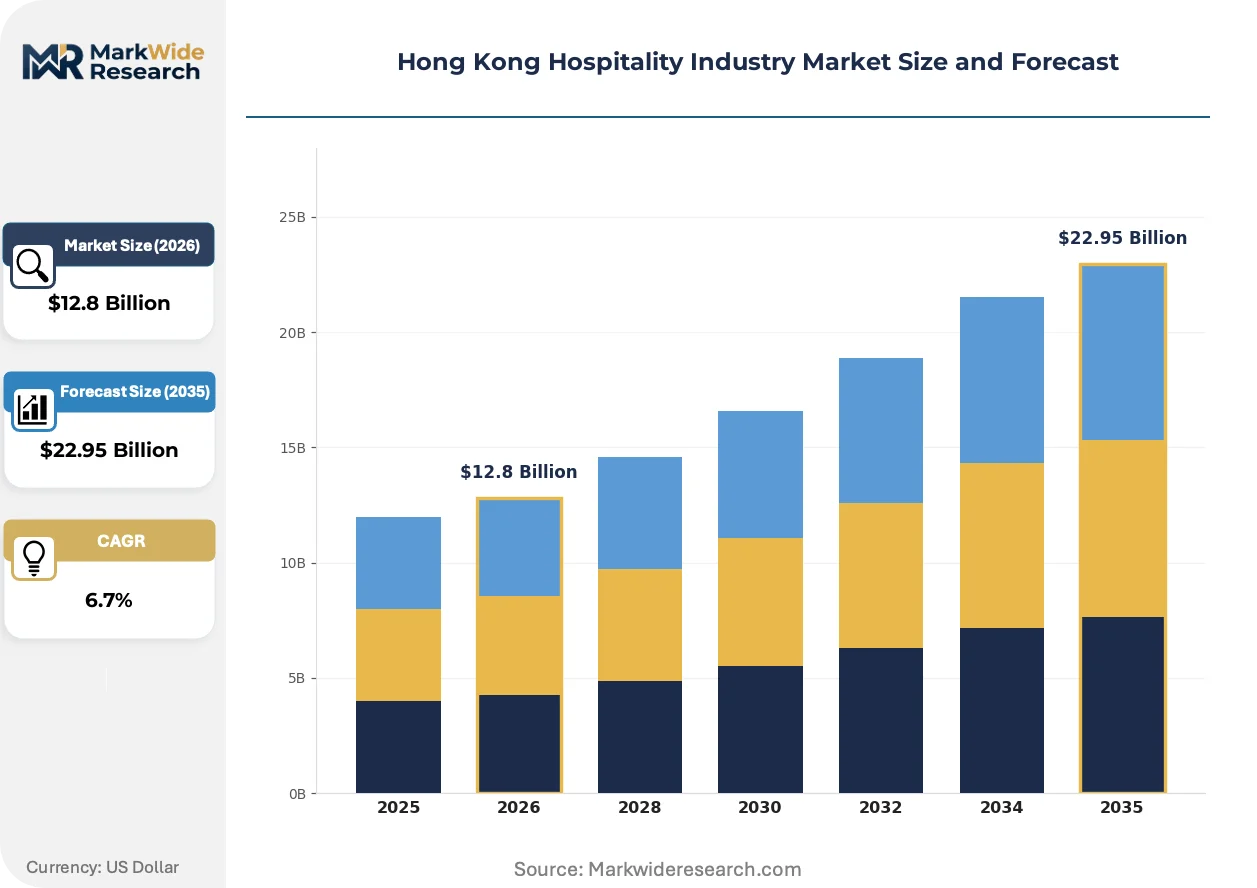
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotels, Restaurants, Cafés, Bars Customer Type: Business Travelers, Tourists, Locals, Event Attendees Offering: Lodging, Dining, Entertainment, Catering Delivery Model: On-Premise, Takeout, Delivery, Catering Services |
| Companies Covered | Marriott International, InterContinental Hotels Group, The Hongkong & Shanghai Hotels Ltd, Nina Hospitality, Four Seasons Hotels & Resorts, Shangri-La Hotels & Resorts, Hilton Worldwide, Regent Hong Kong, Mandarin Oriental International Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Hospitality Industry Market Trends and Innovations
Technology deployment is virtualizing traditional service touchpoints while regulatory pressure accelerates sustainability certification adoption. Demand patterns are fragmenting across generational and origin-market lines.
Contactless service orchestration platforms are virtualizing concierge, housekeeping request, and in-room dining workflows. Luxury tier properties are adopting these systems fastest to reallocate labor toward personalized experience curation rather than transactional processing. The structural consequence is compressing front-of-house headcount while expanding revenue per available room through upsell algorithm integration.
The Buildings Department's mandatory building energy code amendments are accelerating net-zero retrofitting timelines for properties over 20 years old. Compliance deadlines are forcing capital expenditure into HVAC replacement and smart building management systems. Heritage properties in Tsim Sha Tsui and Central face the steepest cost curves given preservation constraints on facade modifications.
Experiential dining preference is diverting food and beverage spend from hotel restaurants to independent chef-operated venues in Wong Chuk Hang and Tai Hang. Corporate travelers are booking external dining through concierge partnerships rather than property restaurants. This pattern concentrates most visibly among finance sector visitors from Singapore and London who prioritize discovery over convenience.
Hong Kong Hospitality Industry Market Segmentation
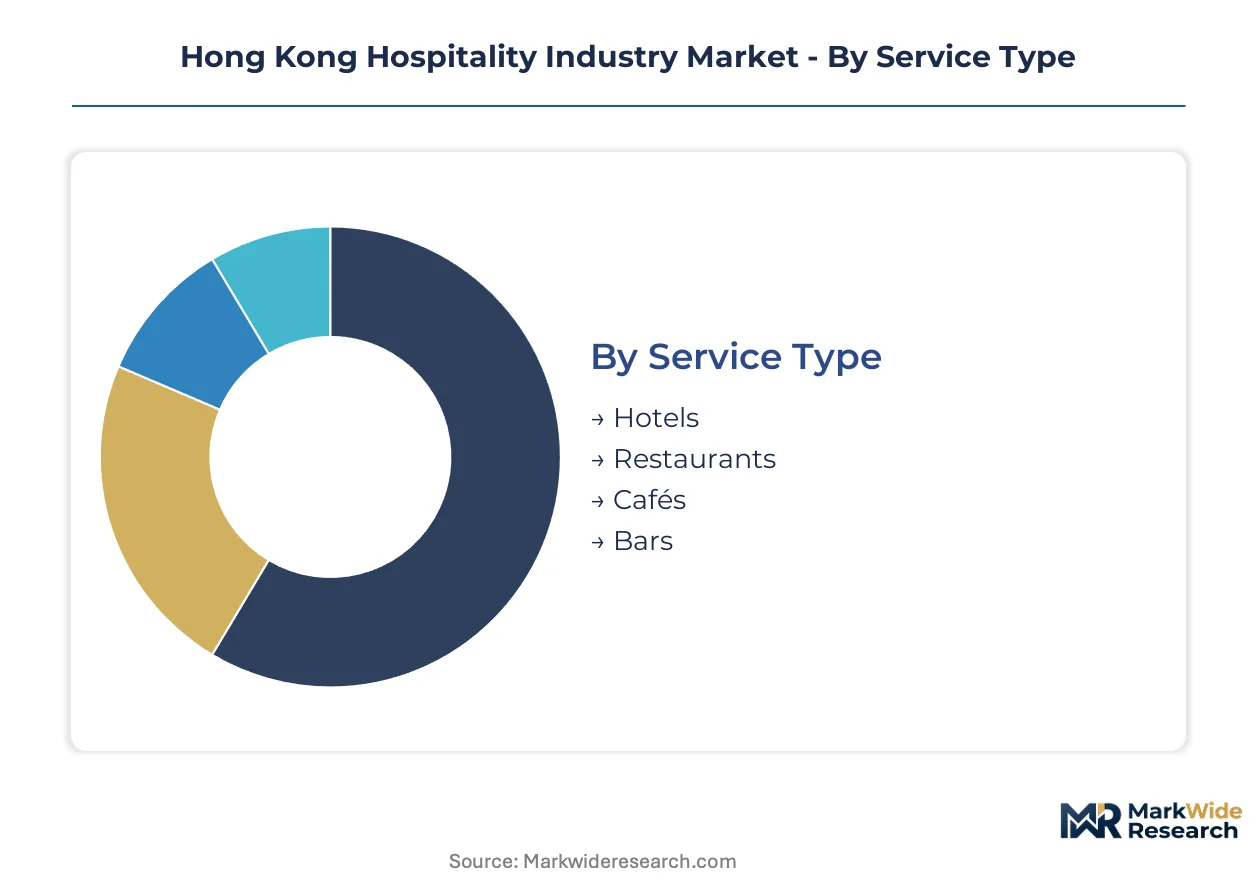
Segmentation in Hong Kong hospitality reveals how regulatory frameworks and infrastructure investments concentrate revenue across distinct operational models. Understanding these divisions exposes where compliance costs and premium rate resilience create competitive moats.
Service Type:
Mature hotel operations anchor revenue stability while emerging formats reshape margin structures through lower fixed-cost bases.
- Hotels:Full-service properties with integrated F&B and meeting infrastructure dominate capital deployment. The Greater Bay Area corporate corridor drives sustained demand for luxury tier inventory with certified fire safety infrastructure.
- Restaurants:Standalone dining venues capture experiential spend diverted from hotel F&B operations. Independent chef-operated venues in Wong Chuk Hang and Tai Hang attract finance sector visitors prioritizing discovery over convenience.
- Cafés:Daypart-focused operations with lower staffing intensity than full-service kitchens. Licensing requirements from the Food and Environmental Hygiene Department compress margins across smaller format footprints.
- Bars:Late-night licensed premises concentrated in Central and Tsim Sha Tsui entertainment zones. Substitution pressure from unlicensed apartment conversions diverts price-sensitive leisure demand.
Hotels handle the majority of throughput; restaurants are expanding most quickly on share as experiential dining preferences fragment traditional F&B revenue.
Customer Type:
Volume concentration clusters around high-frequency corporate demand while margin expansion tracks emerging event infrastructure.
- Business Travelers:Corporate accounts with negotiated rate structures and loyalty program integration. Marriott International's global infrastructure sustains repeat bookings across premium Hong Kong properties.
- Tourists:Leisure visitors from Greater Bay Area cities benefiting from visa liberalization and cross-border bridge-tunnel completion. Weekend escape demand from Shenzhen concentrates in New Territories resort corridors.
- Locals:Resident demand for banquet services and celebratory dining anchored in Chinese cuisine heritage. Shangri-La Hotels & Resorts leverages deep-rooted local expertise to capture this recurring revenue.
- Event Attendees:Convention and exhibition participants utilizing maturing infrastructure in Wan Chai and Kai Tak. This segment is gaining share fastest as integrated resort developments embed medical tourism and longevity clinics.
Business travelers handle the majority of throughput; event attendees are climbing the fastest on share as convention infrastructure matures.
Offering:
Margin pools concentrate in lodging operations while adjacent services face cost pressure from regulatory compliance.
- Lodging:Room revenue with premium rate resilience in luxury tier properties. The Buildings Department's mandatory sprinkler retrofitting timeline forces upgrades that lift average daily rates across certified inventory.
- Dining:Restaurant and in-room F&B operations experiencing margin compression from labor cost escalation. Full-service kitchen staffing consumes disproportionate operating expenditure relative to revenue contribution.
- Entertainment:Integrated lifestyle programming within resort developments targeting extended-stay regional visitors. Tung Chung wellness infrastructure captures affluent demand from longevity-focused travelers.
- Catering:Off-premise banquet and corporate event services requiring certified food hygiene manager credentials. Culinary school pipeline output lags sector expansion, creating talent bottlenecks.
Lodging handles the majority of throughput; entertainment is gaining share fastest as wellness programming extends guest duration.
Delivery Model:
Physical presence requirements dominate premium segments while virtualized formats capture efficiency gains.
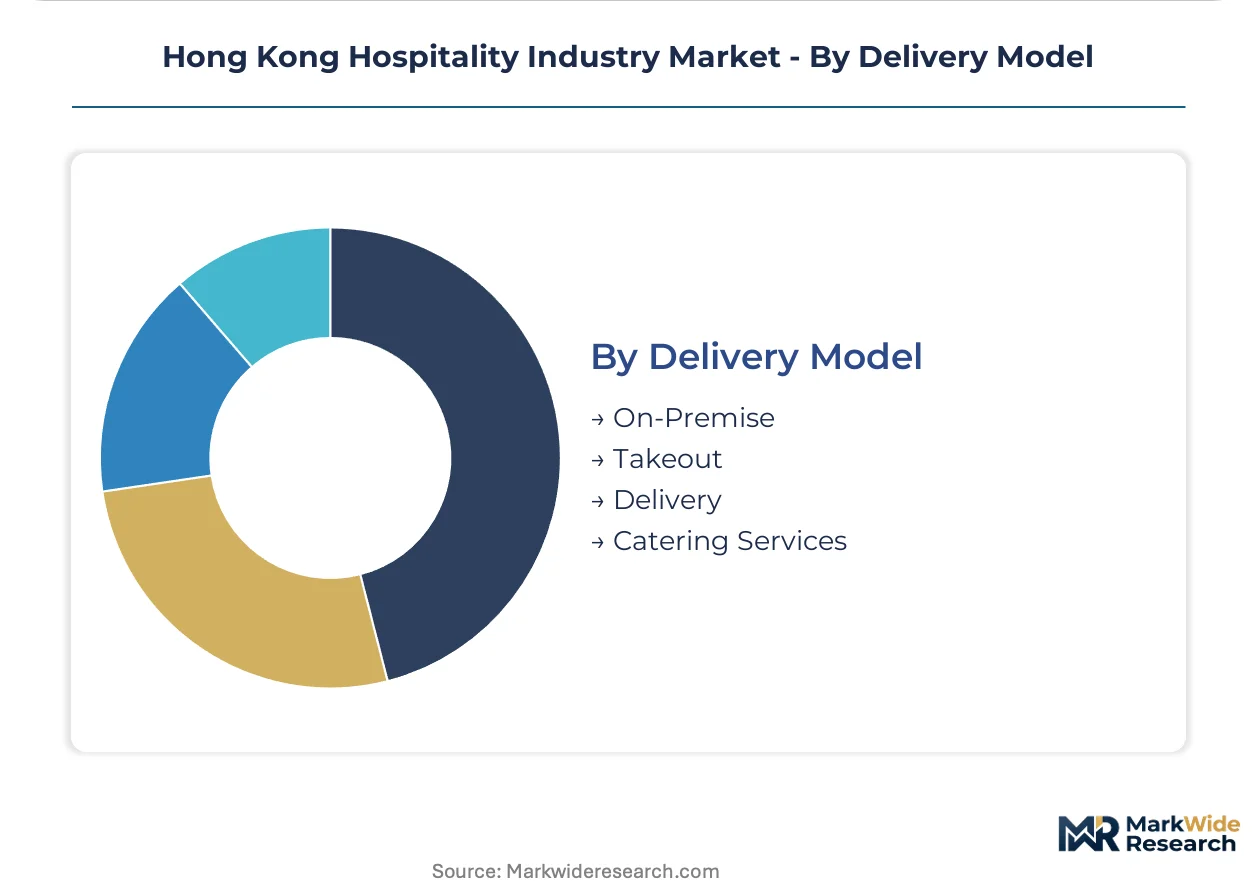
- On-Premise:Traditional hospitality consumption with service density per employee improving through labor reallocation. Biometric identity verification and mobile key technology virtualize front-desk operations.
- Takeout:Prepared food collection with lower real estate intensity than full-service dining. Food and Environmental Hygiene Department licensing shapes operational cost structures across takeaway-focused formats.
- Delivery:Third-party platform-mediated food service expanding addressable market without property footprint expansion. Gray-market apartment conversions in Central and Tsim Sha Tsui compete indirectly through informal delivery networks.
- Catering Services:Off-site event execution with concentrated demand from Greater Bay Area corporate clients. Shenzhen and Dongguan enterprises accelerate corporate event demand through cross-border infrastructure.
On-premise handles the majority of throughput; catering services are expanding most steeply as regional corporate demand crosses the border.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel site releases concentrate in Kai Tak and the New Territories, with developer competition inflating land premiums. The Greater Bay Area corridor redirects corporate event demand from Shenzhen and Dongguan. Regulatory compliance timelines reshape renovation cycles across urban core properties.
Hong Kong Island
Finance sector visitors from Singapore and London drive luxury tier occupancy in Central and Admiralty. The Buildings Department's fire safety ordinance mandates sprinkler retrofitting that lifts average daily rates for certified properties. Heritage properties in Tsim Sha Tsui face steep cost curves from preservation constraints on facade modifications.
Kowloon Peninsula
Independent chef-operated venues in Wong Chuk Hang and Tai Hang divert experiential dining spend from hotel F&B operations. The Food and Environmental Hygiene Department enforces licensing protocols that shape restaurant operational costs. Unlicensed apartment conversions in Tsim Sha Tsui perpetuate gray-market competition for price-sensitive leisure demand.
New Territories
Weekend escape demand from Shenzhen concentrates in Lantau Island eco-tourism corridors with lower land costs than urban core properties. Conservation zoning relaxations enable nature-integrated wellness programming. Integrated resort developments in Tung Chung embed medical tourism infrastructure to capture extended-stay regional visitors.
Greater Bay Area Cross-Border Corridor
Visa liberalization and bridge-tunnel completion extend Hong Kong's catchment radius into Guangdong manufacturing and technology corridors. Corporate event demand from Dongguan enterprises accelerates through cross-border infrastructure maturation. Catering services expand most steeply as regional corporate demand crosses the border for convention infrastructure in Wan Chai and Kai Tak.
Hong Kong Hospitality Industry Market Competitive Landscape
Global loyalty infrastructure operators and heritage-rooted local specialists split the market between scale-driven repeat booking systems and culturally-anchored banquet expertise. The competitive terrain concentrates around three archetypes: multinational flag-bearers with centralized procurement platforms, family-controlled heritage property custodians, and integrated resort developers embedding wellness programming. M&A activity targets boutique inventory in adaptive reuse projects, while portfolio diversification pushes operators into branded retail integration and longevity clinic partnerships.
Within the multinational tier, Marriott International and InterContinental Hotels Group exemplify loyalty-anchored corporate booking systems. The Hongkong & Shanghai Hotels Ltd occupies a position among heritage custodians with Peninsula-branded retail integration. Shangri-La Hotels & Resorts represents the local expertise archetype through deep-rooted Chinese cuisine heritage and banquet capabilities.
| Leading Market Players |
|---|
| Marriott International |
| InterContinental Hotels Group |
| The Hongkong & Shanghai Hotels Ltd |
| Nina Hospitality |
| Four Seasons Hotels & Resorts |
| Shangri-La Hotels & Resorts |
| Hilton Worldwide |
| Regent Hong Kong |
| Mandarin Oriental International Ltd |
| Others |
Pricing and Supply Chain Analysis
Mainland Chinese construction material suppliers and Guangdong-based FF&E manufacturers concentrate upstream procurement leverage, directing margin capture toward operators with centralized procurement platforms and multi-property scale. This supplier geography shapes how premium properties extract rate premiums while limited-service formats absorb cost volatility.
Pricing Analysis
Post-stay loyalty point redemption and extended-stay wellness programming drive lifetime value capture across the luxury tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by fire safety certification status and heritage property designation. Cost compression in full-service F&B operations is intensifying because labor cost escalation outpaces menu price elasticity. Leisure visitors from Greater Bay Area cities exhibit highest price sensitivity; finance sector corporate accounts demonstrate lowest sensitivity due to negotiated rate structures.
Supply Chain Analysis
Extended payment terms from Hong Kong-based general contractors and supply-chain finance facilities through regional banking networks structure working capital cycles. Geographic concentration draws from mainland China for construction materials, Italy and France for luxury FF&E, and Southeast Asia for soft goods and linens. Raw material dependencies rest on imported marble and stone, fire-rated steel, and specialty HVAC components. Single-source vulnerability concentrates in certified fire safety equipment where the Buildings Department mandates specific supplier accreditation. Distribution runs through centralized procurement platforms at multinational operators and project-specific sourcing for independent boutique developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified food hygiene manager credentials and Chinese cuisine heritage expertise constitute binding constraints that segment competitive viability. Operators without access to this talent pipeline face structural margin compression in banquet and catering operations.
For Market Incumbents: Pre-empt certified chef talent scarcity by anchoring exclusive pipeline agreements with Hong Kong culinary institutes before competitor lock-in. Consolidate fire safety certification advantages through accelerated sprinkler retrofitting timelines that lift average daily rates ahead of regulatory deadlines. Vertical integration into wellness programming and longevity clinic partnerships extends guest duration and diversifies revenue beyond room nights.
For New Entrants and Emerging Players: Pursue adaptive reuse opportunities in Grade I and II heritage buildings where Antiquities and Monuments Office incentives create differentiated inventory with tax depreciation advantages. Target New Territories eco-tourism corridors where conservation zoning relaxations enable lower land cost entry than urban core saturation. Lead with nature-integrated wellness programming to capture weekend escape demand from Shenzhen without competing on corporate rate negotiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated resort developments embedding medical tourism infrastructure. Long-term viability over the projection horizon favors operators with demonstrated compliance infrastructure and loyalty program scale. Acquisition target archetype: boutique heritage properties with conservation hospitality positioning and underutilized banquet capacity. The signal to watch is Greater Bay Area visa liberalization velocity as demand migration indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Asset Adaptive Reuse | Antiquities and Monuments Office tax incentives accelerate capital deployment into differentiated boutique inventory. |
| Wellness Infrastructure Integration | Tung Chung medical tourism clinics capture extended-stay revenue from affluent regional longevity-focused visitors. |
| Fire Safety Certification Acceleration | Buildings Department sprinkler mandates create rate premiums for certified properties ahead of compliance deadlines. |
| Digital Check-In Convergence | Biometric identity verification virtualizes front-desk operations and reallocates labor toward guest experience curation. |
| Cross-Border Catering Expansion | Shenzhen and Dongguan enterprise demand accelerates through Greater Bay Area bridge-tunnel infrastructure maturation. |
Research Methodology
Desk research of Hong Kong Tourism Board quality assurance filings, Buildings Department compliance databases, and Food and Environmental Hygiene Department licensing records preceded structured interviews with hotel general managers, procurement directors, culinary school administrators, and convention infrastructure planners. Secondary validation drew from statutory filings of listed hospitality operators, tourism board visitor statistics, and Greater Bay Area infrastructure development disclosures. Bottom-up property-level revenue modeling and top-down sectoral expenditure analysis were triangulated against cross-border demand flow estimates.
Assumptions around visa liberalization velocity, fire safety ordinance enforcement timelines, and labor cost escalation trajectories were held fixed across baseline scenarios while sensitivity testing varied Greater Bay Area integration pace and heritage revitalization incentive durability. Segmentation dimensions modeled encompass service type, customer origin market, offering category, and delivery model across the analysis window. CAGRs were derived from trend extrapolation of visitor arrival patterns and supply pipeline completion schedules, with inputs from cross-border corporate event demand surveys and wellness tourism expenditure benchmarks.
Sensitivities concentrate around regulatory enforcement intensity, infrastructure completion delays, and talent pipeline expansion rates. Forecasts reflect documented assumptions about policy continuity and demand migration patterns. Macroeconomic deviation, regulatory amendment, or technological disruption in identity verification or building management systems would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
In-Flight Catering Services Market
Accommodation
UAE Hospitality Market
Accommodation
Switzerland Hospitality Market
Accommodation
China Online Accommodation Market
Accommodation
Canada Hospitality Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
France Casino Tourism Market
Accommodation
Germany Student Accommodation Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Glamping Market
Accommodation
Romania Hospitality Market
Accommodation
Airport Lounges Market
Accommodation
Sweden Hospitality Market
Accommodation
Casino Hotel Market
Accommodation
Movie Theaters Market
Accommodation
Europe Camping and Caravanning Market