
 Japan Hospitality Market | 2026-2036
Japan Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hospitality Market Insights
Sustainable timber is repositioning traditional ryokan construction economics as engineered wood substitutes steel in seismic-resistant lodge frameworks. APA Hotels & Resorts leverages standardized modular room designs to compress development timelines across its 400-plus property network. Prince Hotels & Resorts anchors its competitiveness through integrated resort complexes pairing ski facilities with thermal spring operations in Niigata and Yamanashi prefectures. Fujita Kanko Inc. specializes in heritage property restoration, converting century-old estates into experiential lodging assets that command rate premiums.
Japan hospitality encompasses lodging, food service, event coordination, and guided tour operations delivered through physical facilities and digital platforms, with quality grading tied to fire safety certifications under the Fire Service Act and accessibility compliance with the Barrier-Free Act. Accommodation and food & beverage segments absorb the majority of industry revenue, while online travel agency bookings are displacing traditional travel agent channels as the dominant reservation pathway. Ryokans compete on cultural authenticity and onsen mineral composition, whereas business-oriented hotels dominate direct corporate contract volume.
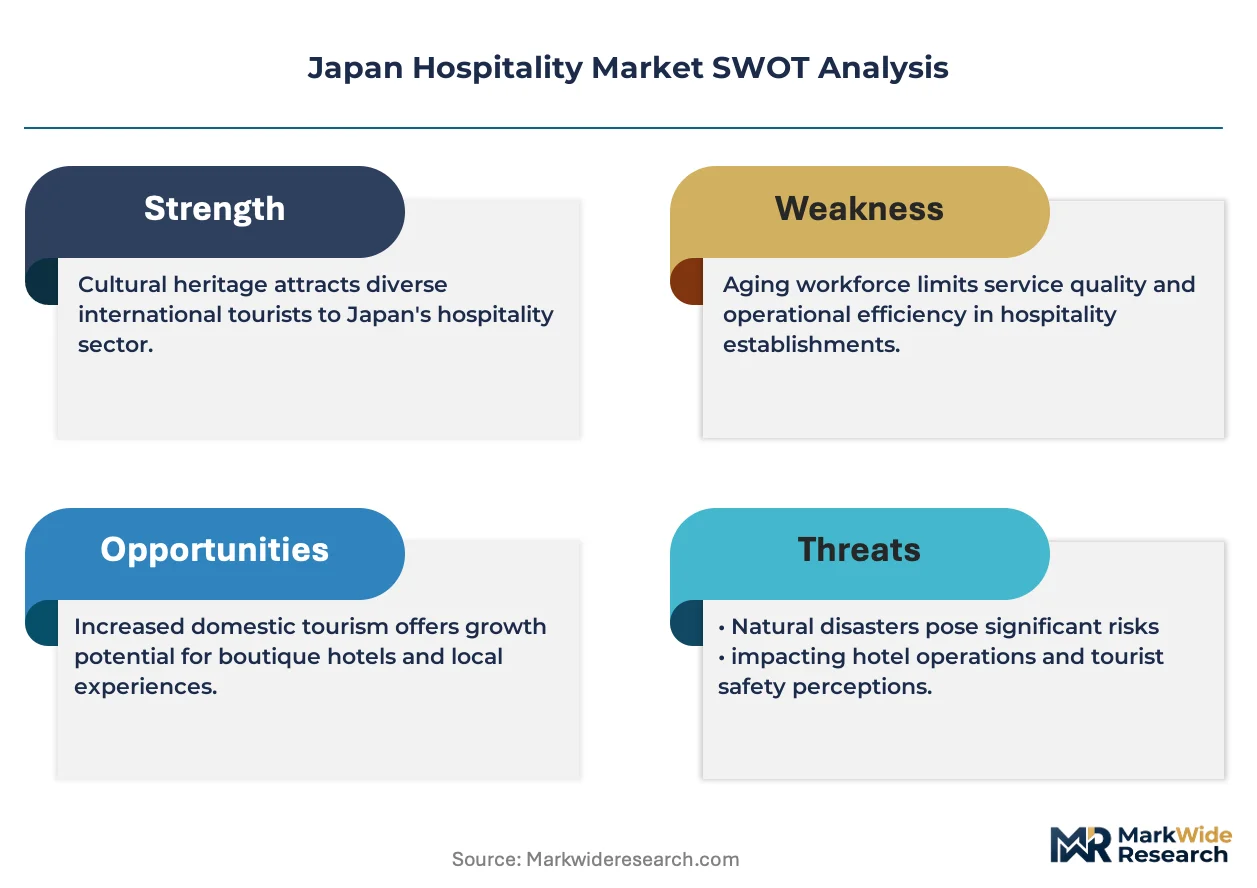
METI promotes tourism infrastructure investment through regional revitalization grants, while the Japan Tourism Agency enforces accommodation registration standards that filter unlicensed short-term rental supply. PMDA oversight of food sanitation within hotel restaurants and JIS accessibility standards for barrier-free design constrain operating cost structures. Stakeholders must weigh capital allocation between automated check-in technologies and workforce-dependent omotenashi service models as labor availability tightens.
Market Dynamics
The Japan Hospitality Market is experiencing structural pressure from inbound tourism recovery patterns that concentrate demand in Tokyo and Kyoto while leaving regional properties underutilized. METI's regional revitalization grants are redirecting capital toward secondary destinations, reshaping where developers commit new supply.
Growth Catalysts
- Amended Hotel Business Act:Streamlined minpaku registration protocols expand legal short-term rental inventory in urban cores. Property owners convert residential assets into licensed hospitality supply.
- Engineered wood substitution:Cross-laminated timber advances seismic-resistant ryokan construction while reducing steel dependency. Sustainable material sourcing attracts ESG-focused institutional capital.
- Inbound tourism concentration:Foreign visitor flows concentrate in Tokyo's 23 wards and Kyoto's historic districts, driving rate premiums and occupancy stability in these clusters.
Market Restraints
- Labor availability compression:Workforce-dependent omotenashi service models face recruitment constraints as Japan's working-age population contracts. Automation investments compete for capital allocation.
- Regional demand asymmetry:Tourism flows bypass secondary prefectures despite infrastructure investment, leaving Niigata and Yamanashi properties exposed to seasonal volatility.
- JIS accessibility compliance:Barrier-Free Act retrofit requirements impose structural modification costs on legacy ryokan properties with limited floor-area flexibility.
Strategic Opportunities
- Heritage estate conversion:Century-old rural properties command experiential rate premiums through Fujita Kanko-style restoration models. Authenticity positioning differentiates from standardized business hotels.
- Integrated resort complexes:Ski-thermal spring pairings in prefectural destinations capture extended-stay demand outside peak urban periods. Prince Hotels demonstrates operational feasibility.
- Online travel agency channel capture:Digital booking platforms displace traditional travel agent intermediaries, enabling direct rate management and guest data ownership.
Industry Challenges
- Fire Service Act certification timelines:Traditional wooden ryokan structures face extended approval processes for fire safety system upgrades, delaying revenue commencement.
- PMDA food sanitation oversight:Hotel restaurant operations require specialized compliance staffing that competes with standalone dining establishments for qualified personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hospitality Market |
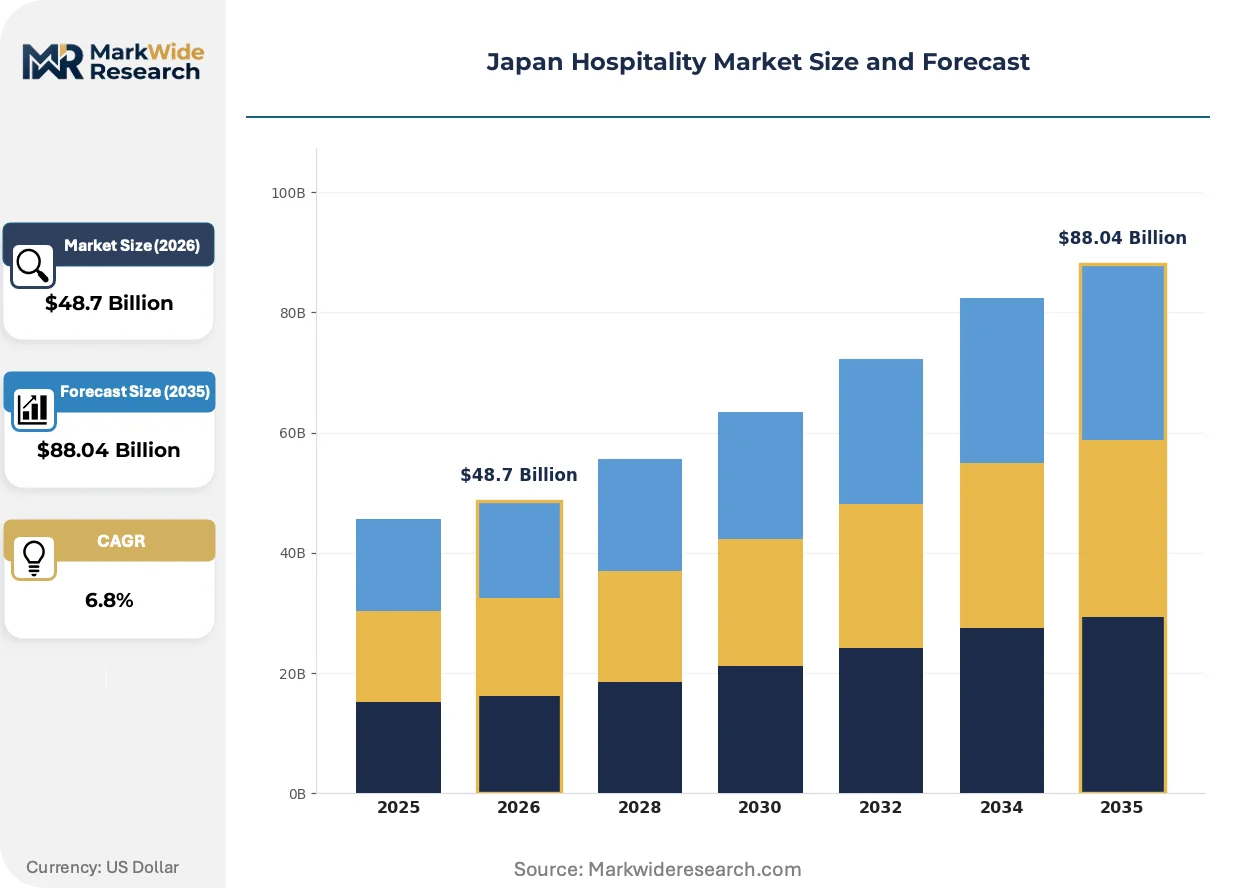
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Food & Beverage, Event Management, Tours Customer Type: Leisure Travelers, Business Travelers, Local Guests, International Tourists Facility Type: Hotels, Ryokans, Hostels, Resorts Booking Channel: Online Travel Agencies, Direct Bookings, Corporate Travel, Travel Agents |
| Companies Covered | APA Hotels & Resorts, Prince Hotels & Resorts, Tokyu Hotels & Resorts Co., Ltd., Marriott International Inc., Fujita Kanko Inc., JR Hotel Group, Hotel Okura Co., Ltd., Route Inn Japan Co., Ltd., Super Hotel Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hospitality Market Trends and Innovations
Digital platform integration is restructuring how Japanese hospitality inventory reaches buyers, compressing traditional intermediary roles while elevating data-centric property management. Technology deployment now determines competitive positioning across both urban and regional assets.
Automated check-in terminals paired with mobile key distribution is rewriting guest arrival workflows across APA Hotels' modular property network. Business-oriented properties deploy these systems to reduce front-desk staffing ratios without degrading service throughput. The technology compresses operating cost structures while preserving omotenashi touchpoints in high-interaction moments.
METI regional revitalization grant frameworks are channeling hospitality investment toward designated secondary destinations, altering where developers secure construction financing. Prefectural governments compete for allocation by bundling infrastructure commitments with property approvals. Rural ryokan conversions access subsidized capital unavailable to Tokyo ward developments.
Corporate travel procurement departments now mandate direct booking platform integration, bypassing traditional travel agency relationships that dominated Japanese hospitality distribution. Multinational firms operating in Tokyo consolidate preferred property lists through centralized expense management systems. This channel rotation elevates properties with API-ready reservation infrastructure while marginalizing legacy manual-booking establishments.
Japan Hospitality Market Segmentation
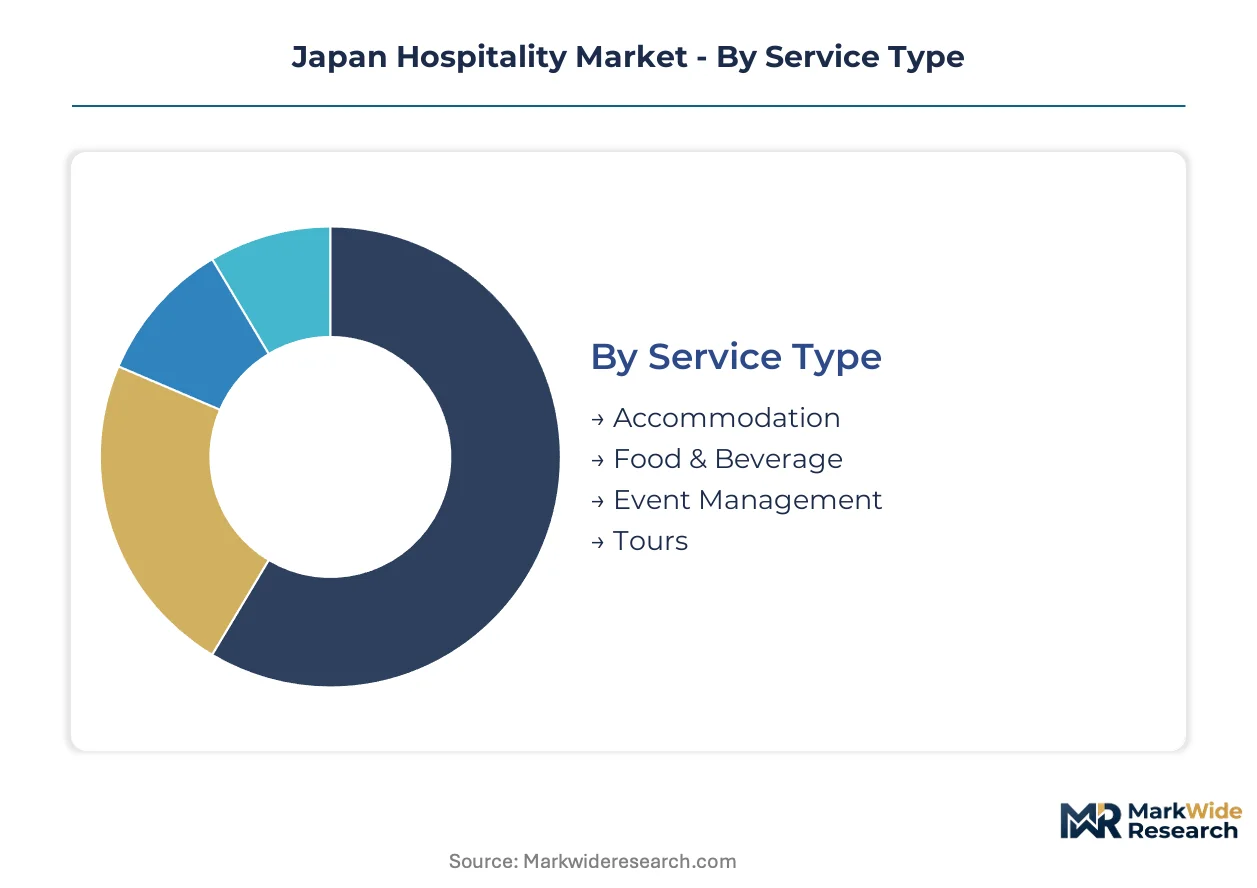
Segmentation reveals how Japan's hospitality value chain fragments across service delivery modes and customer acquisition pathways. Each dimension exposes distinct margin structures and capital intensity requirements that shape operator strategy.
Service Type:
Standalone service offerings compete against integrated bundles for guest wallet share and operational efficiency.
- Accommodation:Physical lodging assets generate revenue through room-night sales across properties ranging from capsule units to luxury suites. Tokyo's 23 wards and Kyoto's historic districts concentrate demand for premium positioning, though METI regional revitalization grants redirect some supply toward secondary prefectures.
- Food & Beverage:Restaurant operations within hospitality properties operate under PMDA food sanitation oversight with specialized compliance staffing requirements. Hotel-based dining competes with standalone establishments for qualified culinary personnel while capturing captive guest expenditure.
- Event Management:Conference and banquet services leverage existing facility infrastructure for incremental revenue generation.
- Tours:Guided experiences bundle transportation, interpretation, and site access into packaged offerings.
Volume placements concentrate in Accommodation; the faster expansion belongs to Food & Beverage as properties expand culinary programming to extend guest dwell time.
Customer Type:
Demand composition shifts with travel purpose, altering service specifications and rate tolerance across the guest base.
- Leisure Travelers:Vacation-motivated guests prioritize experiential programming and cultural authenticity, particularly in ryokan and resort settings. Inbound tourism recovery concentrates this segment in Tokyo and Kyoto, driving rate premiums during peak seasonal windows.
- Business Travelers:Corporate-contracted accommodation demands standardized service levels and proximity to commercial districts. Direct booking platform integration now dominates procurement relationships, displacing traditional travel agency intermediaries.
- Local Guests:Domestic leisure and staycation demand provides occupancy base during international travel troughs.
- International Tourists:Foreign visitor flows exhibit higher per-trip expenditure but greater sensitivity to currency fluctuation and visa policy.
Volume placements concentrate in Leisure Travelers; the faster expansion belongs to Business Travelers as corporate travel procurement consolidates through centralized expense management systems.
Facility Type:
Physical asset categories differentiate through capital structure, operational complexity, and regulatory compliance burden.
- Hotels:Purpose-built lodging facilities operate under the Hotel Business Act with standardized room configurations and fire safety certifications. APA Hotels demonstrates how modular construction compresses development timelines across multi-property networks.
- Ryokans:Traditional Japanese inns compete on cultural authenticity and onsen mineral composition, though JIS accessibility compliance imposes structural retrofit costs on legacy wooden properties. Fujita Kanko-style heritage estate conversions command experiential rate premiums.
- Hostels:Budget-oriented shared accommodation targets price-sensitive traveler segments with minimal service infrastructure.
- Resorts:Integrated complexes pair lodging with recreational amenities; Prince Hotels anchors competitiveness through ski-thermal spring combinations in Niigata and Yamanashi prefectures.
Volume placements concentrate in Hotels; the faster expansion belongs to Ryokans as engineered wood substitution advances seismic-resistant traditional construction.
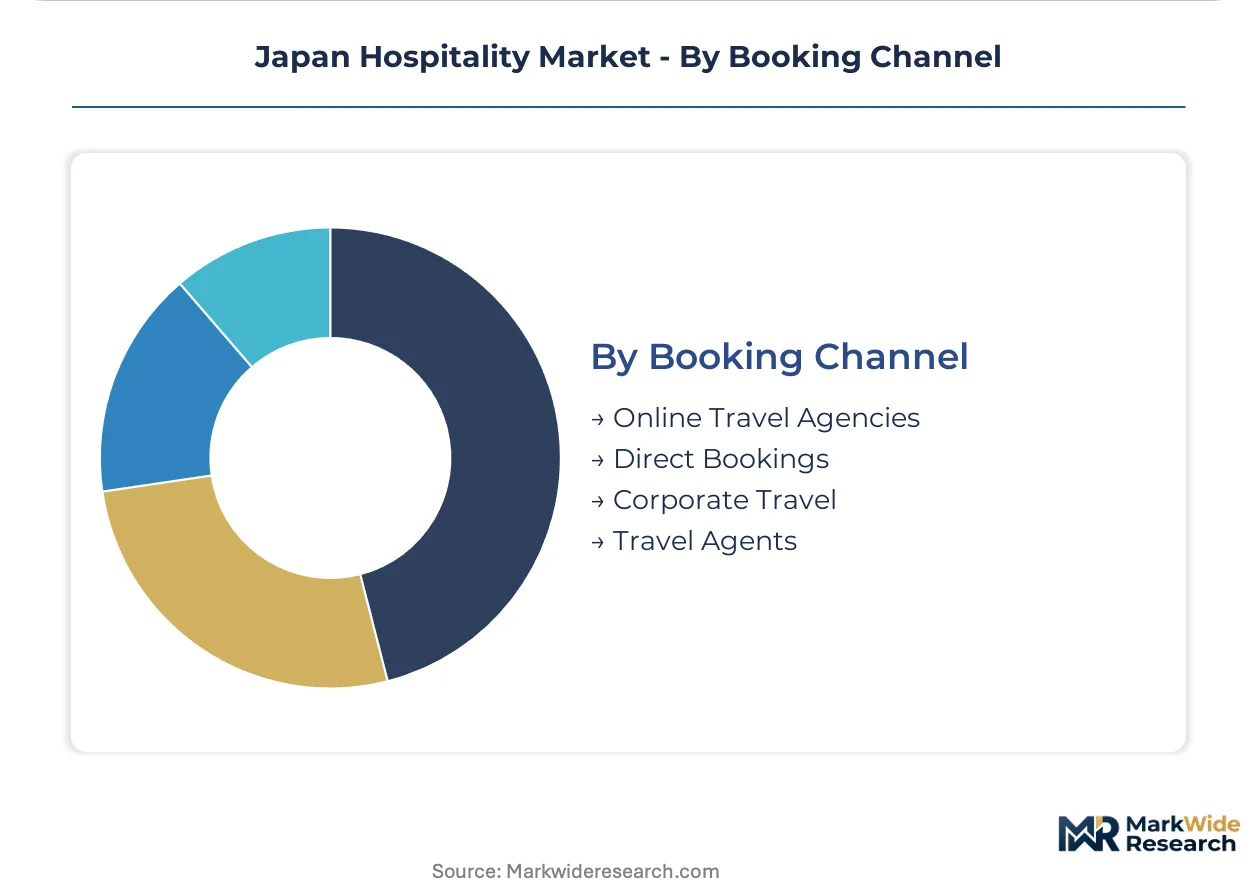
Booking Channel:
Distribution pathway selection determines guest data ownership, rate control, and commission expense structure.
- Online Travel Agencies:Digital platforms displace traditional intermediaries as the dominant reservation pathway, enabling direct rate management for properties with API-ready infrastructure. Corporate travel procurement departments now mandate platform integration for preferred property lists.
- Direct Bookings:Property-controlled reservations eliminate intermediary commissions and capture guest relationship data for repeat marketing.
- Corporate Travel:Negotiated contracts with multinational firms operating in Tokyo provide volume commitments and occupancy stability.
- Travel Agents:Legacy manual-booking establishments face marginalization as digital channels capture share.
Volume placements concentrate in Online Travel Agencies; the faster expansion belongs to Direct Bookings as properties invest in proprietary reservation infrastructure to reduce platform dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Tokyo's 23 wards and Kyoto's historic districts, leaving secondary prefectures exposed to seasonal volatility despite METI regional revitalization grant flows. Capital allocation diverges sharply between these urban cores and peripheral regions.
Kanto/Tokyo
Corporate travel procurement and inbound tourism flows drive occupancy premiums across Tokyo's 23 wards. The amended Hotel Business Act streamlines minpaku registration, expanding legal short-term rental inventory in dense urban cores. APA Hotels deploys standardized modular designs across its network to compress development timelines in this cluster.
Kansai/Osaka
Kyoto's historic districts command experiential rate premiums through cultural authenticity positioning. Fujita Kanko-style heritage estate conversions attract ESG-focused institutional capital to century-old rural properties. The Barrier-Free Act imposes structural retrofit costs on legacy wooden ryokan properties with limited floor-area flexibility.
Chubu/Nagoya
Business-oriented hotels dominate direct corporate contract volume in this manufacturing-heavy corridor. Prince Hotels anchors competitiveness through integrated resort complexes pairing ski facilities with thermal spring operations in adjacent Niigata prefecture. Automated check-in terminals reduce front-desk staffing ratios without degrading service throughput.
Hokkaido
Ski-thermal spring pairings capture extended-stay demand outside peak urban periods. Engineered wood substitution advances seismic-resistant traditional construction while reducing steel dependency. Regional properties face underutilization despite infrastructure investment as tourism flows bypass secondary prefectures.
Kyushu
Onsen mineral composition differentiates ryokan offerings in this thermal spring-rich region. PMDA food sanitation oversight requires specialized compliance staffing that competes with standalone dining establishments. Fire Service Act certification timelines delay revenue commencement for traditional wooden structures.
Japan Hospitality Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators balance automated technologies against workforce-dependent omotenashi service models. The market structures around three tiers: modular business hotel networks, heritage ryokan specialists, and integrated resort complexes. Strategic archetypes include standardization-driven scale players, experiential authenticity curators, and seasonal destination operators. M&A activity and digital platform integration constitute the principal competitive moves reshaping distribution control.
Within the modular standardization tier, APA Hotels & Resorts exemplifies compressed development timelines across multi-property networks. Prince Hotels & Resorts anchors the integrated resort archetype through ski-thermal spring combinations in prefectural destinations. Fujita Kanko Inc. occupies the heritage conversion specialist position, repurposing century-old estates into experiential lodging assets.
| Leading Market Players |
|---|
| APA Hotels & Resorts |
| Prince Hotels & Resorts |
| Tokyu Hotels & Resorts Co., Ltd. |
| Marriott International Inc. |
| Fujita Kanko Inc. |
| JR Hotel Group |
| Hotel Okura Co., Ltd. |
| Route Inn Japan Co., Ltd. |
| Super Hotel Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Corporate travel procurement departments in Tokyo's 23 wards concentrate purchasing power, anchoring contract-based pricing that rewards standardized service levels and API-ready reservation infrastructure over experiential premiums.
Pricing Analysis
Volume placements dominate in business-oriented hotels while margin capture concentrates in heritage ryokan conversions. Three-tier pricing structure across premium, standard, and economy levels separates luxury ryokan estates from modular business properties and capsule accommodations. Cost compression in economy lodging intensifies as APA Hotels-style standardization spreads, while experiential rate premiums shield restored heritage properties. International tourists exhibit highest price sensitivity to currency fluctuation; corporate-contracted volume shows lowest sensitivity due to negotiated annual rates.
Supply Chain Analysis
Single-source vulnerability sits with Japanese domestic timber suppliers for traditional ryokan construction, as cross-laminated timber adoption accelerates. Manufacturing draws from domestic engineered wood processors, Chinese steel alternatives, and South Korean automation equipment providers. Raw material inputs center on structural timber, seismic-resistant hardware, and smart-lock systems. Tariff exposure on imported construction materials threatens development timelines. Distribution runs through regional construction consortiums for rural projects and national modular suppliers for urban business hotels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around operators with capital to automate check-in workflows while preserving omotenashi service layers, forcing labor-dependent independents toward acquisition or exit.
For Market Incumbents: Deploy automated check-in terminals paired with mobile key distribution to compress front-desk staffing ratios without degrading service throughput. Acquire distressed heritage ryokan properties in Kyoto's historic districts before ESG-focused institutional capital prices restoration premiums beyond reach. METI regional revitalization grant access provides defensive moat against urban-only competitors. For New Entrants and Emerging Players: Secondary prefecture corporate travelers present underserved demand as business-oriented hotels in Niigata and Yamanashi face seasonal volatility. White-space exists in ski-thermal spring integrated complexes outside Prince Hotels' established footprint. Go-to-market through direct booking platform integration bypasses OTA commission structures that erode early-stage margins. For Investors and Strategic Acquirers: The window for entry favors modular construction specialists with standardized room design capabilities. Long-term viability hinges on properties that balance automation investment with workforce-dependent service differentiation. Acquisition targets should demonstrate either APA Hotels-style development velocity or Fujita Kanko-style experiential rate premiums. Watch inbound tourism recovery velocity in Tokyo's 23 wards as inflection signal for regional property valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Estate Conversion | Fujita Kanko-style restoration commands experiential rate premiums in Kyoto's historic districts. |
| Modular Construction Scale-Up | APA Hotels demonstrates how standardized designs compress development timelines across multi-property networks. |
| Direct Booking Platform Integration | API-ready reservation infrastructure captures guest data and eliminates OTA commission expenses. |
| Regional Grant Capture | METI revitalization funding channels subsidized capital toward secondary prefecture developments. |
| Automated Check-In Deployment | Terminal-based arrival workflows reduce front-desk staffing ratios in business-oriented properties. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hotel development executives, ryokan owner-operators, METI regional revitalization officers, corporate travel procurement managers, and OTA platform engineers. Japan Tourism Agency accommodation registration databases, JIS standards documentation, Fire Service Act certification records, and PMDA food sanitation filings provided regulatory validation. Bottom-up property-level revenue modeling triangulated against top-down inbound tourism expenditure flows.
Segmentation granularity modeled facility type at individual property level, service type at revenue-line level, and customer type at booking-channel level across the analysis window. CAGRs derived from time-series regression against inbound visitor arrival patterns and corporate travel procurement index movements. Forecast inputs incorporated METI grant allocation trajectories, cross-laminated timber adoption curves, and Barrier-Free Act retrofit compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to yen fluctuation, visa policy shifts, and seismic event frequency. Forecasts reflect documented assumptions about inbound tourism recovery velocity and labor availability compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Movie Theaters Market
Accommodation
US Student Accommodation Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Italy Online Accommodation Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
United States Online Accommodation Market
Accommodation
Asia-Pacific Student Accommodation Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Japan Online Accommodation Market
Accommodation
India Online Accommodation Market
Accommodation
France Online Accommodation Market
Accommodation
Youth Summer Camp Market
Accommodation
Hotel Market
Accommodation
Recreational and Vacation Camp Market