
 India Student Accommodation Market | 2026-2036
India Student Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
India Student Accommodation Market Insights
The UGC's framework for student welfare housing standards is consolidating quality benchmarks across India's purpose-built student housing sector. Stanza Living leverages technology-integrated property management to sustain premium positioning in tier-one cities. Zolo Stays anchors its portfolio around managed shared apartments with standardized amenity layers. OYO Life competes through flexible lease structures designed for transient academic calendars.
Student accommodation in India encompasses purpose-built housing, converted residential assets, and managed rental inventory serving enrolled learners across degree-granting institutions. These facilities typically integrate Wi-Fi infrastructure, security systems, meal services, and maintenance protocols within walkable proximity to campuses. Shared apartments and paying guest arrangements dominate current supply, though fully furnished managed properties capture expanding margin pools as parental preferences shift toward verified safety standards. Hostels retain volume leadership in tier-two and tier-three cities where institutional dormitory capacity falls short of enrollment growth.
BIS guidelines for electrical and fire safety in residential facilities intersect with state-level municipal corporation bylaws governing rental housing density and tenant verification. The CEA's energy efficiency norms are beginning to influence new construction specifications for student housing developments. Stakeholders must monitor how UGC accreditation linkages to housing quality reshape operator compliance costs and capital deployment timelines.
Market Dynamics
The UGC's student welfare housing standards are compressing supply timelines for unverified operators while concentrating demand around accredited facilities with demonstrable safety compliance.
Growth Catalysts
- Engineering enrollment surge:Technical institutes in Maharashtra and Karnataka are expanding intake capacity faster than institutional dormitory construction, pulling private operators into supply gaps.
- CEA energy efficiency norms:New construction specifications are mandating solar thermal integration and LED infrastructure, raising asset quality baselines across greenfield developments.
- Parental safety verification:Demand is concentrating around properties with biometric access, CCTV coverage, and meal hygiene certification as family decision-makers prioritize documented standards over price.
Market Restraints
- Land cost escalation in educational clusters:Mumbai and Hyderabad micro-markets near IIT and NIT campuses are seeing rental yield compression that challenges project viability.
- Municipal density bylaws:State-level corporation rules on maximum occupancy per square foot are capping revenue per unit in converted residential assets.
- Institutional dormitory substitution:Central universities with UGC-mandated hostel expansion plans are reclaiming price-sensitive demand segments from private operators.
Strategic Opportunities
- Telangana secondary cities:Warangal and Karimnagar host expanding state universities with minimal purpose-built supply and limited municipal enforcement capacity.
- Hybrid work-study housing:Co-living operators are layering co-working infrastructure into residential assets to capture postgraduate and research scholar segments.
- BIS fire safety certification:Early compliance with electrical and structural standards is creating differentiation moats as enforcement tightens across tier-one markets.
Industry Challenges
- Facility management talent scarcity:Standardized operations at scale require supervisors trained in hospitality protocols, a skillset concentrated in urban hospitality sectors.
- Legacy asset retrofit costs:Converting aging residential stock to meet UGC welfare benchmarks demands capital outlays for fire suppression and ventilation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Student Accommodation Market |
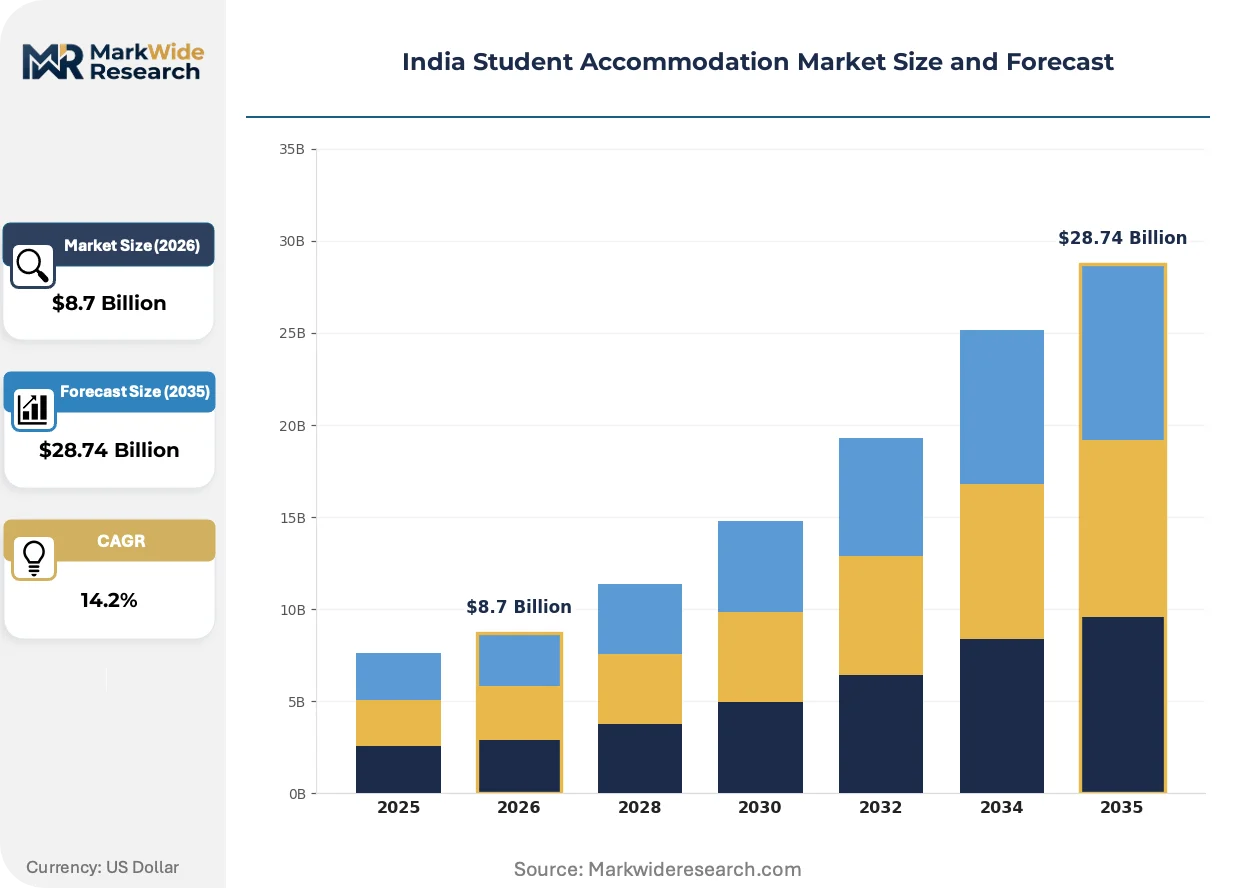
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hostels, PG (Paying Guests), Shared Apartments, Private Rentals Room Type: Single Occupancy, Double Occupancy, Triple Occupancy, Dormitory Service Type: Self-Catering, Fully Furnished, Managed, Unmanaged Pricing Model: Monthly Rent, Annual Subscription, Pay per Stay, Fixed Contract |
| Companies Covered | Stanza Living, Zolo Stays, OYO Life, NestAway, CoHo, Placio, Your-Space, StayAbode, Weroom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Student Accommodation Market Trends and Innovations
Technology integration and regulatory compliance are converging to reshape how student housing assets are designed, operated, and monetized across Indian educational clusters.
Smart access systems combining biometric entry, mobile key management, and real-time occupancy monitoring are rewriting security protocols in premium student housing. Tier-one city operators are deploying these systems across entire portfolios within eighteen-month rollout cycles. The technology is compressing insurance premiums and enabling dynamic pricing based on verified occupancy patterns.
The UGC framework for student welfare housing standards is mandating minimum room sizes, ventilation ratios, and grievance redressal mechanisms for all affiliated institutions. Operators seeking institutional partnerships must now document compliance through third-party audits before accreditation linkage. Karnataka and Telangana are seeing the fastest adaptation as state universities accelerate affiliation requirements.
Booking behavior is fragmenting from annual lease cycles toward semester-aligned tenures with embedded flexibility clauses. Tier-two city operators are responding with modular furnishing packages and storage solutions that accommodate mid-year departures. This pattern is most visible in Pune and Bengaluru where international student mobility creates demand volatility.
India Student Accommodation Market Segmentation
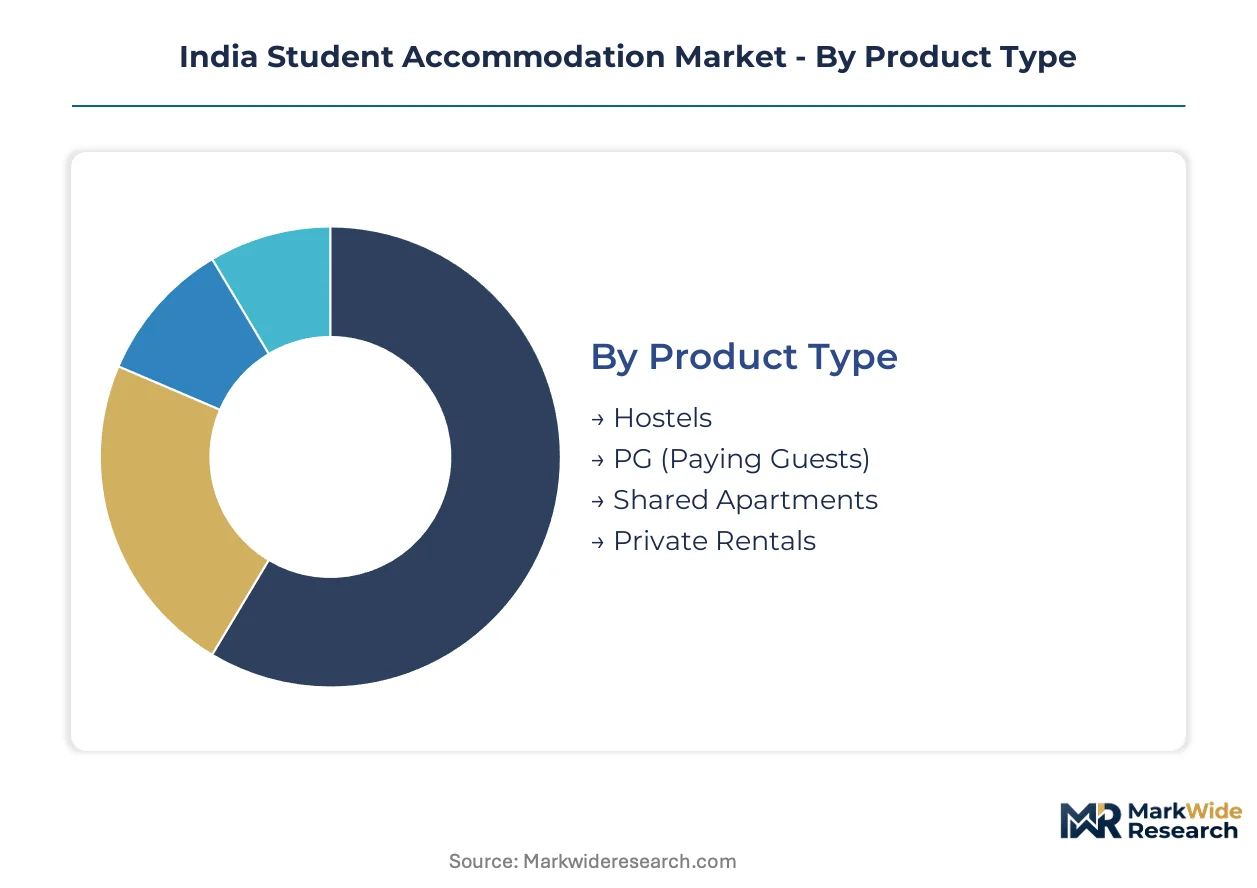
Student accommodation in India fragments across four distinct dimensions that shape capital deployment, operating margins, and compliance exposure for operators. Each segmentation layer captures different buyer priorities — from cost-conscious engineering students in shared apartments to safety-focused families selecting managed inventory near NIT campuses.
Product Type:
Operators target distinct risk-return profiles based on asset vintage and regulatory exposure in each product category.
- Hostels:Purpose-built dormitory blocks with institutional management dominate supply in tier-two and tier-three educational clusters. BIS fire safety compliance and UGC welfare benchmarks are compressing margins for unverified operators in Maharashtra and Karnataka as enforcement tightens.
- PG (Paying Guests):Converted residential stock with owner-operated management represents the largest volume pool across Indian student housing. Municipal density bylaws in Hyderabad and Bengaluru are capping revenue per square foot as occupancy limits tighten.
- Shared Apartments:Managed multi-bedroom units with standardized furnishing layers attract postgraduate segments seeking privacy at mid-tier price points. CEA energy efficiency norms are raising construction costs for new supply in Telangana.
- Private Rentals:Unfurnished independent units leased directly by students or families carry minimal service overlay and the lowest compliance burden. Demand concentrates among research scholars with established local networks in Pune and Chennai.
Hostels lead volumes today; shared apartments are gaining share fastest.
Room Type:
Pricing power and parental willingness-to-pay diverge sharply based on privacy levels and density configurations.
- Single Occupancy:Self-contained rooms with dedicated washroom access command premium positioning in tier-one markets. International student demand in Bengaluru and Mumbai sustains occupancy premiums above shared configurations.
- Double Occupancy:Paired beds with partitioned study zones balance cost and privacy for undergraduate engineering cohorts. This configuration captures the highest booking velocity during admission cycles in Karnataka.
- Triple Occupancy:High-density layouts with shared facilities dominate price-sensitive segments near state university campuses. UGC minimum room size mandates are threatening supply viability in legacy assets across Telangana.
- Dormitory:Open-plan sleeping halls with centralized facilities retain volume leadership in institutional hostel blocks. Cost advantages are eroding as safety verification requirements from BIS raise retrofit capital needs.
Double occupancy leads volumes today; single occupancy is climbing the fastest.
Service Type:
Margin structures and operational complexity scale with the intensity of service layers bundled into base rent.
- Managed:Professional operators delivering housekeeping, maintenance, security, and meal services through centralized protocols. Parental safety verification demand is concentrating bookings around biometric-access properties in Maharashtra.
- Fully Furnished:Turnkey inventory with appliances, bedding, and study furniture eliminates upfront capital outlay for students. This segment captures mid-year transfer demand from international enrollments in Pune.
- Self-Catering:Unfurnished or partially equipped units where tenants procure independent meal and utility arrangements. Cost advantages attract price-sensitive segments near tier-two state universities with limited purpose-built supply.
- Unmanaged:Direct landlord-tenant arrangements with no intermediary service layer and minimal compliance documentation. Regulatory pressure from UGC affiliation requirements is compressing this segment's addressable market.
Managed leads volumes today; fully furnished is expanding most quickly.
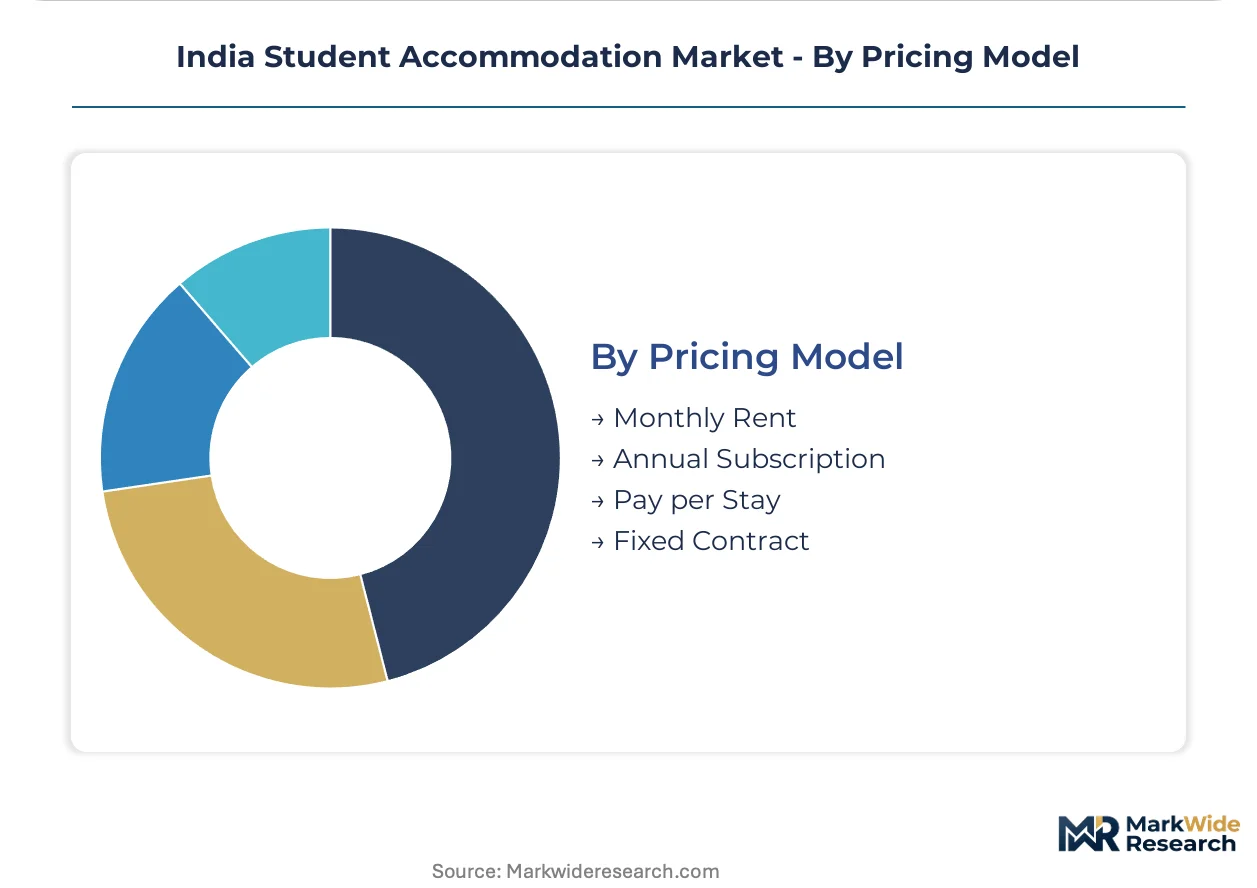
Pricing Model:
Cash flow predictability and customer acquisition costs vary with contract duration and payment structure flexibility.
- Monthly Rent:Recurring billing with standard security deposits dominates the core undergraduate market. This model matches parental budgeting cycles and reduces default risk in volatile admission environments.
- Annual Subscription:Upfront payment for full academic year occupancy with embedded service bundles. Operators in Bengaluru deploy this structure to lock in occupancy before competing supply enters the market.
- Fixed Contract:Semester-aligned tenures with penalty clauses for mid-term exit. International student mobility patterns in Mumbai sustain demand for this structured commitment mechanism.
- Pay per Stay:Short-duration bookings for examination periods, internships, or transient academic requirements. This model captures spillover demand from hotel and co-living segments in Hyderabad's research institute clusters.
Monthly rent leads volumes today; annual subscription is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's student accommodation sector traces its modern lineage to the post-liberalization expansion of private engineering colleges in the 1990s, when institutional dormitory capacity first fell behind enrollment growth. Maharashtra, Karnataka, and Telangana now concentrate the highest private operator density as educational clusters matured around IIT, NIT, and state university campuses.
Maharashtra
Mumbai and Pune host India's densest concentration of managed student housing inventory, driven by IIT Bombay, VJTI, and Symbiosis enrollment expansion. The state's Directorate of Technical Education mandates fire safety audits for all hostels affiliated with AICTE-approved institutions. Thane and Navi Mumbai micro-markets near engineering colleges are seeing purpose-built supply absorption rates above legacy PG stock.
Karnataka
Bengaluru's position as India's startup hub attracts postgraduate and research scholar segments seeking hybrid work-study housing configurations. The Karnataka State Higher Education Council has accelerated UGC welfare standard adoption across Bangalore University-affiliated colleges. Whitefield and Electronic City corridors host the fastest-growing managed apartment supply as international student mobility recovers.
Telangana
Hyderabad's research institute corridor around IIIT, ISB, and University of Hyderabad sustains premium pricing for single-occupancy configurations. The Telangana State Council of Higher Education is linking college affiliation renewals to documented hostel compliance with BIS electrical safety norms. Warangal and Karimnagar secondary cities present supply gaps as state universities expand without matching dormitory investment.
Tamil Nadu
Chennai's Anna University zone and Coimbatore's engineering college belt anchor southern demand with high parental safety verification requirements. The Tamil Nadu Directorate of Collegiate Education enforces strict municipal occupancy density limits in converted residential assets. Sriperumbudur and Oragadam industrial corridors are seeing spillover demand from apprenticeship-linked technical training programs.
Delhi-NCR
The National Capital Region's fragmented supply mixes institutional hostels, unverified PG stock, and emerging managed inventory near Noida and Greater Noida universities. Delhi University's UGC-mandated hostel expansion is reclaiming price-sensitive demand from private operators in North Campus zones. Gurugram's proximity to corporate internship destinations attracts postgraduate segments seeking co-living configurations.
India Student Accommodation Market Competitive Landscape
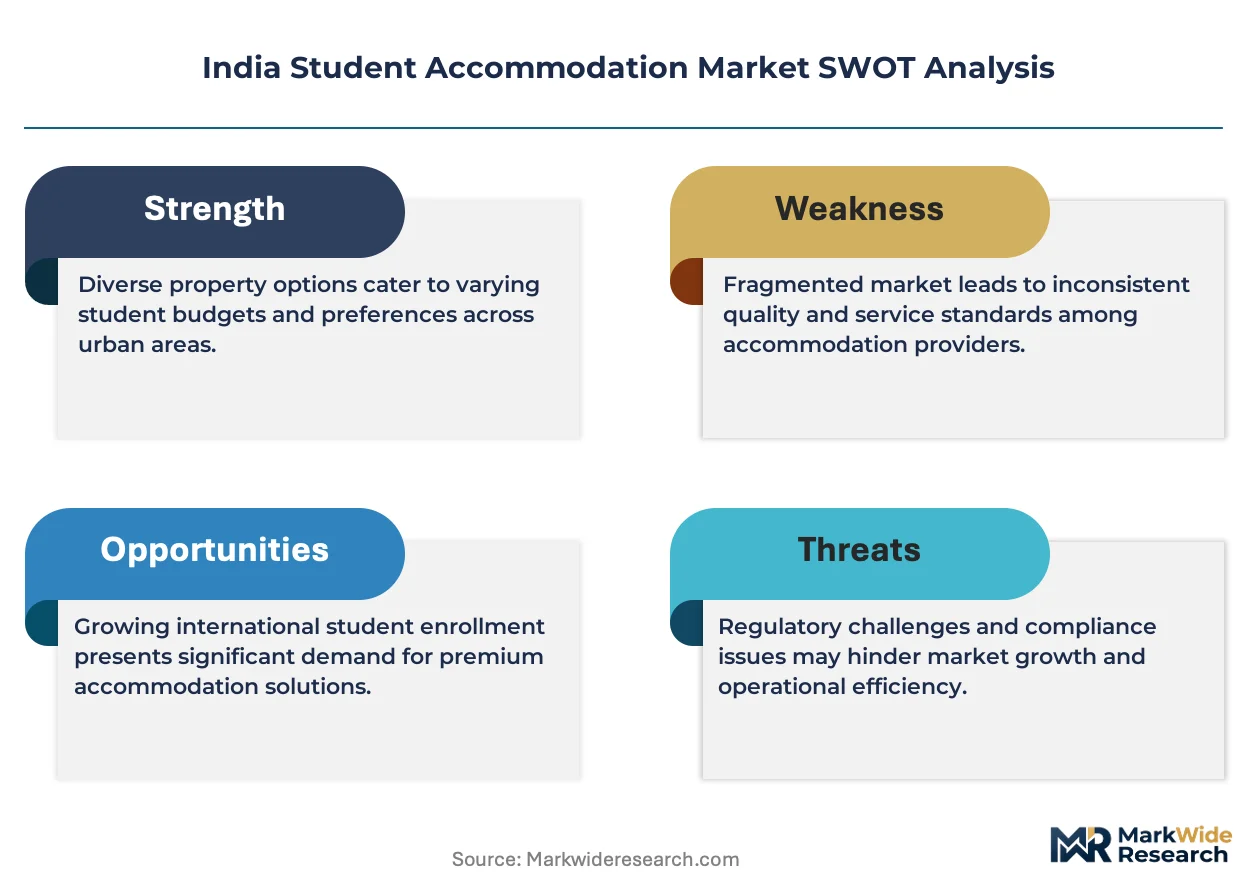
Capital-heavy asset owners compete with asset-light platform operators across India's student accommodation sector. The market structure fragments between institutional-scale developers holding long leaseholds and technology-enabled aggregators managing distributed inventory. Three archetypes dominate: full-stack operators controlling design-build-operate cycles; managed marketplace platforms standardizing service layers across third-party assets; and legacy PG owners retrofitting compliance into converted residential stock. Consolidation pressure is accelerating through BIS fire safety enforcement and UGC accreditation linkages that favor documented operators.
Within the full-stack operator tier, Stanza Living and Zolo Stays exemplify capital-intensive models with proprietary technology platforms and centralized facility management protocols. OYO Life occupies a position bridging managed marketplace and flexible lease specialist, leveraging parent-company distribution infrastructure for transient academic demand. These three anchors represent divergent responses to the same regulatory compression: documented safety compliance as competitive moat.
| Leading Market Players |
|---|
| Stanza Living |
| Zolo Stays |
| OYO Life |
| NestAway |
| CoHo |
| Placio |
| Your-Space |
| StayAbode |
| Weroom |
| Others |
Pricing and Supply Chain Analysis
Biometric access system deployment across tier-one operator portfolios is compressing insurance premiums while simultaneously raising capital intensity barriers for new supply entrants. This technology transition concentrates pricing power among documented operators with UGC welfare compliance, forcing unverified PG owners toward either retrofit investment or margin erosion in Maharashtra and Karnataka clusters.
Pricing Analysis
Monthly rent structures with semester-aligned flexibility clauses dominate undergraduate demand in Hyderabad and Bengaluru, while annual subscription models lock in occupancy ahead of competing supply. Price differentiation rests on BIS fire safety certification status and biometric security documentation, with parental willingness-to-pay widening between verified and unverified properties. Cost compression in converted residential assets is intensifying because municipal density bylaws cap revenue per square foot. Engineering students near state universities exhibit highest price sensitivity; international postgraduate cohorts in Mumbai sustain lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with China-manufactured smart access hardware and LED infrastructure components that tier-one operators deploy across eighteen-month rollout cycles. Construction inputs draw from domestic cement and steel suppliers in Telangana, while fire suppression systems import from Germany and South Korea. Tariff exposure on electronic security components threatens margin stability for technology-integrated properties. Distribution runs through regional facility management networks that centralize procurement of standardized furnishing packages across operator portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in India's student accommodation sector rest on UGC welfare compliance creating documented-operator premiums while unverified PG stock faces regulatory compression costs.
For Market Incumbents: Deepen backward integration into in-house facility management training protocols to address hospitality-talent scarcity compressing operational scale. Acquire distressed converted residential assets in Thane and Navi Mumbai corridors before BIS enforcement raises retrofit capital requirements for competitors. Institutional dormitory substitution by central universities with UGC-mandated expansion plans threatens price-sensitive demand segments. For New Entrants and Emerging Players: Enter via Warangal and Karimnagar secondary cities where Telangana state university expansion outpaces purpose-built supply and municipal enforcement capacity remains limited. Target hybrid work-study housing configurations for postgraduate research scholars in Bengaluru's startup corridor. Co-working infrastructure layering into residential assets offers differentiated go-to-market positioning against legacy PG operators. For Investors and Strategic Acquirers: Valuations sit cheapest among unverified PG owners facing UGC accreditation linkage deadlines in Karnataka and Telangana. Long-term viability across the analysis window favors operators with documented BIS compliance and proprietary technology platforms controlling design-build-operate cycles. Monitor CEA energy efficiency norm enforcement tightening as the inflection signal for greenfield development cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| UGC Welfare Compliance Certification | Third-party audit documentation unlocks institutional partnership revenue streams ahead of affiliation deadline enforcement. |
| Biometric Security System Deployment | Real-time occupancy monitoring enables dynamic pricing compression of insurance premiums across Maharashtra portfolios. |
| Secondary City Geographic Expansion | Warangal and Karimnagar supply gaps capture state university enrollment growth with limited municipal density enforcement. |
| Hybrid Work-Study Infrastructure Layering | Co-working amenity integration targets postgraduate segments in Bengaluru with premium positioning above standard PG stock. |
| Backward Integration into Facility Management | In-house hospitality training protocols address supervisor talent scarcity constraining operational scale across tier-one markets. |
Research Methodology
Multiple input streams — primary interviews with student housing operators, state university hostel administrators, and municipal corporation licensing officials, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Facility management executives at managed accommodation platforms, BIS certification auditors, and Telangana State Council of Higher Education officials provided operational and regulatory perspective. Secondary sources encompassed UGC hostel welfare framework documents, CEA energy efficiency norm filings, municipal corporation bylaws from Hyderabad and Bengaluru, and AICTE-affiliated institution enrollment databases.
Data-stream reconciliation across product type, room configuration, service intensity, and pricing model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from enrollment trajectory modeling against purpose-built supply pipeline tracking throughout the forecast period. BIS fire safety compliance timelines, UGC accreditation linkage deadlines, and international student mobility recovery patterns constituted industry-specific forecast inputs.
Inputs from state higher education councils and municipal licensing databases were available through the study window; gaps in informal PG operator financial disclosures introduce uncertainty bands around market sizing. Forecasts reflect documented assumptions regarding enforcement velocity of welfare housing standards. Regulatory implementation delays, institutional dormitory construction acceleration, or sharp corrections in land values near IIT and NIT campuses could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Switzerland Hospitality Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Italy Online Accommodation Market
Accommodation
Casino Hotel Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Romania Hospitality Market
Accommodation
Japan Hospitality Market
Accommodation
France Hospitality Market
Accommodation
UK Student Accommodation Market
Accommodation
Airport Lounges Market
Accommodation
Global Travel Accommodation Market
Accommodation
Capsule Hotels Market
Accommodation
India Online Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Recreational and Vacation Camp Market