
 United States Online Accommodation Market | 2026-2036
United States Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Online Accommodation Market Analytics
California's SB 761 is broadening the cost-of-entry calculus for hosts operating short-term rental platforms. Airbnb navigates this patchwork by investing in automated tax-remittance tools across municipal jurisdictions. Marriott leverages its Bonvoy loyalty ecosystem to sustain direct booking volumes that bypass third-party commission structures. Booking.com competes through aggressive geographic coverage of secondary US cities where inventory fragmentation remains high.
United States online accommodation denotes digitally intermediated lodging reservations encompassing hotels, vacation rentals, hostels, and bed-and-breakfast properties, typically executed through web-based platforms or mobile applications with real-time availability verification and dynamic rate optimization. The primary commercial purpose centers on reducing search friction between dispersed lodging suppliers and segmented traveler demand while capturing transaction economics through commissions or subscription fees. Hotel booking commands the largest revenue pool within service type segmentation, though vacation rentals extract superior per-night margins in coastal leisure markets. Leisure travelers generate the highest absolute transaction volume among customer types, while business travelers deliver more predictable weekday demand patterns that stabilize revenue management algorithms.
FCC oversight of digital platform transparency intersects with state-level zoning enforcement and local occupancy taxation regimes to create a multilayered compliance architecture. The Department of Labor's evolving contractor-classification scrutiny further shapes platform operating models for host-managed properties. Stakeholders must monitor whether emerging municipal caps on rental nights per property trigger inventory migration toward longer-term furnished housing alternatives.
Market Dynamics
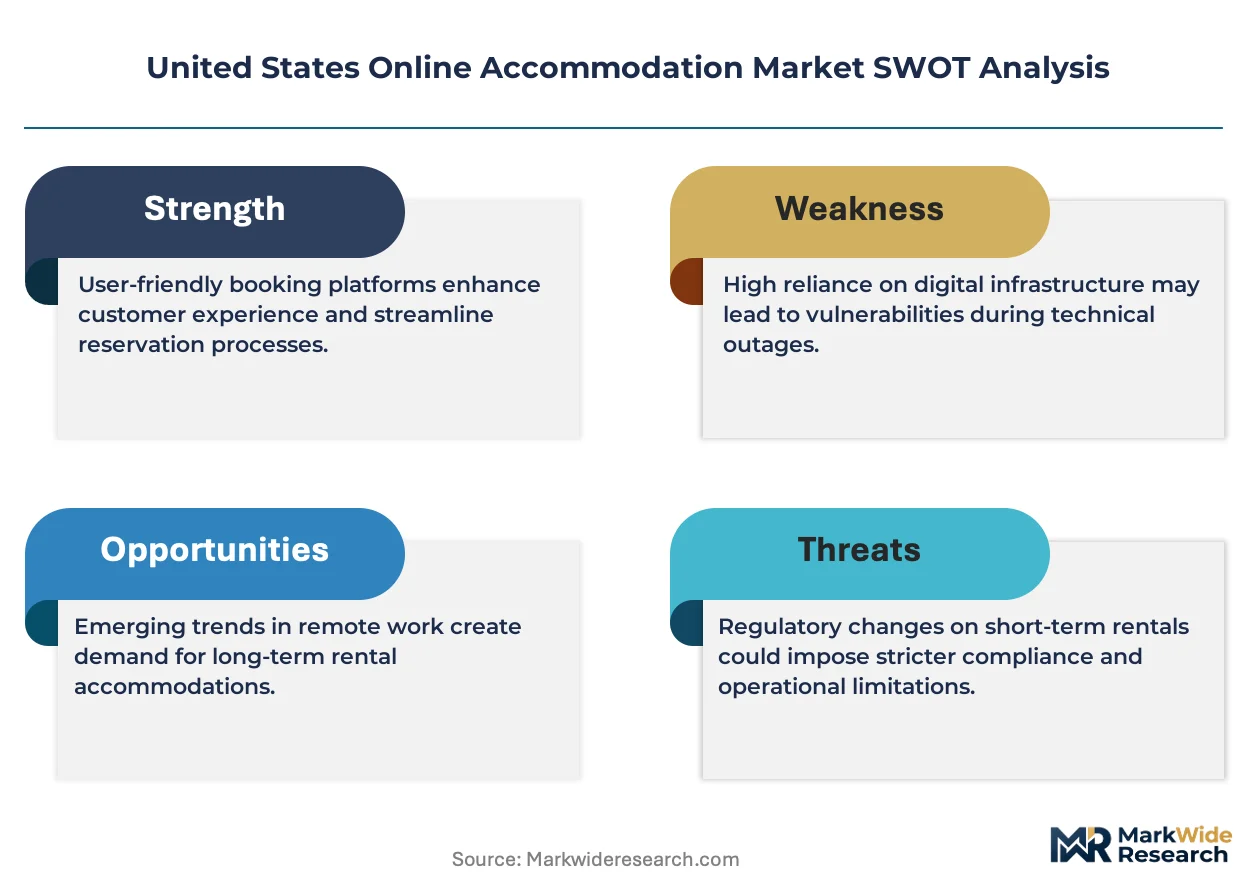
Platform commission compression is reshaping host economics across the United States online accommodation sector. Automated pricing algorithms now determine nightly rates in real time, while state-level short-term rental ordinances fragment compliance requirements.
Growth Catalysts
- Corporate travel policy digitization:Business travelers drive weekday inventory absorption. Centralized booking platforms integrate expense management systems, reducing friction for road-warrior segments.
- SB 761 (California):Mandatory registration databases for short-term rentals professionalize host operations. Legitimate operators gain competitive separation from non-compliant inventory.
- Dynamic rate optimization:Machine learning models adjust pricing by micro-segment, capturing revenue previously lost to static seasonal rates.
Market Restraints
- Municipal night caps:Cities including Miami Beach and Nashville limit annual rental days per property. Hosts face revenue ceiling constraints that discourage full-time platform commitment.
- Occupancy tax fragmentation:Over 10,000 US jurisdictions impose varying lodging tax regimes. Platforms absorb compliance overhead that erodes per-transaction margins.
- Furnished apartment substitution:Corporate housing providers capture extended-stay demand that short-term rentals previously served, compressing average length of stay.
Strategic Opportunities
- Secondary city inventory aggregation:Markets like Austin and Denver exhibit supply fragmentation that rewards first-mover platform density. Booking engines capture host relationships before competitors establish presence.
- Loyalty program convergence:Hotel chains integrate vacation rental inventory into points ecosystems. Travelers redeem accumulated status across accommodation types, reducing platform switching.
- Automated tax remittance infrastructure:Real-time calculation and remittance tools transform compliance from cost center to competitive differentiator for multi-jurisdiction operators.
Industry Challenges
- Host onboarding friction:Property verification, photography standards, and insurance requirements create multi-day activation timelines that delay revenue generation.
- Review system gaming:Coordinated fake review networks erode trust signals. Platforms invest in behavioral detection algorithms that increase operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Online Accommodation Market |
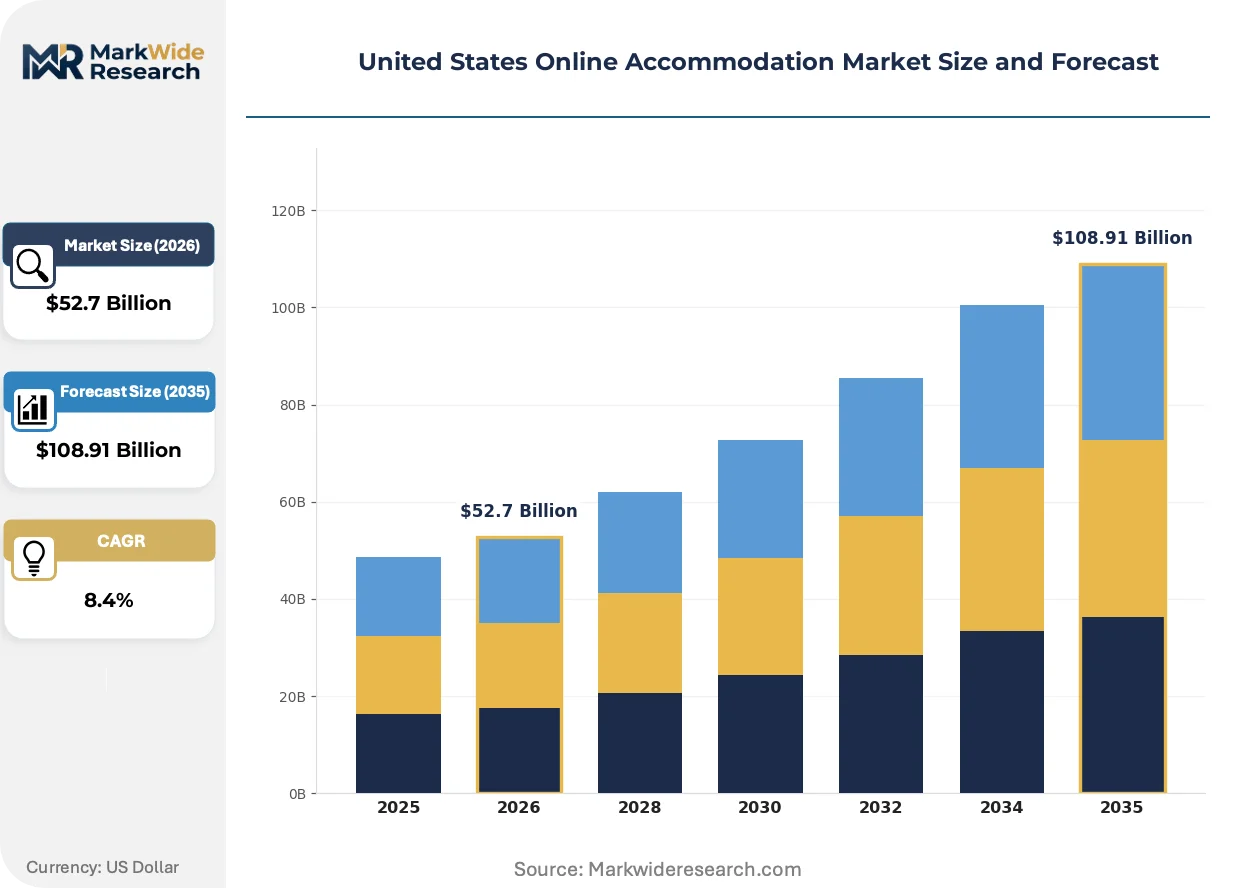
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotel Booking, Vacation Rentals, Hostels, Bed & Breakfasts Customer Type: Business Travelers, Leisure Travelers, Group Travelers, Solo Travelers Distribution Channel: Online Travel Agencies, Direct Booking, Mobile Apps, Metasearch Engines Price Tier: Luxury, Mid-Range, Budget, Affordable |
| Companies Covered | Marriott, Priceline, Expedia, Landing, HotelsCombined, Airbnb, Hilton, Blueground, Booking.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Online Accommodation Market Evolving Landscape
Artificial intelligence is restructuring how accommodation inventory matches traveler intent. Predictive models now anticipate cancellation probability, enabling overbooking strategies that maximize yield.
Machine learning-based revenue management systems process competitor pricing, local event calendars, and flight search data to optimize nightly rates. Mid-scale hotel operators adopt these tools fastest, narrowing the technology gap with major chains. Dynamic pricing is expanding into vacation rental segments previously dependent on host intuition.
FCC transparency mandates for digital platforms intersect with state-level short-term rental enforcement. Disclosure requirements for algorithmic ranking and fee structures increase operational complexity. Florida and California hosts face dual compliance layers that favor professional property managers over individual operators.
Leisure travelers now book shorter lead times with higher cancellation frequency. Mobile-first booking interfaces displace desktop reservation patterns, particularly among spontaneous weekend trip segments. Coastal leisure corridors including Miami Beach exhibit the most compressed booking windows, forcing revenue managers toward real-time inventory reallocation.
United States Online Accommodation Market Segmentation
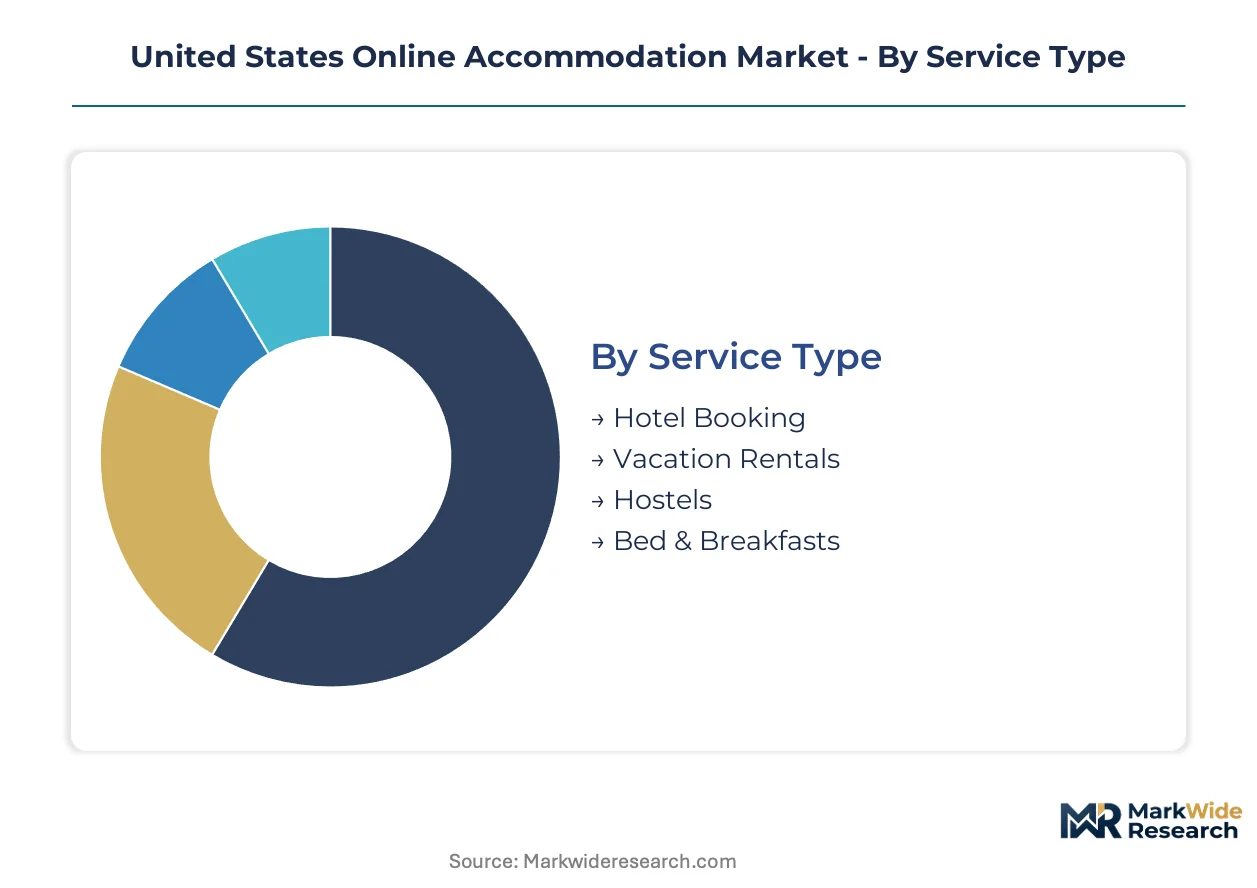
Segmentation in the United States online accommodation market reveals divergent margin structures and booking behaviors across service types and customer profiles. Platform operators calibrate commission rates and marketing spend differently for each slice, while hosts face distinct compliance obligations depending on property classification.
Service Type:
Volume concentration favors standardized inventory with predictable turnover, while premium extraction concentrates in differentiated experiential offerings where host autonomy enables dynamic rate management.
- Hotel Booking:Centralized inventory management systems connect property management software to global distribution networks. Corporate travel policies in New York and Chicago drive weekday absorption, with centralized billing integration reducing friction for administrative coordinators. Mature deployment sits with Hotel Booking. Newer deployment is concentrated in Vacation Rentals.
- Vacation Rentals:Entire-home and apartment listings dominate coastal leisure corridors including Miami Beach and Outer Banks. California's SB 761 registration requirements professionalize host operations, creating competitive separation between compliant operators and shadow inventory. Hosts leverage dynamic pricing algorithms that adjust rates based on local event calendars and competitor availability.
- Hostels:Shared dormitory and private room configurations target price-sensitive solo travelers and student segments. Urban clusters in Austin and Denver attract digital nomad demand with extended-stay pricing structures.
- Bed & Breakfasts:Owner-operated properties with limited room counts emphasize personalized service and local experience curation. Regulatory fragmentation across municipal jurisdictions creates compliance overhead that favors professional property managers.
Mature deployment sits with Hotel Booking. Newer deployment is concentrated in Vacation Rentals.
Customer Type:
Weekday demand patterns diverge sharply from weekend leisure spikes, with business travelers delivering revenue stability that offsets seasonal volatility in discretionary segments.
- Business Travelers:Centralized booking platforms integrate expense management systems and corporate rate negotiations. Road-warrior segments in technology and consulting verticals generate predictable Monday-through-Thursday demand that stabilizes revenue management algorithms.
- Leisure Travelers:Shorter booking lead times and higher cancellation frequency compress revenue planning windows. Mobile-first interfaces dominate spontaneous weekend trip segments, particularly in Nashville and Charleston leisure corridors.
- Group Travelers:Multi-room bookings for events and celebrations require coordination tools that reduce search friction across dispersed inventory. Bachelor party demand in Las Vegas and New Orleans drives concentrated peak-period pricing.
- Solo Travelers:Single-occupancy preferences favor hostels and micro-hotels with social programming. Safety verification features and female-only floor options influence platform selection.
Revenue predictability peaks with Business Travelers. Volume expansion is climbing the fastest among Leisure Travelers.
Distribution Channel:
Commission structures and customer acquisition costs vary dramatically across intermediated versus direct booking pathways, with loyalty program integration increasingly influencing channel selection.
- Online Travel Agencies:Aggregated inventory comparison reduces search friction through standardized review systems and flexible cancellation policies. Hosts absorb commission rates that compress per-transaction margins.
- Direct Booking:Property websites and chain loyalty programs bypass third-party commission structures. Marriott's Bonvoy ecosystem sustains volume through points redemption and status benefits.
- Mobile Apps:Geolocation-enabled last-minute inventory discovery targets spontaneous travelers. Push notification pricing alerts drive conversion for distressed inventory.
- Metasearch Engines:Rate comparison across multiple platforms reduces consumer search costs while increasing price transparency pressure on operators.
Customer lifetime value concentrates in Direct Booking. User acquisition is expanding most quickly through Mobile Apps.
Price Tier:
Rate stratification reflects amenity differentiation, location premium, and service intensity rather than purely physical asset quality.
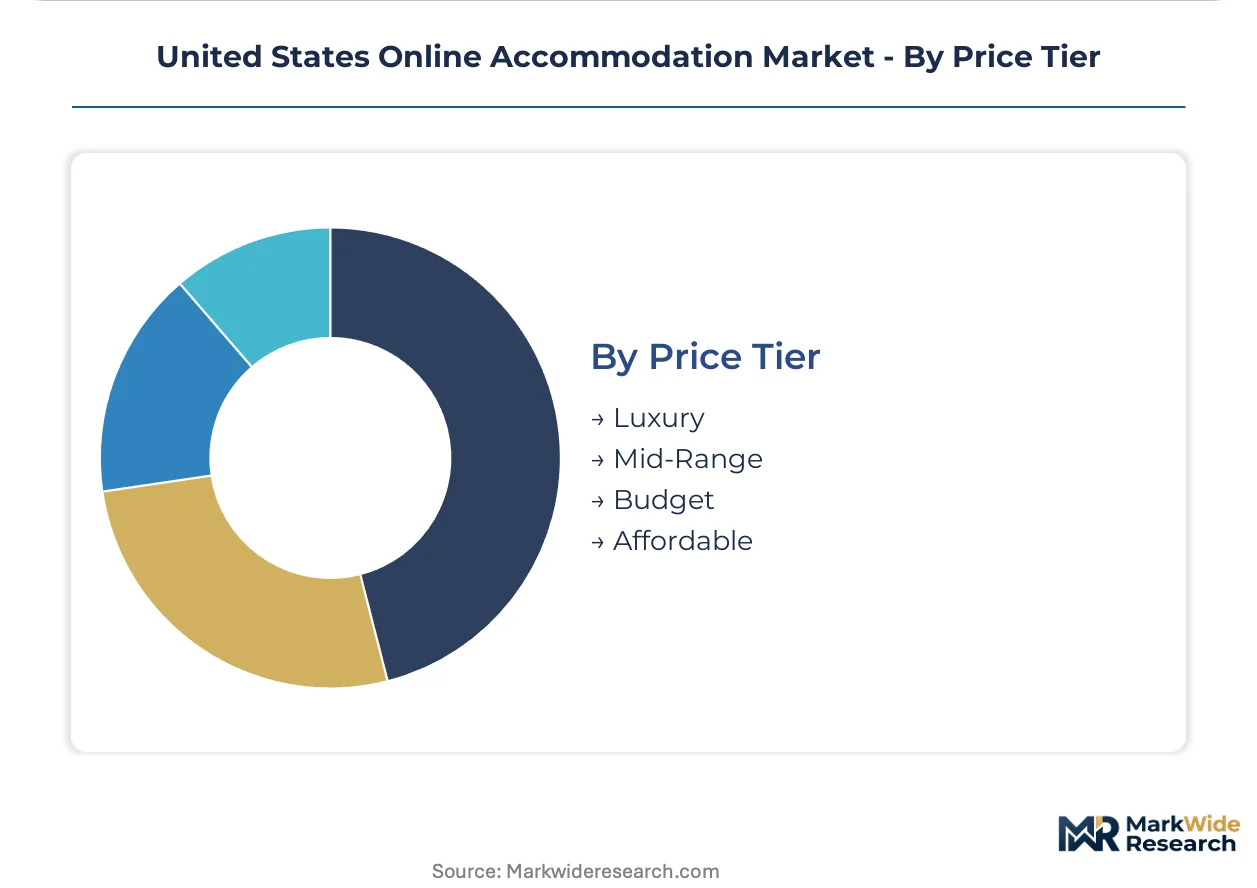
- Luxury:Concierge services, spa amenities, and exclusive access programming command rate premiums in Manhattan and Beverly Hills. Corporate retreat demand sustains weekday occupancy.
- Mid-Range:Full-service hotels and professionally managed vacation rentals balance amenity provision with price accessibility. Business travel policy compliance focuses on this tier.
- Budget:Limited-service properties and economy hotel chains prioritize cost minimization over experiential differentiation. Price-sensitive leisure segments dominate.
- Affordable:Hostels, shared accommodations, and non-traditional lodging options target extreme price sensitivity. Student and backpacker segments drive demand.
Rate stability sits with Mid-Range. Margin pressure is concentrating in Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zone tax incentives in Florida's Miami-Dade corridor concentrate platform infrastructure investment. State-level regulatory divergence creates compliance arbitrage between jurisdictions.
California
SB 761 mandates registration databases for short-term rental operators. Hosts face dual compliance layers from municipal occupancy taxes and state-level disclosure requirements. Los Angeles and San Francisco exhibit the highest professional property manager penetration as individual operators exit.
Florida
Miami Beach enforces strict annual night caps on rental properties. The state's Department of Revenue coordinates with platforms on automated tax remittance. Orlando's vacation rental corridor absorbs spillover demand from constrained coastal inventory.
Texas
Austin's SXSW and Formula 1 events drive extreme peak pricing volatility. The state legislature preempts municipal short-term rental bans, preserving host operating flexibility. Dallas-Fort Worth corporate housing providers capture extended-stay business travel.
New York
Multiple Dwelling Law restrictions limit short-term rental supply in Manhattan. The Attorney General's office actively enforces against illegal hotel operations. Brooklyn and Queens neighborhoods see inventory migration toward 30-day minimum stays.
Tennessee
Nashville's Music City Center expansion sustains convention-driven weekday demand. Local ordinances cap non-owner-occupied rentals in residential zones. The Gulch and Downtown Core concentrate platform-serviced inventory.
United States Online Accommodation Market Competitive Landscape
West Coast technology platforms anchor one tier; traditional hospitality conglomerates hold established distribution infrastructure. Market structure exhibits bifurcation between asset-light intermediaries and vertically integrated property operators. Three archetypes dominate: loyalty-program hotel chains, multi-brand online travel agencies, and peer-to-peer rental marketplaces. Competitive moves concentrate on direct booking incentive programs and automated revenue management system deployment.
Within the hospitality conglomerate tier, Marriott and Hilton exemplify loyalty-driven direct booking strategies. Among technology-native intermediaries, Airbnb and Booking.com occupy positions as marketplace infrastructure providers. Expedia represents the multi-brand portfolio archetype spanning leisure and corporate segments.
| Leading Market Players |
|---|
| Marriott |
| Priceline |
| Expedia |
| Landing |
| HotelsCombined |
| Airbnb |
| Hilton |
| Blueground |
| Booking.com |
| Others |
Value Network & Pricing Analysis
Automated revenue management systems now dominate rate-setting across the United States online accommodation sector, compressing host margins while concentrating pricing power with platform operators who control algorithmic infrastructure. This technology shift simultaneously elevates compliance costs for individual operators and rewards professional property managers with scale economies in multi-jurisdiction tax remittance.
Pricing Analysis
Short lead-time premiums now command substantial rate markups in coastal leisure corridors, while distressed inventory discounts accelerate as cancellation frequency rises. Three-tier pricing structure across premium, standard, and economy levels stratifies by amenity intensity and location access rather than physical asset quality alone. Pricing pressure stems from platform commission compression and municipal night-cap enforcement that constrains revenue ceilings. Budget-tier operators exhibit highest price sensitivity, while luxury segments maintain rate integrity through concierge differentiation and corporate retreat programming.
Supply Chain Analysis
Domestic-content mandates in California's SB 761 registration infrastructure reshape sourcing toward compliant local property managers and away from individual host operators. Supply concentration rests on United States-based professional management firms, Canadian technology vendors for pricing algorithms, and Mexican housekeeping labor pools serving border markets. Raw material dependencies include cloud computing infrastructure, payment processing networks, and property verification photography services. Single-source vulnerability concentrates in platform-dependent distribution channels. Distribution runs through mobile-first booking interfaces that displace traditional travel agency intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States online accommodation market operates as a cost-of-compliance story where California's SB 761 registration database creates a barrier-to-entry moat that professionalizes host operations and squeezes shadow inventory.
For Market Incumbents: Hedge regulatory fragmentation by investing in automated tax-remittance infrastructure that spans municipal jurisdictions. Acquire professional property management firms in Florida and California to consolidate compliant inventory. Vertical integration into revenue management software reduces platform dependency and preserves margin capture from dynamic pricing algorithms. For New Entrants and Emerging Players: AI-powered host onboarding tools offer a technology-first wedge into the market's highest-friction pain point. Target secondary cities including Austin and Denver where supply fragmentation rewards first-mover platform density. Deploy mobile-native interfaces with geolocation-enabled last-minute inventory discovery to capture spontaneous traveler segments underserved by incumbent desktop-first platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hospitality conglomerates seeking vacation rental inventory integration. Long-term viability favors professional property managers with multi-jurisdiction compliance capabilities and direct booking channel development. Watch municipal night-cap enforcement intensity as the critical inflection signal for inventory migration toward extended-stay furnished housing alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Tax Remittance Infrastructure | California's SB 761 and Florida's Department of Revenue coordination transform compliance overhead into competitive differentiation. |
| Professional Property Manager Acquisition | Consolidation captures compliant inventory and operational expertise in fragmented secondary markets. |
| Direct Booking Channel Development | Loyalty program integration reduces commission exposure and builds customer lifetime value. |
| Revenue Management System Deployment | Machine learning pricing algorithms narrow technology gaps between mid-scale operators and major chains. |
| Mobile-First Platform Redesign | Geolocation and push notification capabilities target compressed booking windows in leisure corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform revenue managers, professional property operators, municipal zoning administrators, corporate travel procurement officers, and hospitality technology vendors. Specific sources included SEC 10-K disclosures from publicly traded platforms, state-level short-term rental registration databases, FCC transparency filings, and customs records on cloud infrastructure equipment imports. Bottom-up host inventory counts triangulated against top-down platform commission revenue estimates.
Data-stream reconciliation across booking volume, average nightly rate, and commission yield projections informed the analytical framework across the analysis window. Segmentation dimensions modeled encompassed service type, customer profile, distribution channel, price tier, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy intervention timing and technology adoption curves. Industry-specific forecast inputs incorporated event calendar pricing volatility and corporate travel policy digitization rates.
Several conditions sit outside the modeled scope, including potential federal preemption of state short-term rental regulations, platform algorithmic ranking disclosure mandates beyond current FCC requirements, and macroeconomic recession impacts on discretionary leisure travel. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology adoption timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Sweden Hospitality Market
Accommodation
Croatia Hospitality Market
Accommodation
Russia Online Accommodation Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
Switzerland Hospitality Market
Accommodation
Europe Student Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
Romania Hospitality Market
Accommodation
US Student Accommodation Market
Accommodation
Peer to Peer Accommodation Market
Accommodation
Hostel Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
United Kingdom Hospitality Market
Accommodation
Japan Online Accommodation Market
Accommodation
France Casino Tourism Market
Accommodation
Casino Hotel Market