
 Smart Hospitality Market | 2026-2036
Smart Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hospitality Market Analysis
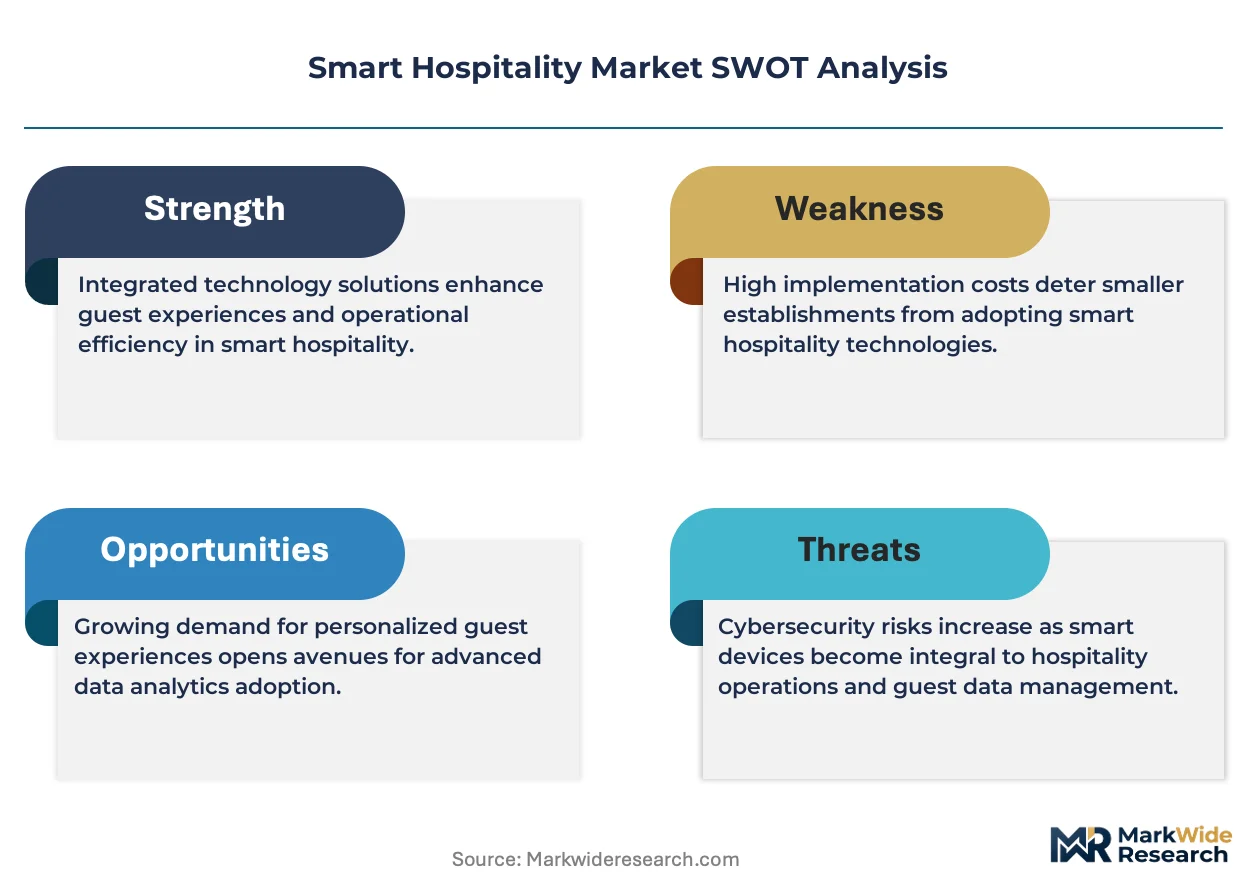
Asset-light franchising and equipment-leasing models is fragmenting competitive dynamics in smart hospitality, lowering capital barriers for mid-scale operators. Huawei Technologies Co., Ltd. leverages its 5G infrastructure dominance to bundle connectivity with property management systems. Cisco Systems, Inc. sustains enterprise-grade network security architectures that anchor premium hotel technology stacks. Schneider Electric competes through integrated building automation platforms that control energy, lighting, and climate from unified dashboards.
Smart hospitality encompasses digitally networked building systems that automate environmental control, security, and guest services through sensor arrays, actuators, and centralized management software operating across IP-based protocols. These installations reduce operational expenditure through predictive maintenance algorithms and real-time energy load balancing while enabling personalized guest experiences via mobile keyless entry and in-room voice interfaces. Room automation commands the largest installed base among application segments, though guest engagement platforms capture disproportionate margin pools through recurring software subscriptions. IoT Solutions lead technology deployment by volume, while AI Analytics represents the fastest-expanding category as properties deploy predictive models for revenue management and demand forecasting.
GDPR in Europe, the EU AI Act, and FCC equipment authorization requirements in the United States collectively shape product design standards and cross-border data governance obligations for smart hospitality vendors. China's MIIT enforces GB standards for network-connected building equipment, creating compliance complexity for multinational suppliers. Stakeholders must monitor divergence between regional data-localization mandates and cloud-native platform architectures when scaling across jurisdictions.
Market Dynamics
AI-driven personalization engines are compressing service delivery cycles across property portfolios, forcing operators to reconfigure staffing models and capital allocation toward software-centric guest engagement architectures.
Growth Catalysts
- EU Green Deal building mandates:Retrofit requirements across European hospitality assets are accelerating demand for integrated energy management platforms that unify HVAC, lighting, and climate control through centralized dashboards.
- China's tier-one smart city integration:State-backed initiatives in Beijing, Shanghai, and Shenzhen are embedding hospitality infrastructure within municipal IoT networks, creating captive demand for interoperable building systems.
- 5G infrastructure densification:Property-wide low-latency connectivity is enabling real-time sensor arrays for predictive maintenance and dynamic revenue management algorithms.
Market Restraints
- Semiconductor supply concentration:Sensor and edge-computing component sourcing remains concentrated among East Asian foundries, exposing installation timelines to geopolitical friction.
- GDPR-EU AI Act compliance layering:Cross-border data governance obligations create architectural constraints on cloud-native platform deployments across European properties.
- Legacy property retrofit costs:Mid-scale operators face prohibitive capital requirements for IP-protocol upgrades in pre-digital building stock.
Strategic Opportunities
- India's hospitality modernization:PLI scheme incentives for electronics manufacturing are reducing landed costs for IoT hardware in underpenetrated tier-two hotel markets.
- Voice-AI convergence:Integration of natural language processing with room automation is creating new subscription revenue pools through guest service unbundling.
- Asset-light franchising models:Equipment-leasing structures are lowering capital barriers for mid-scale operators seeking smart technology parity with luxury chains.
Industry Challenges
- Cybersecurity talent scarcity:Properties struggle to staff dedicated network security functions capable of managing enterprise-grade threat surfaces across distributed IoT endpoints.
- Interoperability fragmentation:Proprietary protocols from competing building automation vendors complicate unified management software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hospitality Market |
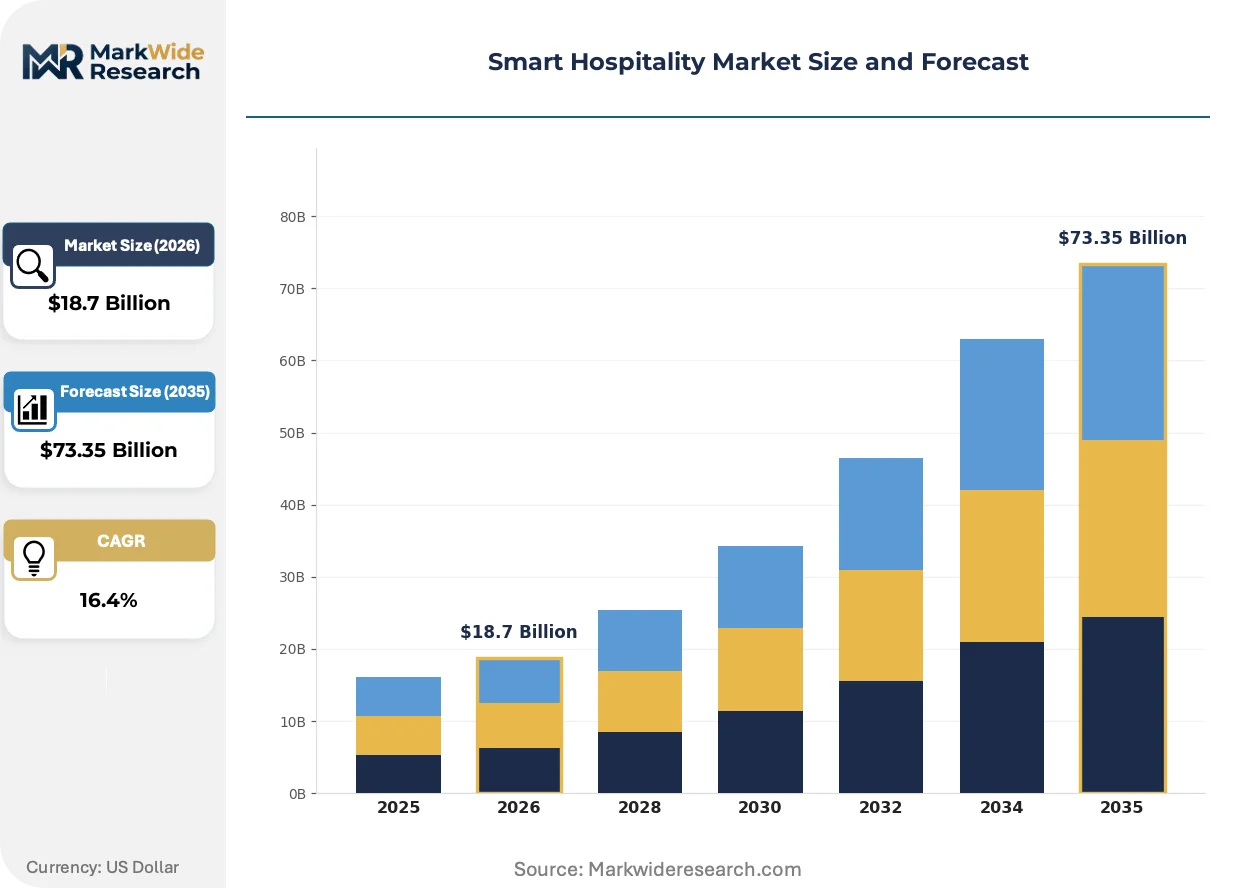
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Locks, Room Management Systems Application: Room Automation, Energy Management, Security Monitoring, Guest Engagement End User: Hotels, Resorts, Restaurants, Cruise Lines Technology: IoT Solutions, Cloud Computing, AI Analytics, Mobile Applications |
| Companies Covered | NEC Corporation, Huawei Technologies Co., Ltd., Cisco Systems, Inc., IBM, Schneider Electric, Honeywell International Inc., Siemens, Oracle, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hospitality Market Emerging Trajectories
Digital twin architectures are compressing the gap between physical building operations and software-defined control layers, enabling predictive intervention before guest-facing service failures materialize.
Edge computing nodes embedded within room automation controllers are virtualizing traditional building management system functions, allowing luxury properties in Dubai and Singapore to process occupancy and environmental data locally rather than routing through centralized servers. High-end hotel chains are deploying these architectures fastest, drawn by sub-second response times for climate and lighting adjustments. This distributed processing model is virtualizing the role of legacy on-premise servers, reducing both latency and cloud egress costs.
The EU AI Act's risk classification framework for automated decision-making systems is forcing hospitality software vendors to reengineer guest profiling algorithms deployed across European properties. Properties must now maintain audit trails for AI-driven pricing and service recommendations. Mid-scale operators dependent on third-party platforms face the steepest compliance adaptation costs.
Corporate travel procurement departments are unbundling technology amenities from room rates, negotiating direct contracts with smart platform vendors for standardized experiences across their hotel portfolios. This disintermediation pressures property-level margins while favoring franchisors with centralized technology procurement leverage. The pattern is most pronounced among Fortune 500 travel programs with contracted properties in China and the United States.
Smart Hospitality Market Segmentation
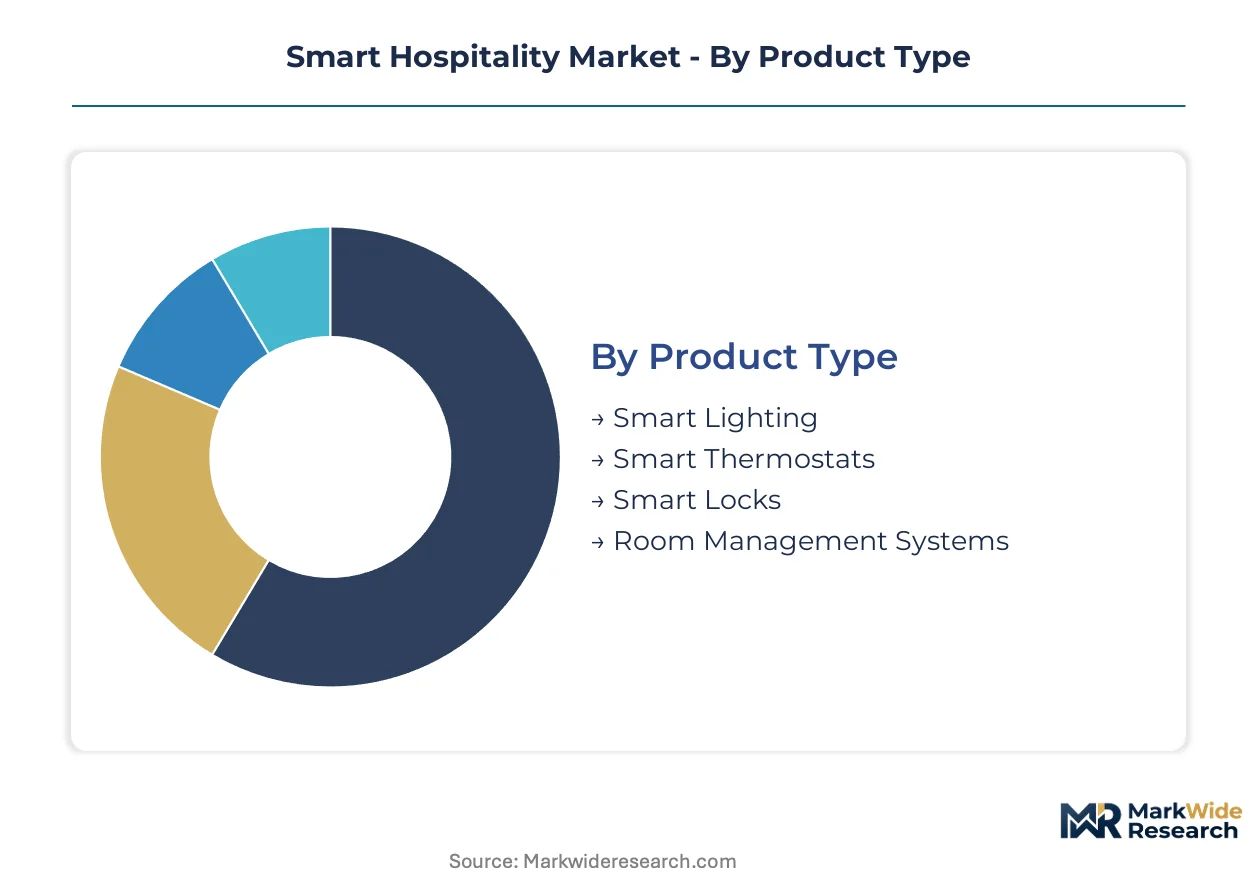
Smart hospitality vendors configure service architectures around distinct deployment patterns. Each segment demands specialized integration protocols and carries diverging margin profiles across property tiers.
Product Type:
After-sales service intensity varies sharply across hardware categories, with sensor-laden devices requiring continuous calibration support.
- Smart Lighting:LED arrays with occupancy-based dimming and circadian rhythm programming dominate retrofit specifications. Demand concentrates in Dubai and Singapore luxury properties where guest experience differentiation commands premium positioning.
- Smart Thermostats:Machine-learning climate controllers adapt to occupancy patterns and weather forecasts. European properties under EU Green Deal mandates drive replacement cycles as building efficiency standards tighten.
- Smart Locks:BLE and NFC-enabled access systems eliminate front desk bottlenecks.
- Room Management Systems:Centralized platforms integrating HVAC, lighting, and entertainment through unified touchpoints.
Room Management Systems holds the largest share; momentum sits with Smart Thermostats.
Application:
Margin structure follows deployment complexity, with software-centric applications capturing recurring revenue streams.
- Room Automation:Integrated environmental and entertainment control through in-room tablets and voice interfaces. China's tier-one cities embed these within municipal smart city networks, creating standardization pressure.
- Guest Engagement:Mobile check-in, service requests, and personalized recommendation engines. Luxury chains in Singapore deploy AI-driven profiling to compress service delivery cycles.
- Energy Management:Real-time load balancing and predictive HVAC optimization.
- Security Monitoring:Video analytics and access logging across distributed property footprints.
Room Automation holds the largest share; Guest Engagement climbs the fastest.
End User:
Capital deployment capacity determines technology tier access, fragmenting vendor go-to-market strategies.
- Hotels:Full-service and limited-service properties represent the foundational installed base. Mid-scale operators in India leverage PLI scheme incentives to narrow the technology gap with luxury competitors.
- Resorts:Expansive footprints with distributed amenities require mesh-networked sensor architectures.
- Restaurants:Table management and kitchen automation systems with lower integration complexity.
- Cruise Lines:Maritime deployments with satellite backhaul and salt-air hardened equipment specifications.
Hotels holds the largest share; momentum sits with Resorts.
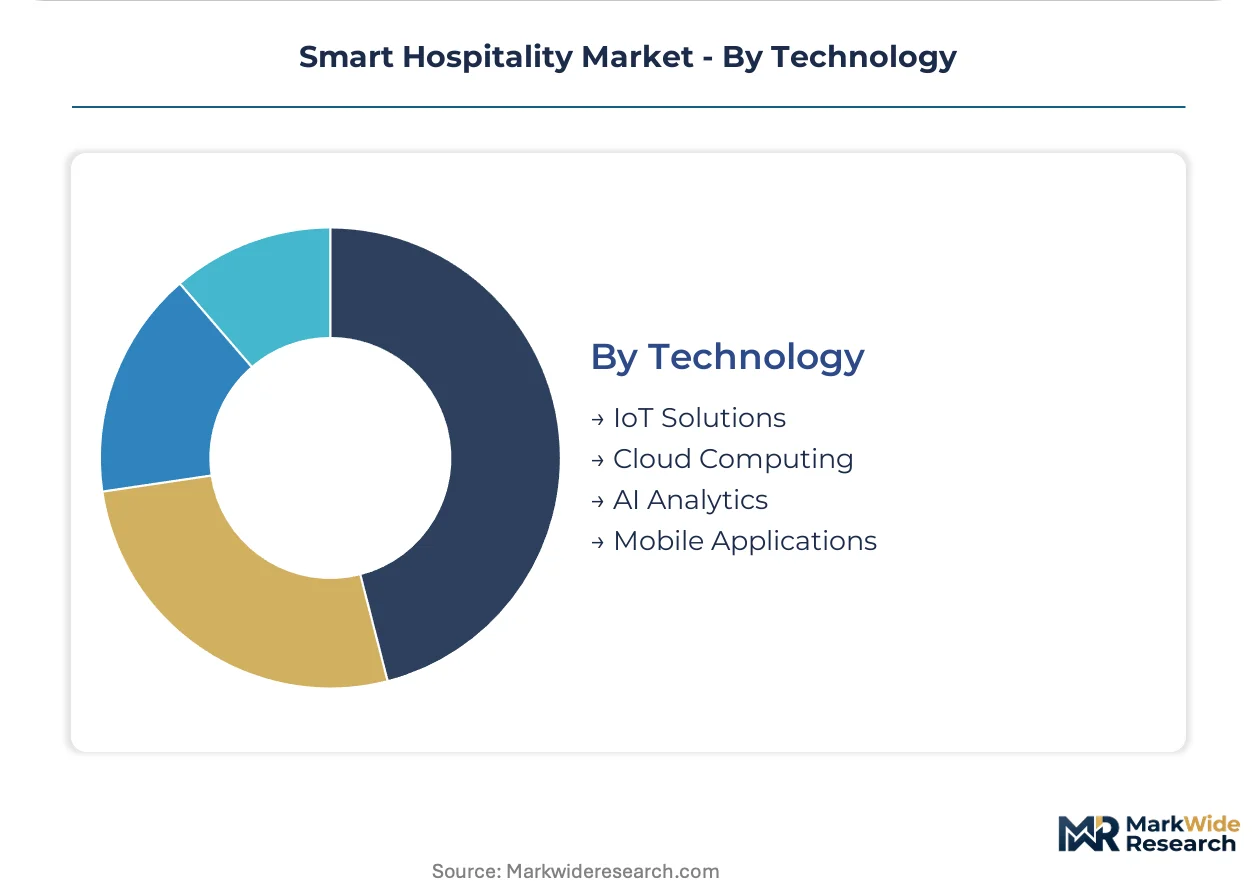
Technology:
Supply concentration in edge-computing components shapes deployment feasibility across technology layers.
- IoT Solutions:Sensor arrays and actuators communicating over Zigbee, Z-Wave, and proprietary protocols. Volume deployment leads this category though margin compression intensifies with hardware commoditization.
- AI Analytics:Predictive models for revenue management, demand forecasting, and guest preference learning. GDPR-EU AI Act compliance layering creates architectural constraints for cloud-native deployments.
- Cloud Computing:Centralized data lakes and software-as-a-service property management platforms.
- Mobile Applications:Guest-facing interfaces for keyless entry, service requests, and loyalty program integration.
IoT Solutions holds the largest share; AI Analytics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart hospitality technology flows concentrate in net-importing advanced economies while manufacturing supply clusters in export-oriented manufacturing bases shape equipment availability timelines.
United States
FCC equipment authorization requirements govern network-connected building systems entering the market. Corporate travel procurement departments headquartered in Chicago and New York Metro negotiate direct vendor contracts, disintermediating property-level technology decisions. The Pacific Northwest corridor hosts cloud-native platform development for guest engagement architectures.
Germany
The EU Green Deal's building efficiency mandates accelerate retrofit demand across hospitality assets in Bavaria and North Rhine-Westphalia. ECHA chemical compliance requirements affect sensor manufacturing specifications for devices deployed across European properties. Frankfurt's financial district hotels anchor demand for enterprise-grade network security stacks.
China
MIIT enforces GB standards for network-connected building equipment, creating compliance complexity for multinational suppliers. State-backed smart city initiatives in Beijing, Shanghai, and Shenzhen embed hospitality infrastructure within municipal IoT networks. Yangtze River Delta manufacturing clusters supply sensor arrays and edge-computing components to domestic and export markets.
United Arab Emirates
MOHAP medical-tourism adjacent hospitality standards influence guest safety monitoring specifications in Dubai healthcare district hotels. Luxury hotel chains deploy AI-driven guest engagement platforms to differentiate service delivery in the premium segment. Dubai's hospitality technology cluster concentrates system integrators serving Gulf Cooperation Council markets.
Singapore
Building and Construction Authority green mark certification drives smart thermostat and energy management adoption across hospitality portfolios. The city-state's data-localization requirements constrain cloud-native platform architectures for multinational hotel operators. Marina Bay and Orchard Road luxury properties anchor AI-driven personalization engine deployments.
Smart Hospitality Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays and connectivity modules. The vendor base organizes around three strategic archetypes: telecommunications infrastructure bundlers, building automation conglomerates, and enterprise software houses. Consolidation pressure intensifies as property operators seek unified dashboards over fragmented point solutions. Competitive moves center on strategic partnerships between connectivity providers and property management software vendors, plus portfolio diversification into adjacent building automation verticals.
Within the telecommunications infrastructure tier, Huawei Technologies Co., Ltd. and Cisco Systems, Inc. occupy positions representing divergent geographic market access strategies. Schneider Electric exemplifies the building automation conglomerate archetype, competing through integrated control platforms. NEC Corporation anchors the enterprise IT systems segment, representing Japanese-origin technology integration capabilities.
| Leading Market Players |
|---|
| NEC Corporation |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| IBM |
| Schneider Electric |
| Honeywell International Inc. |
| Siemens |
| Oracle |
| Johnson Controls |
| Others |
Supply Flow & Price Mechanics
East Asian foundry concentration for sensor and edge-computing components anchors margin capture upstream, while property operators downstream face compressed procurement leverage against bundled system integrators. Hardware commoditization in IoT devices intensifies price competition at the volume tier, redirecting margin pools toward software-centric guest engagement platforms with recurring subscription architectures.
Pricing Analysis
Corporate travel procurement departments anchor pricing negotiations through direct vendor contracts that disintermediate property-level technology decisions. Three-tier pricing structure across premium, standard, and economy levels separates luxury hotel chains with AI-driven personalization budgets from mid-scale operators seeking equipment-leasing parity. Cost compression in sensor hardware stems from Yangtze River Delta manufacturing scale, while pricing softness in cloud-native platforms reflects GDPR-EU AI Act compliance layering. Mid-scale operators dependent on third-party platforms exhibit highest price sensitivity; luxury chains with centralized technology procurement leverage show lowest.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion for edge-computing components deployed in smart hospitality architectures. Supply concentrates in Taiwan, South Korea, and China for sensor arrays, actuators, and connectivity modules. Component sourcing draws from rare earth processing, silicon wafer production, and BLE/NFC chip fabrication. Single-source vulnerability concentrates in advanced node semiconductors for AI analytics workloads. Distribution runs through system integrators serving GCC markets from Dubai, with Yangtze River Delta clusters feeding domestic Chinese demand and European retrofit specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate travel procurement departments negotiating portfolio-wide technology contracts, fragmenting property-level vendor relationships. This consolidation pressures margins while favoring franchisors with centralized procurement leverage.
For Market Incumbents: Entrench platform stickiness through deeper integration with municipal IoT networks in China's tier-one cities, where state-backed smart city initiatives create switching costs. Defend against disintermediation by corporate procurement through exclusive data-localization architectures that satisfy Singapore's requirements. Priority lever: vertical integration into edge-computing node production to reduce cloud egress costs and latency for Dubai luxury properties.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two hotel markets where PLI scheme incentives reduce landed IoT hardware costs and competitive density remains low. Voice-AI convergence with room automation represents the most penetrable white-space, enabling subscription revenue unbundling from traditional guest services. Go-to-market angle: equipment-leasing structures that lower capital barriers for mid-scale operators seeking technology parity with luxury chains.
For Investors and Strategic Acquirers: Capital is best deployed toward building automation conglomerates with unified dashboard capabilities spanning energy, lighting, and climate control, as property operators seek consolidated platforms over fragmented point solutions. Long-term viability hinges on compliance adaptability across GDPR-EU AI Act divergence from cloud-native architectures. Acquisition target archetype: cybersecurity specialists addressing talent scarcity in enterprise-grade threat surface management across distributed IoT endpoints. Signal to watch: corporate travel procurement departments unbundling technology amenities from room rates at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies HVAC, lighting, and climate control through Schneider Electric-style dashboards for EU Green Deal compliance. |
| Strategic Partnership | Huawei leverages 5G infrastructure bundling to capture property management system contracts in GCC markets. |
| Acquisition of Specialist Firm | Cybersecurity talent scarcity drives consolidation for distributed IoT endpoint threat management capabilities. |
| Geographic Expansion | India's tier-two markets offer PLI-reduced hardware costs with underpenetrated mid-scale operator demand. |
| Product Launch | Voice-AI convergence with room automation creates new subscription revenue pools through guest service unbundling. |
Methodological Framework
A spread of perspectives from hotel technology procurement officers, property management system integrators, municipal smart city planners, and corporate travel program directors converged on the working assumptions shaping demand trajectories. Primary interviews with these stakeholders combined with secondary validation against SEC filings from building automation vendors, MIIT GB standard publications, EU regulatory databases, and hospitality industry trade data. Bottom-up installation counts across property tiers triangulated with top-down market sizing from equipment shipment records.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning deployment model, property tier, technology layer, and regional regulatory cluster. CAGRs were derived from curve-fitting historical adoption patterns against infrastructure investment cycles. Industry-specific forecast inputs included 5G densification timelines, EU Green Deal retrofit mandates, and China's smart city integration schedules.
Stress conditions across semiconductor supply availability, cross-border data governance divergence, and corporate travel recovery patterns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about interoperability standards convergence and cybersecurity talent pipeline development. Material shifts in export-control regime stringency or municipal IoT procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
US Restaurant Management Market