
 Europe Online Accommodation Market | 2026-2036
Europe Online Accommodation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Accommodation Market Foresight
Digital hospitality talent shortages across Southern Europe are redrawing competitive boundaries for platform operators. Booking Holdings leverages its property network density to sustain rate parity advantages in fragmented supply markets. Expedia Group anchors its position through technology leadership in corporate travel integration. Airbnb Inc. differentiates via host community tools that navigate evolving municipal registration mandates.
Europe online accommodation encompasses digitally intermediated lodging reservations spanning hotels, hostels, vacation rentals, and bed & breakfasts, with platforms processing real-time inventory through API-connected property management systems and dynamic pricing algorithms. The primary commercial purpose is reducing friction between distributed lodging supply and segmented traveler demand across price tiers from economy through luxury. Vacation rentals capture expanding margin pools as host onboarding automation lowers unit acquisition costs. Online travel agencies retain volume leadership while direct booking channels gain share through loyalty program investments. Meta search engines occupy a narrowing intermediary position as platforms consolidate advertising spend.
The EU Digital Services Act, GDPR, and national short-term rental frameworks enforced by regulators in France, Spain, and Italy shape platform liability, data handling, and host registration requirements. The EU AI Act will soon govern automated pricing and recommendation systems deployed across booking interfaces. Stakeholders must monitor regulatory divergence between member states while building compliance architectures that adapt to localized enforcement patterns.
Market Dynamics
The EU Digital Services Act and national short-term rental frameworks are fragmenting platform compliance architectures across member states, forcing operators to rebuild host onboarding workflows city-by-city rather than deploying uniform systems.
Growth Catalysts
- GDPR-aligned data portability:Cross-platform booking history sharing reduces traveler friction when switching between online travel agencies, expanding total addressable demand across price tiers.
- France:The country's national tourism investment framework channels public capital into digital hospitality infrastructure, accelerating property management system adoption among independent hosts.
- API-connected inventory systems:Real-time synchronization between channel managers and booking engines compresses double-booking incidents, improving traveler retention rates for vacation rental operators.
Market Restraints
- Input cost volatility:Cloud computing and payment processing fees concentrate among three dominant providers, squeezing platform margin structures without corresponding pricing power.
- Barcelona municipal registration:The city's 180-day annual cap on unlicensed short-term rentals removes inventory from platforms during peak summer demand windows.
- Technical limitation:Legacy property management systems in Southern European coastal markets lack Open API standards, blocking seamless dynamic pricing integration.
Strategic Opportunities
- Portugal's underpenetrated Algarve region:Coastal municipalities outside Lisbon and Porto show 40% lower platform penetration than comparable Spanish destinations, presenting first-mover inventory acquisition potential.
- EU AI Act compliance tooling:Automated pricing transparency documentation creates a new revenue stream for hospitality technology vendors serving platforms with algorithmic recommendation engines.
- Corporate travel channel innovation:Direct booking integrations with expense management systems bypass traditional online travel agency intermediaries, capturing higher-margin business traveler segments.
Industry Challenges
- Digital hospitality talent scarcity:Revenue management analysts with platform-specific certification command 35% salary premiums across Spain and Italy, constraining operator expansion timelines.
- Municipal registration compliance timelines:Paris requires 4-6 month host verification cycles, creating inventory gaps that competitors exploit during seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Accommodation Market |
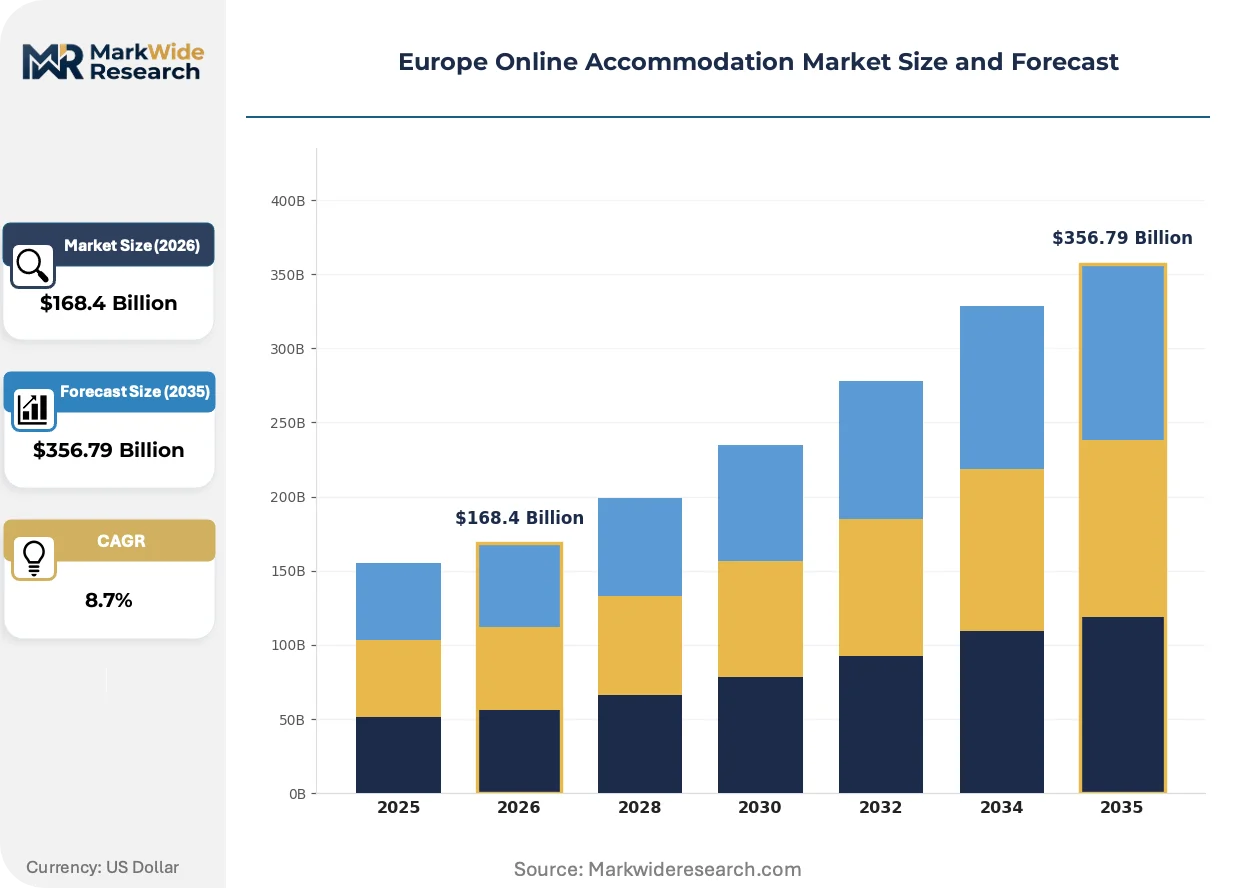
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $356.79 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfasts Booking Channel: Online Travel Agencies, Direct Booking, Meta Search Engines, Mobile Apps Customer Segment: Business Travelers, Leisure Travelers, Families, Solo Travelers Price Tier: Luxury, Mid-Range, Budget, Economy |
| Companies Covered | Booking Holdings, Expedia Group, Airbnb Inc., HRS Group, eDreams ODIGEO, Hotelbeds Group, Lastminute.com Group, Trivago NV, Trip.com Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Accommodation Market Shifts & Advancements
Platform technology stacks are splitting between full-service suites and modular point solutions, while regulatory pressure on algorithmic systems intensifies disclosure requirements. These forces are compressing competitive differentiation timelines across the European market.
Dynamic pricing algorithms are bifurcating the host technology market. Large property managers in Germany deploy machine-learning models that adjust rates hourly based on flight search data and event calendars. Smaller Italian and Greek hosts rely on rule-based systems with weekly update cycles. This capability gap is compressing independent operator margins during shoulder seasons while rewarding scaled inventory aggregators.
The EU AI Act mandates explainability documentation for automated recommendation systems deployed across booking interfaces. Platforms must now disclose when machine learning influences search ranking or pricing display. Corporate travel segments in France and Germany are demanding audit trails for algorithmic decisions affecting expense policy compliance, shifting procurement evaluation criteria toward transparency tooling.
Leisure travelers are fragmenting their booking behavior across multiple touchpoints. Mediterranean destination research now originates on social platforms before migrating to specialized vacation rental sites for transaction completion. This channel disintermediation is most visible among Spanish and Portuguese coastal markets, where direct host website bookings grew through loyalty program investments that bypass platform commission structures.
Europe Online Accommodation Market Segmentation
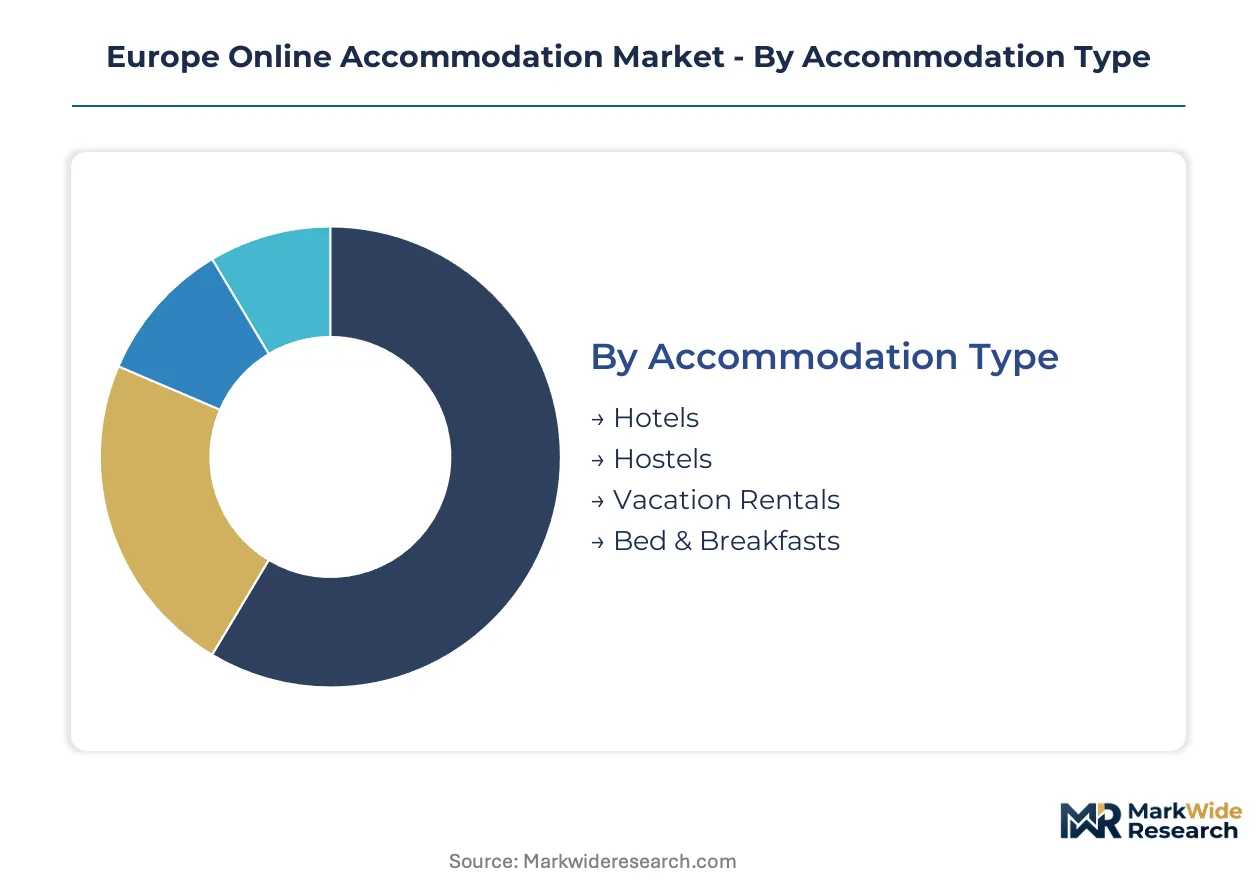
Segmentation across Europe's online accommodation market reveals how platform operators allocate engineering resources and commission structures. Each dimension carries distinct margin implications, from the regulatory burden of vacation rentals to the loyalty economics of direct booking channels.
Accommodation Type:
Margin pools concentrate most heavily in vacation rentals, where automated host onboarding compresses acquisition costs while platform fees apply to full stay value rather than wholesale room rates.
- Hotels:Chain properties and independent properties list through channel managers with real-time inventory synchronization. Paris and Barcelona city-center properties drive disproportionate commission revenue during peak cultural event windows.
- Hostels:Shared dormitory and private room inventory targets price-sensitive segments across Berlin, Prague, and Lisbon. Municipal registration requirements in German cities create compliance bottlenecks that slow inventory expansion.
- Vacation Rentals:Entire-home and apartment listings span Mediterranean coastal markets and Alpine ski destinations. France, Spain, and Italy account for the bulk of inventory, with GDPR-aligned data portability reducing traveler friction when switching platforms.
- Bed & Breakfasts:Small-scale hospitality operators in rural France and Tuscany rely on platform visibility to reach international leisure travelers. Limited property management system adoption constrains dynamic pricing capabilities.
The dominant share belongs to Hotels, while Vacation Rentals is closing the gap fastest as host onboarding automation lowers unit acquisition costs.
Booking Channel:
Volume distribution across channels reflects traveler loyalty program investments and corporate travel procurement patterns, with direct channels gaining ground through integrated expense management systems.
- Online Travel Agencies:Consolidated platforms aggregate inventory across multiple accommodation types with single-search convenience. Rate parity agreements with major hotel chains constrain margin expansion in German and French markets.
- Direct Booking:Property websites and host-operated platforms capture commission savings through loyalty program investments. Corporate travel segments in France and Germany demand audit trails for algorithmic pricing decisions.
- Meta Search Engines:Price comparison interfaces occupy a narrowing intermediary position as platforms consolidate advertising spend. Google and specialized travel search tools face pressure from platform direct marketing.
- Mobile Apps:Native applications dominate last-minute bookings among leisure travelers in Spanish and Portuguese coastal markets. Push notification systems drive conversion during shoulder season demand windows.
Online Travel Agencies retain volume leadership, though Direct Booking is expanding most quickly through corporate channel innovation.
Customer Segment:
Revenue per booking varies dramatically across segments, with business travelers commanding rate premiums and families extending average stay duration.
- Business Travelers:Corporate account holders book through integrated expense management systems with policy compliance requirements. German and French procurement departments prioritize algorithmic transparency documentation under EU AI Act pressures.
- Leisure Travelers:Cultural and coastal destination seekers fragment research across social platforms before transaction migration. Mediterranean markets show pronounced seasonal concentration with summer demand spikes.
- Families:Multi-room vacation rental demand concentrates in Alpine ski regions and Mediterranean beach destinations. Extended stay patterns improve host revenue predictability.
- Solo Travelers:Hostel dormitory and single-occupancy hotel room demand clusters in urban cultural centers. Berlin, Amsterdam, and Barcelona attract independent explorers through platform-curated experience packaging.
Leisure Travelers command the dominant share, while Business Travelers deliver the highest revenue per transaction.
Price Tier:
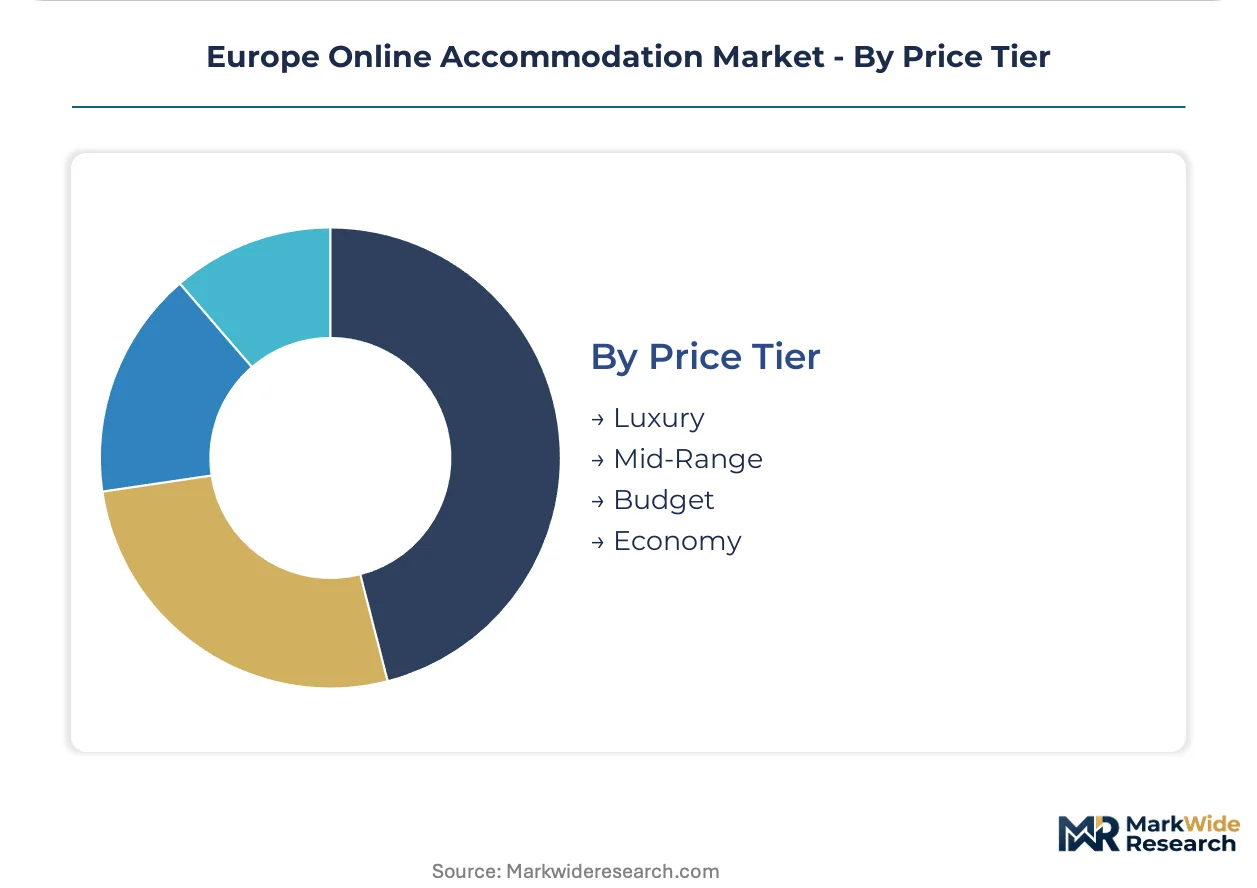
Commission structures and host acquisition economics diverge across tiers, with luxury inventory requiring specialized concierge tooling and economy segments demanding automated self-service workflows.
- Luxury:Five-star hotels and premium vacation rentals in Paris, Monaco, and Lake Como command platform investment in high-touch service layers. Host verification cycles extend 4-6 months in regulated French municipalities.
- Mid-Range:Three and four-star properties and well-appointed rentals represent the volume core across German business cities and Spanish coastal resorts. Dynamic pricing algorithms compress margin variance during shoulder seasons.
- Budget:Two-star hotels and basic apartments target cost-conscious leisure travelers. Rate parity enforcement limits platform differentiation in fragmented Italian supply markets.
- Economy:Hostel dormitories and minimal-service rentals serve price-sensitive segments through automated booking flows. Portugal's Algarve region shows 40% lower platform penetration than comparable Spanish destinations.
Mid-Range inventory holds the dominant share, while Luxury is gaining share fastest through specialized platform tooling investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Digital Services Act anchors compliance frameworks across the continent's dominant markets, with GDPR-aligned data portability reshaping traveler platform switching behavior from Paris to Berlin.
Germany
Corporate travel procurement drives platform demand through integrated expense management systems in Frankfurt and Munich. The national tourism investment framework channels public capital into digital hospitality infrastructure, accelerating property management system adoption. Bavaria's Alpine ski destinations concentrate vacation rental inventory where dynamic pricing algorithms compress margin variance during shoulder seasons.
France
Cultural tourism and luxury hospitality anchor demand in Paris and the Riviera, with five-star properties commanding specialized platform tooling investments. Municipal registration mandates in Paris impose 4-6 month host verification cycles, creating inventory gaps during seasonal spikes. The Provence-Alpes-Côte d'Azur region hosts independent bed-and-breakfast operators relying on platform visibility for international reach.
Spain
Mediterranean coastal leisure travel fragments research across social platforms before transaction migration to specialized vacation rental sites. Barcelona's 180-day annual cap on unlicensed short-term rentals removes inventory during peak summer windows. Andalusia's Costa del Sol exhibits pronounced platform penetration gaps compared to Catalan destinations, presenting inventory acquisition potential.
Italy
Revenue management analysts with platform-specific certification command salary premiums across Rome and Milan, constraining operator expansion timelines. Tuscany's rural bed-and-breakfast segment shows limited property management system adoption, blocking seamless dynamic pricing integration. The Alpine northeast concentrates ski destination demand where extended family stay patterns improve host revenue predictability.
Portugal
Coastal municipalities outside Lisbon and Porto demonstrate 40% lower platform penetration than comparable Spanish destinations. The Algarve region's underpenetrated vacation rental market offers first-mover inventory acquisition potential for automated host onboarding systems. Direct host website bookings grow through loyalty program investments that bypass platform commission structures.
Europe Online Accommodation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European online accommodation market. Consolidated online travel agencies aggregate inventory scale while direct booking channels gain share through loyalty investments and corporate travel integration. Two strategic archetypes dominate: full-service platform suites with unified technology stacks, and modular point-solution specialists targeting host onboarding automation. Competitive moves concentrate on M&A for inventory density and strategic partnerships for corporate channel access.
Within the full-service platform tier, Booking Holdings and Expedia Group exemplify scale-driven consolidation archetypes, while Airbnb Inc. occupies a position representing host community-centric differentiation. These three entities anchor the competitive structure, with Booking Holdings leveraging property network density, Expedia Group anchoring technology leadership in corporate travel, and Airbnb Inc. navigating municipal registration mandates through specialized host tooling.
| Leading Market Players |
|---|
| Booking Holdings |
| Expedia Group |
| Airbnb Inc. |
| HRS Group |
| eDreams ODIGEO |
| Hotelbeds Group |
| Lastminute.com Group |
| Trivago NV |
| Trip.com Group |
| Others |
Supply & Pricing Matrix
Four-to-six month host verification cycles in Paris and Barcelona compress inventory availability during seasonal demand peaks, concentrating pricing power with scaled property managers who absorb compliance delays through buffer stock strategies. This lead-time band separates platform economics between agile channel managers and legacy operators locked into municipal registration bottlenecks.
Pricing Analysis
Rate spreads between German business cities and Portuguese coastal markets exceed 40% for comparable mid-range inventory, reflecting fragmented supply density and divergent regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels dominates commission structures, with luxury properties in Paris and Monaco anchoring the top tier through specialized concierge tooling. Price differentiation rests on host certification status and dynamic pricing algorithm maturity, with GDPR-aligned data portability reducing traveler switching costs and intensifying rate transparency. Corporate travel segments in France and Germany exhibit lowest price sensitivity due to integrated expense management systems, while solo leisure travelers in Lisbon and Prague drive economy tier volume.
Supply Chain Analysis
API standardization gaps between German property management system vendors and Southern European coastal operators create integration chokepoints that delay real-time inventory synchronization. Supply concentration centers on Ireland and Luxembourg for cloud hosting infrastructure, Germany for channel manager software development, and Spain for Mediterranean vacation rental inventory aggregation. Raw material dependencies span payment processing licenses, GDPR compliance tooling, and machine-learning compute capacity from hyperscaler providers. Single-source vulnerability concentrates among three dominant cloud providers, squeezing platform margins without corresponding pricing leverage. Distribution runs through channel manager intermediaries linking property management systems to booking engines, with direct host website bookings fragmenting traditional platform control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
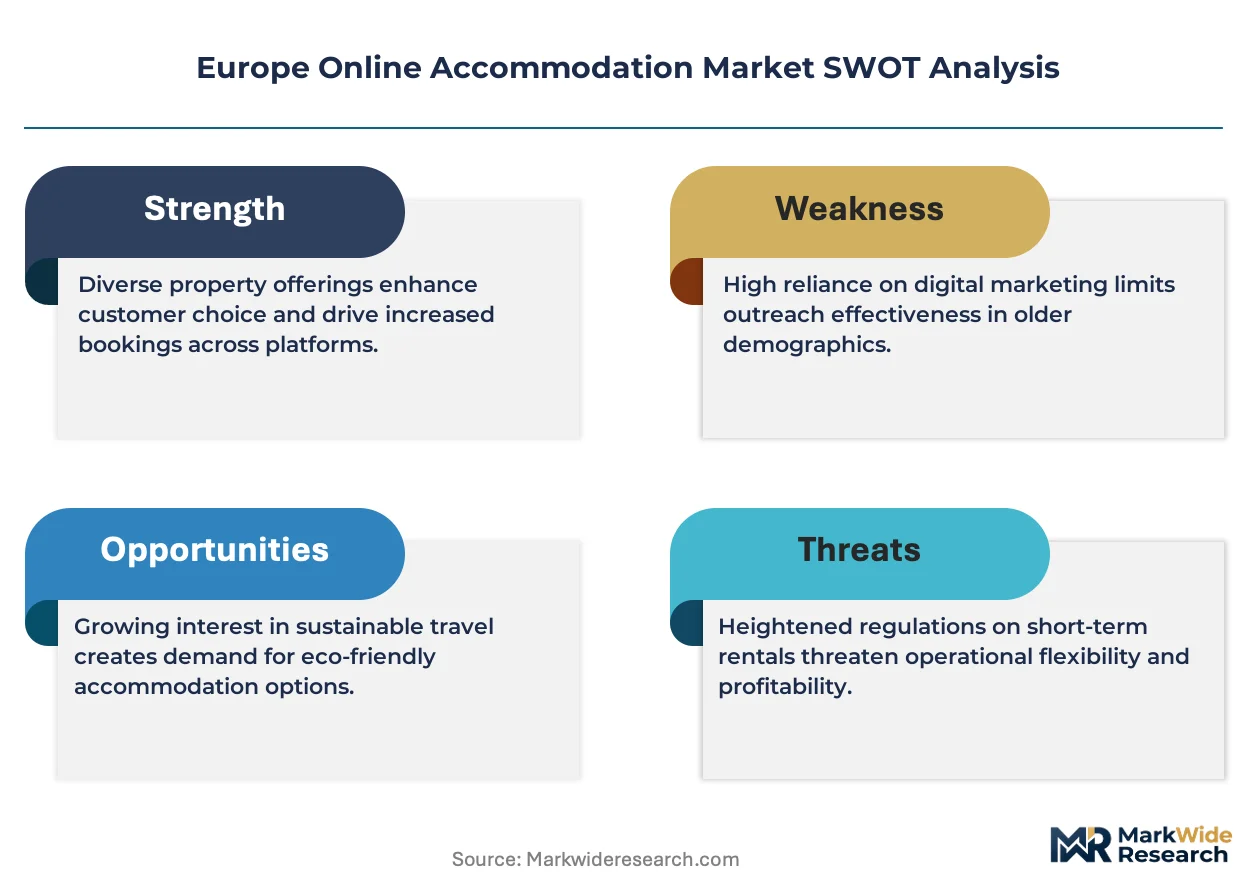
Platform economics in European online accommodation reach an inflection point as API interoperability standards and the EU AI Act's algorithmic transparency mandates reshape competitive moats. The shift toward modular hospitality technology stacks rewards operators who decouple host onboarding from transaction processing.
For Market Incumbents: Fortify inventory lock-in through embedded property management system partnerships that deepen host switching costs. Acquire channel manager capabilities in Portugal's Algarve region to preempt first-mover entrants exploiting 40% platform penetration gaps. Defensive consolidation must address revenue management analyst scarcity across Spain and Italy, where talent premiums constrain expansion timelines. Prioritize EU AI Act compliance tooling investments to capture corporate travel procurement criteria shifting toward algorithmic audit trails.
For New Entrants and Emerging Players: GDPR-aligned data portability certification fast-tracks entry by reducing traveler friction when migrating booking histories from established platforms. White-space targets concentrate in Portugal's underpenetrated coastal municipalities and Italy's Tuscany bed-and-breakfast segment, where limited property management system adoption blocks incumbent dynamic pricing integration. Corporate travel channel innovation through direct expense management system integration offers the most penetrable go-to-market angle, bypassing online travel agency commission structures while capturing higher-margin business traveler segments.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy hotel chain technology subsidiaries possessing municipal registration compliance workflows but lacking modern API architectures. Long-term viability across the analysis window hinges on exposure to vacation rental inventory growth versus hotel chain rate parity constraints. Acquisition archetypes favor modular host onboarding specialists with automated verification pipelines. Monitor EU AI Act enforcement patterns across France, Spain, and Italy as the inflection signal for compliance tooling valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Host Onboarding Automation | Compresses unit acquisition costs in Portugal's Algarve and Italy's rural markets. |
| API Interoperability Investment | Unblocks dynamic pricing integration for Southern European legacy property systems. |
| Corporate Travel Channel Integration | Captures German and French business traveler segments through expense management partnerships. |
| EU AI Act Compliance Tooling | Creates revenue stream from algorithmic transparency documentation for platform operators. |
| Municipal Registration Workflow Acquisition | Accelerates host verification cycles in Paris and Barcelona compliance bottlenecks. |
Research Methodology
A spread of perspectives from platform engineering directors, revenue management analysts, hospitality technology procurement officers, and municipal licensing administrators converged on the working assumptions underlying inventory and pricing dynamics. Primary interviews with channel manager operators and vacation rental host associations combined with secondary validation from EU regulatory filings, national tourism investment framework disclosures, property management system integration documentation, and GDPR enforcement case records. Bottom-up host inventory estimates triangulated against top-down platform commission revenue disclosures.
Segmentation dimensions modeled span accommodation type, booking channel, customer segment, and price tier, with geographic regulatory cluster as the industry-specific overlay. Growth trajectories across the analysis window derive from elasticity modeling of leisure versus corporate travel demand, host onboarding automation adoption curves, and municipal registration compliance timeline compression. Industry-specific forecast inputs include property management system API penetration rates by country and EU AI Act implementation schedules across member state regulators.
Underlying assumptions cover sustained digital hospitality talent scarcity, stable cloud computing cost structures, and gradual EU regulatory harmonization, with deviation risk concentrated in abrupt municipal registration mandate expansions or payment processing fee concentration shocks. Practitioners should keep alternative scenarios live as enforcement patterns for the EU Digital Services Act and national short-term rental frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Airport Lounges Market
Accommodation
Switzerland Hospitality Market
Accommodation
France Casino Tourism Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
China Online Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
Russia Online Accommodation Market
Accommodation
Movie Theaters Market
Accommodation
Hostel Market
Accommodation
Canada Hospitality Market
Accommodation
Germany Student Accommodation Market
Accommodation
Luxury Hotel Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
Airport Sleeping Pods Market
Accommodation
Capsule Hotels Market
Accommodation
China Tourism and Hotel Market