
 Casino Hotel Market | 2026-2036
Casino Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Casino Hotel Market Analysis
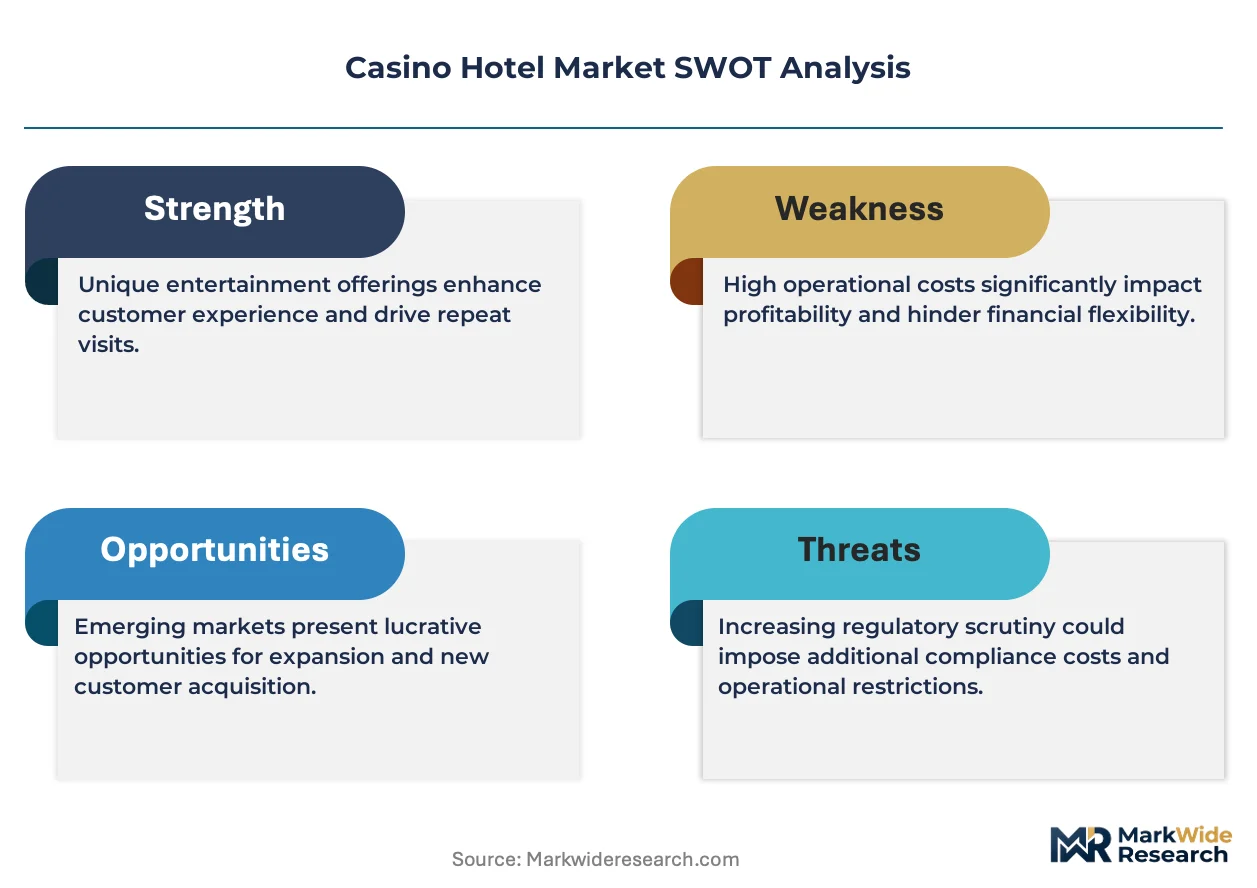
Asset-light management contracts and sale-leaseback structures is rewriting capital deployment across the casino hotel sector, allowing operators to shed property ownership while retaining brand control. MGM Resorts International leverages this model to sustain geographic diversification without balance-sheet concentration. Caesars Entertainment anchors its portfolio through franchise-heavy expansion, while Wynn Resorts differentiates through captive ownership of trophy assets in premium corridors.
A casino hotel constitutes a hospitality property integrating licensed gaming floors with accommodation, food and beverage, and entertainment amenities under a single operational umbrella, typically requiring specialized surveillance infrastructure, chip-tracking systems, and compliance-grade accounting protocols to satisfy gaming commission audit standards. Luxury property types dominate margin pools through higher average daily rates and extended guest stays, while sports betting as a gaming option represents the fastest-growing revenue layer following regulatory liberalization across multiple jurisdictions. Boutique formats compete for destination wedding and convention segments where personalized service offsets smaller scale.
The Nevada Gaming Control Board and state-level tribal gaming compacts shape US market access through licensing density caps and revenue-sharing requirements, while Singapore's Casino Regulatory Authority enforces strict entry levies and family exclusion frameworks that constrain volume but protect social license. Macau's Gaming Inspection and Coordination Bureau coordinates concession renewal terms that dictate capital commitment floors and non-gaming investment ratios. Stakeholders must monitor regulatory bargaining positions in pending concession cycles to calibrate property development timelines and partnership structures.
Market Dynamics
Asset-light management contracts are compressing capital requirements while preserving brand control, forcing operators to restructure balance sheets around intellectual property rather than physical property ownership.
Growth Catalysts
- Singapore's Casino Regulatory Authority entry levy framework:Strict social safeguards preserve operator license viability while channeling demand toward integrated resort complexes with extended-stay programming.
- Macau's non-gaming investment mandates:Concession renewal terms compel capital deployment into hospitality amenities, entertainment venues, and MICE infrastructure beyond gaming floors.
- US tribal gaming compacts:Sovereign land agreements enable regulatory arbitrage for expansion outside state-licensed density caps, opening development corridors in underserved domestic markets.
Market Restraints
- Construction cost escalation:Integrated resort development faces labor shortages and materials volatility, particularly in premium corridor markets where land scarcity compounds project economics.
- Regulatory fragmentation:Jurisdiction-specific licensing timelines, surveillance infrastructure mandates, and accounting protocol variations create compliance overhead that deters cross-border standardization.
- Substitution from online gaming platforms:Digital wagering alternatives capture recreational gaming spend without hospitality attachment, compressing feeder market capture for physical properties.
Strategic Opportunities
- Japan's integrated resort implementation:Delayed but advancing licensing processes in Osaka and Yokohama create first-mover positioning for operators with MICE and entertainment venue expertise.
- Sports betting regulatory liberalization:State-by-state expansion across the US enables hybrid venue concepts combining sportsbook operations with hospitality and broadcast infrastructure.
- Biometric payment convergence with loyalty platforms:Facial recognition and tokenized wagering systems streamline floor transactions while deepening customer data capture for personalized service delivery.
Industry Challenges
- Surveillance technology integration:Legacy analog systems require phased replacement with AI-enabled table monitoring and chip-tracking infrastructure to satisfy evolving gaming commission audit standards.
- Specialized compliance talent scarcity:Shortages of certified gaming accountants, surveillance officers, and regulatory liaison personnel constrain operational scaling in newly liberalized jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casino Hotel Market |
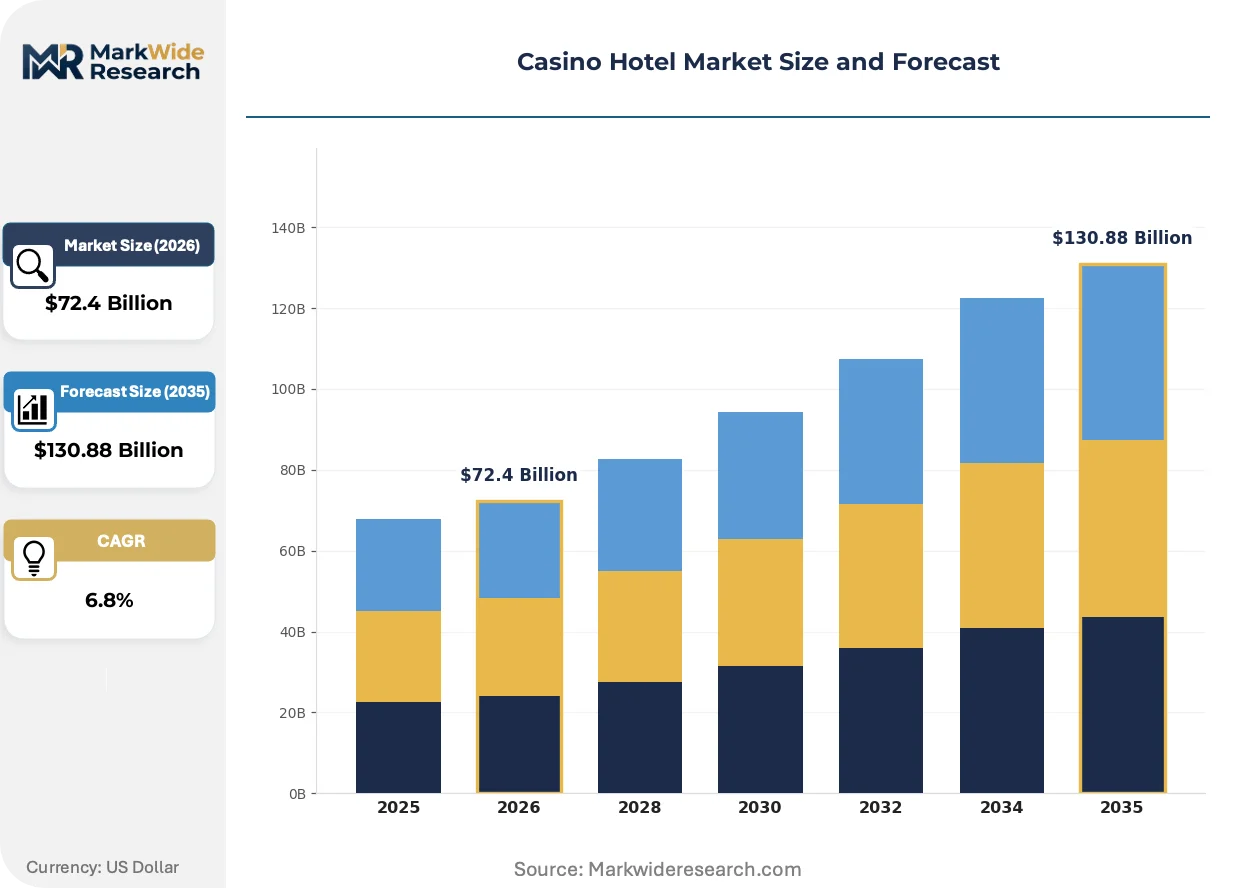
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $130.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Luxury, Boutique, Resort, Standard Target Customer: High Rollers, Vacationers, Business Travelers, Local Gamblers Gaming Options: Slot Machines, Table Games, Sports Betting, Poker Rooms Service Type: Online Reservations, Event Hosting, Dining Services, Spa Services |
| Companies Covered | Wynn Resorts Limited, Galaxy Entertainment Group, MGM Resorts International, Boyd Gaming Corporation, Penn Entertainment Inc., Las Vegas Sands Corporation, Melco Resorts & Entertainment, Hard Rock International, Caesars Entertainment, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casino Hotel Market Emerging Trajectories
Cashless wagering infrastructure and predictive analytics are compressing transaction friction while enabling real-time customer segmentation, reshaping how properties monetize floor activity and extend guest lifetime value.
RFID-enabled chip tracking and digital wallet integration is digitizing table game reconciliation, reducing manual count procedures and accelerating pit-to-cage settlement velocity. Tier-one operators in Macau and Nevada are deploying these systems across high-limit salons first, with rollout timelines compressing from multi-year phases to eighteen-month implementations. This digitizing of physical chip movement is collapsing the latency between wager placement and player rating accuracy, enabling dynamic comp allocation that was previously operationally impossible.
Macau's Gaming Inspection and Coordination Bureau concession renewal framework mandates minimum non-gaming revenue thresholds and capital commitment floors that reshape property development economics. Operators must now justify gaming floor square footage against hospitality, retail, and entertainment amenity ratios, with compliance audits occurring at defined intervals throughout concession terms. Premium corridor developments in Cotai are responding with expanded MICE infrastructure and celebrity chef dining concepts that satisfy ratio requirements while generating independent margin contribution.
Convention and group procurement is fragmenting away from traditional destination management company intermediaries toward direct property negotiation and transparent RFP platforms. Corporate meeting planners now benchmark Singapore integrated resorts against Las Vegas and Macau alternatives using standardized amenity scoring rather than relationship-driven selection. This compression of information asymmetry is most visible in Asia-Pacific markets where multinational corporate travel policies have centralized venue selection authority away from regional offices.
Casino Hotel Market Segmentation
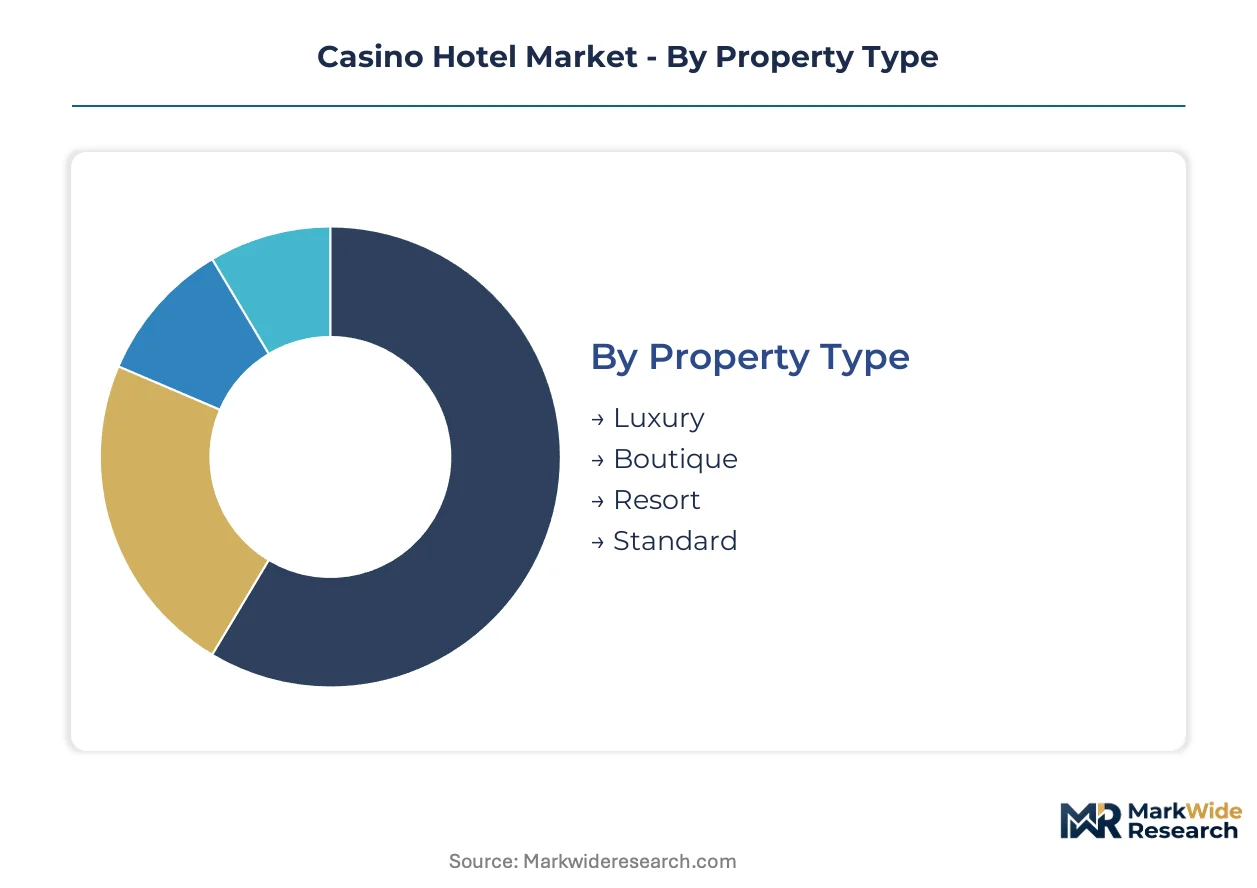
Casino hotel segmentation determines capital deployment intensity, staffing models, and regulatory compliance architecture. Property type and gaming mix dictate surveillance infrastructure requirements, while customer targeting shapes loyalty platform design and comp allocation algorithms.
Property Type:
After-sales service intensity varies dramatically across property tiers, with luxury assets requiring dedicated guest relations teams and boutique formats relying on cross-trained staff.
- Luxury:Trophy assets in premium corridors command extended average daily rates through suite inventory, private gaming salons, and celebrity chef dining. Cotai Strip developments in Macau anchor this tier, where non-gaming amenity ratios satisfy concession renewal mandates while generating independent margin contribution.
- Resort:Integrated complexes combine gaming floors with MICE infrastructure, entertainment venues, and extended-stay programming. Singapore's Marina Bay and Sentosa properties exemplify this format, where entry levy frameworks preserve social license while channeling demand toward comprehensive hospitality ecosystems.
- Boutique:Smaller-scale properties compete through personalized service and destination wedding positioning. These assets offset limited gaming volume with higher per-visitor spend capture in F&B and spa categories.
- Standard:Mid-tier properties serve feeder markets with streamlined amenity packages and efficient floor layouts. Nevada's regional casino markets and tribal gaming facilities outside major metropolitan areas concentrate this inventory.
By volume, Standard properties lead. By growth pace, Resort developments are ahead.
Target Customer:
Customer acquisition cost and lifetime value calculations diverge sharply across behavioral segments, with high-roller programs demanding dedicated hosts and local gambler retention relying on frequency-based rewards.
- High Rollers:Ultra-premium players warrant private jet coordination, credit line management, and bespoke entertainment procurement. Macau's VIP junket networks historically channeled this demand, though direct VIP programs are displacing intermediary-dependent models.
- Vacationers:Leisure travelers generate cross-category spend across gaming, hospitality, and retail. Las Vegas Strip properties optimize for this segment through package pricing and show ticket bundling.
- Business Travelers:Corporate meeting attendees produce midweek occupancy lift and convention center utilization. Direct RFP platform adoption is compressing destination management company intermediation in this segment.
- Local Gamblers:Proximity-driven players sustain regional properties through frequency programs and promotional event calendars. US tribal gaming compacts enable regulatory arbitrage for this demographic in underserved domestic corridors.
By revenue contribution, High Rollers dominate. By headcount expansion, Vacationers are climbing the fastest.
Gaming Options:
Floor configuration and technology infrastructure requirements vary by gaming vertical, with table games demanding pit supervision and sports betting requiring broadcast integration.
- Table Games:Baccarat, blackjack, and roulette operations require chip-tracking systems, pit accounting protocols, and dealer supervision hierarchies. Macau's concession frameworks mandate minimum table counts as part of capital commitment floors.
- Sports Betting:Wagering on athletic competitions represents the steepest expansion trajectory following US state-by-state regulatory liberalization. Hybrid venue concepts combining sportsbook operations with hospitality infrastructure are capturing this demand layer.
- Slot Machines:Electronic gaming devices generate volume through lower denomination play and automated reconciliation. RFID-enabled ticket-in-ticket-out systems are replacing legacy coin handling across tier-one operators.
- Poker Rooms:Dedicated card rooms attract tournament circuits and cash game specialists with rake-based revenue models. These spaces require distinct surveillance coverage and specialized dealer staffing.
By floor space allocation, Slot Machines lead. By regulatory momentum, Sports Betting is gaining share fastest.
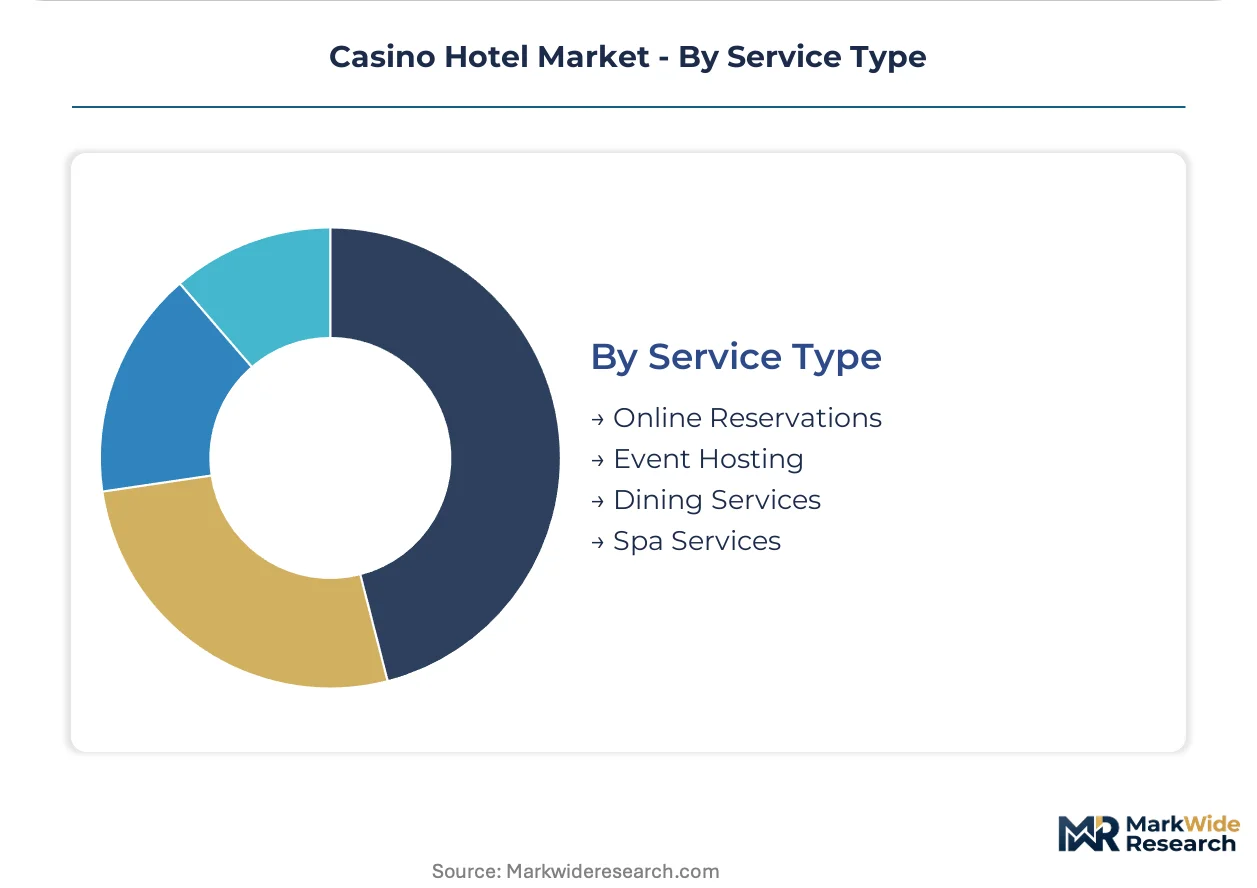
Service Type:
Digital integration and physical amenity bundling create distinct operational models, with online platforms compressing booking friction and on-property services driving ancillary spend.
- Online Reservations:Direct booking platforms and third-party aggregators channel demand while capturing customer data for pre-arrival personalization. Mobile check-in and digital key distribution are reducing front-desk labor intensity.
- Event Hosting:Convention and group procurement is fragmenting toward transparent RFP platforms and direct property negotiation. Corporate meeting planners now benchmark Singapore, Las Vegas, and Macau alternatives using standardized amenity scoring.
- Dining Services:Celebrity chef partnerships and fine dining concepts satisfy Macau's non-gaming investment ratios while generating independent margin. Quick-service outlets serve volume segments with labor-efficient production.
- Spa Services:Wellness amenities extend guest stays and capture discretionary spend outside gaming floors. Resort properties integrate spa programming with pool complexes and fitness facilities.
By transaction volume, Online Reservations lead. By margin expansion, Event Hosting is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign land compacts and concession renewal frameworks are reshaping capital deployment across major casino hotel corridors. Operators calibrate development timelines against regulatory bargaining positions in each jurisdiction.
United States
Tribal gaming compacts enable regulatory arbitrage for expansion outside state-licensed density caps. The Nevada Gaming Control Board enforces licensing density restrictions and revenue-sharing requirements that govern Strip development. Las Vegas anchors this market, where integrated resort complexes compete through MICE infrastructure and entertainment venue differentiation.
Macau
Cotai Strip corridor developments concentrate integrated resort investment under Gaming Inspection and Coordination Bureau oversight. Concession renewal terms mandate minimum non-gaming revenue thresholds and capital commitment floors. Premium corridor properties deploy expanded celebrity chef dining and MICE infrastructure to satisfy ratio requirements while generating independent margin contribution.
Singapore
Marina Bay and Sentosa integrated resorts channel demand through strict entry levy frameworks and family exclusion protocols. The Casino Regulatory Authority enforces social safeguards that preserve operator license viability while protecting market access. Leisure tourism flows concentrate in these complexes through extended-stay programming and comprehensive hospitality ecosystems.
Japan
Delayed but advancing integrated resort licensing processes in Osaka and Yokohama create first-mover positioning opportunities. METI coordinates implementation timelines with prefectural authorities. Developers with MICE and entertainment venue expertise are securing preliminary partnerships ahead of formal concession awards.
Australia
State-level casino licensing frameworks govern development concentration in New South Wales and Victoria. Regulatory scrutiny of VIP junket networks has intensified following compliance failures. Sydney and Melbourne properties are diversifying revenue mix toward domestic visitation and non-gaming amenities to offset high-roller volatility.
Casino Hotel Market Vendor Landscape
Channel-controlling players compete with product-specialist players across asset-light and captive-ownership models. The market structures around three tiers: integrated resort operators with geographic diversification, regional casino specialists with tribal or state-licensed concentration, and boutique hospitality brands with entertainment venue differentiation. Dominant competitive moves include portfolio restructuring through management contract expansion and strategic partnerships targeting Japan's emerging integrated resort licensing.
Within the integrated resort tier, Wynn Resorts Limited and Las Vegas Sands Corporation exemplify contrasting capital deployment philosophies. MGM Resorts International and Caesars Entertainment occupy positions across the asset-light spectrum through franchise-heavy expansion models. Galaxy Entertainment Group anchors the Macau-focused archetype with Cotai Strip concentration.
| Leading Market Players |
|---|
| Wynn Resorts Limited |
| Galaxy Entertainment Group |
| MGM Resorts International |
| Boyd Gaming Corporation |
| Penn Entertainment Inc. |
| Las Vegas Sands Corporation |
| Melco Resorts & Entertainment |
| Hard Rock International |
| Caesars Entertainment, Inc. |
| Others |
Supply Flow & Price Mechanics
Macau's Gaming Inspection and Coordination Bureau concession renewal frameworks concentrate capital commitment requirements among a handful of licensed operators, concentrating downstream margin pools in trophy assets that satisfy non-gaming investment ratios while commanding premium positioning.
Pricing Analysis
Property tier and regulatory compliance grade create the primary spread between luxury integrated resorts and standard regional properties. Three-tier pricing structure across luxury, resort, and standard levels segments customers by average daily rate tolerance and gaming volume commitment. Pricing pressure stems from construction cost escalation in premium corridors where land scarcity compounds labor shortages. Local gambler segments exhibit highest price sensitivity through frequency-dependent promotional calendars, while high-roller programs demonstrate lowest sensitivity through credit line and bespoke service bundling.
Supply Chain Analysis
Extended payment terms from gaming equipment manufacturers to property developers compress working capital cycles across project timelines. Supply concentrates in Nevada, Macau, and Singapore for surveillance infrastructure, with chip-tracking systems and compliance-grade accounting software drawing from specialized vendors in the United States and China. Raw material dependencies include steel and concrete for integrated resort construction, imported marble and finish materials for luxury interiors, and semiconductors for RFID-enabled gaming devices. Single-source vulnerability runs through specialized surveillance technology providers serving gaming commission audit standards. Distribution runs through direct procurement relationships between operators and tier-one equipment vendors, bypassing intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across customer acquisition models creates white-space opportunities as direct VIP programs displace junket-dependent intermediaries and biometric payment convergence reshapes loyalty platform economics.
For Market Incumbents: Entrench market position through captive ownership of trophy assets in premium corridors while accelerating asset-light management contract expansion into secondary markets. Defend against online gaming platform substitution by deepening hospitality attachment through extended-stay programming and MICE infrastructure investment. Prioritize vertical integration into surveillance technology and compliance talent pipelines to constrain operational scaling costs.
For New Entrants and Emerging Players: Japan's delayed integrated resort licensing processes in Osaka and Yokohama present underpenetrated development corridors where MICE and entertainment venue expertise secures preliminary partnership positioning. Target sports betting regulatory liberalization across US state markets with hybrid venue concepts combining sportsbook operations with broadcast infrastructure. Pursue franchise-heavy expansion models that shed property ownership while retaining brand control.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional casino specialists seeking exit liquidity as tribal gaming compact renegotiations reshape sovereign land economics. Long-term viability centers on operators with demonstrated concession renewal navigation and non-gaming revenue diversification. Watch Japan integrated resort licensing timelines and US state sports betting legislative calendars as inflection indicators for capital deployment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Management Contract Expansion | MGM Resorts International and Caesars Entertainment deploy this model to sustain geographic diversification without balance-sheet concentration. |
| Biometric Payment Platform Integration | Facial recognition and tokenized wagering systems streamline floor transactions while deepening customer data capture for personalized service delivery. |
| Non-Gaming Amenity Ratio Compliance | Macau's Gaming Inspection and Coordination Bureau mandates force capital deployment into hospitality, retail, and entertainment infrastructure. |
| Sports Betting Hybrid Venue Development | State-by-state US regulatory liberalization enables concepts combining sportsbook operations with hospitality and broadcast infrastructure. |
| Direct VIP Program Displacement | Operators are displacing junket-dependent models with proprietary high-roller acquisition to reduce intermediary risk and improve margin capture. |
Methodological Framework
A standing panel of casino operations executives, gaming regulatory affairs specialists, hospitality procurement directors, and tribal gaming compact negotiators provided ongoing calibration against secondary validation from SEC 10-K filings, state gaming commission revenue reports, Macau Gaming Inspection and Coordination Bureau concession disclosures, and Singapore Casino Regulatory Authority entry levy statistics. Bottom-up property-level data triangulated against top-down market sizing from customs records and tourism board visitation statistics.
Scenario-bracketing framed projections across the analysis window, modeling segmentation dimensions including property type, target customer behavioral segment, gaming option mix, and service type integration. CAGRs derived from historical trajectory analysis adjusted for regulatory cycle timing and capital commitment floor requirements. Forecast inputs incorporated concession renewal term structures, non-gaming investment mandate ratios, and sports betting legislative velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light franchise operators or sovereign wealth-backed integrated resort developers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Africa Hotel Market
Accommodation
Netherlands Hospitality Industry Market
Accommodation
Europe Online Accommodation Market
Accommodation
UAE Hospitality Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
France Casino Tourism Market
Accommodation
US Student Accommodation Market
Accommodation
Capsule Hotels Market
Accommodation
Europe Camping and Caravanning Market
Accommodation
France Online Accommodation Market
Accommodation
China Tourism and Hotel Market
Accommodation
India Student Accommodation Market
Accommodation
Bed and Breakfast Accommodation Market
Accommodation
Sweden Hospitality Market
Accommodation
Romania Hospitality Market
Accommodation
Europe Student Accommodation Market