
 High Voltage Direct Current (HVDC) Transmission System Market | 2026-2036
High Voltage Direct Current (HVDC) Transmission System Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Direct Current (HVDC) Transmission System Market Foresight
Project finance tied to long-term offtake agreements is narrowing the field of viable HVDC bidders to firms with balance-sheet depth. Siemens Energy leverages its manufacturing scale across converter stations and cable systems. Hitachi Energy Ltd anchors its position through technology leadership in voltage source converter installations. Prysmian Group dominates submarine cable supply for offshore wind interconnectors.
A high voltage direct current transmission system converts alternating current to direct current for bulk power transfer across distances exceeding 600 kilometers or submarine spans where AC losses become prohibitive, employing thyristor or insulated-gate bipolar transistor switching at ratings from 100 kV to 800 kV and above. Voltage source converter technology leads new project awards due to its black-start capability and independent reactive power control, while line commutated converter installations retain cost advantages at the highest power ratings. Submarine cable deployment for offshore wind integration represents the fastest-growing installation category, with overhead lines maintaining the largest installed base across continental corridors.
The EU Green Deal and REPowerEU framework shape cross-border interconnector timelines and permitting requirements across European member states. Germany's Federal Network Agency and Denmark's Energinet coordinate North Sea offshore grid development through joint network planning. China's National Energy Administration and State Grid Corporation set domestic UHVDC corridor standards that influence equipment specifications globally. Stakeholders must weigh converter technology selection against evolving grid code requirements for inertia provision and frequency response before committing to decade-long asset lifecycles.
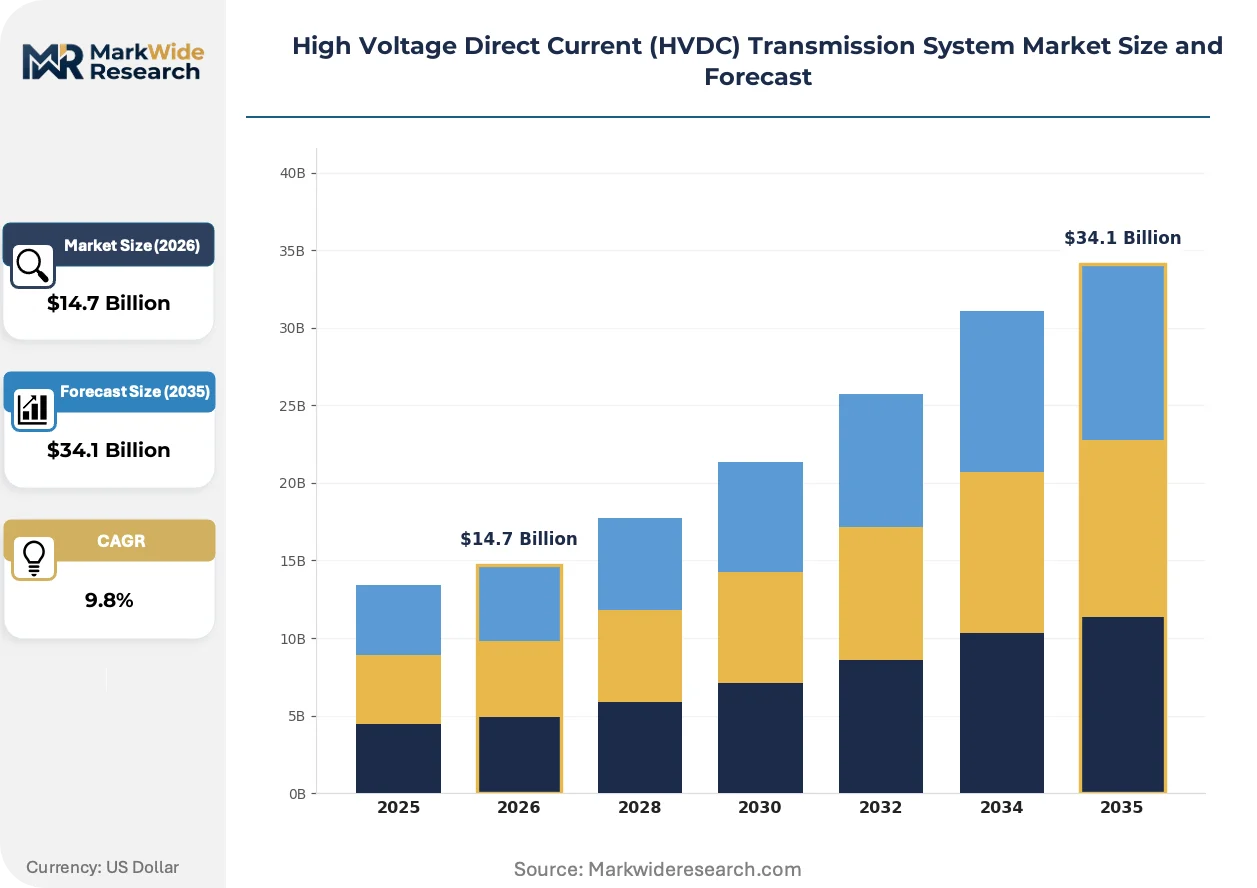
Market Dynamics
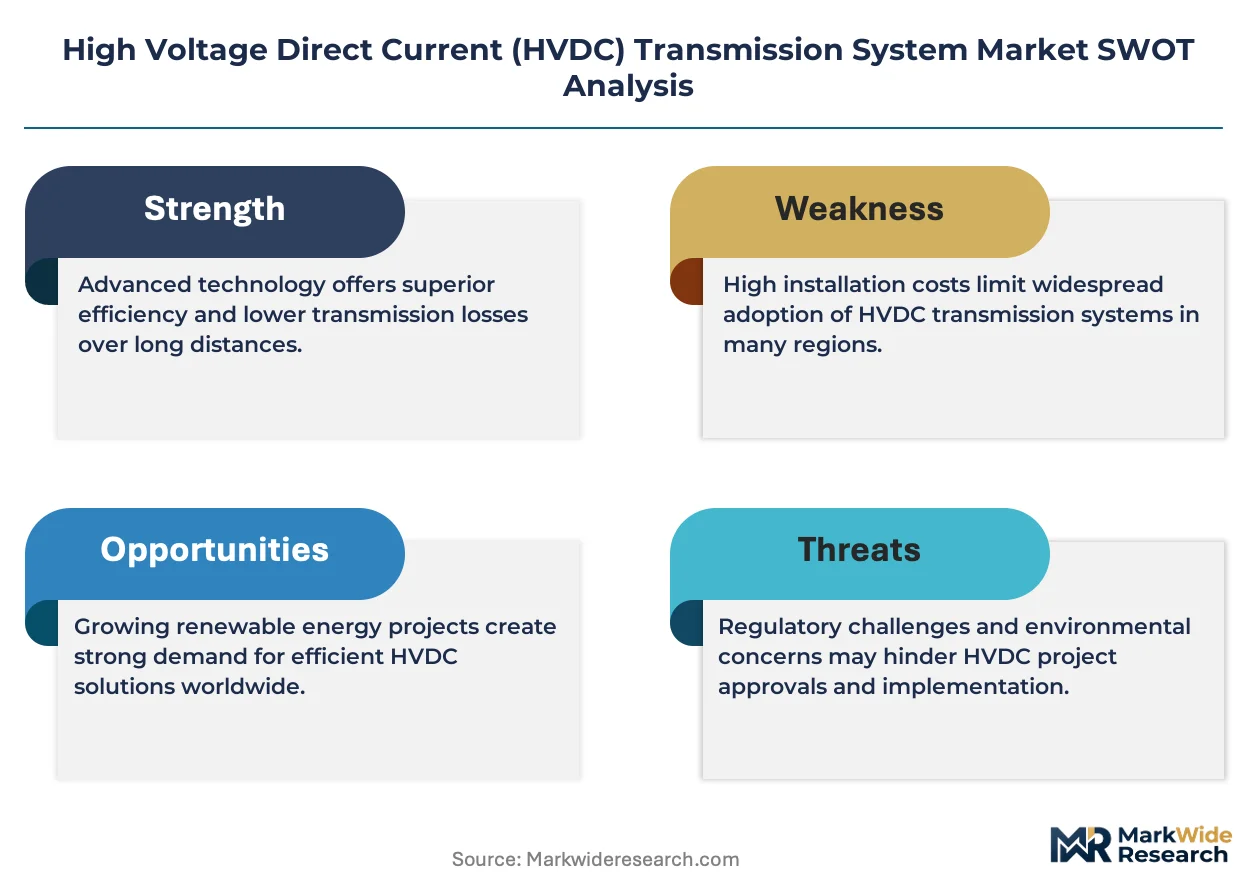
Voltage source converter technology is consolidating project awards across offshore wind corridors, compressing line commutated converter dominance as black-start capability becomes mandatory in grid codes.
Growth Catalysts
- REPowerEU framework:Cross-border interconnector permitting timelines have shortened across member states, accelerating Baltic and North Sea corridor development.
- Offshore wind farm developers:Submarine cable procurement volumes are expanding as Germany's North Sea leasing rounds require HVDC export capacity.
- Thyristor switching advances:Higher voltage ratings at 800 kV and above are unlocking continental-scale overhead line projects.
Market Restraints
- Copper and rare earth price volatility:Insulated-gate bipolar transistor modules depend on concentrated Chinese processing capacity for semiconductor substrates.
- Submarine cable supply concentration:Specialized vessel fleets for deep-water installation remain limited to three European and Asian suppliers.
- Line commutated converter technical ceiling:Inertia provision requirements in modern grid codes expose reactive power control limitations.
Strategic Opportunities
- United States Atlantic coast:Bureau of Ocean Energy Management lease areas lack sufficient interconnection infrastructure for planned 30 GW offshore capacity.
- Green hydrogen electrolyzer co-location:Direct current coupling between HVDC terminals and industrial loads bypasses alternating current conversion losses.
- Japan's METI grid reinforcement roadmap:Inter-island submarine links between Hokkaido and Honshu specify voltage source converter standards.
Industry Challenges
- Power electronics specialist scarcity:Converter station commissioning requires engineers fluent in both high-voltage hardware and digital control systems.
- Multi-joint submarine cable certification:Factory acceptance testing protocols vary between Germany's Federal Network Agency and Denmark's Energinet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Direct Current (HVDC) Transmission System Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $34.1 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Hybrid Converter, Others Application: Renewable Energy Integration, Long-Distance Transmission, Grid Interconnection, Industrial Applications End User: Utilities, Renewable Energy Operators, Industrial Manufacturers, Government Agencies Installation Type: Overhead Lines, Underground Cables, Submarine Cables, Others |
| Companies Covered | Siemens Energy, Hitachi Energy Ltd, Mitsubishi Electric Corporation, GE Vernova, Prysmian Group, Toshiba Energy Systems & Solutions Corporation, NKT A/S, LS Electric Co., Ltd., TBEA Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Direct Current (HVDC) Transmission System Market Shifts & Advancements
Digital twin deployment is compressing commissioning timelines for converter stations while predictive maintenance algorithms reshape asset management economics across transmission operators.
Modular multilevel converter architecture is virtualizing traditional thyristor-based valve hall designs. Offshore wind developers in the German Bight are specifying MMC platforms for their independent reactive power control. This topology is virtualizing the engineering hours previously consumed by harmonic filter design.
The EU F-Gas Regulation is phasing down sulfur hexafluoride use in gas-insulated switchgear. Converter station designers are adopting vacuum interrupters and clean air insulation for new North Sea projects. Manufacturers serving the Baltic Sea corridor have accelerated fluoronitrile-based alternative development to maintain project eligibility.
Transmission system operators are unbundling long-term service agreements from initial equipment supply. Ørsted and RWE now procure converter station maintenance through separate competitive tenders. This pattern is most visible in Denmark, where Energinet's standard contract templates separate availability guarantees from construction milestones.
High Voltage Direct Current (HVDC) Transmission System Market Segmentation
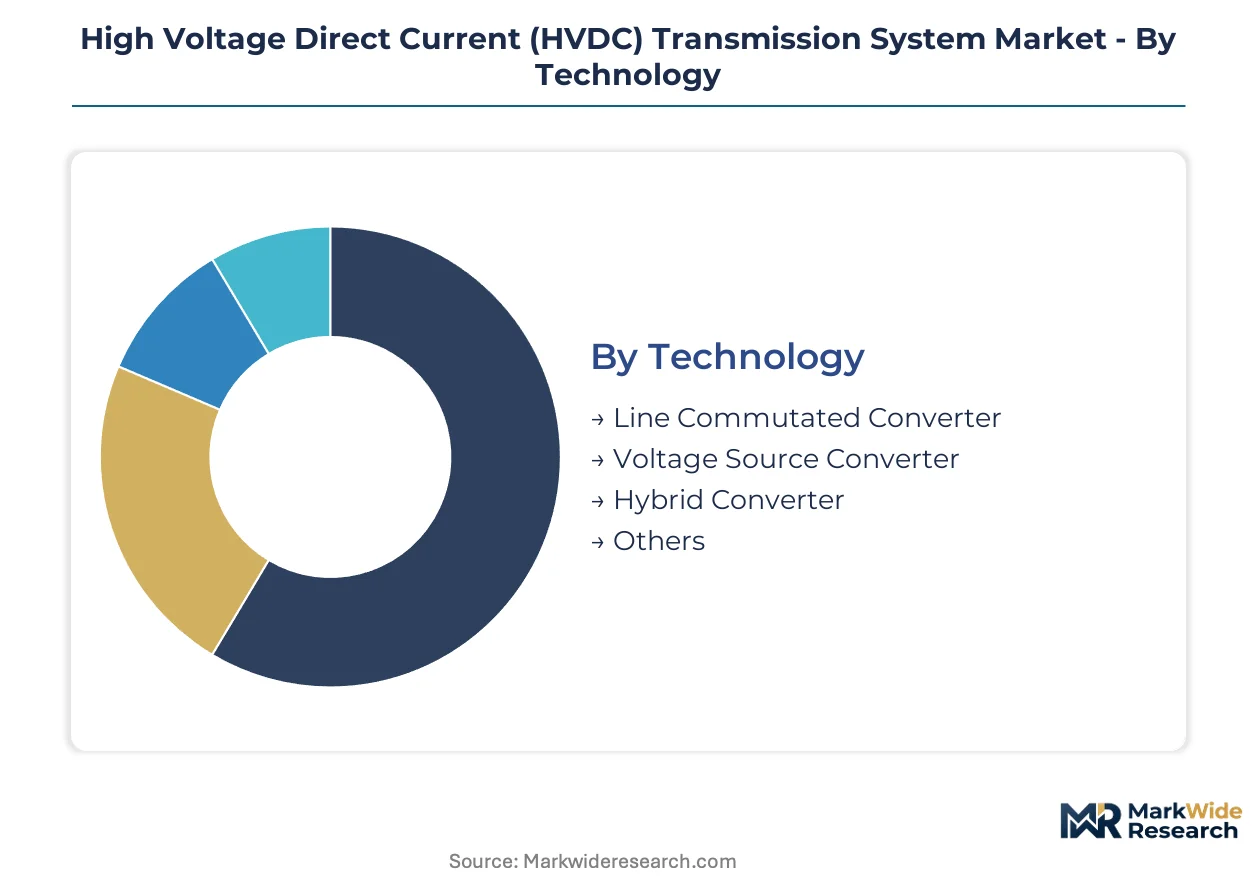
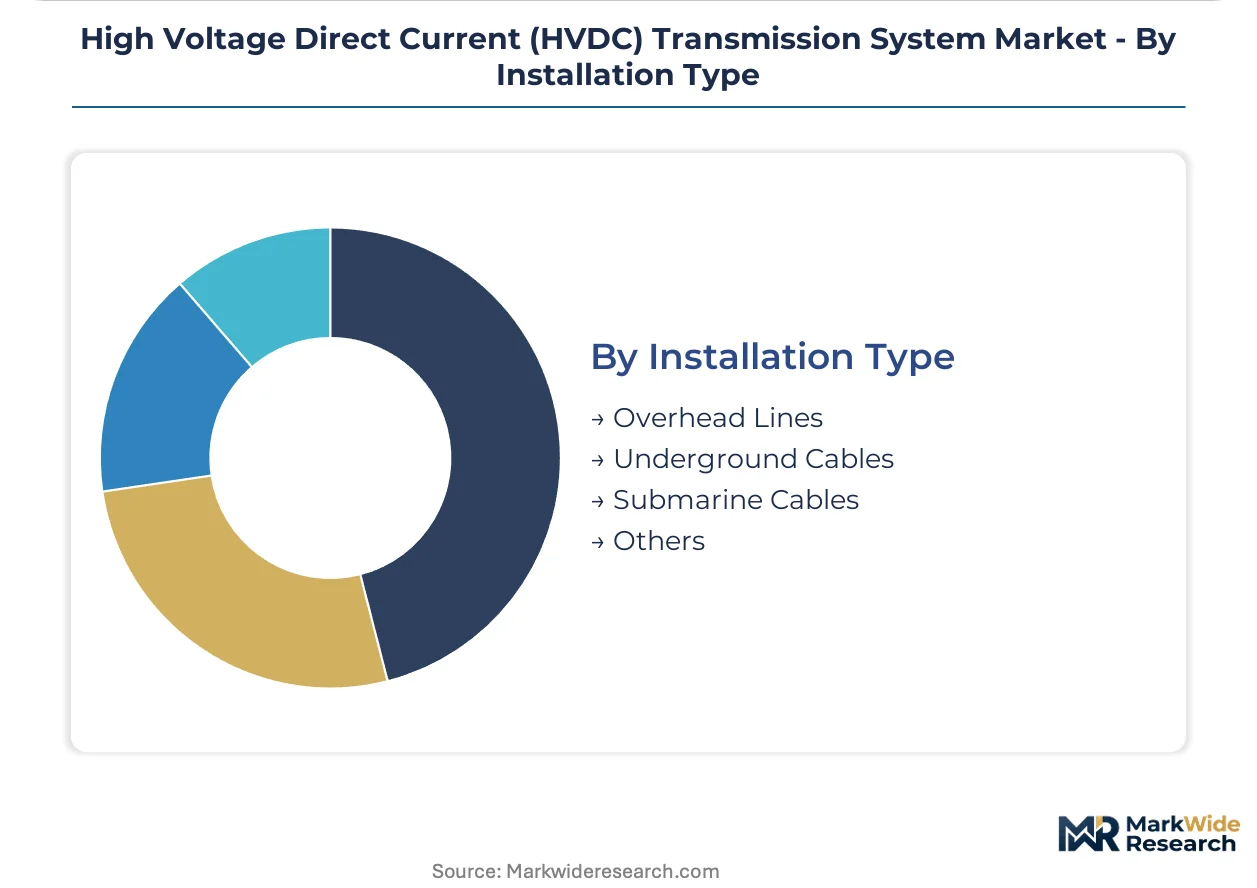
Technology selection in HVDC systems locks in decades of operational characteristics and maintenance protocols. Converter architecture determines grid code compliance, black-start capability, and reactive power management. Installation type drives capital intensity and permitting complexity across continental corridors and offshore environments.
Technology:
Cycle times diverge sharply: voltage source converter platforms refresh every 8-12 years with semiconductor upgrades, while line commutated converter installations operate 25-30 years between major overhauls.
- Voltage Source Converter:Insulated-gate bipolar transistor switching enables independent active and reactive power control. Germany's North Sea offshore wind corridors specify VSC for black-start mandates in grid codes. Modular multilevel converter architectures are displacing traditional two-level designs in new project awards.
- Line Commutated Converter:Thyristor-based technology dominates existing installed base above 800 kV ratings. China's State Grid Corporation maintains LCC preference for continental-scale UHVDC corridors where capital cost sensitivity outweighs grid code flexibility requirements.
- Hybrid Converter:Combines LCC bulk power economics with VSC terminal flexibility for complex multi-terminal networks.
- Others:Experimental resonant converter topologies remain confined to pilot installations.
Line commutated converter dominates installed base. Voltage source converter is where expansion concentrates.
Application:
Cost tiers separate applications by capital intensity per megawatt and revenue model certainty.
- Renewable Energy Integration:Submarine cable links from offshore wind farms to onshore substations. Germany's Federal Network Agency and Denmark's Energinet coordinate joint network planning for North Sea and Baltic Sea corridors. Merchant risk allocation differs from regulated utility returns.
- Long-Distance Transmission:Overhead lines spanning 600+ kilometers where AC losses become prohibitive. China's western-to-eastern UHVDC corridors demonstrate this application at scale.
- Grid Interconnection:Cross-border links enabling power trading and resource sharing. REPowerEU framework accelerates permitting timelines for Baltic and North Sea interconnectors.
- Industrial Applications:Direct current supply to aluminum smelters and electrochemical plants bypasses AC conversion losses.
Grid interconnection carries the highest regulatory complexity. Renewable energy integration is climbing the fastest.
End User:
Customer type determines procurement sophistication, financing structure, and service contract unbundling preferences.
- Utilities:Transmission system operators with regulated cost recovery and standardized technical specifications. Energinet's contract templates now separate availability guarantees from construction milestones.
- Renewable Energy Operators:Offshore wind developers procuring HVDC export capacity as part of lease commitments. Ørsted and RWE negotiate long-term service agreements through competitive tender.
- Industrial Manufacturers:Large electrochemical and metallurgical facilities seeking direct current coupling.
- Government Agencies:National energy administrations setting corridor standards and cross-border coordination frameworks.
Utilities control legacy asset base. Renewable energy operators are driving new order intake.
Installation Type:
Supply concentration varies by installation complexity and specialized equipment requirements.
- Submarine Cables:Deep-water installation requires specialized vessel fleets limited to three European and Asian suppliers. Prysmian Group dominates supply for offshore wind interconnectors in the German Bight and Baltic Sea.
- Overhead Lines:Conventional tower construction with established contractor networks. Maintains largest installed base across continental corridors in China and India.
- Underground Cables:Urban and environmentally constrained corridors where overhead routing is prohibited.
- Others:Gas-insulated lines and superconducting links remain niche.
Overhead lines dominate installed base. Submarine cables are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import electricity imbalances are reshaping corridor investments across major economies. Nations with surplus renewable generation seek long-distance transmission to demand centers. Submarine cable procurement concentrates where offshore wind leasing accelerates.
Germany
North Sea offshore wind leasing rounds mandate HVDC export capacity for developers. The Federal Network Agency coordinates joint network planning with Denmark's Energinet under REPowerEU timelines. Converter station fabrication clusters in Lower Saxony and Hamburg port zones.
China
Western-to-eastern UHVDC corridors move surplus solar and wind from Xinjiang and Gansu to coastal load centers. The National Energy Administration sets domestic standards that influence global equipment specifications. State Grid Corporation anchors manufacturing in Shandong and Jiangsu provinces.
United States
Bureau of Ocean Energy Management lease areas lack interconnection infrastructure for planned Atlantic coast offshore capacity. FERC Order 1000 compliance requirements shape merchant transmission proposals. Converter assembly concentrates in Texas and the Northeast Corridor.
Denmark
Energinet's standard contract templates separate availability guarantees from construction milestones. Baltic Sea interconnectors to Germany and Poland advance under accelerated permitting frameworks. Cable landing facilities cluster on Jutland's west coast.
Japan
METI's grid reinforcement roadmap specifies voltage source converter standards for Hokkaido-Honshu inter-island links. Submarine cable procurement targets 2040 carbon neutrality deadlines. Manufacturing partnerships concentrate in Nagoya and Osaka industrial zones.
High Voltage Direct Current (HVDC) Transmission System Market Competitive Landscape
On the supply side, the industry is consolidating around firms with integrated converter and cable capabilities. Project finance requirements favor balance-sheet depth over pure technology plays. Two archetypes dominate: full-system integrators and specialized component suppliers. Strategic moves center on submarine cable vessel fleet expansion and modular multilevel converter licensing partnerships.
Among European-headquartered system integrators, Siemens Energy and Hitachi Energy Ltd occupy positions spanning converter stations and grid integration services. Prysmian Group anchors the specialized cable fabrication tier with deep-water installation assets. These three exemplify the capital intensity barriers that compress viable bidder pools for large-scale offshore wind interconnectors.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy Ltd |
| Mitsubishi Electric Corporation |
| GE Vernova |
| Prysmian Group |
| Toshiba Energy Systems & Solutions Corporation |
| NKT A/S |
| LS Electric Co., Ltd. |
| TBEA Co., Ltd. |
| Others |
Supply & Pricing Matrix
Shandong province's converter station fabrication clusters anchor global HVDC equipment capacity, with State Grid Corporation's procurement scale translating directly into pricing leverage for domestic suppliers and cost pressure on European and Japanese competitors bidding for offshore wind interconnectors in the German Bight.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures with long-term offtake agreements spanning converter stations and submarine cable bundles. Price differentiation rests on voltage rating certification and black-start capability compliance, with VSC platforms commanding premiums over LCC alternatives. Cost compression in the 800 kV and above segment is intensifying because China's UHVDC corridor standardization drives equipment commoditization. Renewable energy operators exhibit highest price sensitivity due to merchant risk exposure, while regulated utilities absorb premiums for grid code compliance.
Supply Chain Analysis
Copper cathode and rare earth oxide feedstock draws from Chilean mining operations and Chinese processing refineries concentrated in Inner Mongolia and Jiangxi province. Insulated-gate bipolar transistor modules hinge on semiconductor substrate supply from Taiwanese foundries and South Korean packaging houses. Single-source vulnerability runs through deep-water cable installation vessels limited to three European and Asian operators. Distribution runs through EPC contractors and transmission system operators with unbundled procurement of construction and long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC incumbents face substitution pressure from emerging high-voltage alternating current solutions with advanced reactive power compensation, requiring defensive positioning around converter technology lock-in and submarine cable installation asset control.
For Market Incumbents: Build regulatory certification moats through early engagement with Germany's Federal Network Agency and Denmark's Energinet on evolving grid code requirements for inertia provision. Deepen backward integration into IGBT module supply through partnerships with Taiwanese semiconductor foundries to offset Chinese rare earth processing concentration. Counter emerging entrants from industrial automation sectors by controlling cable landing facility access along the North Sea corridor. For New Entrants and Emerging Players: Build out specialized maintenance and digital twin services for existing LCC installations approaching mid-life overhaul cycles, where incumbent OEMs have deprioritized service intensity. Target the United States Atlantic coast interconnection gap ahead of Bureau of Ocean Energy Management lease round infrastructure requirements. Pursue joint development agreements with offshore wind developers lacking in-house HVDC procurement expertise as the primary go-to-market pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular multilevel converter licensing specialists with intellectual property portfolios transferable across voltage source converter and hybrid converter architectures. Long-term viability centers on firms with demonstrated project execution in submarine cable installation rather than pure converter hardware manufacturing. Watch for inflection signals in FERC Order 1000 compliance acceleration for Atlantic coast merchant transmission proposals.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Vessel Fleet Expansion | Deep-water installation capacity constraints in the Baltic Sea and German Bight favor early movers with chartered heavy-lift assets. |
| Modular Multilevel Converter Licensing | Technology partnerships with Siemens Energy or Hitachi Energy Ltd accelerate grid code compliance for black-start mandates. |
| Long-term Service Agreement Unbundling | Ørsted and RWE's separated procurement of availability guarantees creates standalone revenue pools for specialized service providers. |
| Green Hydrogen Electrolyzer Co-location | Direct current coupling bypasses AC conversion losses for industrial loads adjacent to HVDC terminal stations. |
| EU F-Gas Regulation Compliance Investment | Fluoronitrile-based switchgear development maintains project eligibility for North Sea and Baltic Sea corridor awards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and equipment procurement records. Interviews with transmission system planning officers, offshore wind project developers, EPC contractor procurement leads, and converter station commissioning engineers informed demand-side assumptions. Secondary validation drew from FERC interconnection queue data, EIA electric power surveys, IEA transmission investment trackers, and national energy administration corridor planning documents. Bottom-up project pipeline aggregation was cross-checked against top-down transmission capacity expansion targets across the analysis window.
Forecast inputs incorporate converter technology substitution rates, submarine cable installation vessel utilization, and grid code evolution timelines. Segmentation modeling spans voltage source converter versus line commutated converter technology, renewable energy integration versus grid interconnection application, and submarine cable versus overhead line installation type. CAGRs were derived from weighted project award pipelines and capacity expansion announcements. Industry-specific inputs include REPowerEU permitting acceleration schedules and China's UHVDC corridor commissioning cadence.
Stress conditions across copper and rare earth price volatility, semiconductor substrate supply disruption, and offshore wind lease round delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition timing and regulatory framework stability. Cross-checking against IEA and national transmission system operator investment disclosure is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
DC Distribution Network Market