
 Posterior Chamber Lens Market | 2026-2036
Posterior Chamber Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Posterior Chamber Lens Market Analytics
Foldable hydrophobic acrylic material is tilting manufacturing priorities toward thinner optic profiles and enhanced uveal biocompatibility. Alcon Inc. leverages its vertically integrated acrylic supply chain to control material consistency across production batches. Johnson & Johnson Vision Care, Inc. anchors its competitive stance through sustained R&D spending on diffractive optic platforms. STAAR Surgical Company specializes in silicone-based designs that compete in niche refractive correction segments.
Posterior chamber lenses are implantable optical devices positioned behind the iris within the capsular bag, typically measuring 5.5–6.5 mm in optic diameter and 10–13 mm in haptic span, manufactured through precision lathe-cutting or cast-molding of medical-grade polymers to restore refractive power after natural lens extraction. Monofocal designs still occupy the largest volume share due to established reimbursement pathways, while extended depth of focus platforms capture expanding margin pools as out-of-pocket payment tolerance rises among presbyopic candidates. Toric segments demonstrate the fastest structural growth where astigmatism correction integrates into standard surgical workflows, particularly in eye clinics and surgical centers adopting wavefront-guided biometric planning.
FDA premarket approval requirements and EMA Medical Device Regulation (MDR) compliance frameworks enforce rigorous clinical evidence standards for optical performance and posterior capsule opacification rates, effectively filtering market access for newer entrants. CE marking under the EU MDR and ISO 11979 biocompatibility testing protocols further stratify competitive positioning between established manufacturers and emerging suppliers. Stakeholders must monitor how laser-assisted surgical techniques reshape preoperative measurement precision and postoperative lens selection protocols.
Market Dynamics
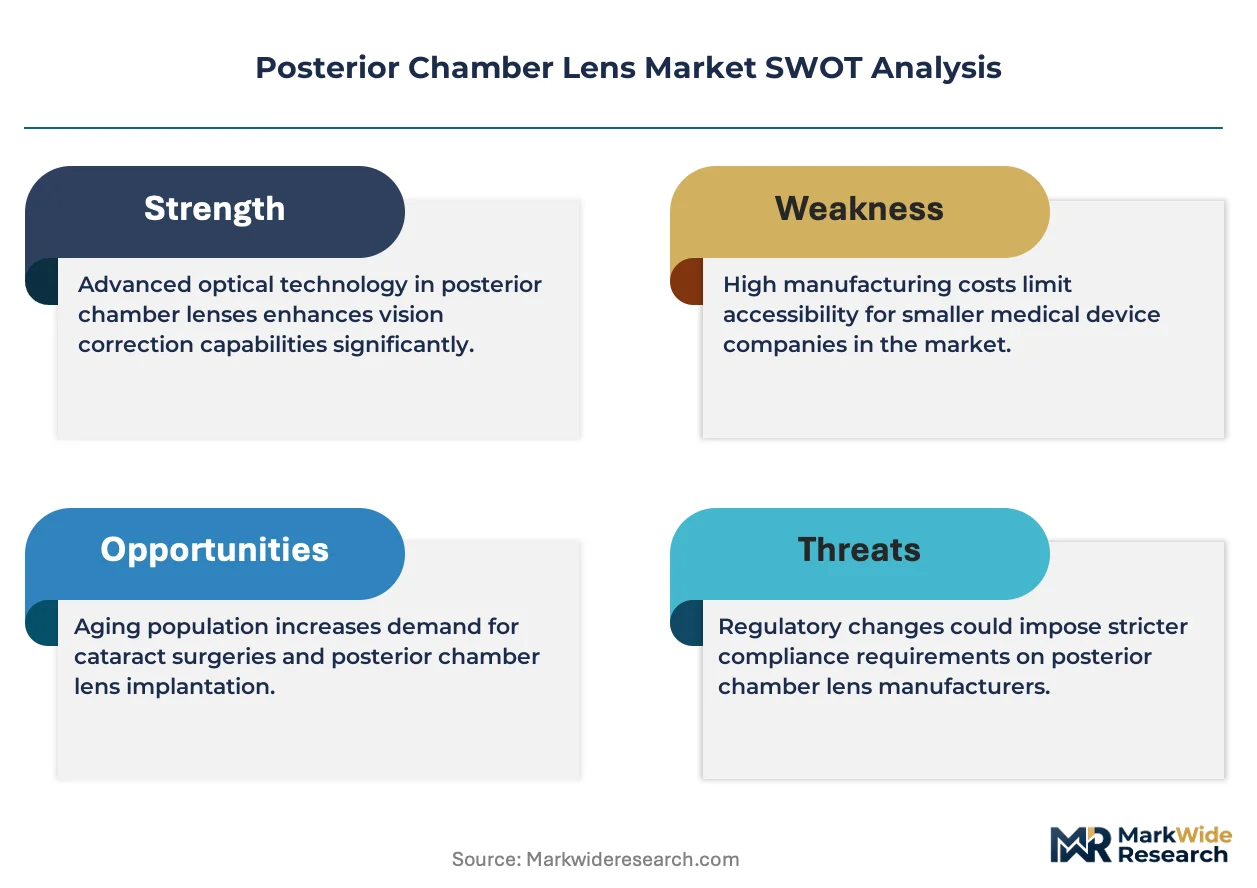
Foldable hydrophobic acrylic material is compressing manufacturing cycles while FDA and EMA biocompatibility protocols extend clinical validation timelines, creating tension between speed-to-market and safety assurance in posterior chamber lens development.
Growth Catalysts
- Aging surgical populations:Expanding Medicare-eligible cohorts in the United States sustain procedural volumes for cataract extraction and IOL implantation.
- EU MDR harmonization:Centralized CE marking under Medical Device Regulation streamlines multi-country market access for compliant manufacturers.
- Wavefront-guided biometry:Preoperative measurement precision enables toric and extended depth of focus lens customization at the point of surgical planning.
Market Restraints
- Acrylic monomer supply concentration:Limited qualified polymer suppliers create input cost volatility and batch consistency risks for optic manufacturing.
- ISO 11979 testing duration:Biocompatibility and optical performance validation protocols extend product development timelines by months.
- Monofocal reimbursement ceilings:Established Medicare payment categories cap revenue potential for standard lens categories despite volume scale.
Strategic Opportunities
- Indian outpatient surgical networks:Private eye hospital chains in Maharashtra and Tamil Nadu expand premium lens access beyond metropolitan centers.
- Femtosecond laser convergence:Integration of laser-assisted capsulotomy with biometric planning creates bundled procedural value.
- Direct-to-clinic distribution:Manufacturer-authorized inventory programs bypass traditional distributor markups for high-volume surgical centers.
Industry Challenges
- Optical engineer scarcity:Specialized expertise in diffractive optic design remains concentrated among a limited pool of trained professionals.
- Legacy phacoemulsification system compatibility:New lens insertion systems require adaptation workflows for installed base surgical platforms.
- Posterior capsule opacification litigation exposure:Long-term optical performance claims create product liability monitoring costs across installed patient bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Posterior Chamber Lens Market |
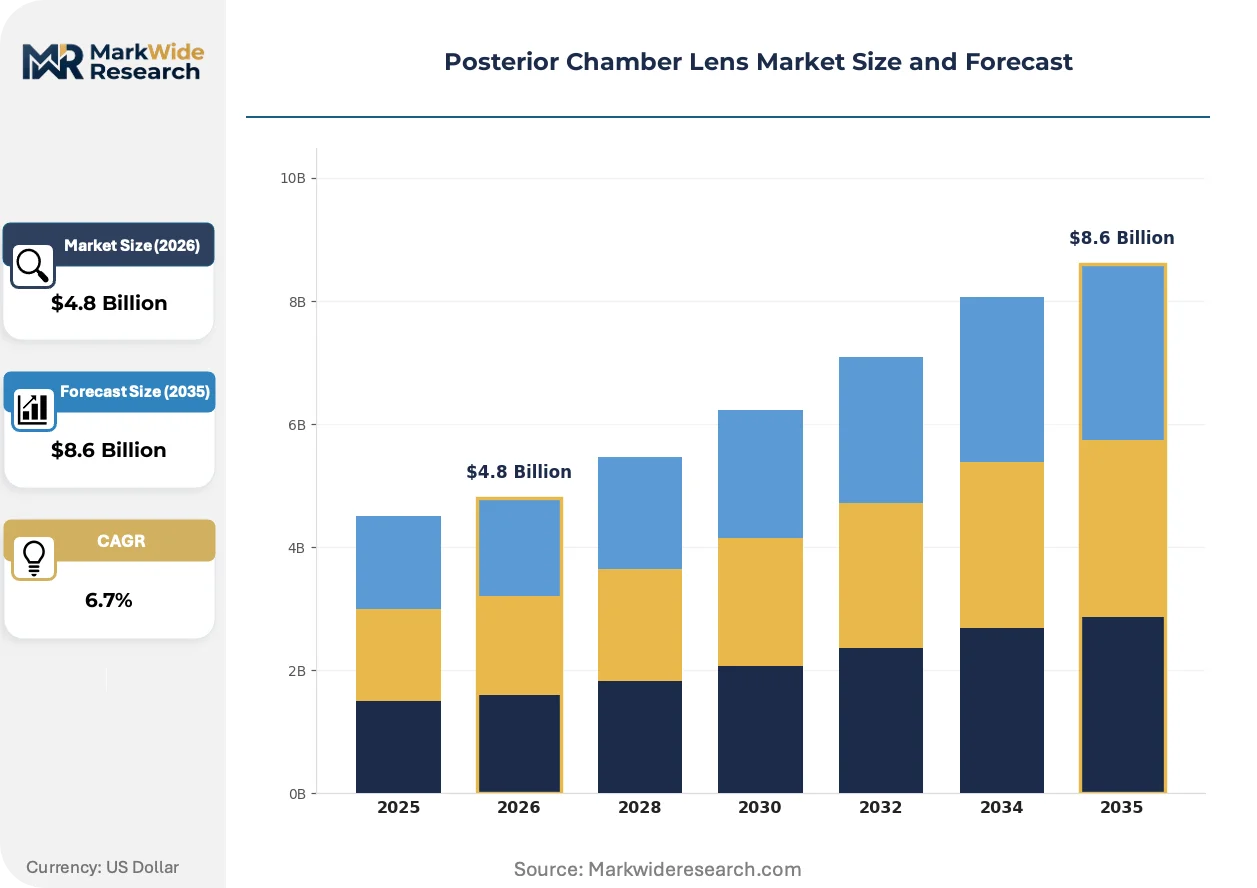
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Extended Depth of Focus Application: Cataract Surgery, Refractive Surgery, Corrective Procedures, Pediatric Applications End User: Hospitals, Eye Clinics, Surgical Centers, Private Practices Technology: Wavefront Technology, Computer-assisted Design, Biometric Measurement, Laser-assisted Techniques |
| Companies Covered | Alcon Inc., Johnson & Johnson Vision Care, Inc., Bausch & Lomb Incorporated, Carl Zeiss Meditec AG, Hoya Corporation, Rayner Intraocular Lenses Limited, Lenstec, Inc., PhysIOL SA, STAAR Surgical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Posterior Chamber Lens Market Evolving Landscape
Digital surgical planning platforms are rewriting preoperative measurement protocols, while material science advances and regulatory data requirements reshape how posterior chamber lenses reach ophthalmic surgeons.
Extended depth of focus optic platforms are virtualizing the traditional monofocal-pseudophakic vision correction tradeoff. Premium surgical centers in Germany and Japan adopt these designs for presbyopic patients seeking reduced spectacle dependence. The technology is virtualizing conventional segmentation between standard reimbursed lenses and out-of-pocket refractive options.
EMA Medical Device Regulation post-market surveillance requirements now mandate systematic clinical follow-up data collection from implanted patients. Manufacturers must establish quality management systems capable of traceability across distributed surgical sites. European ophthalmology clinics are restructuring informed consent protocols to accommodate longitudinal outcome tracking obligations.
Patient self-pay tolerance for astigmatism-correcting toric designs is compressing traditional reimbursement-dependent purchasing patterns. Independent ambulatory surgical centers in Texas and Florida now stock expanded toric inventories based on preoperative corneal topography prevalence rather than insurance preauthorization rates. This behavioral shift is most visible in metropolitan markets where direct consumer marketing drives procedure volume.
Posterior Chamber Lens Market Segmentation
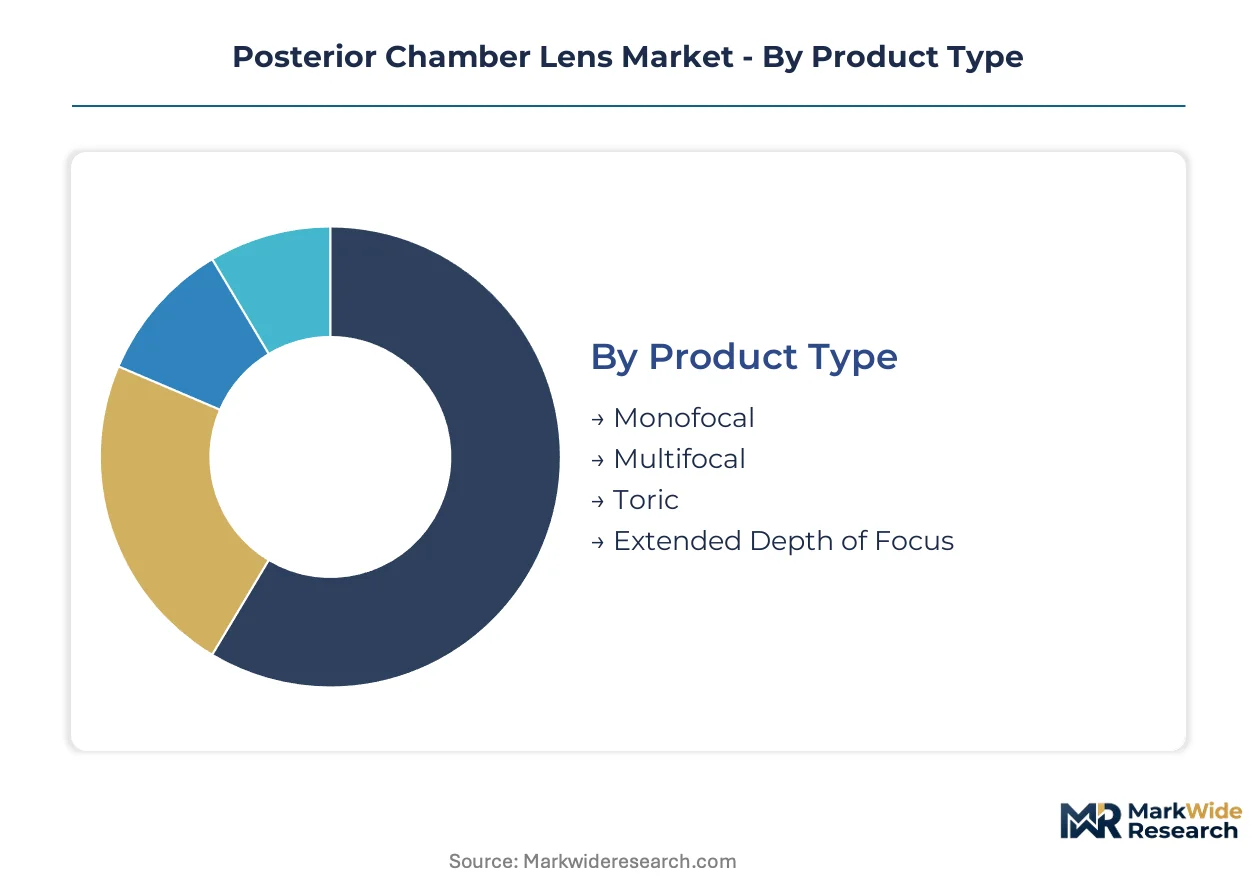
Posterior chamber lens segmentation reveals how surgical workflow specialization, reimbursement structures, and optical engineering complexity fragment demand across distinct customer and technology categories. Each dimension carries implications for pricing power, regulatory pathway, and distribution channel design.
Product Type:
Clinical use-cases span vision correction goals from basic post-cataract refractive power restoration to presbyopia management and astigmatism correction.
- Monofocal:Single-focus optic design manufactured from hydrophobic acrylic or silicone materials for standard distance vision correction. Medicare reimbursement pathways in the United States sustain procedural volumes across hospital outpatient departments and ambulatory surgical centers, though payment ceilings compress margin expansion.
- Extended Depth of Focus:Diffractive or refractive optic engineering extends the range of functional vision without discrete focal points. Patient self-pay tolerance in Germany and Japan drives adoption among presbyopic candidates seeking reduced spectacle dependence, with premium pricing outside standard reimbursement categories.
- Multifocal:Segmented optic surfaces provide discrete near and distance focal zones through refractive or diffractive principles.
- Toric:Cylindrical power correction integrated into the optic platform addresses pre-existing corneal astigmatism at the point of implantation.
Established volume favors monofocal designs; emerging adoption favors extended depth of focus platforms.
Application:
Cost tiers separate high-volume reimbursed procedures from out-of-pocket refractive corrections and specialized pediatric interventions.
- Cataract Surgery:Lens extraction with IOL implantation represents the dominant procedural channel, driven by aging demographics and established clinical pathways. FDA premarket approval requirements and Medicare payment structures in the United States create predictable demand volumes with defined reimbursement ceilings.
- Refractive Surgery:Clear lens extraction or phakic IOL procedures target presbyopic or high-myopic patients outside cataract indications. Private payment models in Spain and South Korea enable premium lens selection unconstrained by government pricing schedules.
- Corrective Procedures:Secondary IOL implantation or lens exchange addresses complications or refractive surprises from prior surgery.
- Pediatric Applications:Congenital cataract extraction with primary or secondary IOL placement requires specialized sizing and biocompatibility protocols.
Reimbursed volume concentrates in cataract surgery; margin expansion concentrates in refractive applications.
End User:
Customer type determines procurement scale, inventory turnover, and direct-to-manufacturer relationship potential.
- Eye Clinics:Specialized ophthalmology practices with integrated surgical suites capture high toric and extended depth of focus adoption. Wavefront-guided biometric planning capabilities in Texas and Florida metropolitan markets enable premium lens customization at the point of care.
- Surgical Centers:Ambulatory facilities optimize throughput through standardized monofocal protocols with selective premium upsells. Direct-to-clinic distribution programs from manufacturers reduce working capital requirements for high-volume operators.
- Hospitals:Academic medical centers and community hospital systems manage mixed payer populations with diverse lens portfolios.
- Private Practices:Solo and small-group ophthalmologists rely on distributor relationships for inventory access and consignment arrangements.
Procurement scale favors surgical centers; technology adoption velocity favors eye clinics.
Technology:
Supply concentration in measurement and manufacturing systems creates vendor lock-in and interoperability constraints.
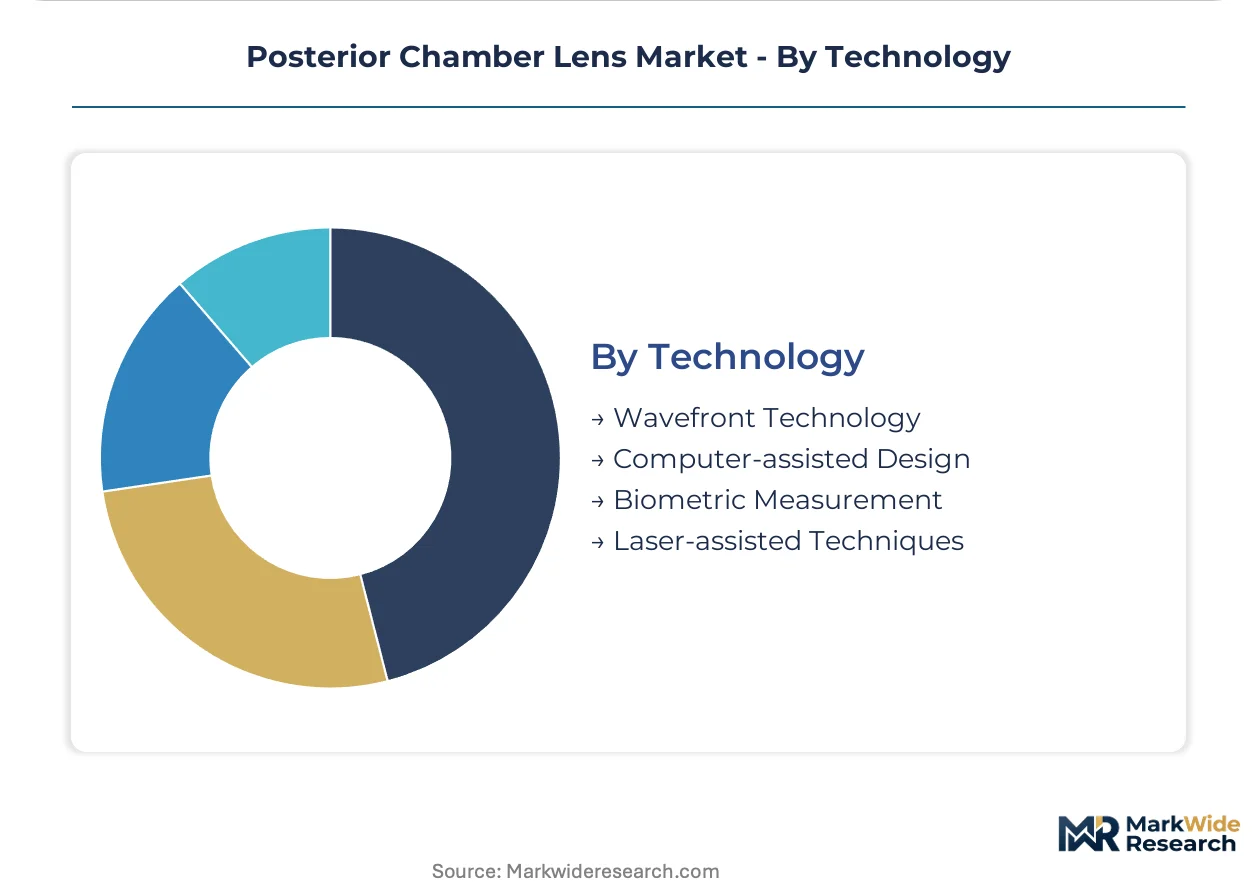
- Wavefront Technology:Aberrometry-based preoperative assessment maps higher-order optical imperfections to guide toric alignment and extended depth of focus candidate selection. Integration with femtosecond laser platforms in Japanese university hospitals creates bundled procedural value and device ecosystem loyalty.
- Biometric Measurement:Optical coherence tomography and partial coherence interferometry deliver axial length and anterior chamber depth precision for IOL power calculation. IOLMaster and Lenstar device penetration across French and Italian clinic networks standardizes measurement protocols.
- Computer-assisted Design:Digital modeling of optic geometry and haptic configuration enables patient-specific lens customization.
- Laser-assisted Techniques:Femtosecond laser capsulotomy and lens fragmentation integrate with lens insertion workflows.
Measurement standardization favors biometric systems; surgical integration favors laser-assisted platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision optic components to surgical centers across France and the Netherlands, while the United States ships finished hydrophobic acrylic lenses to Canadian and Mexican eye clinic networks. This trade-flow pattern concentrates manufacturing expertise in established polymer processing hubs while distributing finished devices through regional distribution partnerships.
United States
Medicare-eligible surgical volumes and direct-to-clinic distribution programs sustain demand for toric and extended depth of focus platforms. FDA premarket approval requirements enforce biocompatibility validation timelines that filter market access for newer suppliers. Metropolitan surgical centers in Texas and Florida deploy wavefront-guided biometric planning to enable premium lens customization at the point of care.
Germany
Presbyopic patient self-pay tolerance and university hospital adoption of femtosecond laser platforms drive extended depth of focus lens volumes. EMA Medical Device Regulation post-market surveillance mandates systematic clinical follow-up data collection from implanted patients. Precision optic manufacturing clusters in Baden-Württemberg supply hydrophobic acrylic components to French and Italian surgical networks.
Japan
Aging demographics and private ophthalmology clinic expansion sustain procedural volumes for multifocal and toric designs. PMDA regulatory frameworks require optical performance documentation and posterior capsule opacification rate submissions for market authorization. University hospitals in the Kanto region integrate laser-assisted capsulotomy with biometric planning for bundled procedural value.
India
Private eye hospital chains in Maharashtra and Tamil Nadu expand premium lens access beyond metropolitan centers through outpatient surgical networks. CDSCO medical device registration requirements govern import and local manufacturing compliance for optic biocompatibility standards. Chennai and Mumbai surgical hubs adopt toric inventory protocols based on preoperative corneal topography prevalence rather than insurance preauthorization rates.
France
Public hospital procurement consolidation and ambulatory surgical center expansion create volume concentration for monofocal and standard toric categories. ANSM post-market vigilance requirements align with EU MDR traceability obligations for implanted optical devices. IOLMaster and Lenstar device penetration across clinic networks in Île-de-France standardizes preoperative measurement protocols.
Posterior Chamber Lens Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. The vendor base concentrates around multinational polymer processors with captive acrylic supply chains, mid-scale optic designers with diffractive platform specialization, and regional fabricators serving price-sensitive procurement channels. Three strategic archetypes dominate: vertically integrated material-to-device manufacturers, R&D-intensive optic engineering specialists, and distribution-anchored regional suppliers. Competitive moves center on backward integration into polymer supply and direct-to-clinic inventory programs that bypass traditional distributor markups.
Among the vertically integrated tier, Alcon Inc. and Johnson & Johnson Vision Care, Inc. occupy positions defined by material supply control and sustained platform development investment. STAAR Surgical Company sits within the specialization archetype, with its corporate designation indicating focused engagement on distinct refractive correction segments. These three entities exemplify how competitive positioning stratifies between scale-driven channel control and technology-driven product differentiation in posterior chamber lens supply.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson & Johnson Vision Care, Inc. |
| Bausch & Lomb Incorporated |
| Carl Zeiss Meditec AG |
| Hoya Corporation |
| Rayner Intraocular Lenses Limited |
| Lenstec, Inc. |
| PhysIOL SA |
| STAAR Surgical Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in German hydrophobic acrylic polymer production is compressing input costs while simultaneously enabling tiered pricing flexibility for finished lens manufacturers serving Medicare-constrained and premium self-pay segments.
Pricing Analysis
Cost-plus contracts with phenoxyethyl acrylate monomer indexation dominate procurement between lens manufacturers and polymer suppliers. Three-tier pricing structure across premium extended depth of focus, standard toric, and economy monofocal levels separates patient self-pay tolerance from reimbursement ceilings. Cost compression in monofocal tiers is intensifying because Medicare payment categories cap revenue potential despite procedural volume scale. Ambulatory surgical centers exhibit highest price sensitivity due to throughput-dependent margin structures, while metropolitan eye clinics with wavefront-guided biometric capabilities demonstrate lowest sensitivity.
Supply Chain Analysis
Upstream phenoxyethyl acrylate and silicone elastomer feedstock production concentrates in Germany, Japan, and the United States. Finished lens manufacturing draws from medical-grade polymer resins, precision lathe-cutting equipment, and diffractive optic design software. Single-source vulnerability in qualified acrylic monomer suppliers creates batch consistency risks and input cost volatility. Distribution runs through manufacturer-authorized inventory programs that bypass traditional distributor markups for high-volume surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as femtosecond laser-assisted refractive procedures capture presbyopic patients who might otherwise select premium intraocular lenses.
For Market Incumbents: Insulate market position through backward integration into hydrophobic acrylic polymer supply and captive diffractive optic engineering capabilities. Secure FDA premarket approval pathways for extended depth of focus platforms before EMA MDR post-market surveillance requirements harden. Prioritize direct-to-clinic distribution programs that lock in high-volume ambulatory surgical center relationships against emerging regional fabricators. For New Entrants and Emerging Players: Mid-market eye clinic networks in Maharashtra and Tamil Nadu represent the most penetrable entry point, where corneal topography-guided toric adoption outpaces insurance preauthorization infrastructure. Refractive surgery centers in Spain and South Korea offer secondary white-space for phakic IOL and clear lens extraction procedures outside cataract reimbursement constraints. Pursue CDSCO registration partnerships with Chennai-based surgical hubs to establish regulatory credibility for pan-Indian expansion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated material-to-device manufacturers with captive acrylic supply chains and sustained R&D investment in diffractive platforms. Long-term viability across the analysis window favors acquisition targets with FDA premarket approval portfolios and established EU MDR quality management systems. Watch femtosecond laser platform bundling rates as the inflection indicator for premium lens displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Biocompatibility validation timelines filter market access for optical performance claims. |
| CE Marking Under EU MDR | Post-market surveillance mandates reshape quality management system investments. |
| Hospital System Partnership | Direct-to-clinic inventory programs reduce working capital for high-volume operators. |
| Software Companion Development | Wavefront-guided biometric planning integration enables toric customization at point of care. |
| Reimbursement Strategy | Medicare payment category navigation determines monofocal volume versus premium margin capture. |
Research Methodology
A spread of perspectives from cataract surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers converged on the working assumptions for procedural volume and premium lens adoption rates. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, CMS Medicare payment schedules, and hospital procurement databases. Bottom-up surgical volume estimates and top-down polymer consumption data triangulated on market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application channel, end-user procurement scale, and technology integration level. CAGRs derived from surgical demographic projections, reimbursement trajectory assumptions, and premium lens penetration curves. Forecast inputs incorporated aging population eligibility expansion and femtosecond laser platform adoption rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, EU MDR compliance costs, or acrylic monomer pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway durations and patient self-pay tolerance thresholds. Cross-checking against CMS procedural volume benchmarks and EMA medical device registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Suction Catheters Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
External Pacemakers Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market