
 United Kingdom Foodservice Market | 2026-2036
United Kingdom Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Foodservice Market Analytics
Foodservice distribution in the United Kingdom is fragmenting as digital intermediaries, dark kitchens, and direct-to-consumer apps compete for the same meal occasions. McDonald's Corporation sustains its position through extensive real estate control and drive-thru infrastructure across British motorways and retail parks. Deliveroo competes by embedding logistics technology into neighbourhood-level delivery radius optimisation. Whitbread PLC anchors the mid-market hotel and restaurant segment through its Premier Inn and Beefeater estate, giving it predictable institutional catering volumes.
United Kingdom foodservice encompasses the preparation, sale, and delivery of meals and beverages through commercial outlets ranging from Michelin-starred kitchens to automated vending systems, with operational parameters governed by Food Standards Agency hygiene ratings, allergen management protocols, and temperature-controlled supply chains. The sector's primary purpose is to convert agricultural and processed inputs into consumed meals outside the domestic kitchen, serving time-constrained consumers, corporate clients, and tourists. Quick Service Restaurants dominate volume throughput in the service type dimension, while online delivery captures the fastest expansion within distribution channels as platform economics reshape last-mile economics. Premium and luxury price tiers concentrate margin pools in London's West End and Mayfair districts, where experiential dining commands discretionary spend from business groups and international visitors.
The Food Standards Agency enforces hygiene ratings that determine consumer trust and local authority licensing across England, Wales, and Northern Ireland. The UK government's HFSS regulations restrict promotional placement of high-fat, salt, and sugar products in large retail and foodservice settings, compelling reformulation and menu architecture changes. Stakeholders must monitor how evolving UK border inspection posts and post-EU sanitary rules reshape ingredient sourcing costs and supplier qualification requirements for imported produce.
Market Dynamics
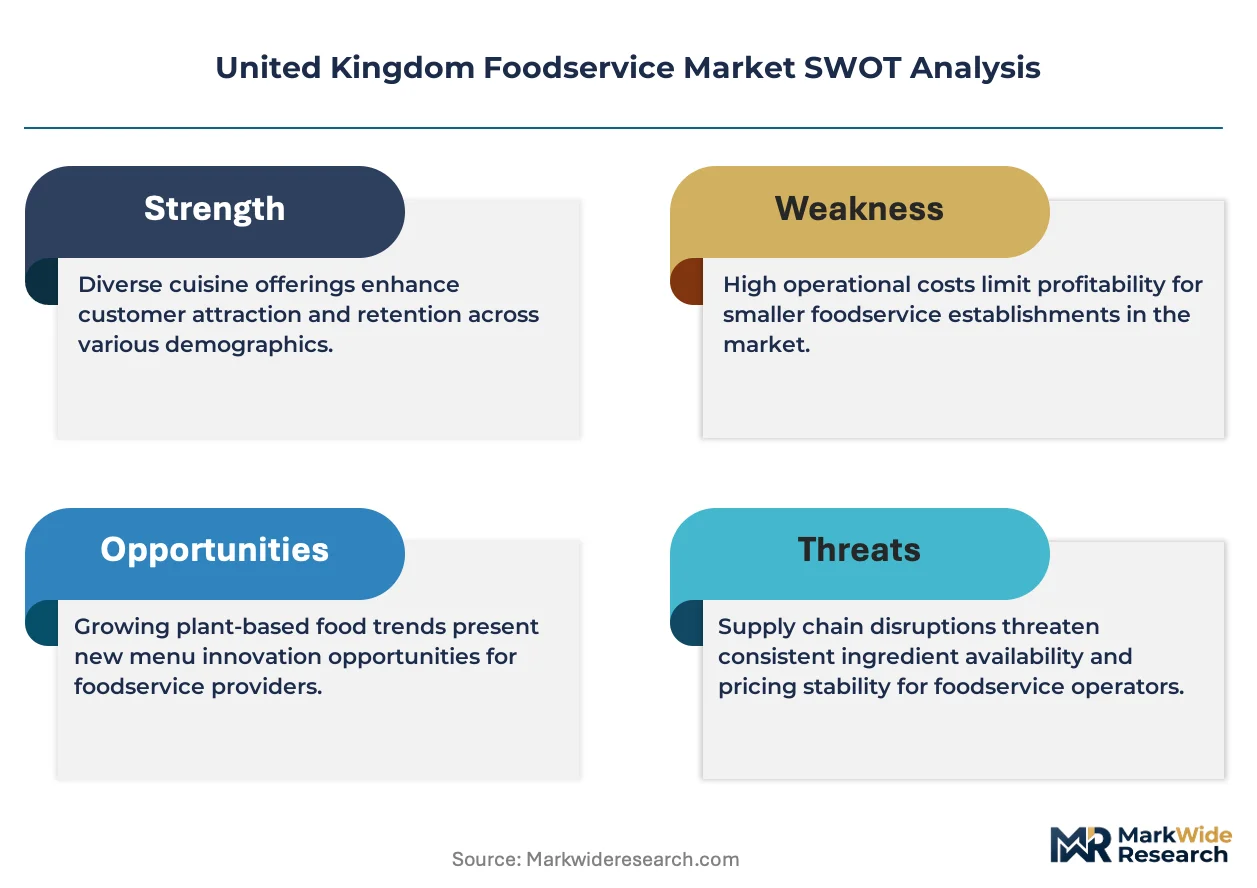
Platform economics are compressing last-mile delivery margins while calorie labeling mandates and HFSS advertising restrictions force simultaneous menu reformulation and marketing architecture changes across British foodservice operations.
Growth Catalysts
- Dark kitchen infrastructure:Cloud-based production facilities eliminate front-of-house capex and enable rapid market testing across Greater London postcodes without property acquisition cycles.
- Corporate catering contracts:High-density employment zones in the South East corridor generate predictable institutional volumes through multi-year service agreements with technology and financial services firms.
- Food Standards Agency hygiene ratings:Transparent scoring systems create consumer trust differentials that drive footfall toward five-rated establishments in competitive high streets.
Market Restraints
- Imported produce qualification costs:Post-EU sanitary rules at UK border inspection posts extend supplier onboarding timelines and raise compliance expenditure for continental European ingredient sourcing.
- Labour market tightness:Visa regime changes constrain access to EU hospitality workers, compressing kitchen and front-of-house staffing ratios across independent restaurants.
- Energy price volatility:Commercial gas and electricity tariffs expose high-throughput quick service operators to margin erosion during cold-peak heating and refrigeration demand periods.
Strategic Opportunities
- Suburban delivery radius expansion:Secondary urban centres in the Midlands and North West exhibit lower platform commission density and higher average order values for family-oriented meal occasions.
- Automated vending integration:Temperature-controlled smart lockers and robotic preparation stations address 24-hour consumption windows in transport hubs and healthcare campuses.
- HFSS reformulation incentives:Government technical support programmes for recipe modification create first-mover advantage in compliant product ranges ahead of promotional placement restrictions.
Industry Challenges
- Allergen management protocols:Natasha's Law implementation demands real-time ingredient traceability systems and staff training cadences that strain smaller operator IT budgets.
- Legacy POS integration:Third-party delivery platform APIs conflict with established property management and stock control systems, requiring middleware development or full-stack replacement.
- Temperature-controlled supply chain reconfiguration:Multi-drop consolidation across fragmented distributor networks raises spoilage risk and complicates just-in-time fresh produce scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Foodservice Market |
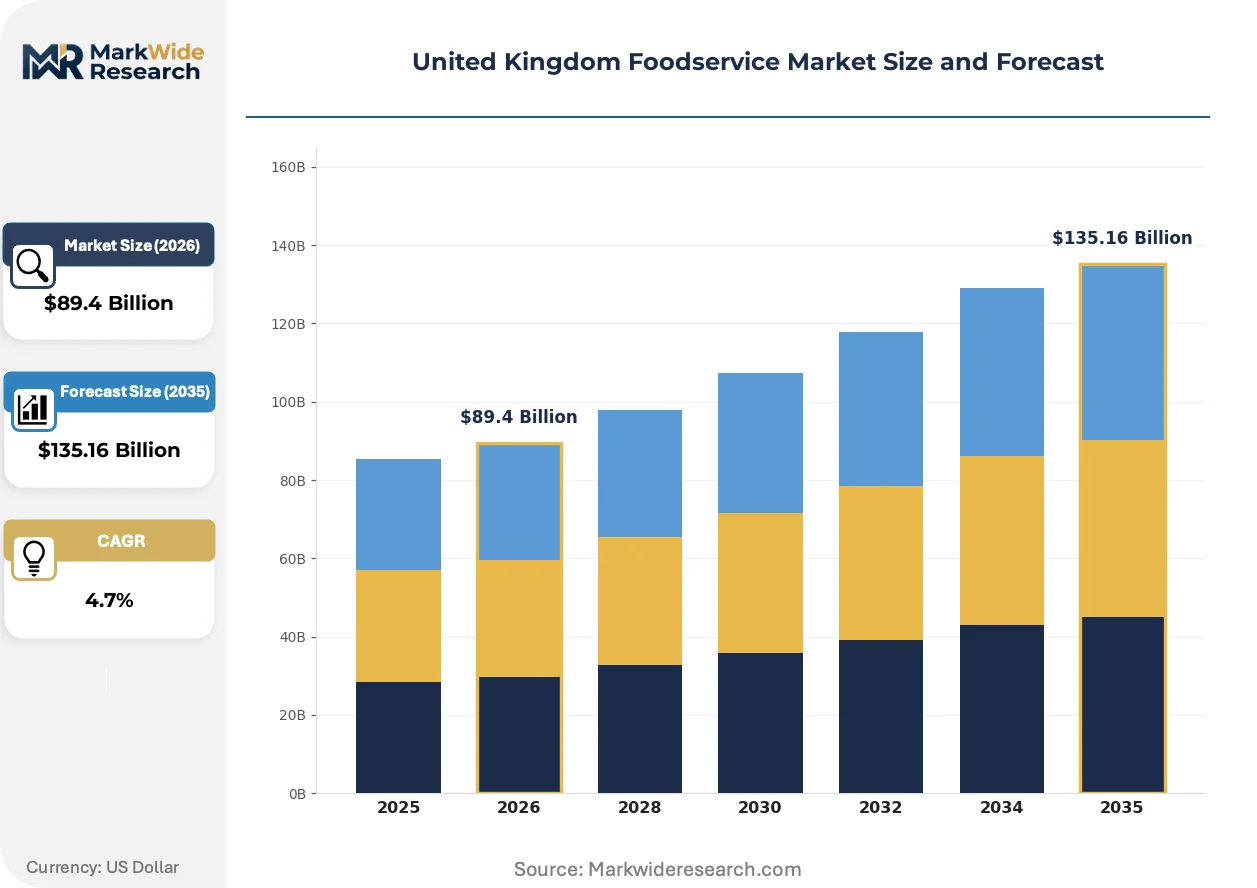
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $135.16 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafés, Catering Services Distribution Channel: Online Delivery, Takeaway, Dine-In, Drive-Thru Price Tier: Low-Cost, Mid-Range, Premium, Luxury Customer Type: Individuals, Families, Business Groups, Tourists |
| Companies Covered | Starbucks Corporation, Popeyes UK, McDonald's Corporation, Bunzl, Coca-Cola Company, Whitbread PLC, Deliveroo, Kitwave Group, Greggs plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Foodservice Market Evolving Landscape
Digital intermediaries are disintermediating traditional wholesale relationships while regulatory compliance technology and experiential dining formats compete for capital allocation across the sector.
Kitchen display systems integrated with predictive demand algorithms are digitizing production sequencing in high-volume quick service environments. Chains with 50-plus UK sites deploy these platforms to compress ticket times and reduce food waste through prep-quantity optimisation. The technology is digitizing back-of-house labour deployment, enabling cross-training across stations during demand troughs.
The UK government's HFSS regulations restrict promotional placement of high-fat, salt, and sugar products in retail and foodservice settings above 2,000 square feet. Large operators must reconfigure menu boards, remove multi-buy offers, and reformulate core lines to maintain visibility in high-traffic locations. Quick service restaurant chains with extensive drive-thru estates face the steepest compliance costs given limited display real estate.
Corporate procurement teams are consolidating catering contracts toward single-source providers with carbon accounting capabilities and uniform allergen protocols. Financial services and technology firms in Canary Wharf and the Square Mile now mandate Scope 3 emissions reporting for all foodservice suppliers. This specification shift favours national operators with established sustainability auditing infrastructure over regional independents.
United Kingdom Foodservice Market Segmentation
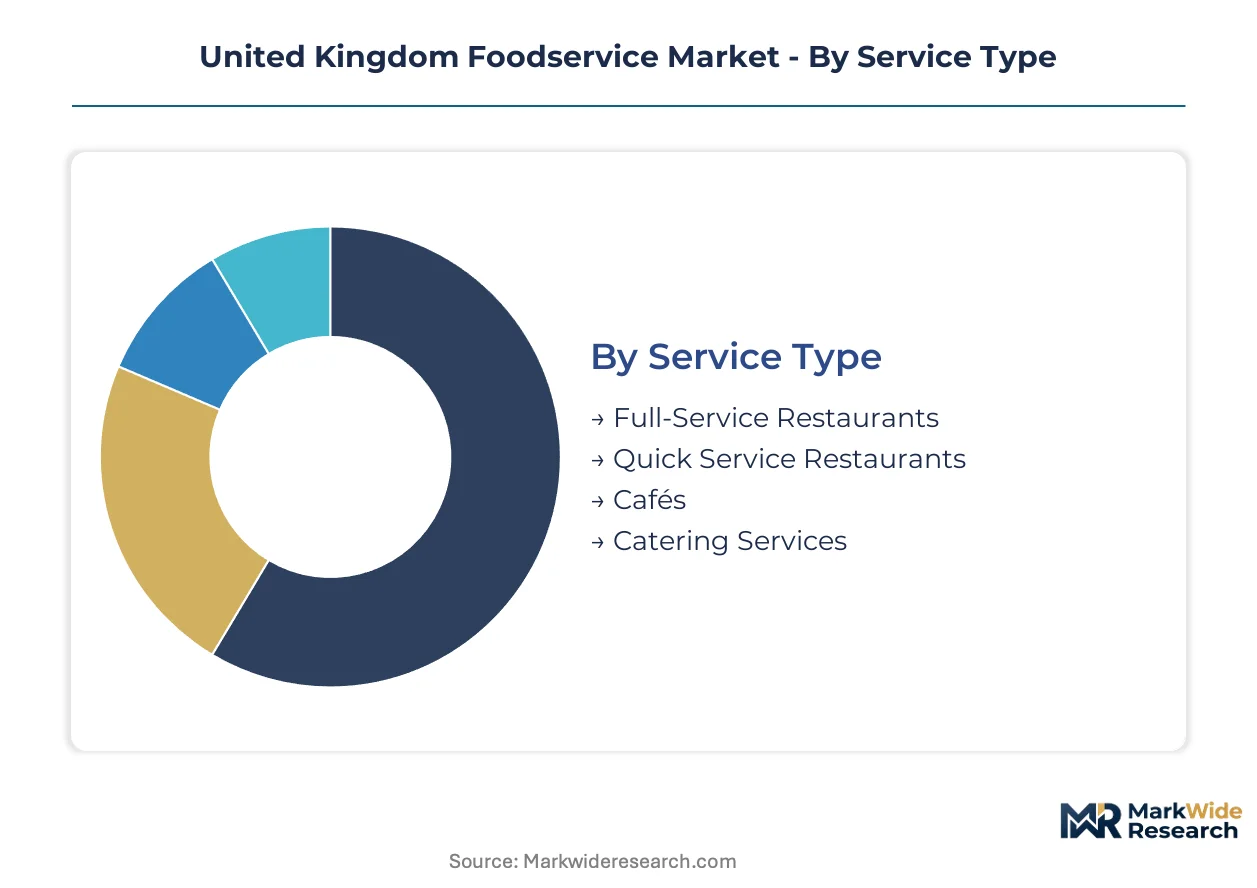
United Kingdom foodservice segmentation reveals how consumption occasions fragment across service formats, purchase channels, and spending thresholds. Operators must align kitchen configuration, labour deployment, and real estate strategy to the specific demands of each segment cluster.
Service Type:
Full-service and quick-service formats anchor opposite ends of the UK foodservice use-case spectrum, with cafés and catering occupying specialised niches.
- Full-Service Restaurants:Table-service operations with extended meal durations and higher per-cover spend. Greater London's West End and Mayfair districts concentrate premium experiential dining demand from business entertainment and international visitor segments.
- Quick Service Restaurants:Limited-menu, high-throughput formats optimised for speed and standardisation. McDonald's Corporation's drive-thru estate across British motorways and retail parks captures commuter and family meal occasions with predictable volume velocity.
- Cafés:Beverage-forward formats with lighter food attachment and extended dwell times. High-street locations in urban centres serve remote workers and casual social meetings.
- Catering Services:Off-premise preparation for institutional and event-based consumption. Corporate contracts in Canary Wharf and the Square Mile generate multi-year revenue streams with Scope 3 emissions reporting requirements.
Established volume favors Quick Service Restaurants; emerging adoption favors Catering Services.
Distribution Channel:
Channel selection in UK foodservice now hinges on last-mile economics and real estate access rather than traditional dine-in dominance.
- Online Delivery:Platform-mediated ordering with third-party logistics fulfilment. Deliveroo's neighbourhood-level radius optimisation in Greater London postcodes demonstrates how algorithmic dispatch reshapes competitive positioning.
- Takeaway:Customer-collected orders with no on-premise consumption. Independent operators in high-density urban corridors use this channel to bypass front-of-house staffing constraints.
- Dine-In:Traditional on-premise consumption with full service or self-service models. The Food Standards Agency's hygiene ratings system creates consumer trust differentials that drive footfall toward five-rated establishments.
- Drive-Thru:Vehicle-based ordering and collection without leaving the automobile. Quick service chains face steepest HFSS compliance costs here given limited menu board real estate for reformulated product visibility.
Online Delivery is expanding most quickly; Dine-In retains the largest revenue base.
Price Tier:
UK foodservice pricing stratification reflects ingredient sourcing intensity, labour skill levels, and experiential design investment.
- Low-Cost:Value-engineered menus with minimised input costs and operational complexity. High-frequency consumption in suburban locations and transport hubs sustains volume despite compressed margins.
- Mid-Range:Balanced quality-positioning for routine dining occasions. Whitbread PLC's Beefeater estate exemplifies this tier's reliance on predictable institutional and family traffic.
- Premium:Elevated ingredients and service standards commanding discretionary spend. Corporate entertainment and celebration occasions concentrate in Greater London and the South East corridor.
- Luxury:Michelin-level execution with theatrical presentation and wine programme integration. Mayfair and Knightsbridge clusters serve international visitors and ultra-high-net-worth domestic clientele.
Mid-Range captures the broadest customer base; Luxury commands the highest margin per cover.
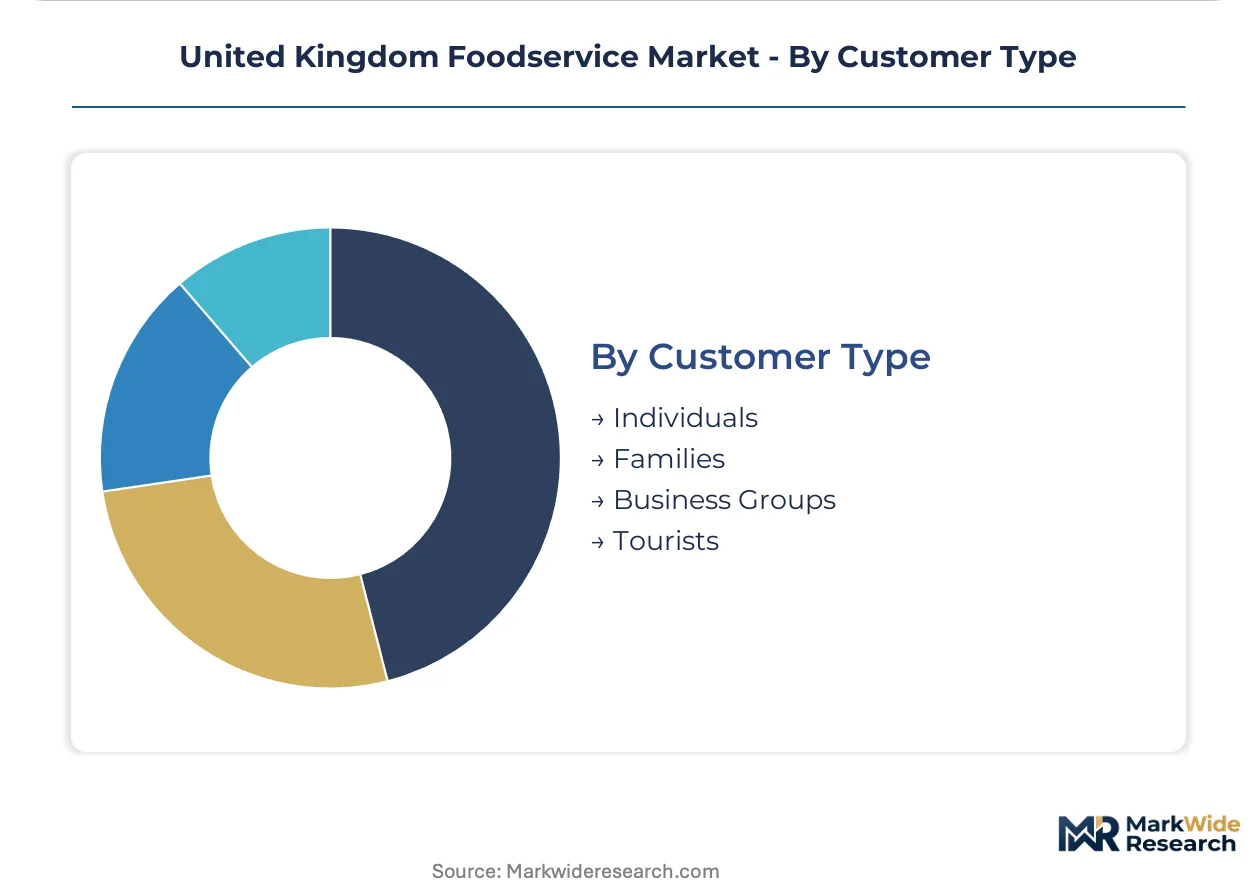
Customer Type:
Distinct consumption patterns across demographic and situational segments require tailored menu architecture and service protocols.
- Individuals:Solo diners prioritising speed, convenience, or personal indulgence. Digital ordering platforms and automated vending systems address 24-hour consumption windows in transport hubs and healthcare campuses.
- Families:Multi-generational groups requiring value bundles, child-friendly options, and flexible seating. Secondary urban centres in the Midlands and North West exhibit higher average order values for family-oriented meal occasions.
- Business Groups:Corporate clients demanding reliable execution, dietary accommodation, and carbon accounting transparency. Financial services and technology firms now mandate uniform allergen protocols and Scope 3 emissions reporting from suppliers.
- Tourists:Visitors seeking authentic or iconic British foodservice experiences. London's West End and historic city centres concentrate this segment's discretionary spend on experiential dining.
Business Groups offer the most predictable contract value; Tourists present the highest seasonal volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Food Standards Agency anchors regulatory oversight across England, Wales, and Northern Ireland, with Scotland operating under Food Standards Scotland. Sub-regional demand clusters reflect employment density, tourism flows, and infrastructure access rather than uniform national distribution.
London and the South East
Corporate catering contracts from Canary Wharf financial services firms and technology companies generate multi-year revenue streams with Scope 3 emissions reporting mandates. Westminster City Council enforces additional licensing conditions for street trading and late-night operations in the West End entertainment district. Michelin-starred kitchens and premium casual dining concentrate in Mayfair, Knightsbridge, and Soho, capturing business entertainment and international visitor spend.
Midlands
Secondary urban centres including Birmingham, Leicester, and Nottingham exhibit lower platform commission density for online delivery operators targeting family-oriented meal occasions. Birmingham City Council's food safety and hygiene enforcement creates competitive differentiation through transparent scoring systems. Industrial logistics corridors around the M6 motorway support dark kitchen infrastructure serving dispersed suburban populations without front-of-house property costs.
North England
Manchester and Leeds anchor regional demand through high-density employment zones and university populations sustaining quick service and café formats. Greater Manchester Combined Authority coordinates local licensing approaches across ten constituent councils. Newcastle and Liverpool tourism traffic supports experiential dining formats, though seasonal volatility exceeds southern counterparts.
Scotland
Food Standards Scotland operates independently with distinct hygiene rating protocols and enforcement priorities from the rest of the United Kingdom. Edinburgh's festival economy and Glasgow's corporate base create concentrated seasonal demand spikes. Aberdeen's energy sector employment historically sustained premium catering contracts, though transition to renewable energy investment is reshaping contract volumes.
Wales and Northern Ireland
Rural population dispersion and limited motorway infrastructure constrain quick service drive-thru expansion compared to English counterparts. Welsh Government procurement frameworks increasingly specify local sourcing percentages for public sector catering contracts. Belfast's hospitality sector operates under dual UK-EU regulatory awareness given land border proximity and all-island supply chain integration.
United Kingdom Foodservice Market Competitive Landscape
International quick service chains and domestic hospitality groups split the market between scale-driven standardisation and property-anchored institutional presence. Consolidation concentrates around drive-thru real estate control and digital platform logistics rather than manufacturing or ingredient supply. Three archetypes dominate: global quick service operators with extensive British motorway and retail park estates, mid-market hotel and restaurant groups with predictable contract catering volumes, and delivery platform intermediaries embedding algorithmic dispatch technology into neighbourhood-level operations. Competitive moves centre on suburban delivery radius expansion and automated production integration.
Within the global quick service tier, McDonald's Corporation and Starbucks Corporation occupy positions defined by drive-thru infrastructure density and digital ordering platform penetration. Among domestic hospitality groups, Whitbread PLC anchors mid-market positioning through integrated hotel and restaurant estate control. Deliveroo exemplifies the platform intermediary archetype, with logistics technology determining competitive reach across Greater London postcodes and secondary urban centres.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Popeyes UK |
| McDonald's Corporation |
| Bunzl |
| Coca-Cola Company |
| Whitbread PLC |
| Deliveroo |
| Kitwave Group |
| Greggs plc |
| Others |
Value Network & Pricing Analysis
Post-EU sanitary chokepoints at UK border inspection posts determine both tiered pricing spreads across imported produce categories and the geographic reconfiguration of supplier networks toward domestic and near-shore alternatives. Foodservice operators face simultaneous cost compression in low-cost tiers and premiumization pressure in luxury segments as continental European ingredient sourcing extends lead times and raises qualification expenditure.
Pricing Analysis
Configured-to-order menu pricing versus standard bundle pricing creates the primary spread across UK foodservice tiers. Premium-mid-economy pricing differentiation rests on ingredient provenance intensity and labour skill deployment. Cost compression in the low-cost tier intensifies as platform commission density rises and energy tariffs squeeze refrigeration economics. Family-oriented suburban operators exhibit highest price sensitivity; corporate catering procurement teams in Canary Wharf demonstrate lowest sensitivity due to contract-based volume commitments.
Supply Chain Analysis
Export-control regime friction on EU food safety certifications limits continental European ingredient flows into British foodservice channels. Supply concentration draws from Spain, Netherlands, and domestic UK producers for fresh produce; protein sourcing rests on Irish, Danish, and Brazilian supplier networks. Single-source vulnerability concentrates in specialty cheese and cured meat categories previously dominated by French and Italian suppliers. Distribution runs through multi-drop consolidation across fragmented wholesale networks serving dark kitchens and traditional outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK foodservice represents a service-attach opportunity where recurring revenue from corporate catering contracts and subscription meal programmes expands faster than transactional dine-in throughput.
For Market Incumbents: Harden perimeter control through backward integration into temperature-controlled distribution infrastructure serving Greater London postcodes. Deepen proprietary digital ordering platform penetration to reduce third-party commission exposure. Certification investment in Food Standards Agency five-rating maintenance creates consumer trust differentials that platform-dependent competitors cannot replicate. For New Entrants and Emerging Players: Build out dark kitchen infrastructure in secondary urban centres across the Midlands and North West where platform commission density remains lower and family-oriented average order values exceed London equivalents. Target suburban delivery radius expansion with algorithmic dispatch optimisation. Go-to-market positioning should emphasise HFSS-compliant menu architecture ahead of promotional placement restrictions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favours operators with integrated real estate and logistics technology stacks. Long-term viability across the projection horizon hinges on contract catering volume predictability and carbon accounting infrastructure for Scope 3 emissions reporting. Acquisition target archetype: mid-scale regional chains with established corporate relationships and underutilised kitchen capacity. The signal to watch is government procurement framework shifts toward local sourcing mandates in public sector catering.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Infrastructure Expansion | Eliminates front-of-house capex while enabling rapid postcode-level market testing across Greater London. |
| HFSS Reformulation Programme | Positions compliant product ranges ahead of promotional placement restrictions in retail and foodservice settings. |
| Corporate Catering Contract Consolidation | Captures multi-year revenue streams with Scope 3 emissions reporting mandates from financial services firms. |
| Automated Production Integration | Addresses 24-hour consumption windows in transport hubs through temperature-controlled smart locker deployment. |
| Suburban Delivery Radius Optimisation | Exploits lower platform commission density in Midlands and North West secondary urban centres. |
Research Methodology
Operator-level perspectives from quick service chain procurement directors, dark kitchen facility managers, corporate catering contract specialists, and Food Standards Agency enforcement officers anchored the qualitative base. Secondary validation drew from Food Standards Agency hygiene rating databases, UK government HFSS regulatory filings, Deliveroo and Just Eat platform commission disclosures, and corporate sustainability reporting from FTSE 250 hospitality groups. Bottom-up site-level volume estimates triangulated against top-down sector expenditure data from national accounts.
Scenario-bracketing around post-EU sanitary rule implementation timelines and energy price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, distribution channel, price tier, and customer occasion. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated platform economics evolution and labour market tightness from visa regime changes.
Stress conditions across border inspection post throughput capacity, commercial energy tariff spikes, and EU worker visa availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and platform commission structure persistence. Material shifts in UK-EU trade agreement terms or Food Standards Scotland regulatory divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Sushi Restaurants Market
Food Service
Restaurant Griddle Market
Food Service
Bar Refrigeration Market
Food Service
Breakfast Takeout Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
France Foodservice Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Commercial Charbroiler Market
Food Service
Bangladesh Food Service Market
Food Service
Contract Catering Market
Food Service
Vacuum Flask Market
Food Service
Europe Cloud Kitchen Market
Food Service
Beverage Vending Machine Market
Food Service
Global Waffle Maker Market
Food Service
Australia Foodservice Market