
 Commercial Charbroiler Market | 2026-2036
Commercial Charbroiler Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Charbroiler Market Outlook
NSF International certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Middleby Corporation leverages its manufacturing scale to dominate high-volume institutional accounts. Garland Group Ltd. differentiates through specialized product lines for premium restaurant chains. Vulcan LLC anchors its position with broad distribution across independent operators and regional foodservice groups.
A commercial charbroiler is a heavy-duty cooking appliance that generates radiant and convective heat through gas burners, electric elements, or infrared panels to sear proteins at temperatures exceeding 550°F for restaurant and institutional kitchens. Gas charbroilers retain the largest installed base due to lower operational costs and faster recovery times, though infrared charbroilers are capturing margin-rich segments in steakhouse and fine-dining installations where precise heat control commands premium pricing. Countertop configurations lead replacement cycles in space-constrained urban kitchens, while free-standing units sustain higher average selling prices in new-build commercial facilities.
FDA food safety guidelines, EPA emissions standards, and ENERGY STAR efficiency thresholds collectively determine product design requirements and procurement eligibility for institutional buyers. These frameworks push manufacturers toward lower-NOx burner systems and improved insulation, raising engineering barriers for new entrants. Stakeholders must monitor evolving efficiency mandates and fuel infrastructure shifts as electrification incentives reshape total cost-of-ownership calculations for end users.
Market Dynamics
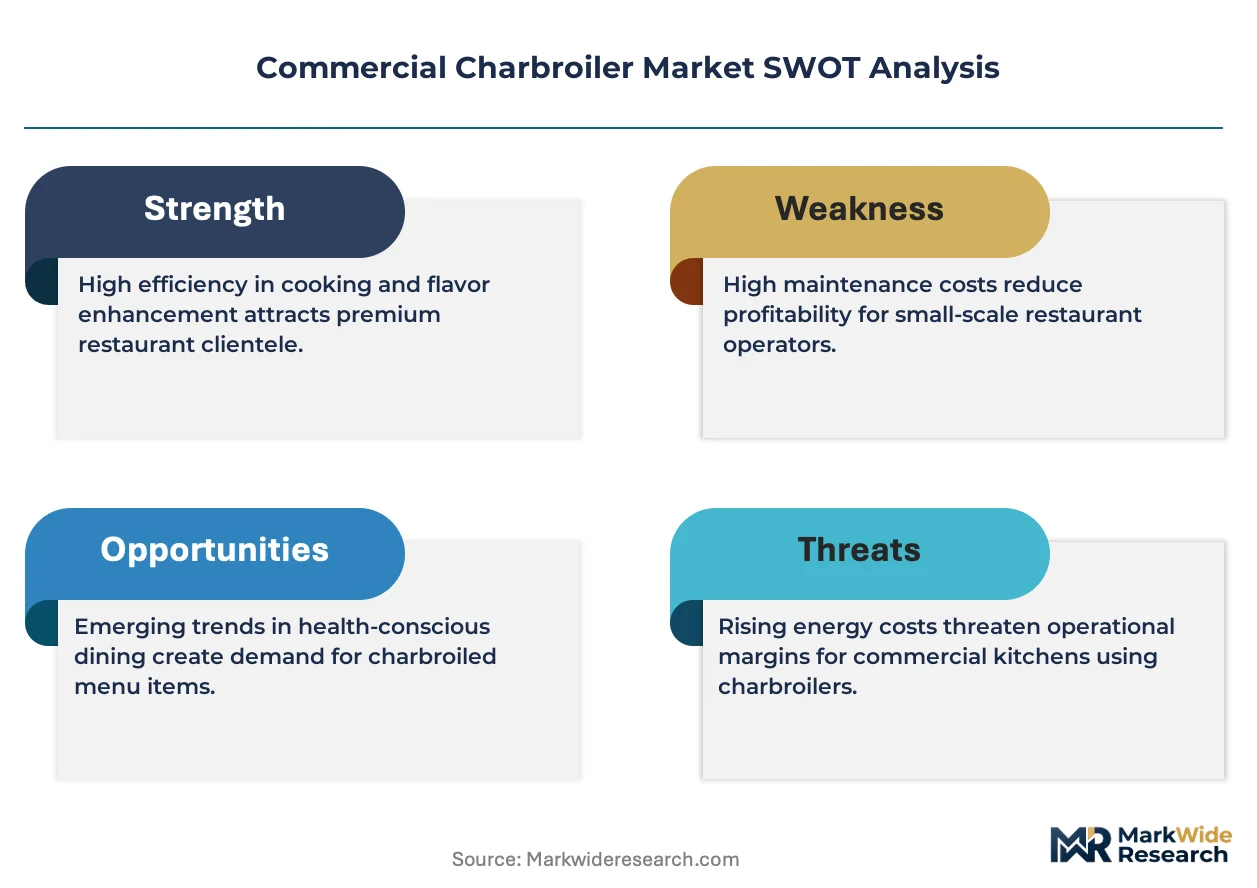
EPA emissions standards and ENERGY STAR efficiency thresholds are compressing product lifecycles while elevating engineering barriers for equipment manufacturers serving commercial kitchens.
Growth Catalysts
- Full-service restaurant renovation cycles:Chain operators in the United States are replacing aging equipment to meet modern efficiency benchmarks and reduce utility expenditures.
- ENERGY STAR thresholds:Institutional procurement policies now mandate certified equipment, disqualifying non-compliant suppliers from school, hospital, and government contracts.
- Infrared panel technology:Steakhouse and fine-dining segments are specifying infrared charbroilers for precise heat control and reduced energy waste during peak service hours.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices compress manufacturer margins and destabilize quoted equipment pricing for multi-month projects.
- Component supply concentration:Burner assembly and control valve production clusters in specific manufacturing regions, creating vulnerability to logistics disruptions.
- Gas infrastructure lock-in:Existing kitchen ventilation and utility configurations create switching costs that slow electrification adoption despite incentive programs.
Strategic Opportunities
- Urban countertop configurations:Space-constrained kitchens in dense metropolitan areas present replacement demand for compact, high-output equipment.
- Electrification incentives:The Inflation Reduction Act and state-level rebate programs are altering total cost-of-ownership calculations for electric charbroiler specifications.
- Aftermarket service contracts:Independent operators and regional foodservice groups represent underserved demand for preventive maintenance and parts replacement programs.
Industry Challenges
- NSF certification timelines:Third-party testing and documentation requirements extend product development cycles, delaying revenue recognition for new model introductions.
- Technician training gaps:Infrared and smart-control systems require specialized service capabilities that exceed the skill base of legacy repair networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Charbroiler Market |
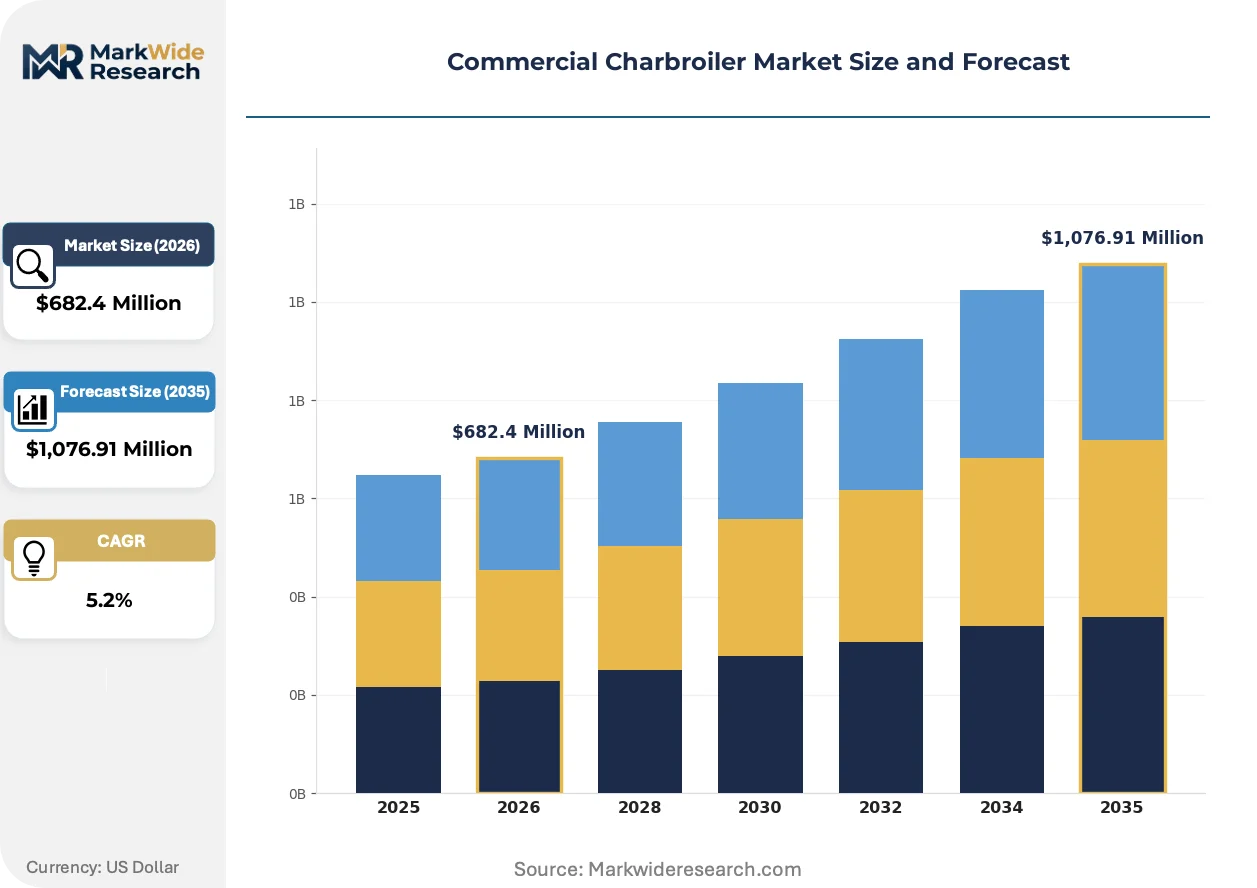
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,076.91 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Charbroilers, Electric Charbroilers, Charcoal Charbroilers, Infrared Charbroilers Installation Type: Countertop, Free-standing, Mobile, Drop-in End User: Restaurants, Cafes, Catering Services, Food Trucks Fuel Type: Natural Gas, Propane, Electricity, Wood |
| Companies Covered | Middleby Corporation, Garland Group Ltd., Vulcan LLC, The Vollrath Company LLC, Wells Manufacturing Inc., Bakers Pride, MagiKitch'n, Southbend, Montague Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Charbroiler Market Strategic Shifts
Infrared heating technology is accelerating product segmentation while regulatory pressure on combustion emissions intensifies manufacturer R&D priorities.
Infrared radiant panels are decomposing the traditional gas burner market by delivering superior searing performance with reduced energy input. Premium steakhouse chains are specifying these systems for new-build locations, while retrofit demand grows among independent operators seeking differentiation. The technology is decomposing price competition in the mid-market tier by establishing performance-based rather than cost-based procurement criteria.
EPA New Source Performance Standards for commercial cooking equipment are mandating lower NOx emissions across gas-fired categories. Manufacturers must redesign burner architectures and invest in catalytic after-treatment systems to maintain market access. Full-service restaurant chains with corporate sustainability mandates are accelerating compliance-driven replacement schedules ahead of regulatory deadlines.
Buyer concentration among multi-unit operators is compressing equipment specification cycles and consolidating vendor relationships. National accounts teams at major suppliers now coordinate directly with culinary directors rather than routing through traditional foodservice distributors. This pattern is most pronounced in the United States, where chain restaurant expansion and centralized procurement functions have matured.
Commercial Charbroiler Market Segmentation
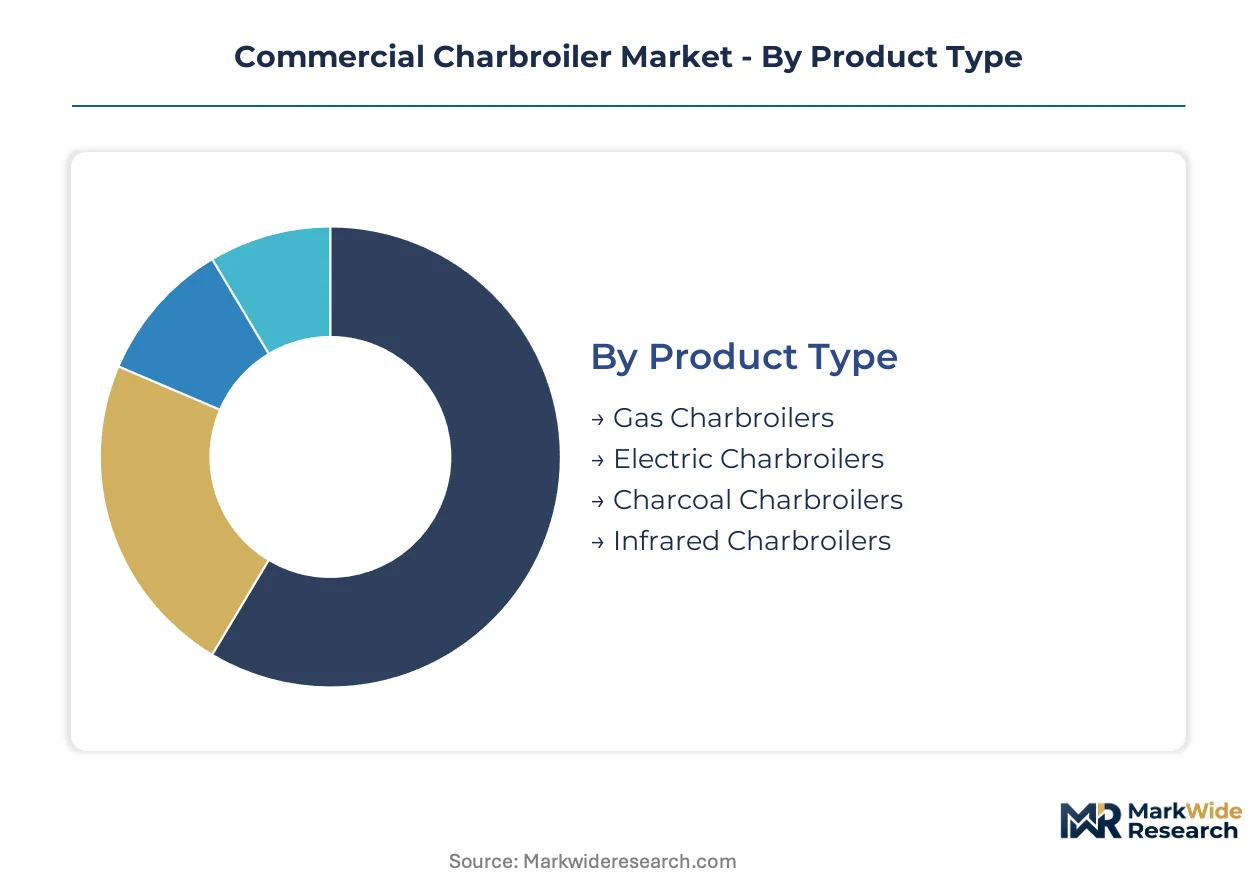
Segmentation in the commercial charbroiler market determines procurement eligibility, installation feasibility, and total cost-of-ownership calculations for distinct operational environments. Equipment specifications vary sharply across fuel infrastructure availability, kitchen spatial constraints, and end-user volume requirements.
Product Type:
EPA emissions standards and ENERGY STAR certification thresholds create divergent compliance pathways for each technology platform, reshaping manufacturer R&D priorities and buyer procurement criteria.
- Gas Charbroilers:These units deploy atmospheric or infrared-enhanced burners delivering radiant heat at operating costs below electric alternatives. Full-service restaurant chains in the United States specify gas configurations for high-throughput protein preparation where recovery time determines kitchen throughput.
- Infrared Charbroilers:Ceramic or metal radiant panels generate intense, direct heat exceeding 800°F surface temperatures with minimal convective loss. Steakhouse operators and premium independent restaurants adopt these systems for precise sear control and reduced energy waste during peak service windows.
- Electric Charbroilers:Resistance or induction elements eliminate combustion emissions entirely, qualifying for electrification rebates under the Inflation Reduction Act.
- Charcoal Charbroilers:Solid-fuel combustion delivers distinctive flavor profiles for barbecue-centric concepts and ethnic cuisine specialists.
Established volume favors gas charbroilers; emerging adoption favors infrared charbroilers.
Installation Type:
Spatial economics and kitchen workflow patterns determine configuration selection, with urban real estate constraints accelerating demand for compact, high-output alternatives.
- Countertop:Compact units mount on existing work surfaces or refrigerated bases, maximizing production capacity per square foot in Manhattan, San Francisco, and Chicago kitchen footprints where lease rates exceed $50 per square foot annually.
- Free-standing:Modular base and caster-mounted designs support new-build commercial facilities and renovation projects requiring flexible equipment positioning.
- Mobile:Casters and quick-disconnect utility fittings enable repositioning for catering operations and temporary event kitchens.
- Drop-in:Flush-mount integration into custom fabrication supports seamless aesthetic requirements for open-kitchen fine-dining concepts.
Replacement cycles concentrate in countertop configurations; new-build spending flows toward free-standing units.
End User:
Volume throughput and menu complexity create distinct equipment durability and control precision requirements across operator categories.
- Restaurants:Full-service and limited-service operators generate the largest equipment installed base, with chain accounts driving standardization and independent operators seeking differentiation through specialized configurations.
- Catering Services:Off-premise event production demands rapid setup, transport durability, and flexible fuel connectivity for venues lacking permanent utility infrastructure.
- Cafes:Limited-menu operators prioritize compact footprints and reduced ventilation requirements for secondary cooking applications.
- Food Trucks:Mobile operators confront severe space, weight, and utility constraints that favor specialized compact designs with propane flexibility.
Procurement scale concentrates with restaurant chains; specification diversity expands across catering and mobile segments.
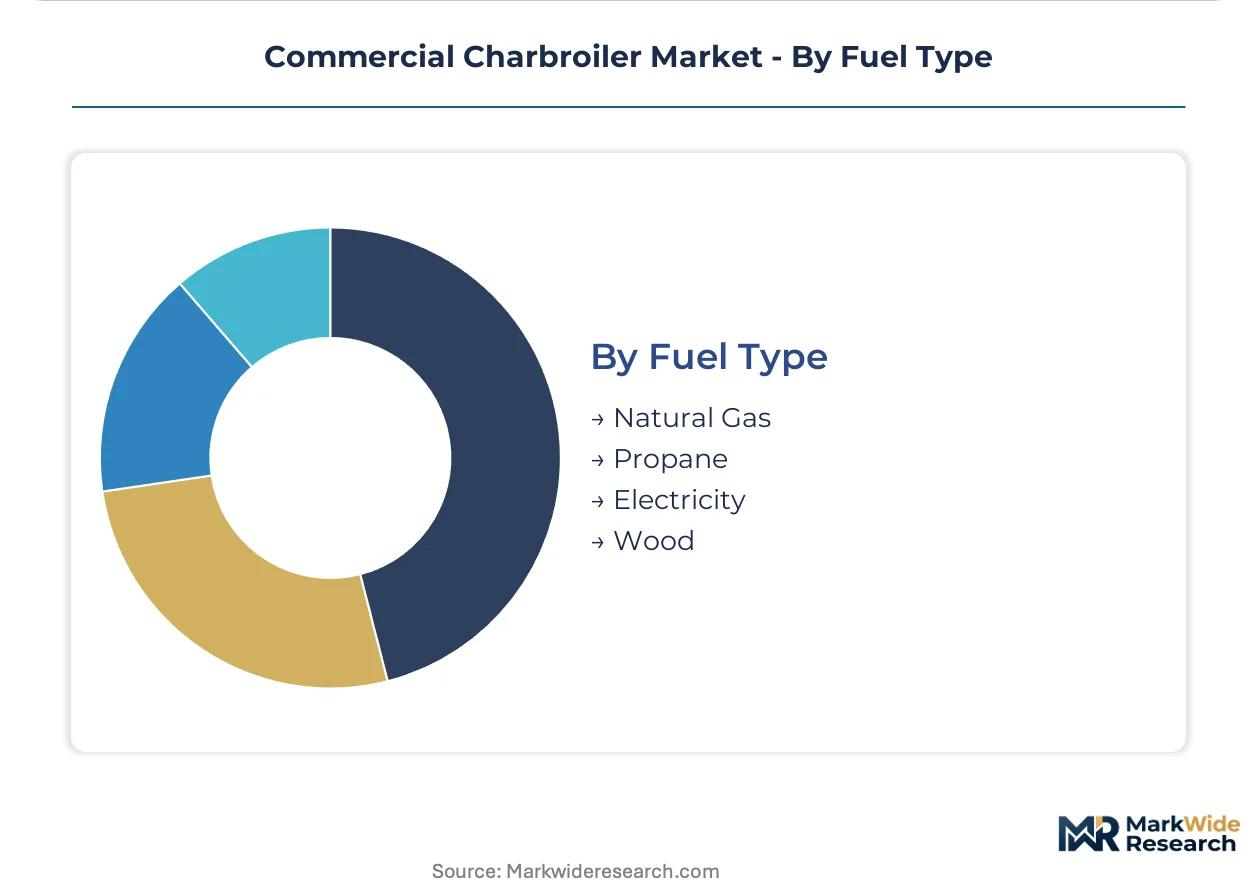
Fuel Type:
Utility infrastructure availability and regulatory incentive structures determine fuel selection, with electrification mandates altering long-term equipment planning horizons.
- Natural Gas:Permanent utility connection delivers lowest per-BTU operating costs in regions with established pipeline distribution, anchoring specifications for high-volume institutional kitchens.
- Propane:Tank-based supply enables installation flexibility for rural locations, mobile operations, and facilities lacking natural gas lateral connections.
- Electricity:Grid-connected or battery-backed systems eliminate point-source emissions and qualify for IRA rebates, gaining share fastest in jurisdictions with aggressive decarbonization timelines.
- Wood:Solid-fuel combustion supports authentic barbecue and wood-fired concepts, subject to local air quality district restrictions on particulate emissions.
Natural gas retains the largest installed base; electricity is climbing the fastest under incentive-driven replacement schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chain restaurant procurement teams concentrate equipment specification authority in the United States, while electrification mandates and efficiency standards reshape replacement cycles across developed markets.
United States
Full-service restaurant chains drive standardized equipment rollouts across thousands of locations. EPA New Source Performance Standards mandate lower NOx emissions from gas-fired commercial cooking equipment. Dallas and Atlanta serve as distribution hubs where regional foodservice dealers coordinate national account fulfillment.
Germany
Commercial kitchen operators prioritize energy efficiency certifications under EU Green Deal implementation timelines. Ecodesign regulations and REACH compliance requirements elevate engineering barriers for imported equipment. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized fabricators serving Central European institutional buyers.
China
Urban restaurant expansion in tier-one cities generates demand for compact, high-output cooking equipment. MIIT efficiency standards and local air quality regulations constrain combustion-based equipment in Beijing and Shanghai. The Yangtze River Delta manufacturing corridor supplies cost-optimized units for domestic and export markets.
United Kingdom
Pub and casual dining chains upgrade kitchen infrastructure to meet corporate sustainability targets. Post-Brexit regulatory divergence from EU standards creates dual certification requirements for equipment suppliers. London's dense restaurant concentration drives replacement demand for space-efficient countertop configurations.
Japan
High-end steakhouse concepts specify precision heating equipment for premium protein preparation. METI energy conservation standards accelerate replacement of aging gas-fired appliances in commercial kitchens. The Kanto region's restaurant density supports specialized service networks for complex infrared systems.
Commercial Charbroiler Market Competitive Environment
Player mix skews toward diversified foodservice equipment conglomerates with captive manufacturing scale and specialized regional fabricators serving premium independent operators. Market structure concentrates around three to four integrated suppliers controlling institutional procurement channels, while mid-tier competition fragments across price-sensitive replacement demand. Strategic archetypes separate into scale-driven national account specialists, technology-differentiated premium-positioned players, and cost-optimized regional fabricators. Dominant competitive moves include backward integration into burner component manufacturing and geographic expansion through distributor network acquisition.
Among North American equipment conglomerates, Middleby Corporation, Garland Group Ltd., and Vulcan LLC occupy positions across distinct buyer segments. Middleby exemplifies the scale-driven archetype through manufacturing breadth serving high-volume institutional accounts. Garland represents technology-differentiated positioning with specialized configurations for premium restaurant chains. Vulcan anchors the diversified distribution model spanning independent operators and regional foodservice groups.
| Leading Market Players |
|---|
| Middleby Corporation |
| Garland Group Ltd. |
| Vulcan LLC |
| The Vollrath Company LLC |
| Wells Manufacturing Inc. |
| Bakers Pride |
| MagiKitch'n |
| Southbend |
| Montague Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day burner assembly lead times concentrate pricing power with qualified NSF-certified suppliers while compressing margins for fabricators locked into stainless steel indexation clauses. This inventory-to-pricing dynamic intensifies when nickel price volatility triggers contract renegotiations between tier-one manufacturers and institutional buyers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and chromium benchmarks dominate equipment procurement between manufacturers and chain restaurant accounts. Price differentiation rests on ENERGY STAR certification tier and burner technology grade, with infrared-enhanced systems commanding premiums over atmospheric burner configurations. Pricing pressure intensifies in the standard-equipment tier as regional fabricators from China compete on delivered cost for replacement-cycle demand. Independent operators exhibit highest price sensitivity due to capital constraints, while national accounts prioritize total cost-of-ownership metrics over upfront equipment expenditure.
Supply Chain Analysis
Strait of Malacca transit routes underpin component delivery schedules for burner assemblies sourced from Malaysian and Thai manufacturing clusters. Supply concentrates in China for stainless steel fabrication, the United States for control valve engineering, and Italy for premium infrared ceramic panels. Raw material dependencies span nickel-chromium alloys, cast iron grates, and electronic control modules. Single-source vulnerability concentrates in specialized ceramic radiant panel production. Distribution runs through regional foodservice equipment dealers serving independent operators, with national accounts receiving direct manufacturer fulfillment coordinated through Dallas and Atlanta logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated chain restaurant procurement functions that centralize equipment specification authority across thousands of locations. This consolidation fragments vendor access for mid-tier suppliers unable to meet national account compliance requirements.
For Market Incumbents: Shield installed base relationships by deepening captive supply of burner components through backward integration into valve manufacturing. Prioritize ENERGY STAR pre-certification for next-generation infrared platforms to disqualify emerging competitors from institutional procurement pipelines before EPA compliance deadlines tighten.
For New Entrants and Emerging Players: Lead with aftermarket service contracts targeting independent operators and regional foodservice groups currently underserved by national account teams. The most penetrable white space sits in preventive maintenance programs for aging gas charbroiler installed bases in secondary metropolitan markets. Establish foothold through direct technician training partnerships that address documented skill gaps in infrared system repair.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because equipment lifecycles are compressing under regulatory pressure while buyer concentration accelerates vendor rationalization. Target acquisition archetypes include specialized infrared technology developers with NSF certification already secured and established regional service networks. The signal to watch is Inflation Reduction Act rebate program expansion rates altering electric charbroiler adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Component Manufacturing | Captive valve production insulates margin from stainless steel price volatility and qualifies suppliers for expedited NSF timelines. |
| ENERGY STAR Pre-Certification Investment | Early compliance locks in institutional procurement eligibility before regulatory thresholds disqualify competitors. |
| Aftermarket Service Network Expansion | Preventive maintenance contracts generate recurring revenue from independent operators outside national account channels. |
| Infrared Technology Platform Development | Premium positioning in steakhouse and fine-dining segments commands pricing power through performance-based procurement criteria. |
| Regional Distributor Acquisition | Direct channel control in secondary markets bypasses consolidated procurement functions that exclude non-qualified vendors. |
Study Parameters
Cross-validation between regulatory filing analysis and equipment procurement database audits anchors the qualitative findings in documented compliance patterns. Primary interviews with commercial kitchen equipment procurement directors, NSF certification engineers, chain restaurant culinary directors, and regional foodservice dealer principals combined with secondary validation against EPA New Source Performance Standards dockets, ENERGY STAR qualified product listings, and SEC 10-K disclosures from publicly traded equipment manufacturers. Bottom-up unit shipment estimates triangulate against top-down restaurant construction spending data.
Sensitivity analysis across fuel type adoption scenarios and regulatory compliance timelines shapes the projection framework. Segmentation dimensions modeled include product technology platform, installation configuration, end-user category, and fuel infrastructure availability across the projection horizon. CAGRs derive from equipment replacement cycle analysis and new-build commercial kitchen construction forecasts. Industry-specific inputs incorporate ENERGY STAR threshold evolution assumptions and Inflation Reduction Act rebate program participation rates.
The analysis sits within stated boundaries; outcomes outside sustained chain restaurant expansion or accelerated electrification mandates would require recalibration. Forecasts reflect assumptions regarding regulatory implementation schedules and stainless steel price stability. Practitioners should keep alternative scenarios live as EPA NOx emissions standards and state-level decarbonization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Foodservice Market
Food Service
Undercounter Ice Makers Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Indonesia Foodservice Market
Food Service
Ship Catering Service Market
Food Service
Commercial Air Fryer Oven Market
Food Service
India Quick Service Restaurant Market
Food Service
Global Vending Machine Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Air Fryer Market
Food Service
Air Fryer Meal Kits Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Spain Food Service Market
Food Service
Pizza Oven Market
Food Service
Plates Market
Food Service
Peer-To-Peer Dining Market