
 Bar Refrigeration Market | 2026-2036
Bar Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
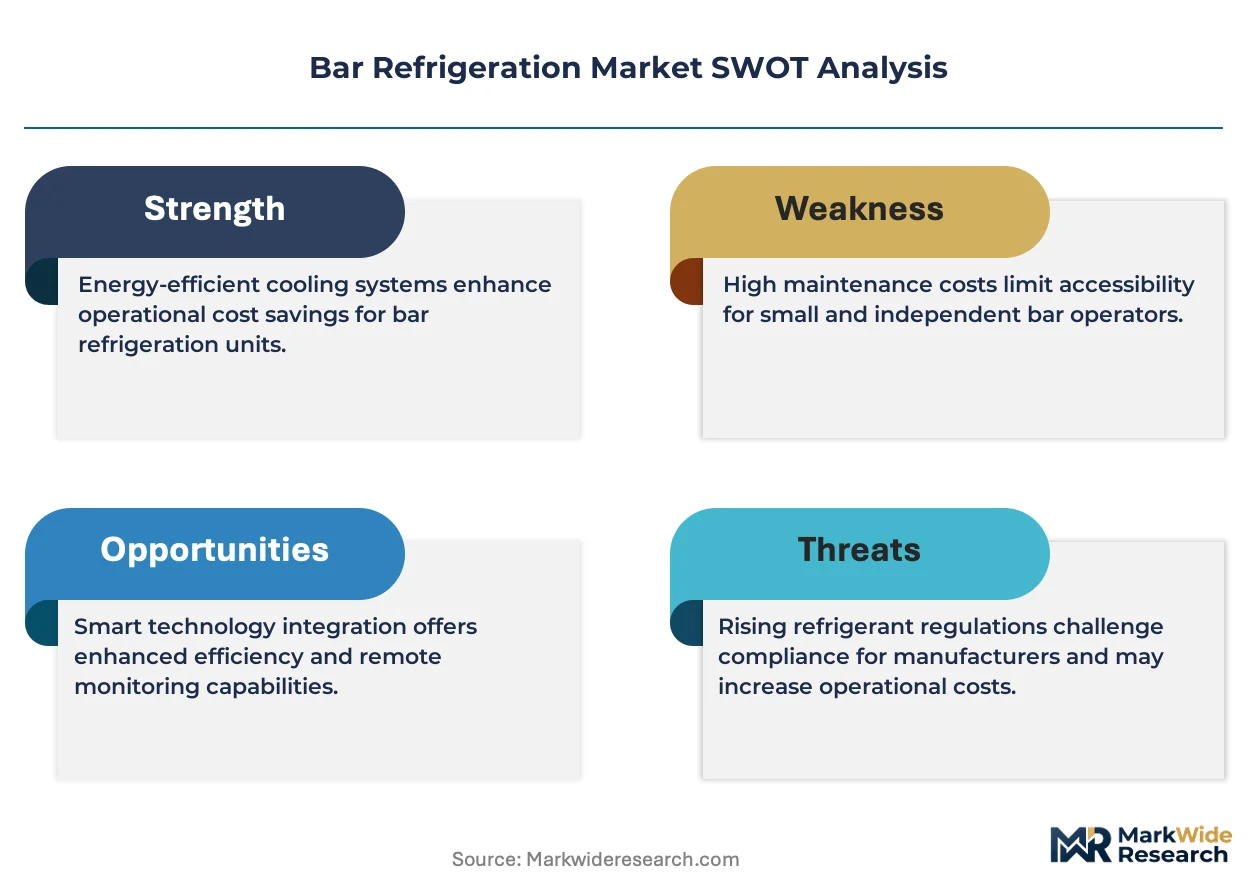
Bar Refrigeration Market Analysis
Multi-source procurement among commercial kitchen equipment distributors is consolidating as tier-one manufacturers tighten direct channel control. True Manufacturing Company, Inc. leverages its Missouri-based fabrication footprint to dominate domestic back-bar cooler supply. Continental Refrigerator anchors its position through stainless-steel construction specialization across under-counter lines. Turbo Air Inc. competes aggressively on energy-efficient compressor technology for independent bar operators.
Bar refrigeration encompasses self-contained cooling systems engineered to maintain beverages between 33°F and 38°F through forced-air or static-cooling architectures, typically employing R290 or R600a hydrocarbon refrigerants in sealed vapor-compression loops. These units serve the commercial on-premise alcohol and soft-drink service sector by preserving product quality while enabling high-visibility merchandising at point of consumption. Back bar coolers and under-counter refrigerators command the largest installed base, though draft beer dispensers generate premium margin pools through integrated glycol chiller configurations and tower tap systems. Vapor compression technology leads volume shipments while thermoelectric cooling occupies niche wine preservation applications where vibration elimination matters.
US DOE federal efficiency standards and EPA SNAP refrigerant phase-down rules are accelerating hydrocarbon adoption and redesign cycles across domestic manufacturers. Ecodesign requirements and F-Gas Regulation in Europe are forcing parallel refrigerant transitions and mandatory energy labeling, raising compliance costs for exporters. Stakeholders must monitor evolving refrigerant approvals and regional efficiency tier thresholds to avoid stranded inventory and maintain cross-border product eligibility.
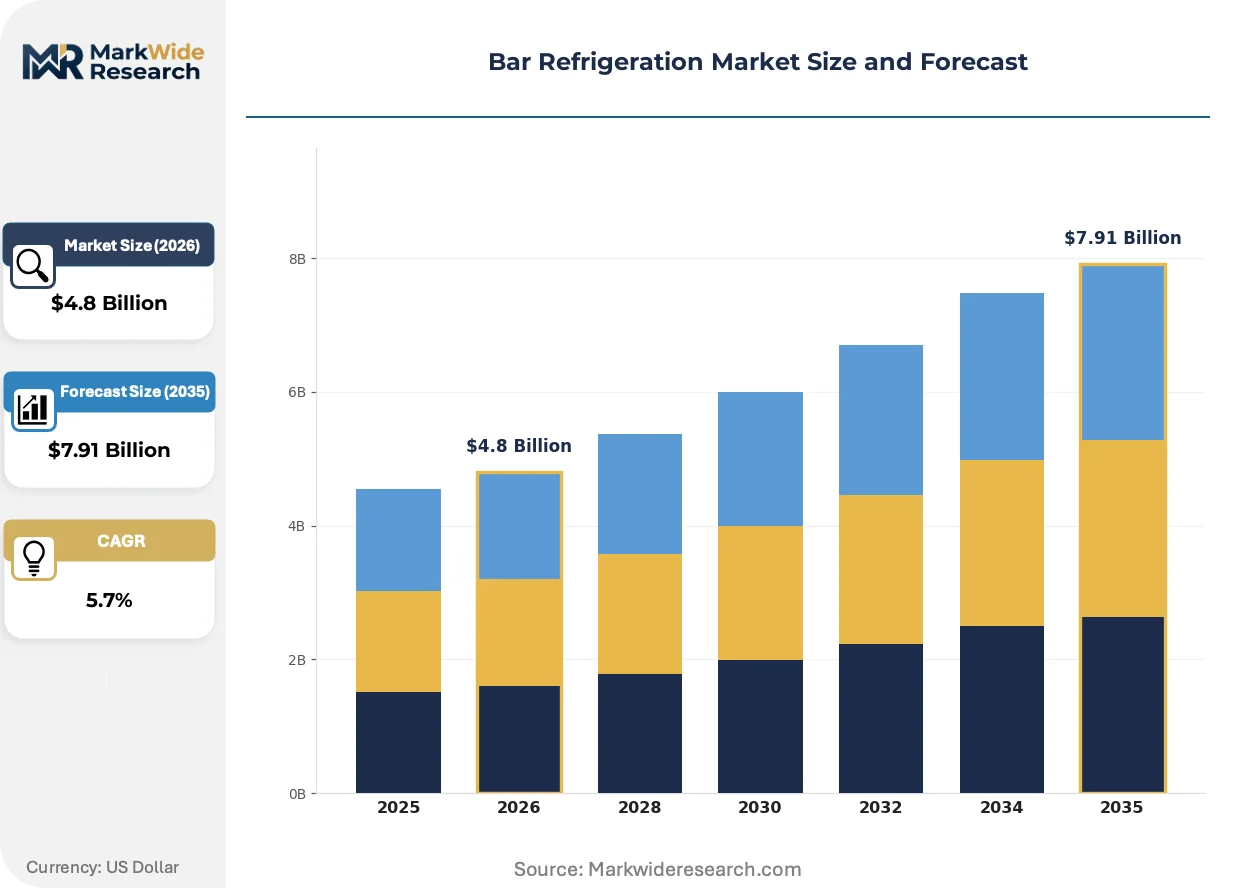
Market Dynamics
Variable-speed compressor architectures are displacing fixed-speed designs across the US bar refrigeration installed base as the Department of Energy tightens federal appliance efficiency standards. This technology transition concentrates procurement leverage among manufacturers with captive motor-controller development capabilities.
Growth Catalysts
- EPA SNAP refrigerant phase-down:Hydrocarbon refrigerant approvals under SNAP rules are accelerating R290 and R600a adoption, forcing redesign cycles that favor specialized sealed-system fabricators.
- Craft cocktail bar expansion:Gastropubs and mixology-focused venues are expanding back-of-house cold storage footprints to support premium beverage programs with precise temperature zoning.
- German draft beer culture:Per-capita cooler deployment rates in Germany sustain replacement demand for glycol-chilled draft systems and tower tap configurations.
Market Restraints
- Copper and aluminum price volatility:Raw material swings in heat exchanger metals compress margin predictability for mid-tier manufacturers without long-term supply agreements.
- Supply concentration in compressor motors:Nidec and EBM-Papst control critical variable-speed motor supply, creating single-source vulnerability for domestic fabricators.
- Technical limitation of thermoelectric cooling:Peltier systems face capacity ceilings above 150 liters, restricting their deployment to wine preservation niches.
Strategic Opportunities
- Underpenetrated India:Organized retail alcohol service expansion in Mumbai and Bangalore creates first-mover positioning for energy-efficient under-counter lines.
- Smart connectivity convergence:IoT temperature logging and predictive maintenance algorithms are merging with refrigeration hardware to create subscription service revenue streams.
- US Inflation Reduction Act efficiency incentives:Commercial building electrification tax credits are redirecting capital toward replacement of aging bar refrigeration fleets.
Industry Challenges
- Refrigerant handler certification gaps:EPA Section 608 technician shortages delay field service response times for hydrocarbon system deployments.
- Legacy control integration friction:Variable-speed compressor retrofits require controller reprogramming that conflicts with existing building management system protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Refrigeration Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Under-Counter Refrigerators, Back Bar Coolers, Bottle Coolers, Draft Beer Dispensers End User: Bars, Restaurants, Nightclubs, Hotels Applications: Beer Storage, Wine Storage, Soft Drink Dispensing, Ice Storage Cooling Technology: Vapor Compression, Thermoelectric, Cascade Cooling, Absorption Systems |
| Companies Covered | True Manufacturing Company, Inc., Continental Refrigerator, Turbo Air Inc., Ali Group, ONNERA GROUP, Valpro Commercial Refrigeration, Perlick Corporation, Beverage-Air, Hoshizaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Refrigeration Market Emerging Trajectories
Forced-air cooling architectures are ceding share to static-cooling and hybrid designs as beverage quality preservation takes precedence over rapid pull-down speed. This shift reflects buyer prioritization of temperature stability over recovery performance.
Natural refrigerant sealed systems using R290 propane is expanding into mid-capacity back-bar coolers previously dominated by HFC-134a. Independent bar operators in Texas and Florida are specifying hydrocarbon units for new builds at accelerating rates. This transition is compressing the addressable market for legacy refrigerant service infrastructure and spare parts distribution.
Europe's F-Gas Regulation is mandating phasedown quotas that eliminate high-GWP refrigerants from imported equipment categories by 2030. Domestic manufacturers serving EU markets must retool production lines and recertify safety testing protocols. Under-counter refrigerator segments face the steepest compliance cost escalation due to volume sensitivity and thin margin structures.
Buyer preference is consolidating around direct manufacturer relationships, disintermediating traditional commercial kitchen equipment distributors who previously controlled specification influence. Large multi-unit operators in California and New York are establishing national account contracts with fabrication plants. This channel compression is most visible among craft brewery taproom chains with standardized equipment specifications across 50-plus locations.
Bar Refrigeration Market Segmentation
Bar refrigeration segmentation reveals divergent compliance burdens across product architectures. Hydrocarbon refrigerant approvals and DOE efficiency tiers create tiered certification costs that reshape procurement patterns among commercial operators.
Product Type:
EPA SNAP hydrocarbon approvals and UL 471 safety certifications concentrate most heavily on sealed-system designs with refrigerant charge thresholds above 150 grams.
- Back Bar Coolers:Glass-door forced-air units dominate craft cocktail venues and gastropubs. California and New York multi-unit operators specify these for high-visibility merchandising at point of consumption.
- Draft Beer Dispensers:Glycol-chilled tower tap systems integrate sealed compressors with recirculating coolant loops. German draft beer culture sustains replacement demand for these premium-margin configurations.
- Under-Counter Refrigerators:Stainless-steel static-cooling units serve back-of-house storage in space-constrained urban bars.
- Bottle Coolers:Solid-door reach-in designs target high-volume beer service with rapid recovery specifications.
Leading the category by volume: Under-Counter Refrigerators. Growing fastest: Draft Beer Dispensers.
End User:
Channel concentration varies sharply by operator scale, with national account contracts displacing traditional distributor relationships among multi-location chains.
- Bars:Independent operators drive hydrocarbon specification shifts in Texas and Florida new builds. These buyers prioritize energy-efficient compressor technology with IoT temperature logging capabilities.
- Restaurants:Gastropubs expand cold storage footprints to support premium beverage programs with precise temperature zoning for craft cocktails.
- Nightclubs:High-capacity bottle cooler deployment concentrates in Miami and Las Vegas entertainment corridors.
- Hotels:Property-level procurement standardizes across flag properties through corporate sustainability mandates.
Restaurants capture the steepest expansion trajectory as gastropub formats proliferate. Bars retain the largest installed base requiring fleet replacement.
Applications:
Temperature stability requirements diverge sharply by beverage chemistry, with wine preservation demanding vibration elimination that thermoelectric systems address.
- Beer Storage:Forced-air architectures maintain 33°F to 38°F across high-turnover draft systems. German per-capita cooler deployment rates sustain this segment's replacement velocity.
- Wine Storage:Thermoelectric Peltier systems eliminate compressor vibration for cellar-temperature preservation. Capacity ceilings above 150 liters restrict deployment to upscale hotel and restaurant niches.
- Soft Drink Dispensing:Post-mix syrup cooling integrates with carbonation systems in high-volume bar environments.
- Ice Storage:Bin refrigeration maintains ice quality during extended service periods in nightclub and hotel settings.
Beer Storage commands the largest addressable market. Wine Storage shows the most rapid technology substitution as thermoelectric costs decline.
Cooling Technology:
Refrigerant phase-down regulations are compressing the technology mix toward natural hydrocarbon sealed systems and away from legacy HFC architectures.
- Vapor Compression:R290 and R600a hydrocarbon refrigerants in sealed loops dominate mid-capacity back-bar and under-counter lines. US DOE efficiency standards accelerate variable-speed compressor adoption across this installed base.
- Thermoelectric:Peltier solid-state cooling occupies wine preservation niches where vibration elimination outweighs efficiency penalties. European F-Gas Regulation compliance costs favor this technology for small-capacity imports.
- Cascade Cooling:Dual-refrigerant systems target ultra-low temperature applications in specialty cocktail ice programs.
- Absorption Systems:Heat-driven cooling serves off-grid or silent-operation requirements in boutique hotel minibars.
Vapor Compression leads by unit shipments. Thermoelectric gains share fastest in premium wine service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum sourcing corridors in Arizona and Chile anchor fabrication costs for compressor heat exchangers and coil assemblies. These metal supply chains directly influence manufacturing economics across major bar refrigeration production clusters.
United States
Variable-speed compressor retrofits accelerate across California and New York multi-unit bar chains as the Department of Energy tightens federal appliance efficiency standards. The US Inflation Reduction Act commercial building electrification tax credits redirect capital toward fleet replacements. Texas and Florida independent operators specify hydrocarbon units for new builds at accelerating rates.
Germany
Per-capita cooler deployment rates sustain replacement demand for glycol-chilled draft systems and tower tap configurations. The F-Gas Regulation mandates phasedown quotas that eliminate high-GWP refrigerants from imported equipment categories by 2030. Bavaria's brewing equipment clusters drive specification influence across European draft beer dispenser procurement.
China
Organized retail alcohol service expansion in Shanghai and Shenzhen creates positioning opportunities for energy-efficient under-counter lines. The country's national appliance efficiency standards push domestic manufacturers toward hydrocarbon refrigerant adoption. Yangtze River Delta fabrication hubs concentrate sealed-system production for export markets.
India
Organized retail alcohol service expansion in Mumbai and Bangalore creates first-mover positioning for energy-efficient under-counter lines. The Bureau of Indian Standards appliance certification requirements raise compliance barriers for imported equipment. Maharashtra's hospitality infrastructure investments concentrate new venue development in premium bar formats.
Japan
Precision temperature zoning requirements in Tokyo's high-end cocktail bars sustain demand for advanced control systems. The Ministry of Economy, Trade and Industry energy efficiency labeling programs accelerate variable-speed compressor adoption. Osaka's commercial kitchen equipment distribution networks anchor specification influence across western Japan.
Bar Refrigeration Market Vendor Landscape
Direct channel control dominates the current landscape as tier-one manufacturers tighten relationships with multi-unit operators. The vendor base concentrates around fabrication specialists with captive sealed-system capabilities and national account contracting infrastructure. Three strategic archetypes prevail: domestic stainless-steel fabricators, hydrocarbon sealed-system specialists, and energy-efficient compressor technology providers. M&A activity and geographic expansion represent the dominant competitive moves as players seek scale and refrigerant compliance breadth.
Among US-based fabricators, True Manufacturing Company, Inc., Continental Refrigerator, and Turbo Air Inc. exemplify the domestic stainless-steel and hydrocarbon specialization archetypes. True Manufacturing occupies a position tied to Missouri-based fabrication footprints. Continental Refrigerator sits within the construction-specialization tier. Turbo Air Inc. represents the energy-efficient technology vector for independent bar operators.
| Leading Market Players |
|---|
| True Manufacturing Company, Inc. |
| Continental Refrigerator |
| Turbo Air Inc. |
| Ali Group |
| ONNERA GROUP |
| Valpro Commercial Refrigeration |
| Perlick Corporation |
| Beverage-Air |
| Hoshizaki |
| Others |
Supply Flow & Price Mechanics
Multi-unit bar chains in California and New York anchor pricing power through national account contracts that compress distributor margins and favor direct manufacturer relationships with bundled service terms.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier sealed-system fabricators from unbundled economy suppliers competing on upfront unit cost alone. Three-tier pricing structure across premium, standard, and economy levels tracks UL 471 certification grade and hydrocarbon refrigerant charge thresholds. Cost compression in mid-tier stainless-steel fabrication is intensifying because of copper heat exchanger price volatility. Independent bar operators in Texas and Florida exhibit the highest price sensitivity, while craft brewery taproom chains with 50-plus locations prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Direct-to-operator channels handle multi-unit chain demand while commercial kitchen equipment distributors serve independent bar replacement cycles. Manufacturing concentrates in Missouri fabrication clusters, Yangtze River Delta sealed-system hubs, and Bavarian brewing equipment corridors. Raw material flows draw from Arizona and Chile copper sourcing corridors for heat exchanger coils, plus domestic steel service centers for stainless cabinet fabrication. Single-source vulnerability concentrates in Nidec and EBM-Papst variable-speed motor supply. Distribution runs through national account contracting infrastructure and regional foodservice equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive sealed-system fabrication and hydrocarbon refrigerant handling capabilities determine margin capture and compliance breadth.
For Market Incumbents: Lock in hydrocarbon sealed-system fabrication capacity through backward integration into compressor motor-controller development or captive heat exchanger coil production. Defend against emerging Asian fabricators by tightening direct channel control with national account contracts that specify R290 and R600a configurations. Prioritize EPA Section 608 technician certification programs to reduce field service response gaps that erode customer retention. For New Entrants and Emerging Players: IoT-enabled predictive maintenance algorithms offer a technology-first wedge into premium bar operator segments where subscription service revenue streams remain underdeveloped. Target underpenetrated organized retail alcohol service expansion in Mumbai and Bangalore with energy-efficient under-counter lines certified to Bureau of Indian Standards requirements. Pursue white-label manufacturing partnerships with Yangtze River Delta fabrication hubs to bypass capital-intensive sealed-system development timelines. For Investors and Strategic Acquirers: The window for entry favors hydrocarbon sealed-system specialists with UL 471 safety certifications and established EPA SNAP refrigerant approval pathways. Long-term viability hinges on refrigerant compliance breadth across US DOE efficiency tiers and European F-Gas Regulation phasedown quotas. Monitor EPA Section 608 technician certification expansion rates as an inflection indicator for hydrocarbon system deployment velocity and aftermarket service margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant Line Certification | UL 471 and EPA SNAP approvals unlock US market eligibility before HFC phase-down deadlines. |
| Variable-Speed Compressor Integration | DOE efficiency tier compliance secures procurement preference among California and New York operators. |
| National Account Contracting Infrastructure | Direct channel control with craft brewery taproom chains displaces traditional distributor influence. |
| IoT Predictive Maintenance Platform Launch | Temperature logging subscriptions create recurring revenue from independent bar operator segments. |
| Indian Market Certification Investment | Bureau of Indian Standards compliance captures first-mover positioning in Mumbai and Bangalore expansion. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with commercial kitchen equipment distributors, bar operations managers, sealed-system fabrication engineers, and EPA-certified refrigerant technicians combined with Foodservice Equipment & Supplies Association reports, US DOE appliance efficiency standard dockets, and import tariff schedules. Bottom-up unit shipment estimates triangulated against top-down value projections derived from manufacturer revenue disclosures and national account contract values.
Data-stream reconciliation across product type, cooling technology, end-user segment, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were computed from fitted growth curves applied to base-year market sizing across the projection horizon. Hydrocarbon refrigerant adoption curves, variable-speed compressor retrofit penetration rates, and F-Gas Regulation compliance cost escalations served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt refrigerant approval reversals or copper price spike scenarios. Periodic stress-testing of base assumptions is recommended given regulatory transition timelines and raw material sourcing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Food Contract Manufacturing Market
Food Service
Pasteurized Eggs Market
Food Service
Restaurant Takeout Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Healthy Takeout Market
Food Service
Food Trucks Market
Food Service
Turkey Food Service Market
Food Service
China Inflight Catering Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Global Digital Food Delivery Market
Food Service
Wok Market
Food Service
Global Digital Grocery Market