
 Asia-Pacific Food Away from Home Market | 2026-2036
Asia-Pacific Food Away from Home Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Away from Home Market Analytics
ISO 22000 food safety management certification is rotating as a gatekeeping standard across Asia-Pacific supply chains, determining which operators qualify for institutional procurement contracts. McDonald's Corporation leverages its cold-chain infrastructure to sustain quality consistency across fragmented Southeast Asian markets. Haidilao International Holding Ltd. anchors its expansion on theatrical dine-in service formats that command premium positioning in tier-one Chinese cities. Jollibee Foods Corporation dominates the Philippines while extending its brand architecture into North American diaspora communities.
Food away from home comprises commercially prepared meals consumed outside domestic kitchens, spanning quick-service counters to full-service restaurants with standardized portion controls, temperature-monitored holding equipment, and traceable ingredient sourcing protocols. The primary commercial purpose is to monetize convenience, social experience, and culinary variety for time-constrained urban populations. Fast food and casual dining together occupy the volume core, though fine dining captures disproportionate margin pools in Shanghai, Tokyo, and Singapore. Online ordering and delivery infrastructure is reshaping capital allocation, with ghost kitchens and aggregator-platform partnerships displacing traditional front-of-house investment.
FSSAI in India, SAMR in China, and Japan's Food Sanitation Act collectively enforce allergen labeling, hygiene grading, and digital traceability requirements that elevate compliance costs for smaller operators. These frameworks are tightening cross-border supply chain scrutiny, particularly for imported proteins and dairy inputs. Stakeholders must monitor regulatory divergence between national food safety regimes while calibrating menu localization against centralized procurement economics.
Market Dynamics
China's SAMR digitization mandates are compressing compliance timelines across commercial kitchens, forcing operators to reallocate capital from front-of-house aesthetics toward back-end traceability infrastructure and real-time temperature monitoring systems.
Growth Catalysts
- Urban wage corridors:Metropolitan wage growth in India is redirecting household food expenditure toward commercial dining, expanding the addressable base for quick-service and casual dining formats.
- FSSAI hygiene grading mandates:India's mandatory display of hygiene ratings creates competitive differentiation for compliant operators, accelerating format upgrades across tier-one and tier-two cities.
- Ghost kitchen infrastructure:Aggregator-platform partnerships and delivery-optimized production facilities are lowering entry barriers for digital-native food brands across Southeast Asian urban clusters.
Market Restraints
- Protein import scrutiny:Cross-border supply chain tightening for imported proteins and dairy inputs elevates procurement risk and working capital requirements for operators dependent on foreign sourcing.
- Cold-chain fragmentation:Inconsistent refrigerated logistics across Indonesian archipelago markets and Philippine island chains degrade quality consistency and expand spoilage losses.
- ISO 22000 certification costs:Gatekeeping certification requirements for institutional procurement contracts exclude smaller operators lacking capital for documentation and audit systems.
Strategic Opportunities
- Vietnamese secondary cities:Underpenetrated urban corridors outside Ho Chi Minh City and Hanoi present whitespace for standardized quick-service formats targeting emerging middle-class wage earners.
- Japan's Food Sanitation Act digitization:Regulatory tailwinds for electronic record-keeping create demand for integrated kitchen management platforms that bundle compliance with operational efficiency.
- Aggregator-platform convergence:Super-app ecosystems combining food delivery with grocery, transport, and financial services offer captive customer acquisition channels for restaurant partners.
Industry Challenges
- Food safety auditor scarcity:Shortage of certified auditors across India and Southeast Asia extends ISO 22000 and FSSAI compliance timelines, delaying market entry and contract eligibility.
- Legacy POS integration:Kitchen management system upgrades require costly middleware development to interface with entrenched point-of-sale infrastructure in established restaurant chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Away from Home Market |
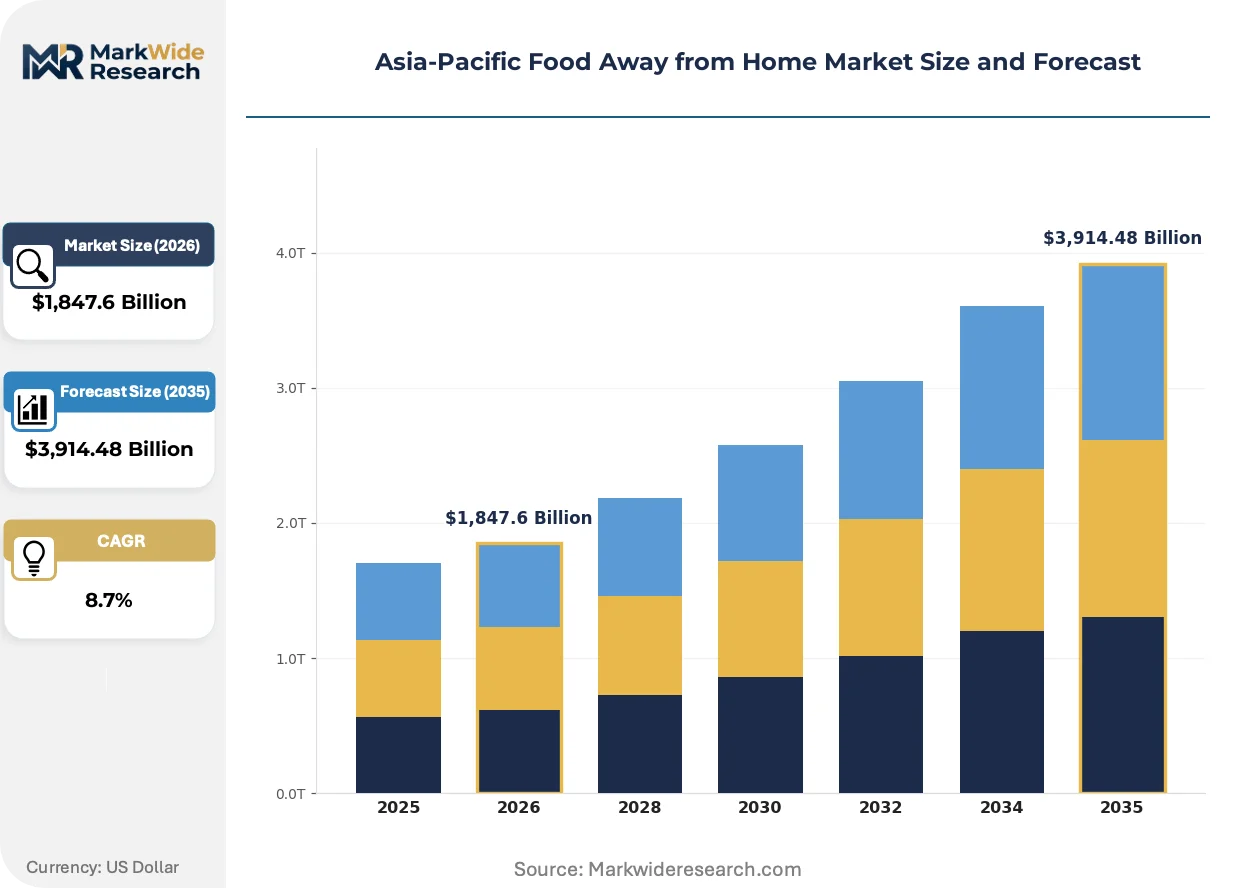
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,914.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Food Trucks Customer Type: Families, Young Adults, Business Travelers, Tourists Menu Type: Vegetarian, Vegan, Gluten-Free, Desserts Delivery Model: Dine-in, Takeout, Delivery, Online Ordering |
| Companies Covered | Jollibee Foods Corporation, Luckin Coffee Inc., McDonald's Corporation, Domino's Pizza, Restaurant Brands International Inc., Starbucks Corporation, Haidilao International Holding Ltd., CJ Freshway Corporation, Yum! Brands, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Away from Home Market Evolving Landscape
Kitchen operations across the Asia-Pacific region are undergoing systemic reconfiguration as regulatory pressure, platform economics, and shifting consumption patterns converge to redefine capital allocation and competitive positioning.
IoT-enabled temperature monitoring systems are supplanting manual logbook compliance across commercial kitchens. Quick-service chains in China and South Korea are deploying these sensors at scale, transmitting real-time data to SAMR-aligned traceability platforms. This infrastructure compression is collapsing the cost gap between institutional-grade and independent operators.
Japan's Food Sanitation Act amendments are mandating electronic documentation of allergen handling and hygiene protocols. The industrial consequence is accelerated software procurement by mid-size restaurant groups previously reliant on paper-based systems. Full-service operators in Tokyo and Osaka are responding fastest, integrating tablet-based kitchen display systems with automated compliance reporting.
Consumption patterns among young adults in Southeast Asian cities are rotating toward aggregator-platform discovery over brand loyalty. Quick-service counters and casual dining rooms are being displaced by delivery-optimized menus and dark kitchen formats. This shift is most visible in Bangkok and Jakarta, where front-of-house square footage is being repurposed for production volume rather than dine-in experience.
Asia-Pacific Food Away from Home Market Segmentation
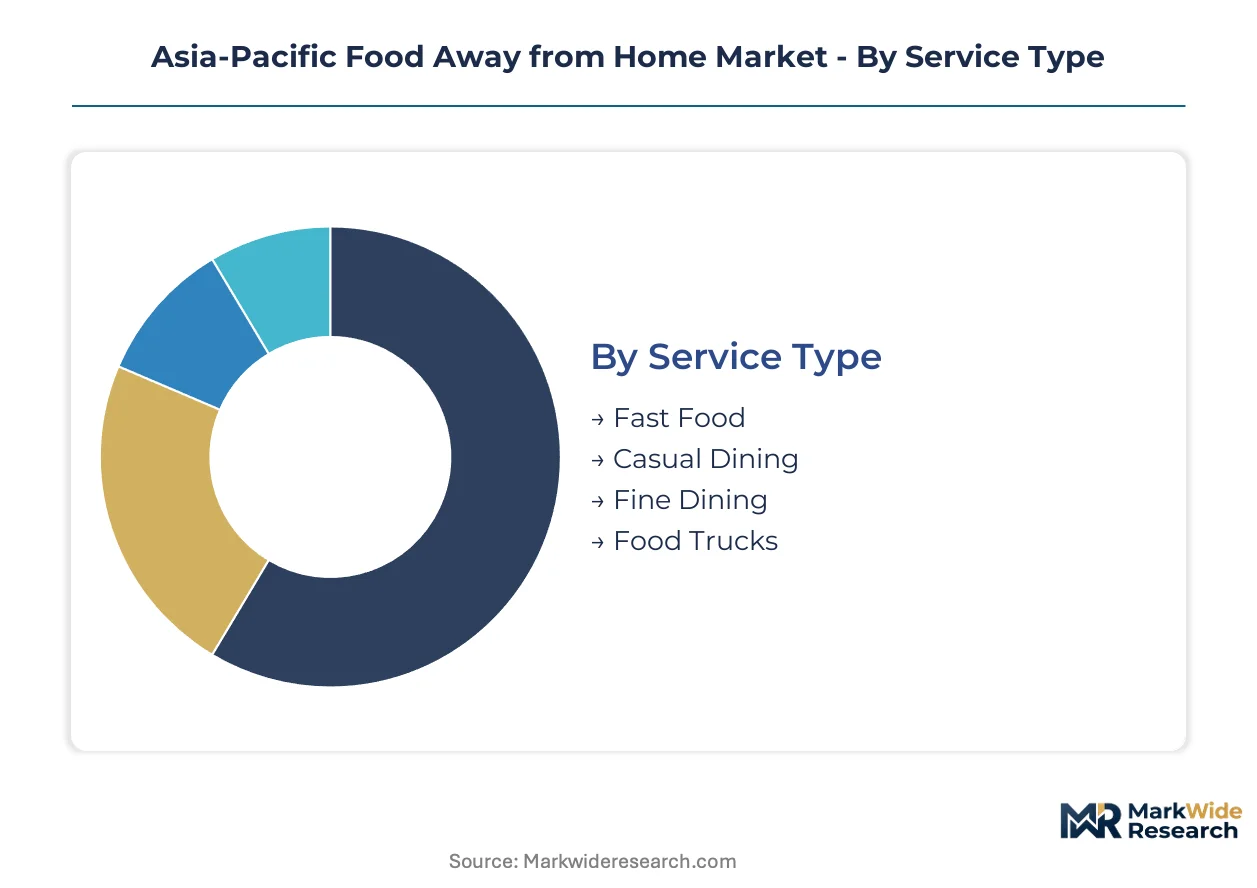
Segmentation in the Asia-Pacific Food Away from Home Market reveals divergent capital allocation patterns across service formats and consumption occasions. Operators calibrate format selection against urban density, wage corridors, and regulatory compliance thresholds that vary sharply across national boundaries.
Service Type:
Domestic consumption anchors fast food and casual dining expansion across Southeast Asian cities, while fine dining formats in Shanghai, Tokyo, and Singapore capture export-oriented tourism and business travel expenditure.
- Fast Food:Standardized portion controls and temperature-monitored holding equipment enable rapid replication across tier-two and tier-three Chinese cities. SAMR digitization mandates favor chains with capital for real-time traceability infrastructure.
- Casual Dining:Theatrical service formats command premium positioning in tier-one Chinese cities while aggregator-platform partnerships reshape front-of-house investment toward production volume. Haidilao's expansion model exemplifies this format's capital intensity.
- Fine Dining:Disproportionate margin pools concentrate in Shanghai, Tokyo, and Singapore where tourism and business travel sustain elevated price tolerance.
- Food Trucks:Lower entry barriers attract independent operators in Philippine and Indonesian urban clusters, though cold-chain fragmentation constrains menu complexity.
Fast Food commands the established base. The steepest expansion runs through Casual Dining.
Customer Type:
Cost tier differentiation separates family-oriented value formats from premium-positioned business and tourism segments across metropolitan corridors.
- Young Adults:Aggregator-platform discovery patterns dominate consumption behavior in Bangkok and Jakarta, displacing brand loyalty. Quick-service chains target this demographic with delivery-optimized menus and dark kitchen formats.
- Families:Value-engineered menus and standardized hygiene ratings drive format selection in Indian tier-one and tier-two cities where FSSAI grading mandates create competitive differentiation.
- Business Travelers:Premium dine-in and concierge-level service expectations concentrate demand in Shanghai, Singapore, and Tokyo central business districts.
- Tourists:Culinary variety and social experience monetization sustains fine dining and casual dining occupancy in destination cities across the region.
Families anchor volume throughput. Young Adults are gaining share fastest.
Menu Type:
Application-driven segmentation aligns with regulatory pressure on allergen labeling and ingredient traceability across national food safety regimes.
- Vegetarian:Religious and cultural dietary patterns sustain dominant positioning in Indian metropolitan corridors, with FSSAI compliance requirements elevating documentation standards for plant-based protein sourcing.
- Gluten-Free:Japan's Food Sanitation Act amendments on allergen handling accelerate adoption in Tokyo and Osaka full-service operations integrating electronic documentation systems.
- Vegan:Emerging middle-class wage earners in Vietnamese secondary cities drive nascent demand, though supply chain constraints on dairy alternatives limit format scalability.
- Desserts:Social media discovery patterns and aggregator-platform promotion sustain category relevance across Southeast Asian urban clusters.
Vegetarian formats hold the volume core. Gluten-Free specifications show the steepest compliance-driven upgrade trajectory.
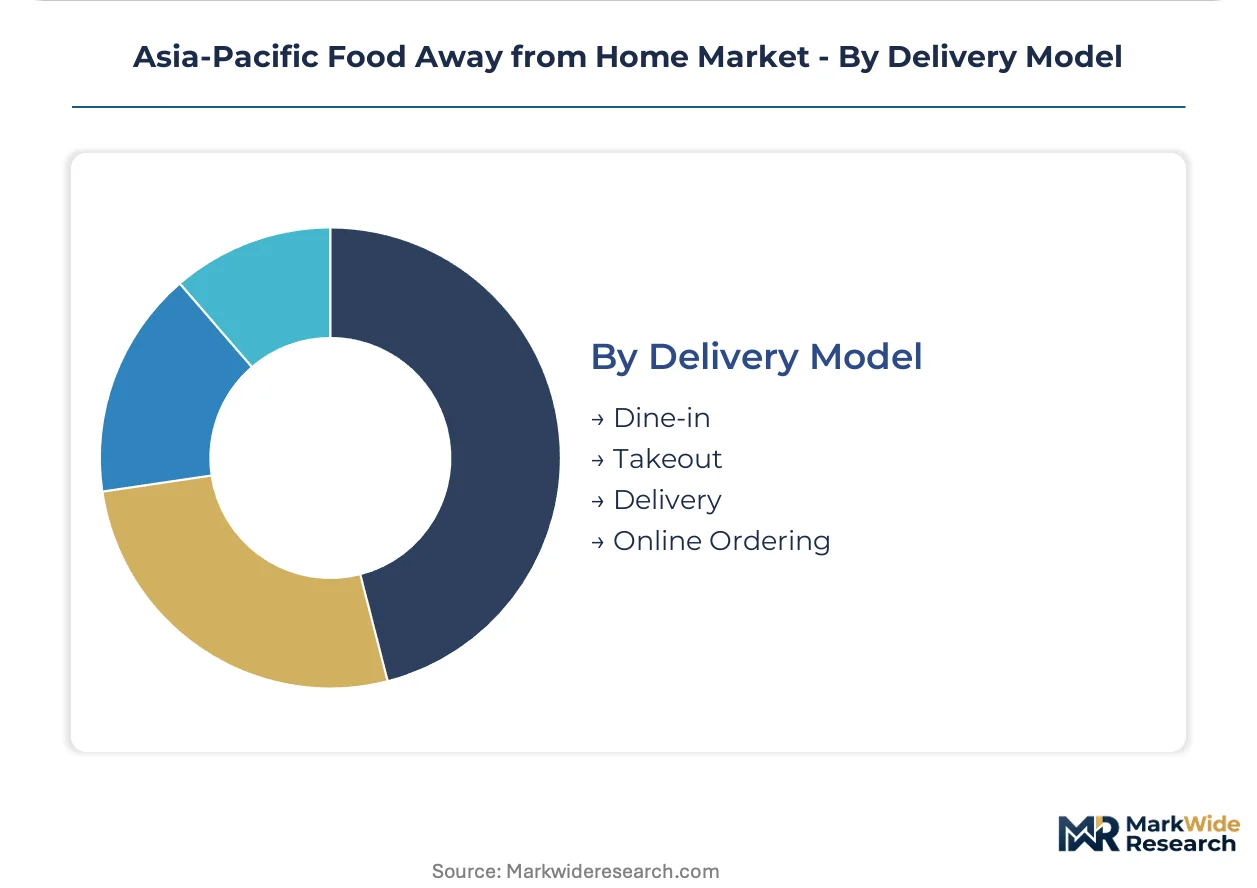
Delivery Model:
Supply concentration in aggregator-platform ecosystems is collapsing traditional front-of-house economics across the region's densest urban corridors.
- Online Ordering:Super-app ecosystems combining food delivery with grocery, transport, and financial services offer captive customer acquisition channels reshaping capital allocation toward digital infrastructure.
- Delivery:Ghost kitchen infrastructure and production-optimized facilities lower entry barriers for digital-native brands in Bangkok, Jakarta, and Ho Chi Minh City.
- Takeout:Quick-service counters repurpose square footage for production volume rather than dine-in experience across Philippine and Indonesian markets.
- Dine-in:Theatrical service formats and social experience monetization sustain relevance in tier-one Chinese cities and Japanese metropolitan areas.
Delivery captures the steepest capital reallocation. Dine-in retains margin concentration in premium urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR digitization mandates in China are compressing compliance timelines and redirecting capital toward back-end traceability infrastructure across the region's largest food service economy.
China
Urban wage growth in tier-one cities sustains demand for theatrical dine-in formats and premium casual dining. SAMR food safety digitization mandates enforce real-time temperature monitoring and electronic traceability documentation. Shanghai and Beijing anchor expansion for chains with capital to deploy IoT-enabled kitchen management systems.
India
Metropolitan corridors in Mumbai and Delhi-NCR redirect household food expenditure toward commercial dining as urban wages rise. FSSAI hygiene grading mandates create competitive differentiation through mandatory display of compliance ratings. Tier-one and tier-two cities accelerate format upgrades as standardized quick-service counters capture emerging middle-class demand.
Japan
Business travel and tourism sustain premium dine-in occupancy in Tokyo and Osaka central business districts. Food Sanitation Act amendments mandate electronic documentation of allergen handling and hygiene protocols. Full-service operators integrate tablet-based kitchen display systems with automated compliance reporting.
Vietnam
Emerging middle-class wage earners in secondary cities outside Ho Chi Minh City and Hanoi drive nascent demand for standardized quick-service formats. General food safety regulations elevate documentation standards for commercial kitchen operations. Da Nang and Hai Phong present whitespace for delivery-optimized production facilities targeting underpenetrated urban corridors.
Indonesia
Aggregator-platform discovery patterns dominate consumption behavior among young adults in Jakarta and Surabaya. National food safety frameworks tighten cross-border scrutiny for imported proteins and dairy inputs. Cold-chain fragmentation across the archipelago degrades quality consistency and elevates spoilage losses for operators dependent on refrigerated logistics.
Asia-Pacific Food Away from Home Market Competitive Landscape
Player mix skews toward multinational quick-service chains with established cold-chain infrastructure and regional full-service operators deploying theatrical service formats. Market structure concentrates around scale-driven logistics networks and compliance-capable procurement systems. Two strategic archetypes dominate: aggregator-platform integrated delivery specialists and institutional-grade certification holders. Competitive moves center on ghost kitchen infrastructure deployment and ISO 22000 certification acquisition for contract eligibility.
Among Philippines-based operators, Jollibee Foods Corporation exemplifies diaspora-market expansion architecture. Within the theatrical dine-in tier, Haidilao International Holding Ltd. occupies a position emphasizing premium service formats in tier-one Chinese cities. At the multinational quick-service vector, McDonald's Corporation anchors cold-chain consistency across fragmented Southeast Asian markets.
| Leading Market Players |
|---|
| Jollibee Foods Corporation |
| Luckin Coffee Inc. |
| McDonald's Corporation |
| Domino's Pizza |
| Restaurant Brands International Inc. |
| Starbucks Corporation |
| Haidilao International Holding Ltd. |
| CJ Freshway Corporation |
| Yum! Brands, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term procurement contracts with frozen protein suppliers lock in both supply access and price visibility for quick-service chains navigating SAMR traceability mandates and FSSAI hygiene grading requirements across Chinese and Indian metropolitan corridors.
Pricing Analysis
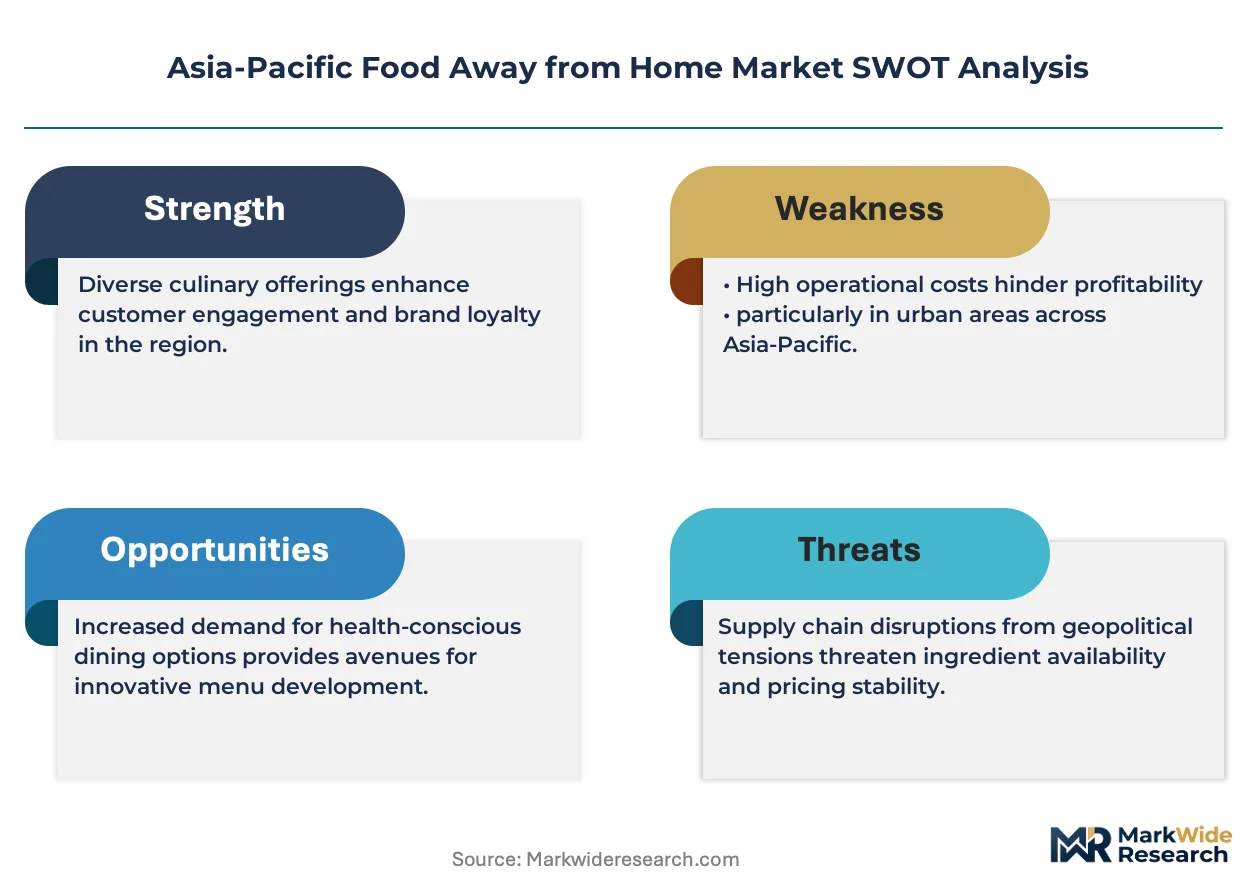
Certification level (ISO 22000-grade) creates the primary spread between institutional contract winners and excluded independents. Three-tier pricing structure across ISO-certified, FSSAI-graded, and ungraded operators reflects compliance capital intensity. Cost compression in the ungraded tier is intensifying because aggregator-platform commission structures squeeze already-thin margins. Family-oriented value formats in Indian tier-two cities show highest price sensitivity, while theatrical dine-in formats in Shanghai command lowest elasticity.
Supply Chain Analysis
China and Australia anchor imported protein sourcing for Southeast Asian quick-service expansion. Cold-chain logistics rest on refrigerated trucking networks and temperature-monitored holding equipment from South Korean manufacturers. Single-source vulnerability concentrates in Indonesian archipelago cold-chain gaps where inter-island ferry logistics degrade quality consistency. Distribution runs through aggregator-platform super-apps and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through aggregator-platform super-apps that bundle food delivery with grocery, transport, and financial services, consolidating restaurant discovery and customer acquisition behind single interfaces.
For Market Incumbents: Fortify cold-chain infrastructure across Philippine and Indonesian island chains to defend quality consistency against spoilage losses. Deepen backward integration into temperature-monitored holding equipment to offset logistics fragmentation. Prioritize ISO 22000 certification renewal ahead of institutional contract rebidding cycles.
For New Entrants and Emerging Players: Anchor in Vietnamese secondary cities outside Ho Chi Minh City and Hanoi where standardized quick-service formats remain underpenetrated. Target emerging middle-class wage earners in Da Nang and Hai Phong with delivery-optimized production facilities. Lead with aggregator-platform partnerships rather than front-of-house investment to minimize capital intensity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ghost kitchen operators with exclusive aggregator-platform contracts and digital-native brand portfolios. Five-to-ten-year viability favors compliance-capable mid-size chains with SAMR-aligned traceability infrastructure already deployed. Watch for FSSAI auditor scarcity easing as certification backlog clears, signaling accelerated format upgrade spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Infrastructure Deployment | Lowers entry barriers for digital-native brands in Bangkok and Jakarta aggregator ecosystems. |
| ISO 22000 Certification Acquisition | Unlocks institutional procurement contracts in India and Southeast Asian education sectors. |
| IoT-Enabled Temperature Monitoring Scale-Up | Compresses compliance cost gap between chains and independents under SAMR mandates. |
| Aggregator-Platform Super-App Integration | Captures captive customer acquisition channels combining delivery with grocery and transport. |
| Backward Integration into Cold-Chain Equipment | Offsets logistics fragmentation across Indonesian archipelago and Philippine island markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with restaurant chain procurement directors, FSSAI compliance officers, aggregator-platform partnership managers, and cold-chain logistics operators; and secondary validation through SAMR digitization filings, FSSAI hygiene grading databases, customs import records for frozen proteins, and SEC disclosures from listed food service operators. Bottom-up outlet counting and top-down expenditure modeling were triangulated against regional wage data.
Across the analysis window, forecasts were constructed using segmented modeling across service format, customer type, menu category, and delivery model dimensions. CAGRs were derived from trend extrapolation of urban wage growth, platform penetration curves, and regulatory compliance cost trajectories. Inputs included metropolitan household expenditure surveys and aggregator-platform order volume indices.
Material uncertainties — regulatory enforcement intensity variations, cold-chain infrastructure investment delays, and aggregator-platform commission structure changes — sit outside the modeled envelope. Forecasts reflect assumptions about continued urban wage growth and digitization mandate adherence. Recalibration cycles align with material shifts in SAMR and FSSAI regulatory implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Bahrain Food Service Market
Food Service
Global Dark Store Market
Food Service
Europe Vending Machine Market
Food Service
Commercial Ice Dispenser Market
Food Service
Europe Pizza Oven Market
Food Service
Steam Stew Pot Market
Food Service
United States Food Truck Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Global Vending Machine Market
Food Service
Commercial Tableware Services Market
Food Service
South Korea Foodservice Market
Food Service
Portion Cups Market
Food Service
Chained Consumer Foodservice Market
Food Service
Latin America Inflight Catering Market
Food Service
Turkey Food Service Market
Food Service
Commercial Kitchen Appliances Market