
 Bangladesh Food Service Market | 2026-2036
Bangladesh Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Food Service Market Insights
Multi-source ingredient procurement is pivoting toward centralized supply agreements as chains expand beyond Dhaka. Transcom Foods Limited leverages its Cold Storage network to sustain freshness guarantees across 40-plus outlets. PRAN-RFL Group anchors the processed ingredient segment with captive manufacturing of sauces and frozen items. Jubilant FoodWorks Limited competes through standardized kitchen protocols that reduce variance across franchise locations.
Bangladesh Food Service encompasses commercial preparation and sale of meals through organized and unorganized outlets, operating across temperature-controlled supply chains with HACCP-aligned protocols to ensure safety from raw material intake to final service. The sector serves urban consumers, corporate canteens, and institutional buyers requiring scalable, repeatable meal solutions. Fast Food and Online Ordering command disproportionate growth velocity as digital payment penetration and delivery logistics mature in dense urban corridors. Fine Dining occupies narrower volume but captures concentrated margin pools from expatriate and affluent Bangladeshi segments in Dhaka's premium zones.
Bangladesh Food Safety Authority mandates licensing under the Safe Food Act, while BSTI standards govern packaged ingredient quality entering commercial kitchens. Dhaka City Corporation enforces location-specific zoning and waste management rules that constrain street-vendor density in core business districts. Stakeholders must monitor regulatory harmonization between national food safety mandates and municipal enforcement capacities as the market formalizes.
Market Dynamics
The Bangladesh Food Service Market pivots on tightening hygiene mandates from the Bangladesh Food Safety Authority, which force kitchen infrastructure upgrades and consolidate procurement toward HACCP-certified suppliers. Cloud kitchens and quick-service chains absorb this compliance cost faster than fragmented street vendors, accelerating formalization.
Growth Catalysts
- Safe Food Act licensing:Mandatory BFSA permits push unorganized vendors toward certified cloud kitchen infrastructure, expanding addressable market for compliant equipment suppliers.
- Digital payment rails:bKash and Nagad penetration above 60% in Dhaka enables cashless delivery transactions, reducing order friction for quick-service aggregators.
- Gulshan-Banani corridor density:Corporate office concentration in this Dhaka zone generates predictable weekday lunch demand, anchoring cloud kitchen placement algorithms.
Market Restraints
- Imported equipment tariffs:Commercial refrigeration and ventilation systems face 25-45% import duties, inflating capex for HACCP-compliant kitchen builds.
- Dhaka-centric supply concentration:Temperature-controlled logistics providers cluster in the capital, leaving Chattogram and Sylhet with higher spoilage rates and limited frozen protein access.
- Natural gas rationing:Titas Gas Transmission imposes periodic supply curbs on commercial kitchens, forcing LPG fallback that raises per-meal energy costs.
Strategic Opportunities
- Chattogram port zone underpenetration:Industrial worker density near the port lacks organized meal solutions, creating first-mover space for corporate canteen contractors.
- ISO 22000 certification arbitrage:Early adopters of international food safety standards gain preferential supplier status with multinational manufacturers expanding manufacturing in Bangladesh.
- AI-driven demand forecasting:Integration of POS data with delivery platform algorithms reduces ingredient waste for cloud kitchens operating multiple virtual brands from shared prep lines.
Industry Challenges
- HACCP auditor shortage:Bangladesh Food Safety Authority certifies fewer than 200 qualified inspectors nationwide, creating 6-12 month licensing backlogs for new entrants.
- Legacy POS integration:Established quick-service chains operate fragmented payment and inventory systems that resist real-time synchronization with third-party delivery aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Food Service Market |
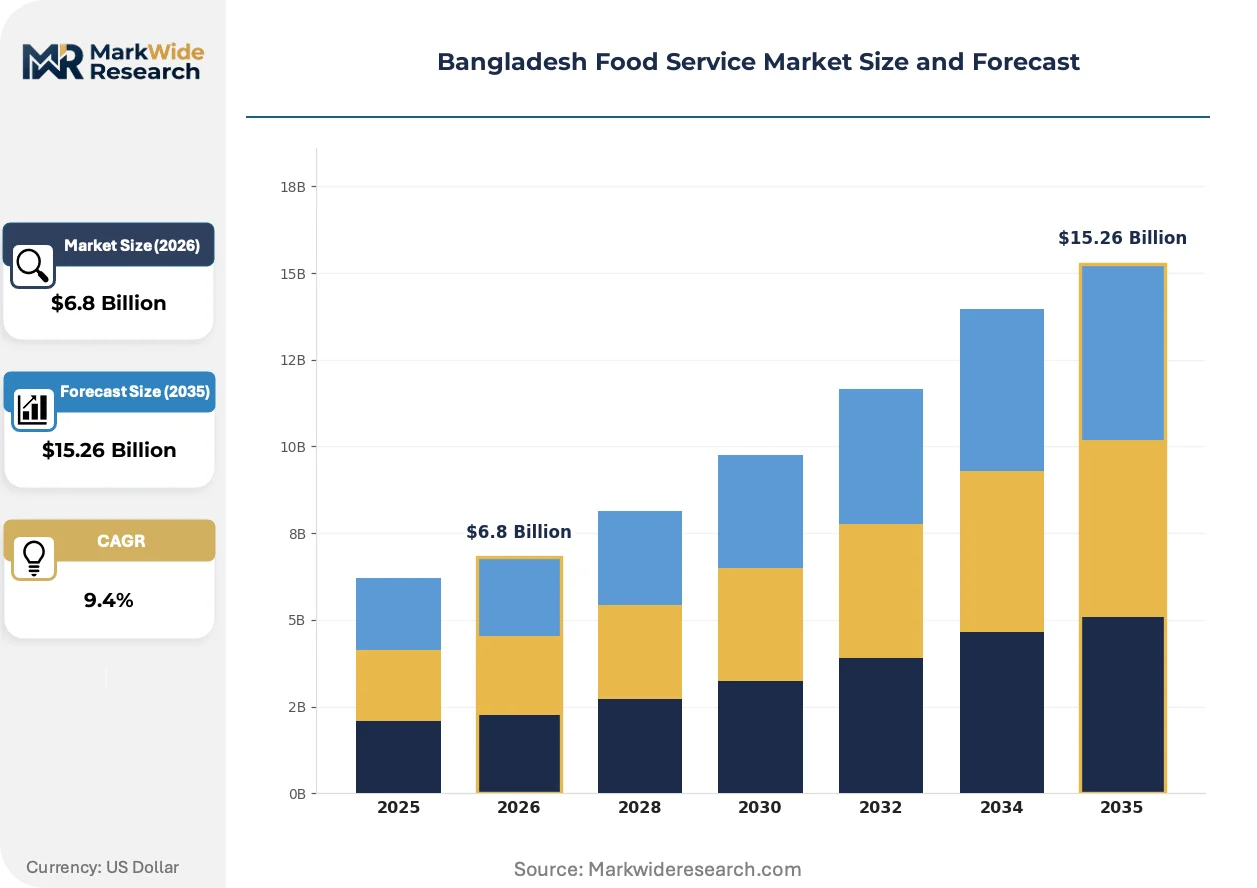
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Cafes End User: Households, Corporates, Educational Institutions, Healthcare Facilities Distribution Channel: Dine-in, Takeaway, Delivery, Online Ordering Cuisine Type: Bengali, Chinese, Indian, Italian |
| Companies Covered | Herfy Food Service Company, CP Bangladesh Co Ltd, Transcom Foods Limited, Peyala Cafe, Chillox, Jubilant FoodWorks Limited, The Manhattan Fish Market, Tiffin Box Ltd, PRAN-RFL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Food Service Market Trends and Innovations
Automation and regulatory digitization are compressing operational timelines across Bangladesh food service, while procurement centralization reconfigures supplier relationships. These shifts favor capitalized players with compliance infrastructure over fragmented traditional operators.
Smart kitchen display systems integrating order aggregation from multiple delivery platforms is electrifying ticket management in Dhaka's cloud kitchens. Operators running three to five virtual brands from single prep facilities adopt these systems to synchronize cook times across disparate menus. The technology compresses labor coordination overhead and reduces order error rates that previously eroded aggregator ratings.
Bangladesh Food Safety Authority's phased rollout of digital traceability requirements under Safe Food Act amendments imposes ingredient sourcing documentation on all licensed commercial kitchens. Processed protein and dairy suppliers must now provide batch-level certificates of analysis, creating compliance friction for informal wet-market sourcing. Quick-service chains with captive supply agreements through PRAN-RFL Group and similar integrated processors absorb this transition faster than independent restaurants.
Corporate canteen outsourcing is displacing in-house kitchen operations among Bangladeshi garment manufacturers and pharmaceutical firms. Third-party food service contractors assume meal provision liability while offering ISO 22000-certified menus that satisfy multinational buyer audits. This shift concentrates procurement volume with organized caterers in Dhaka's export processing zones and Chattogram's industrial belts, marginalizing small independent vendors previously serving factory gates.
Bangladesh Food Service Market Segmentation
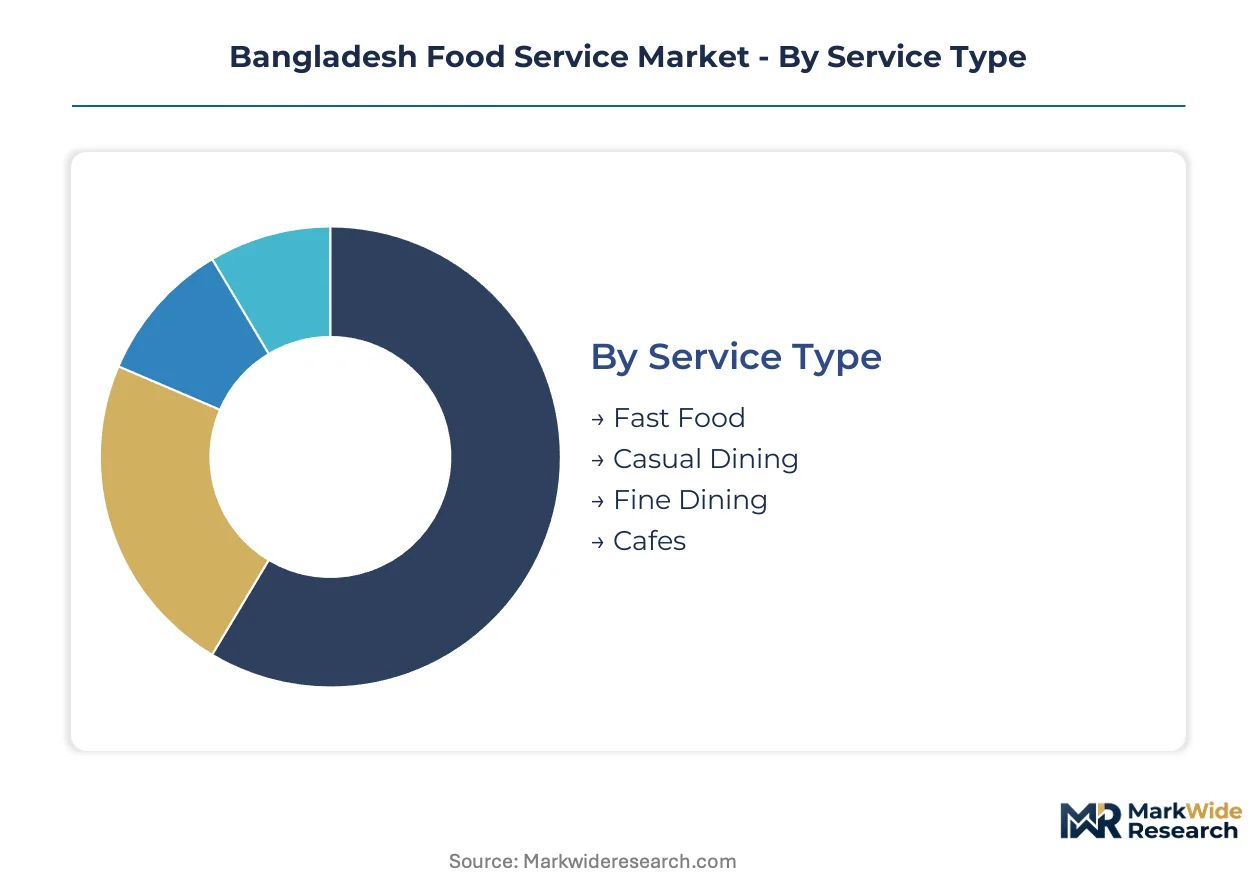
Segmentation reveals how Bangladesh food service operators configure their value propositions around distinct buyer contexts. Each dimension exposes different cost structures, regulatory exposure, and technology requirements that determine competitive viability.
Service Type:
Speed of service and capital intensity drive how operators position against Dhaka's constrained real estate and labor markets.
- Fast Food:Standardized menus executed through assembly-line kitchen layouts with minimal skilled labor. Demand clusters in Gulshan-Banani corridor lunch rushes and university-adjacent zones where price-sensitive students prioritize speed over ambiance.
- Casual Dining:Full-service formats with moderate check averages and extended dwell times. Chattogram's port zone industrial workers and Dhaka's emerging middle-class families in Mirpur-Dhanmondi drive expansion as disposable incomes rise.
- Fine Dining:Chef-driven concepts targeting expatriate communities and affluent Bangladeshi households in Baridhara and Uttara. Limited scale but elevated margins support imported ingredient sourcing and specialized wine licensing.
- Cafes:Beverage-forward formats with light meal accompaniment, concentrated in coworking clusters and retail mall food courts.
Fast Food leads on scale; Fine Dining leads on momentum.
End User:
Contract reliability and payment predictability separate institutional buyers from volatile consumer demand.
- Households:Individual and family consumption through discretionary outings or delivery aggregation. Weekend dining patterns and festival-season spikes create capacity planning challenges for operators.
- Corporates:Third-party canteen contracts and business catering for manufacturing and service sector employers. ISO 22000 certification requirements from multinational buyers filter vendor eligibility.
- Educational Institutions:School and university meal programs with price-capped tenders and nutritional compliance mandates from the Bangladesh Food Safety Authority.
- Healthcare Facilities:Therapeutic and standard patient feeding with stringent hygiene protocols and dietician oversight requirements.
Corporates anchor procurement volume; Healthcare Facilities impose the steepest compliance barriers.
Distribution Channel:
Channel mix determines technology stack requirements and aggregator dependency.
- Dine-in:Traditional table service with front-of-house labor intensity and rent burden concentrated in premium Dhaka locations.
- Takeaway:Counter-service pickup with lower square footage requirements, common in street-front quick-service formats.
- Delivery:Platform-mediated fulfillment through Pathao, Foodpanda, and emerging local aggregators. Commission structures and rating algorithms reshape kitchen operations.
- Online Ordering:Direct-to-consumer digital channels bypassing aggregator fees, requiring proprietary app development and payment gateway integration.
Delivery commands the steepest expansion trajectory; Dine-in retains margin superiority where location permits.
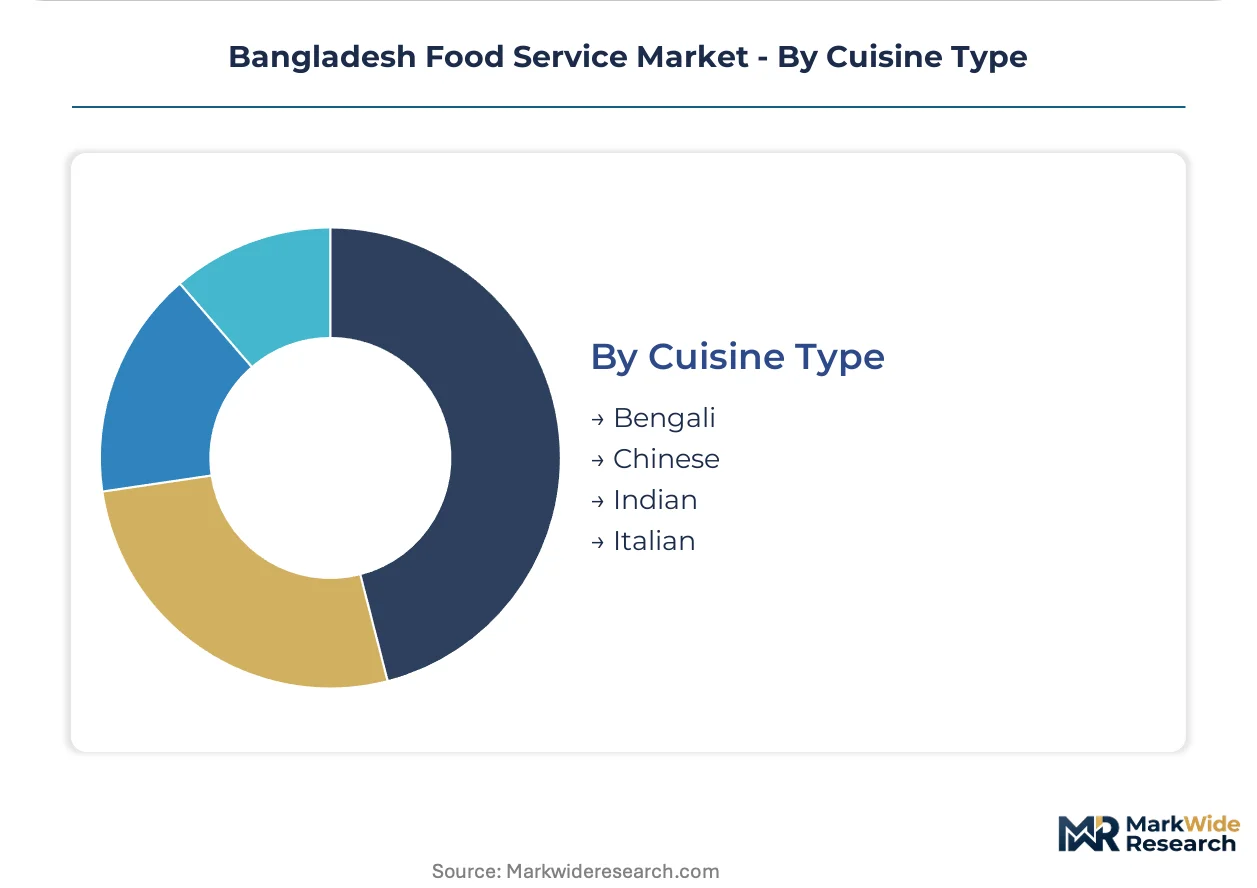
Cuisine Type:
Ingredient sourcing complexity and skill availability constrain format proliferation.
- Bengali:Indigenous flavor profiles with freshwater fish, mustard oil, and spice-forward preparations. Domestic supply chains minimize import dependency and currency risk.
- Chinese:Adapted Indo-Chinese hybrid cuisine with established supplier networks for soy sauces and specialty condiments through PRAN-RFL Group distribution.
- Indian:North Indian tandoor and South Indian dosa formats requiring specialized equipment and trained tandoor operators in short supply.
- Italian:Pizza and pasta concepts dependent on imported cheese and cured meats facing tariff-inflated input costs.
Bengali formats dominate volume penetration; Italian concepts gain share fastest among premium positioning strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
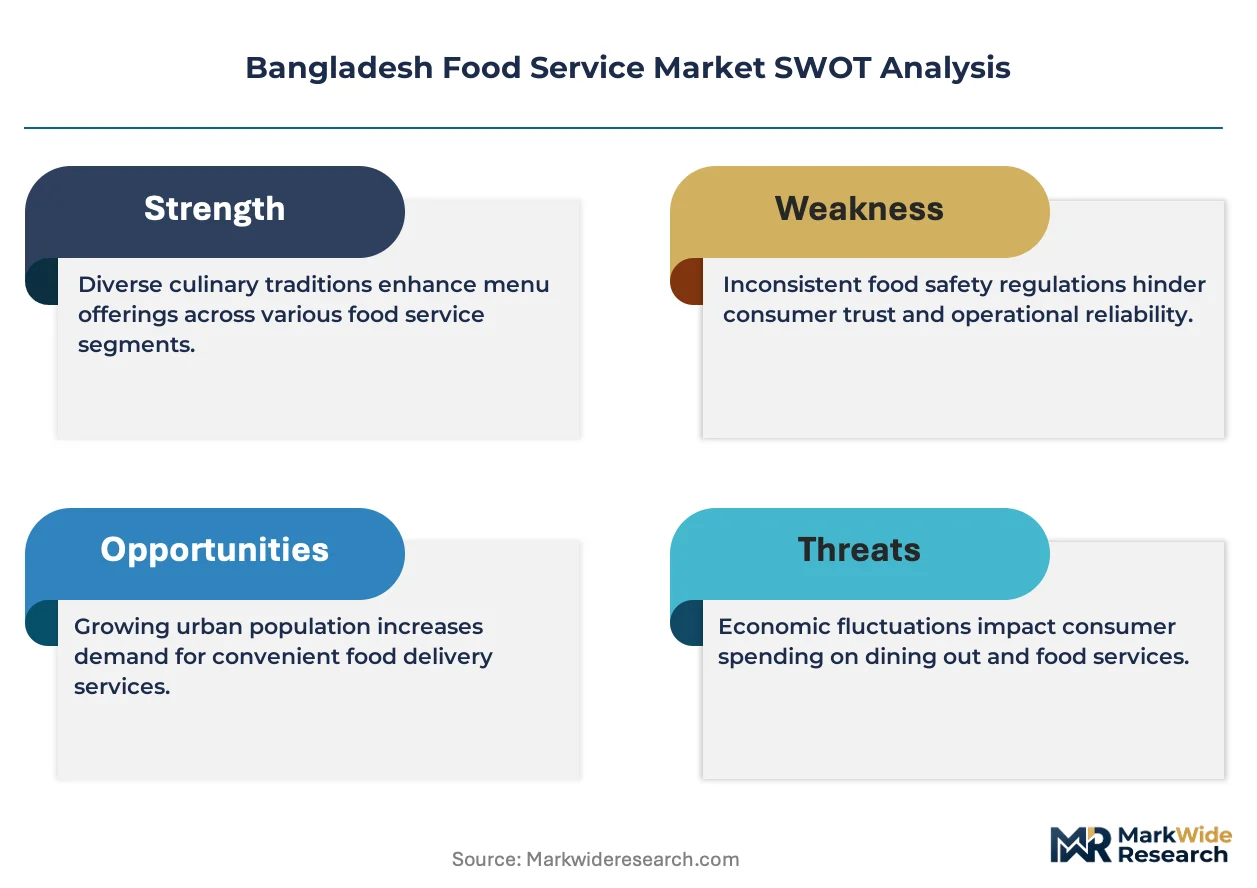
Regulatory arbitrage is accelerating kitchen infrastructure migration toward Chattogram and Sylhet as compliance costs in Dhaka force operators to seek lower-cost HACCP certification pathways. The Bangladesh Food Safety Authority's uneven enforcement capacity creates geographic gradients where formalization proceeds at different speeds.
Dhaka Division
Gulshan-Banani corridor concentration drives premium cloud kitchen placement as corporate lunch demand anchors weekday revenue predictability. Dhaka City Corporation enforces strict zoning that displaces street vendors from core business districts. Temperature-controlled logistics providers cluster in Tejgaon and Mohammadpur industrial zones, supporting frozen protein distribution to quick-service chains.
Chattogram Division
Port zone industrial worker density generates unmet demand for organized canteen contractors serving garment and shipping enterprises. Bangladesh Export Processing Zone Authority mandates ISO 22000-certified meal provision for multinational buyer audits. Halishahar and Patenga industrial belts concentrate third-party food service contracts displacing informal factory-gate vendors.
Sylhet Division
Remittance-funded consumption supports casual dining expansion among diaspora-connected households with elevated disposable incomes. Sylhet City Corporation implements location-specific waste management rules constraining unorganized vendor density in commercial cores. Zindabazar and Amberkhana retail corridors attract quick-service franchises targeting middle-class families.
Rajshahi Division
Educational institution meal programs create price-capped tender opportunities with nutritional compliance mandates from the Bangladesh Food Safety Authority. Rajshahi City Corporation enforces municipal licensing that filters vendor eligibility for school and university contracts. Boalia and Shaheb Bazar commercial zones concentrate budget-oriented fast-food outlets serving student populations.
Bangladesh Food Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud kitchen virtualization and aggregator-dependent delivery models. The market structures around three tiers: integrated conglomerates with captive supply chains, franchise operators leveraging standardized protocols, and asset-light virtual brands sharing prep facilities. Consolidation pressures favor capitalized players absorbing HACCP compliance costs while fragmented street vendors face licensing attrition. Dominant competitive moves include backward integration into ingredient processing and strategic partnerships with delivery platforms.
Within the integrated conglomerate tier, Transcom Foods Limited and PRAN-RFL Group exemplify players combining captive manufacturing with retail network control. Jubilant FoodWorks Limited occupies a position representing franchise-standardization archetypes. These entities anchor competitive dynamics through supply chain configuration rather than front-of-house differentiation.
| Leading Market Players |
|---|
| Herfy Food Service Company |
| CP Bangladesh Co Ltd |
| Transcom Foods Limited |
| Peyala Cafe |
| Chillox |
| Jubilant FoodWorks Limited |
| The Manhattan Fish Market |
| Tiffin Box Ltd |
| PRAN-RFL Group |
| Others |
Pricing and Supply Chain Analysis
HACCP certification tiers split Bangladesh food service operators into divergent cost structures that propagate through both menu pricing and procurement configurations. Premium quick-service chains absorb Bangladesh Food Safety Authority compliance costs through centralized supply agreements, while unorganized vendors face margin compression from informal wet-market sourcing that fails digital traceability mandates.
Pricing Analysis
Distributor margin layers concentrate pricing power with integrated conglomerates controlling captive manufacturing. Three-tier pricing structure across premium ISO-certified, standard licensed, and informal economy segments reflects compliance grade and volume scale differentiation. Pricing pressure stems from imported equipment tariffs inflating kitchen capex, forcing LPG fallback during natural gas rationing. Corporate canteen contractors show least price sensitivity due to multinational audit mandates, while street vendors face acute margin compression from licensing attrition.
Supply Chain Analysis
Multi-supplier qualification requirements from Bangladesh Food Safety Authority digital traceability rules reshape procurement toward HACCP-certified processors. Geographic supply concentration draws from domestic PRAN-RFL Group manufacturing, Indian condiment imports, and Chinese equipment sourcing. Raw material dependencies center on freshwater fish from Barisal, mustard oil from Rajshahi, and frozen protein from Chattogram port zone cold storage. Single-source vulnerability runs through Tejgaon temperature-controlled logistics clustering. Distribution runs through Transcom Foods Limited cold storage networks feeding quick-service chains, cloud kitchen aggregators, and corporate canteen contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Bangladesh food service hinges on compliance cost absorption by capitalized players as HACCP infrastructure investments create sustainable premium-tier separation from informal competitors.
For Market Incumbents: Anchor cloud kitchen density in Gulshan-Banani corridor through smart kitchen display systems synchronizing multi-brand prep lines. Deepen backward integration into processed ingredient manufacturing to offset imported protein tariff exposure. Counter street vendor displacement by Bangladesh City Corporation zoning through certified satellite kitchen networks in peripheral Dhaka zones. For New Entrants and Emerging Players: Chattogram port zone industrial canteen contractors represent an underserved buyer archetype with ISO 22000 audit requirements from Bangladesh Export Processing Zone Authority. Halishahar garment manufacturing clusters lack organized meal solutions despite predictable weekday demand. Target corporate canteen outsourcing contracts through third-party food service contractors assuming meal provision liability for multinational buyer compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where HACCP auditor shortages create 6-12 month licensing backlogs that fragment vendor eligibility. Long-term viability favors asset-light virtual brands sharing prep facilities over front-of-house rent burdens in premium Dhaka locations. Acquisition target archetype: cloud kitchen operators with multi-brand aggregation technology and Bangladesh Food Safety Authority licensing. Signal to watch: Bangladesh Food Safety Authority digital traceability mandate enforcement acceleration formalizing procurement toward certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | Accelerates licensing approval through Bangladesh Food Safety Authority inspector capacity constraints. |
| Cloud Kitchen Infrastructure Expansion | Captures corporate lunch demand density in Gulshan-Banani corridor through virtual brand aggregation. |
| Backward Integration into Ingredient Processing | Reduces import dependency through PRAN-RFL Group-style captive sauce and frozen item manufacturing. |
| Corporate Canteen Outsourcing Contracts | Locks predictable volume from Bangladesh Export Processing Zone Authority multinational audit requirements. |
| Smart Kitchen Display System Deployment | Compresses labor coordination overhead across multi-brand prep lines in shared cloud kitchen facilities. |
Research Methodology
Direct dialogue with cloud kitchen operators, quick-service chain procurement heads, Bangladesh Food Safety Authority licensing officers, corporate canteen contractors, and temperature-controlled logistics providers grounded the qualitative foundation. Secondary validation drew from Bangladesh Export Processing Zone Authority compliance filings, Dhaka City Corporation zoning records, customs import data on commercial kitchen equipment, and Bangladesh Food Safety Authority digital traceability mandate amendments. Bottom-up outlet counting across Dhaka, Chattogram, Sylhet, and Rajshahi divisions combined with top-down consumer expenditure modeling for triangulation.
Value projections across the analysis window emerged from segment-level modeling of service type, end user, distribution channel, and cuisine type dimensions. CAGRs derived from historical trajectory analysis adjusted for Safe Food Act licensing acceleration, digital payment penetration curves, and cloud kitchen virtual brand proliferation. Industry-specific forecast inputs incorporated Titas Gas Transmission rationing patterns and Chattogram port zone industrial worker meal program tender schedules.
Underlying measurement precision varies by segment; formal quick-service chains and corporate canteen contractors carry tighter precision than fragmented street vendor estimates. Forecasts reflect assumptions around Bangladesh Food Safety Authority inspector capacity expansion and digital traceability mandate phased rollout timing. Deviation in natural gas supply stability or imported equipment tariff rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Switzerland Food Service Market
Food Service
US Food Trucks Services Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Vacuum Flask Market
Food Service
United States Foodservice Market
Food Service
Sandwich Toasters Market
Food Service
Cutting Boards Market
Food Service
Food and Grocery Retail Market
Food Service
Thailand Food Service Market
Food Service
Portion Cups Market
Food Service
Latin America Online Grocery Market
Food Service
Online Catering Market
Food Service
Full-Service Restaurants Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Instant Grocery Market