
 Beverage Vending Machine Market | 2026-2036
Beverage Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Vending Machine Market Analytics
ISO 9001 quality management certification is unwinding vendor eligibility across institutional procurement channels, forcing smaller fabricators toward third-party audit investments. Fuji Electric Co., Ltd. leverages its refrigeration compressor integration to control unit cost structures in Asian deployments. Crane Co. anchors North American market presence through direct service networks that minimize downtime for hospital and office clients. Azkoyen Group differentiates via cashless payment module specialization across European transit systems.
A beverage vending machine is an electromechanical dispensing unit engineered to store, chill or heat, and deliver packaged or freshly prepared drinks upon payment verification, typically operating within temperature bands of 2°C to 65°C depending on product category. These units serve commercial environments requiring unattended retail access with minimal labor overhead. Cold beverages occupy the dominant revenue position given year-round consumption patterns, while healthy drinks represent the fastest-expanding product type as sugar taxation spreads. Cashless payment technology commands premium placement economics, though energy-efficient refrigeration modules capture margin pools through utility rebate eligibility.
The US FDA governs contact-surface materials and sanitation protocols for machines dispensing freshly prepared beverages, while EU F-Gas Regulation constrains refrigerant selection and drives retrofit investment cycles across European installed bases. Japan's METI enforces standby power limits that reshape component sourcing for units destined for East Asian markets. Stakeholders must weigh refrigerant transition timelines against cashless infrastructure upgrade priorities when allocating capital across regional portfolios.
Market Dynamics
Cashless payment mandates are compressing procurement timelines across institutional buyers, forcing simultaneous hardware retrofit cycles alongside refrigerant compliance upgrades. This dual-transition pressure concentrates vendor selection around integrated solution providers capable of delivering payment modules and energy-efficient cooling systems within unified deployment schedules.
Growth Catalysts
- ISO 9001 Certification Mandates:Institutional procurement channels now require quality management certification, expanding addressable market for audit-compliant fabricators while disqualifying uncertified competitors from hospital and university contracts.
- Japan METI Standby Power Directives:Energy-efficiency regulations are accelerating replacement cycles across East Asian installed bases, creating pull-through demand for compressor and control system upgrades.
- Transit Hub Modernization:Urban density in Germany, China, and the United States supports high-footfall placement economics, with rail and airport authorities expanding unattended retail infrastructure.
Market Restraints
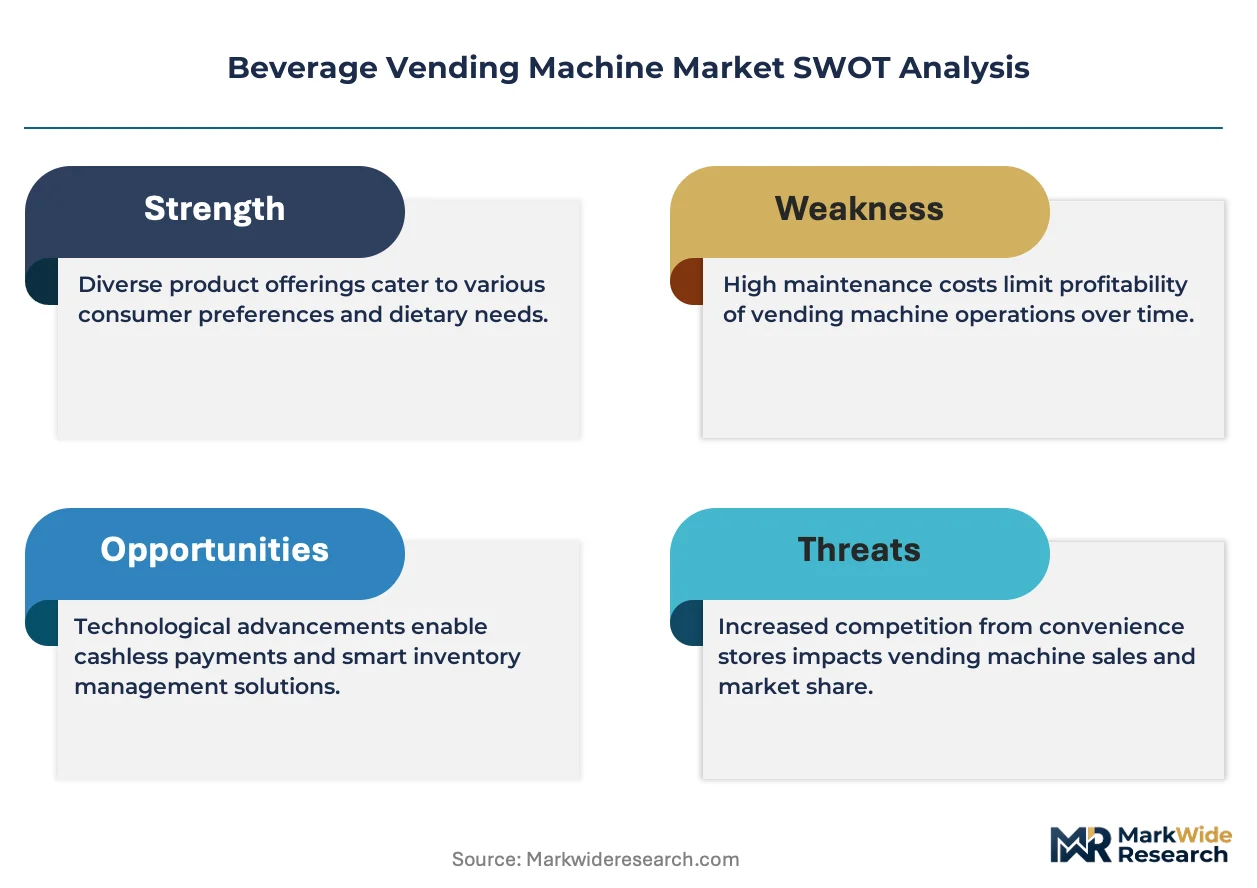
- Refrigerant Input Volatility:EU F-Gas Regulation constrains hydrofluorocarbon supply, elevating compressor unit costs and compressing margins for European-focused manufacturers.
- Component Supply Concentration:Asian compressor fabrication concentrates in specific manufacturing clusters, exposing procurement timelines to regional logistics disruptions.
- Cashless Infrastructure Substitution:Mobile payment platform proliferation threatens standalone vending terminal relevance where smartphone penetration exceeds machine density.
Strategic Opportunities
- Healthy Beverage Category Expansion:Sugar taxation spreading across OECD markets creates white space for low-sugar and functional drink dispensing configurations.
- Utility Rebate Capture:Energy-efficient refrigeration modules qualify for rebate programs in multiple jurisdictions, enabling premium pricing through total-cost-of-ownership positioning.
- Hospital Channel Penetration:Direct service network capabilities unlock 24/7 beverage access in medical facilities where downtime tolerance approaches zero.
Industry Challenges
- Dual Certification Timelines:Simultaneous ISO 9001 quality audits and refrigerant compliance testing extend product launch cycles, compressing competitive response windows.
- Legacy Payment System Integration:Retrofitting cashless modules onto existing machine bases requires firmware reconciliation with aging mechanical dispensing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Vending Machine Market |
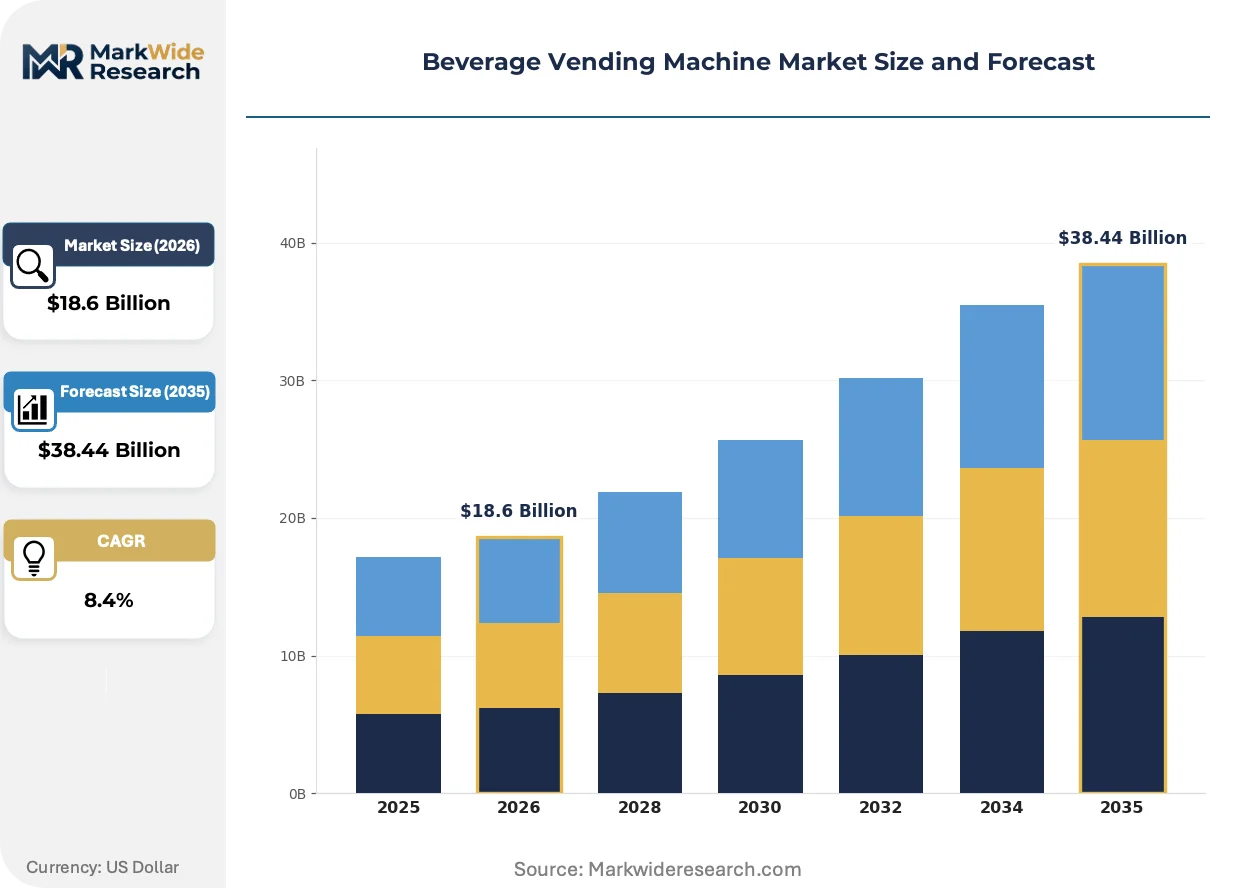
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Beverages, Hot Beverages, Healthy Drinks, Carbonated Drinks End User: Offices, Schools, Hospitals, Retail Stores Technology: Cashless Payment, Interactive Displays, Energy Efficient, Refrigeration Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | The Coca-Cola Company, PepsiCo, Inc., Fuji Electric Co., Ltd., Crane Co., Azkoyen Group, Royal Vendors, Inc., Seaga Manufacturing, Inc., Westomatic Vending Services Ltd., Compass Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Vending Machine Market Evolving Landscape
Refrigeration and payment technologies are diverging into parallel development tracks, with vendors forced to synchronize cooling efficiency gains against digital transaction security upgrades. This dual-technology pressure favors integrated manufacturers over component assemblers.
Smart refrigeration systems utilizing variable-speed compressor control and IoT-enabled temperature monitoring are bifurcating the installed base. Corporate campus operators are adopting these units fastest, prioritizing utility rebate eligibility over upfront capital minimization. The technology is bifurcating vendor tiers into energy-certified specialists versus legacy mechanical suppliers.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerant quotas through 2030. European fabricators must redesign cooling circuits around natural refrigerants or low-global-warming-potential alternatives. Cold beverage configurations face the steepest retrofit investment given their continuous compressor duty cycles.
Freshly prepared beverage demand is rotating procurement criteria toward sanitation-certifiable contact surfaces. US FDA material compliance now filters vendor pools for hospital and food-service deployments. Germany and Japan are observing similar specification tightening, though through industry association standards rather than direct regulator mandates.
Beverage Vending Machine Market Segmentation
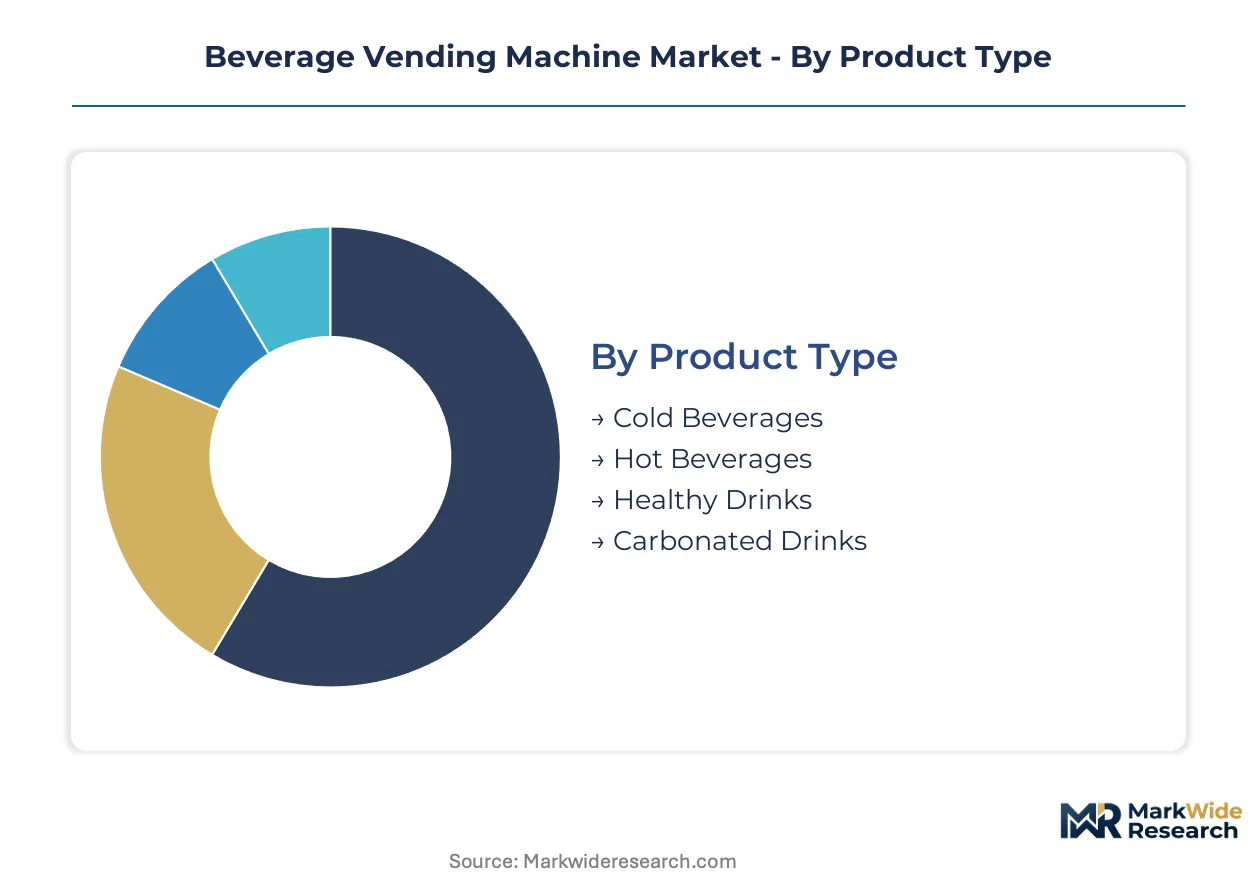
Segmentation in beverage vending machines reveals how procurement criteria diverge across institutional buyers. Payment technology mandates and energy-efficiency regulations create distinct upgrade cycles that reshape vendor selection priorities. Understanding these fault lines clarifies where capital allocation concentrates and which configurations face obsolescence pressure.
Product Type:
Cold beverage configurations face the most acute substitution pressure from micro-market formats and grab-and-go retail, while hot beverage units benefit from limited alternative access in transit and medical environments.
- Cold Beverages:These units deploy continuous-cycle refrigeration compressors maintaining 2°C to 8°C storage bands for packaged sodas, juices, and bottled water. Demand concentrates in United States corporate campuses and German transit hubs where high ambient temperatures and extended operating hours justify capital-intensive cooling infrastructure. Sugar taxation across OECD markets is compressing margins on conventional sugary drinks.
- Healthy Drinks:Machines configured for low-sugar, functional, and protein-enhanced beverages require expanded SKU flexibility and adjustable temperature zoning. Schools in Japan and hospitals in Germany are deploying these units fastest as institutional wellness mandates harden procurement specifications. Refrigeration systems must accommodate dairy-based and preservative-free formulations with stricter temperature controls.
- Hot Beverages:Coffee and tea dispensing systems utilize thermoblock or boiler heating elements operating at 65°C to 85°C output temperatures. Office deployments in China sustain volume.
- Carbonated Drinks:Traditional cola and sparkling water configurations dominate legacy installed bases. United States convenience retail retains concentration.
Cold Beverages retains volume leadership; Healthy Drinks holds the steepest expansion curve.
End User:
Cost tier stratification separates premium-specification medical deployments from price-sensitive educational procurement, with downtime tolerance serving as the critical differentiator.
- Hospitals:These installations demand 99.9% uptime guarantees, HACCP-compatible contact surfaces, and direct service network coverage with sub-four-hour response commitments. Japan's acute care facilities and Germany's university medical centers are expanding 24/7 beverage access for staff and visitors. FDA material compliance filters vendor pools aggressively.
- Offices:Corporate campuses in the United States and China are retrofitting fastest, prioritizing cashless payment integration and utility rebate-eligible refrigeration over upfront cost minimization. Lease-versus-buy decisions increasingly favor service-inclusive operating contracts.
- Schools:Educational procurement emphasizes sugar-content restrictions and vandal-resistant mechanical design. District-level contracts in Germany aggregate volume.
- Retail Stores:Convenience and grocery channels face margin compression from adjacent ready-to-drink shelving. Footfall dependency shapes placement economics.
Offices dominates procurement volume; Hospitals commands premium pricing tiers.
Technology:
Application-specific requirements fragment technology adoption, with payment security and cooling efficiency advancing on separate upgrade calendars that complicate integrated vendor selection.
- Cashless Payment:NFC readers, mobile wallet integration, and closed-loop card systems are becoming mandatory in institutional procurement specifications across the United States and Japan. Transit authorities in Germany require payment module certification against banking security standards. Retrofit complexity with legacy mechanical architectures extends deployment timelines.
- Energy Efficient:Variable-speed compressor control, vacuum insulation panels, and LED lighting configurations qualify for utility rebate programs in multiple United States jurisdictions and Japanese prefectural schemes. Corporate sustainability mandates are accelerating specification upgrades ahead of regulatory minimums.
- Interactive Displays:Touchscreen interfaces with nutritional information and advertising integration are penetrating premium office and retail deployments. Content management requirements favor networked over standalone units.
- Refrigeration:Cooling system specifications are bifurcating between EU F-Gas Regulation-compliant natural refrigerant circuits and legacy hydrofluorocarbon designs in non-regulated markets. Compressor sourcing concentrates in Asian manufacturing clusters.
Cashless Payment captures capital allocation priority; Energy Efficient posts the most rapid specification penetration.
Distribution Channel:
Customer type concentration determines channel viability, with large institutional accounts favoring direct relationships and fragmented small business demand sustaining distributor intermediation.
- Direct Sales:National accounts in the United States and Japan negotiate multi-site service contracts bundling equipment, maintenance, and payment processing. Crane Co. and Fuji Electric leverage direct networks to minimize downtime for hospital and corporate clients. Contract terms typically span 36 to 60 months with renewal optionality.
- Distributors:Regional intermediaries aggregate smaller retail and educational accounts across Germany and China, providing installation and first-line maintenance capabilities. Inventory financing requirements filter distributor viability.
- Online Sales:E-commerce penetration remains limited to replacement components and small countertop units. Specification complexity constrains full-system transactions.
- Others:Leasing companies and vending management operators assume equipment ownership in service-inclusive arrangements. United States corporate campuses increasingly prefer this structure.
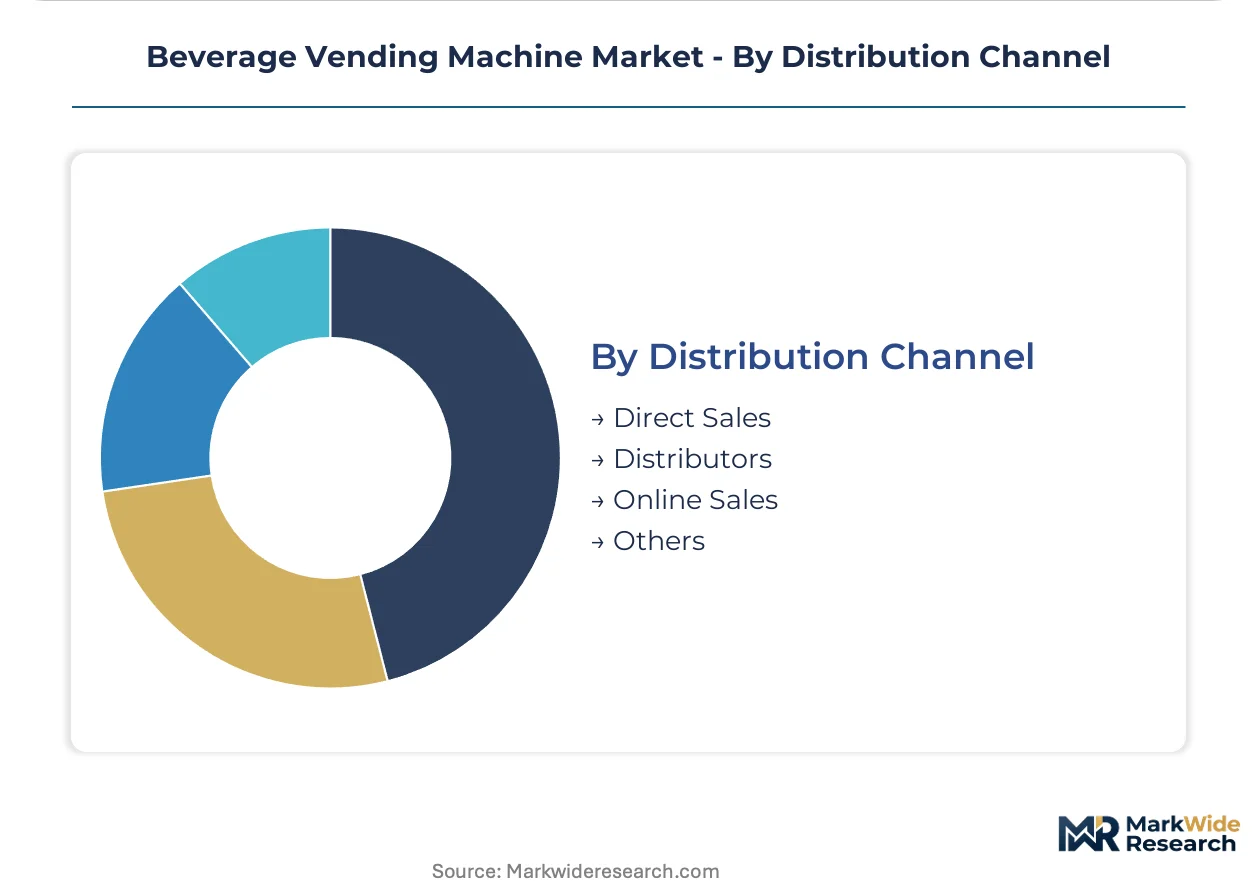
Direct Sales anchors revenue concentration; Distributors sustains geographic coverage breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cashless payment mandates and energy-efficiency rebates are redirecting procurement budgets toward compliant equipment across major markets. Japan's METI standby power limits and EU F-Gas refrigerant phase-downs are accelerating replacement cycles. Urban transit authorities and corporate campuses in high-density metros sustain placement economics.
United States
Corporate campuses in Texas and the Pacific Northwest are retrofitting machines fastest to capture utility rebates for variable-speed compressor systems. FDA material compliance for freshly prepared beverages filters vendor pools for hospital deployments in Greater Boston and the Northeast Corridor. Direct service networks from Chicago-based operators minimize downtime for medical facility contracts.
Germany
Transit authorities in Berlin and Munich are expanding unattended retail infrastructure across rail hubs with banking-security-certified payment modules. EU F-Gas Regulation constrains hydrofluorocarbon supply, elevating natural refrigerant redesign costs for Bavarian fabricators. District-level educational contracts in North Rhine-Westphalia aggregate volume for sugar-restricted beverage configurations.
Japan
METI standby power directives are compressing replacement timelines for installed bases in Tokyo and Osaka metropolitan corridors. Acute care facilities in Nagoya and Fukuoka are deploying 24/7 beverage access with HACCP-compatible contact surfaces. Corporate sustainability mandates in Kanagawa Prefecture accelerate specification upgrades ahead of regulatory minimums.
China
Office deployments in Shanghai and Shenzhen sustain hot beverage volume through thermoblock heating systems. MIIT energy-labeling schemes are reshaping component sourcing for units destined for Yangtze River Delta manufacturing zones. Beijing-Tianjin-Hebei corridor operators prioritize lease-versus-buy structures with service-inclusive operating contracts.
Beverage Vending Machine Market Competitive Landscape
Player mix skews toward integrated electromechanical specialists with captive refrigeration and payment module capabilities. Market structure concentrates around vendors capable of delivering unified hardware-software deployments within compressed institutional procurement timelines. Two strategic archetypes dominate: compressor-integrated manufacturers controlling unit cost structures, and direct-service-network operators minimizing downtime for zero-tolerance environments. Competitive moves center on refrigerant compliance retrofit bundling and cashless infrastructure certification.
Among Japan-based electromechanical conglomerates, Fuji Electric Co., Ltd. exemplifies the compressor-integrated archetype through upstream control over cooling system components. North American presence anchors around Crane Co. and its direct service network model for hospital and corporate campus contracts. European transit specialization is represented by Azkoyen Group, which occupies a position within the cashless payment module tier. These three fabricators illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors across procurement channels.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Fuji Electric Co., Ltd. |
| Crane Co. |
| Azkoyen Group |
| Royal Vendors, Inc. |
| Seaga Manufacturing, Inc. |
| Westomatic Vending Services Ltd. |
| Compass Group |
| Others |
Value Network & Pricing Analysis
Natural refrigerant substitution for hydrofluorocarbon coolants is simultaneously relocating compressor sourcing toward East Asian manufacturing clusters and compressing margin structures for European fabricators facing EU F-Gas compliance redesign costs. This input transition concentrates procurement leverage among integrated manufacturers with captive cooling system production.
Pricing Analysis
Certification level creates the primary spread across vendor tiers, with ISO 9001 and FDA-grade material compliance commanding 15-25% premiums over uncertified alternatives in hospital and university procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and energy-efficiency rebate eligibility rather than hardware differentiation alone. Pricing pressure stems from cashless module retrofit mandates forcing simultaneous payment infrastructure and refrigerant compliance investments. Educational procurement in Germany and China exhibits highest price sensitivity, while medical facility contracts in Japan and the United States prioritize uptime guarantees over capital minimization.
Supply Chain Analysis
Inventory lead times for variable-speed compressors and NFC payment modules have extended to 14-20 weeks as institutional retrofit cycles concentrate demand spikes. Component fabrication concentrates in China, Japan, and South Korea, with refrigeration compressor assembly anchored in Yangtze River Delta manufacturing zones. Supply chain risk centers on single-source vulnerability for natural refrigerant-compatible compressor controllers following EU F-Gas quota phase-downs. Distribution runs through direct service networks for hospital and corporate national accounts, while regional distributors aggregate fragmented educational and retail demand across Germany and secondary Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through district-level educational contract aggregation in Germany and multi-site corporate campus procurement in the United States, fragmenting vendor access to smaller accounts while elevating price pressure on standardized configurations.
For Market Incumbents: Compound defensive positioning by bundling refrigerant compliance retrofits with cashless payment certification to compress competitor response windows, while deepening upstream control over compressor controller supply to mitigate single-source exposure from Asian fabrication concentration. Prioritize direct service network density in hospital corridors where downtime tolerance approaches zero and contract renewal rates exceed 85%. For New Entrants and Emerging Players: Differentiate on healthy beverage category specialization targeting Japanese schools and German hospitals where institutional wellness mandates create specification white space unaddressed by legacy cola-centric vendors. Enter through lease-versus-operate service contracts preferred by United States corporate campuses, avoiding capital-intensive hardware ownership models dominated by established fabricators. For Investors and Strategic Acquirers: The market sits at a dual-transition phase that favors integrated electromechanical specialists over component assemblers, with refrigerant and payment technology cycles compressing procurement timelines toward unified solution providers. Acquisition targets should demonstrate captive refrigeration production and banking-security-certified payment module capabilities. Monitor utility rebate program expansion across United States jurisdictions as the inflection signal for energy-efficient specification penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Compliance Retrofit Bundling | Captures EU F-Gas-driven replacement cycles while locking in multi-year service contracts with transit authorities. |
| Cashless Payment Module Certification | Meets Japan METI and German banking security mandates that filter vendor eligibility in institutional procurement. |
| Direct Service Network Expansion | Reduces downtime response commitments below four hours for hospital contracts where uptime guarantees command premium pricing. |
| Healthy Beverage Configuration Development | Addresses sugar taxation spread across OECD markets and institutional wellness procurement specifications in schools. |
| Utility Rebate Program Participation | Enables total-cost-of-ownership positioning for variable-speed compressor systems in United States corporate campuses. |
Research Methodology
Desk research of trade association technical standards, customs import records, and regulatory filing databases preceded structured interviews with vending machine procurement managers at hospital systems, transit authority retail operators, and corporate facilities directors. Primary fieldwork with refrigeration compressor manufacturers and payment module integrators in China, Japan, and Germany was cross-validated against secondary sources including EU F-Gas Regulation implementation reports, METI energy-labeling scheme disclosures, and FDA material compliance guidance documents. Bottom-up unit deployment estimates were triangulated against top-down procurement budget allocations across end-use segments.
Variance decomposition across product type, payment technology, end-use vertical, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion assumptions. Forecast inputs incorporated refrigerant transition timelines, cashless infrastructure penetration curves, and utility rebate program enrollment trajectories specific to vending equipment categories.
Material uncertainties — regulatory enforcement intensity variations, compressor supply disruption events, and mobile payment platform substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these exogenous factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Shaker Bottles Market
Food Service
Food Service Utensils Market
Food Service
Snack Subscription Box Service Market
Food Service
Vietnam Food Service Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Food Away from Home Market
Food Service
United States Food Truck Market
Food Service
Global Food Retail Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Electric Tiffin Market
Food Service
Kuwait Food Service Market
Food Service
Takeout Dinner Market
Food Service
Europe Food Away from Home Market
Food Service
Virtual Kitchen Market
Food Service
Peer-To-Peer Dining Market