
 Flexible Office Market | 2026-2036
Flexible Office Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Office Market Analytics
Platform licensing revenue is tilting away from pure desk rentals toward bundled workplace-as-a-service contracts. WeWork leverages its software stack to anchor enterprise clients in multi-year agreements. Industrious competes through premium build-outs in secondary urban cores. Servcorp sustains margin density via executive suite specialization in financial district towers.
Flexible office denotes commercially operated workspace delivered under short-term contracts with shared infrastructure, typically featuring IT bandwidth exceeding 1 Gbps per user and modular furniture systems reconfigurable within 24 hours. The primary purpose is to convert fixed real estate overhead into variable operating expenditure for occupiers. Coworking space dominates volume but serviced offices capture disproportionate margin through hospitality-grade amenities. Private office demand concentrates among SMEs seeking brand-differentiated headquarters without capital deployment. Executive suites retain pricing power in central business districts where supply constraints persist.
OSHA ventilation standards in the US and the EU Green Deal building certification requirements are elevating fit-out costs while filtering subscale operators from prime locations. ESG disclosure frameworks now compel large enterprises to verify supplier environmental credentials, redirecting procurement toward certified flexible office providers. Stakeholders must monitor how municipal zoning reforms in major employment hubs reshape permissible supply density before committing to development pipelines.
Market Dynamics
Hybrid work policies have hardened into permanent corporate infrastructure, converting fixed real estate overhead into variable operating expenditure and forcing landlords to reconfigure legacy office stock into serviceable flexible product.
Growth Catalysts
- EU Green Deal building efficiency mandates:Certification requirements under the EU Green Deal are redirecting enterprise procurement toward certified flexible office providers with verified environmental credentials.
- Technology sector tenant concentration:Technology firms now anchor the fastest-growing end-use segment as hybrid work policies institutionalize distributed workforce models.
- German market absorption velocity:Berlin and Frankfurt office absorption rates for flexible product now outpace conventional leasing velocity, signaling demand maturation in Europe's largest economy.
Market Restraints
- Fit-out cost inflation from OSHA ventilation standards:US OSHA ventilation standards and EU Green Deal certification requirements are elevating capital requirements for new space delivery.
- Supply concentration in prime central business districts:Executive suites retain pricing power where supply constraints persist, limiting expansion capacity for subscale operators.
- Technical limitation of 24-hour furniture reconfiguration:Modular furniture systems require specialized labor pools that concentrate in major metropolitan areas, constraining rural and tertiary market penetration.
Strategic Opportunities
- Secondary urban core penetration:Premium build-outs in secondary urban cores offer margin capture outside oversupplied primary markets.
- Workplace-as-a-service contract bundling:Platform licensing revenue is tilting toward bundled contracts combining physical space with IT infrastructure and hospitality services.
- ESG disclosure framework tailwinds:Large enterprises must verify supplier environmental credentials under emerging disclosure frameworks, creating procurement preference for certified operators.
Industry Challenges
- Certification timeline compression:EU Green Deal building certification requirements and US OSHA standards are extending pre-opening timelines while filtering subscale operators from prime locations.
- Integration complexity with legacy corporate IT systems:Enterprise clients require seamless integration of flexible office IT bandwidth exceeding 1 Gbps per user with existing security and identity management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Office Market |
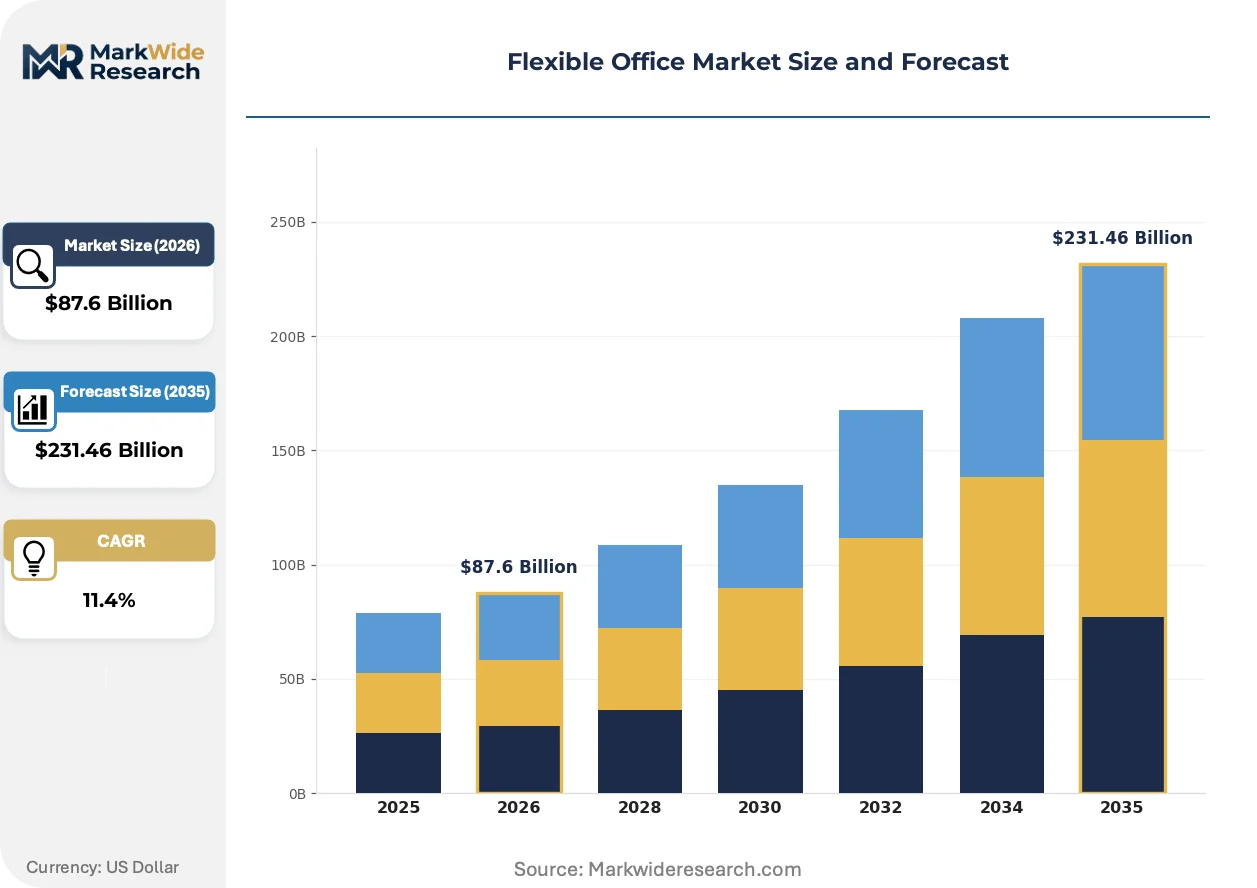
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coworking Space, Serviced Office, Private Office, Executive Suite End User: Startups, Freelancers, SMEs, Large Enterprises Pricing Model: Hourly, Daily, Monthly, Annual Service Type: Hot Desk, Dedicated Desk, Meeting Room, Event Space |
| Companies Covered | International Workplace Group, WeWork, Industrious, Servcorp, Flex by JLL, Knotel, SmartWorks, Serendipity Labs, LiquidSpace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Office Market Evolving Landscape
Technology-enabled service bundling and regulatory-driven certification requirements are compressing the competitive set toward operators with capital depth and compliance infrastructure.
AI-powered space utilization analytics is rendering obsolete static floorplate designs based on fixed headcount assumptions. Enterprise occupiers with distributed workforce models are adopting these systems fastest. Real-time occupancy data is rendering obsolete multi-year lease commitments predicated on utilization estimates.
The EU Green Deal's building certification requirements are mandating energy performance disclosures and retrofit timelines for commercial stock. Subscale operators lacking capital reserves face exclusion from prime locations. Germany's federal building codes are tightening enforcement fastest, compressing supply formation in Berlin and Frankfurt.
Enterprise procurement departments are consolidating vendor relationships under master service agreements spanning multiple cities and contract durations. Traditional transactional desk rentals are losing share to multi-year workplace-as-a-service contracts with embedded IT and hospitality. This consolidation is most visible among technology sector tenants with distributed workforce policies.
Flexible Office Market Segmentation
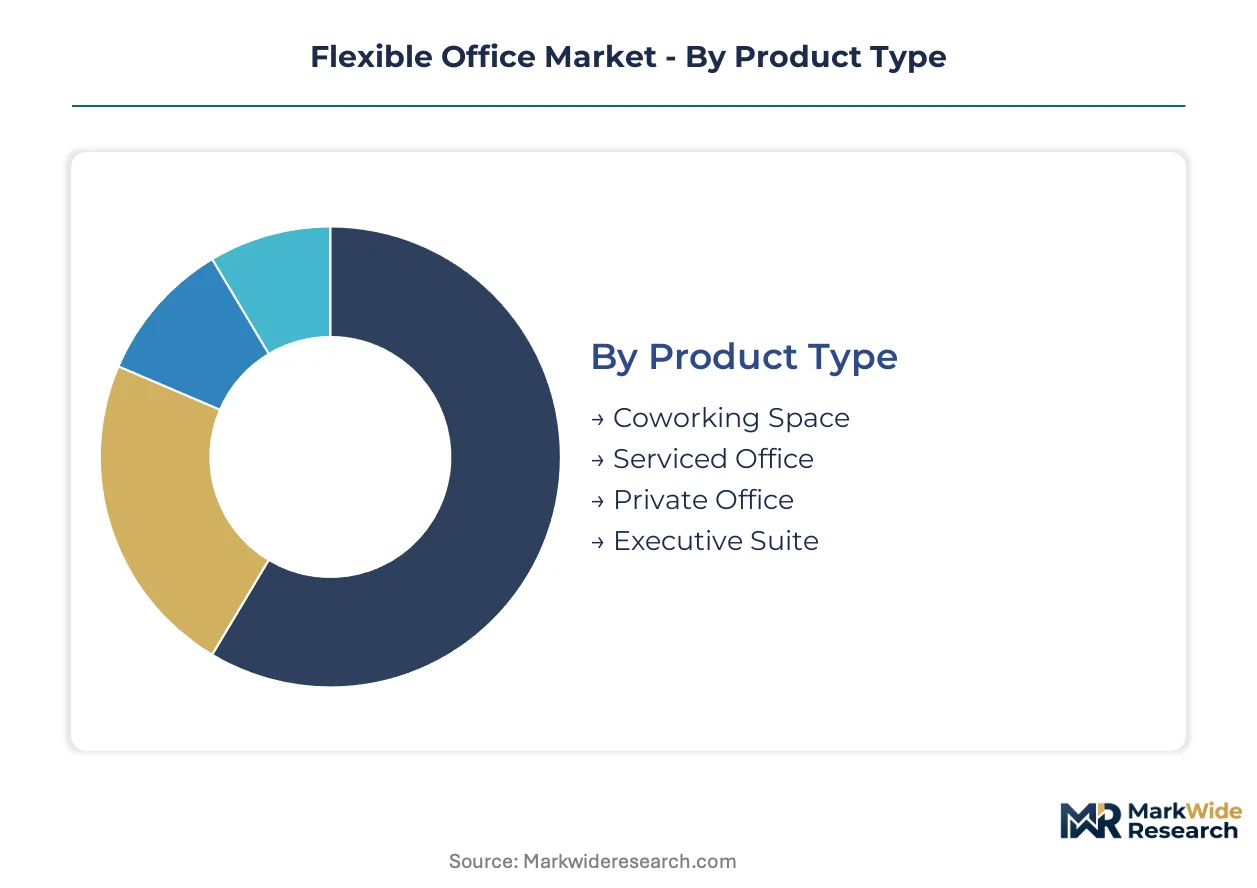
Flexible office segmentation reveals how operators balance volume against margin density. Product configuration and contract duration together determine capital efficiency and customer lifetime value.
Product Type:
Mature formats dominate revenue concentration while emerging variants reshape competitive positioning.
- Coworking Space:Open-plan environments with shared infrastructure and IT bandwidth exceeding 1 Gbps per user. Demand concentrates among technology sector tenants in Berlin and Frankfurt where hybrid work policies institutionalize distributed workforce models. Coworking handles the majority of throughput; Executive Suite is the fastest mover on share.
- Serviced Office:Hospitality-grade amenities with reception, mail handling, and administrative support bundled into short-term contracts. SMEs seeking brand-differentiated headquarters without capital deployment drive absorption in Germany's secondary urban cores. Margin density exceeds coworking through premium fit-out specifications.
- Private Office:Enclosed workspace for teams of 4-50 with modular furniture systems reconfigurable within 24 hours. Demand clusters among established SMEs requiring confidentiality and identity separation.
- Executive Suite:Premium positioning in financial district towers with concierge-level service. EU Green Deal certification requirements filter subscale operators from prime central business district locations where supply constraints persist.
Coworking generates volume velocity; Executive Suite commands pricing power.
End User:
Customer scale determines contract structure and service bundling depth.
- Startups:Venture-backed firms with headcount volatility requiring month-to-month flexibility. Technology sector concentration in Berlin anchors demand for hot desk and dedicated desk configurations.
- Freelancers:Individual operators purchasing hourly or daily access. Price sensitivity limits attach rates for premium hospitality services.
- SMEs:Mid-market firms converting fixed real estate overhead into variable operating expenditure. Procurement departments verify supplier environmental credentials under ESG disclosure frameworks, redirecting contracts toward certified providers.
- Large Enterprises:Multi-year workplace-as-a-service agreements spanning multiple cities with embedded IT infrastructure and security compliance. OSHA ventilation standards and EU Green Deal mandates elevate fit-out requirements for enterprise-grade delivery.
SMEs anchor current absorption; Large Enterprises are expanding most quickly on contract value.
Pricing Model:
Duration tiers align revenue predictability with customer commitment levels.
- Hourly:Transactional access for freelancers and mobile workers. Lowest margin contribution but highest space utilization efficiency during peak demand windows.
- Daily:Business travelers and project-based teams requiring temporary presence without recurring obligation. Concentrates in airport-adjacent and financial district locations.
- Monthly:Standard commitment for startups and SMEs with moderate headcount stability. Platform licensing revenue is tilting toward bundled contracts combining physical space with IT infrastructure.
- Annual:Enterprise procurement under master service agreements with volume discounts and service-level guarantees. Multi-year workplace-as-a-service contracts embed hospitality and technology services.
Monthly contracts handle transaction volume; Annual agreements drive margin expansion.
Service Type:
Space configuration determines utilization economics and labor intensity.
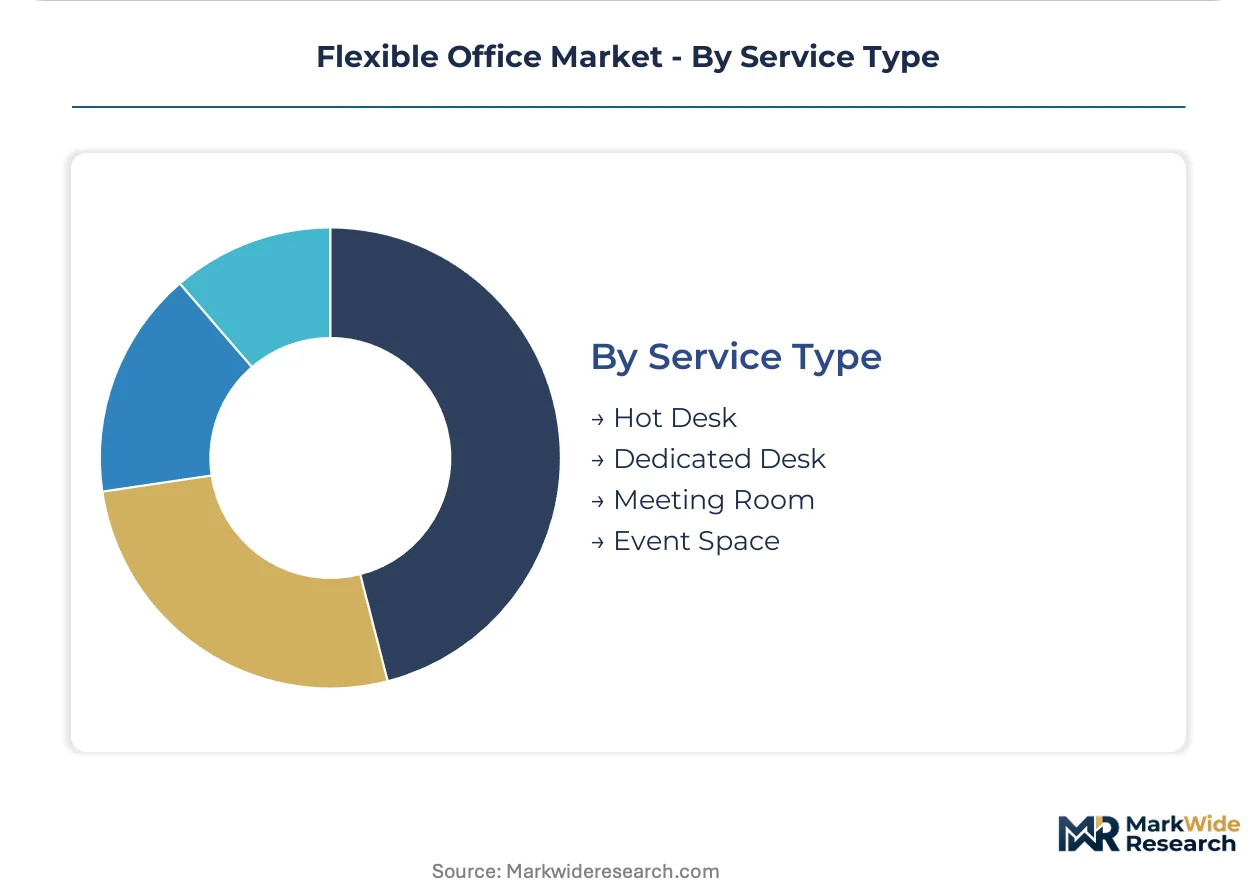
- Hot Desk:Unassigned seating in open areas with first-come access. AI-powered space utilization analytics optimize density in high-velocity locations.
- Dedicated Desk:Reserved workstation with personal storage and 24/7 access. Startups and freelancers seeking consistency without private office overhead.
- Meeting Room:Bookable enclosed spaces for 4-20 participants with AV conferencing infrastructure. Large Enterprises with distributed workforce models drive hourly and half-day bookings.
- Event Space:Configurable areas for 50-200 attendees with catering and production support. Corporate programming and product launches generate premium pricing in Berlin and Frankfurt.
Hot Desk captures utilization density; Event Space achieves peak rate realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive freelancers dominate transaction volume in India and Southeast Asia, while premium contract values concentrate in Germany and the United States where enterprise procurement departments prioritize ESG-verified suppliers.
United States
Technology sector tenants with distributed workforce policies drive workplace-as-a-service contract proliferation across Austin, Seattle, and San Francisco. OSHA ventilation standards for commercial buildings elevate fit-out costs and filter subscale operators from prime central business districts. New York and Chicago absorb flexible product faster than conventional leasing as landlords reconfigure legacy office stock.
Germany
Berlin and Frankfurt office absorption rates for flexible product outpace conventional leasing velocity, signaling demand maturation in Europe's largest economy. EU Green Deal building certification requirements redirect enterprise procurement toward operators with verified environmental credentials. Munich and Hamburg concentrate premium executive suite positioning where supply constraints persist in financial district towers.
United Kingdom
SMEs seeking brand-differentiated headquarters without capital deployment cluster in London's secondary urban cores and Manchester's technology corridors. CSRD disclosure frameworks compel large enterprises to verify supplier environmental credentials, favoring certified flexible office providers. Birmingham and Edinburgh absorb private office configurations for established mid-market firms requiring confidentiality.
India
Startups and freelancers in Bangalore, Hyderabad, and Mumbai drive hot desk and dedicated desk utilization density. The country's national building efficiency codes are tightening commercial stock retrofit timelines, though enforcement varies by state. Delhi-NCR concentrates serviced office demand among mid-market professional services firms converting fixed overhead to variable expenditure.
Japan
Large enterprises under METI energy efficiency guidelines procure multi-year workplace-as-a-service agreements in Tokyo and Osaka. JIS standards for modular building systems constrain rapid furniture reconfiguration timelines outside major metropolitan areas. Fukuoka and Sapporo represent emerging penetration opportunities as hybrid work policies institutionalize across financial services and technology sectors.
Flexible Office Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding pricing power in constrained central business districts; scale advantage sits with platform operators aggregating enterprise contracts across multiple metropolitan markets. The vendor base organizes around three strategic archetypes: hospitality-grade serviced office specialists, technology-enabled workplace-as-a-service platforms, and executive suite operators in financial district towers. Competitive moves center on multi-year contract bundling combining physical space with IT infrastructure, and secondary urban core expansion to capture margin outside oversupplied primary markets.
Within the scale-driven platform tier, WeWork and Industrious occupy positions exemplifying technology-enabled service bundling and premium build-out strategies respectively. Servcorp anchors the executive suite specialization archetype in financial district towers. International Workplace Group represents geographic breadth across multiple continental markets. These three named entities collectively illustrate how competitive positioning diverges between volume aggregation and margin density capture.
| Leading Market Players |
|---|
| International Workplace Group |
| WeWork |
| Industrious |
| Servcorp |
| Flex by JLL |
| Knotel |
| SmartWorks |
| Serendipity Labs |
| LiquidSpace |
| Others |
Value Network & Pricing Analysis
Overcapacity in secondary urban cores across the United States and Germany is compressing spot desk rates while concentrating pricing power with certified operators in constrained central business districts. Utilization differentials between prime and non-prime locations directly shape supplier capital allocation decisions and tenant procurement postures.
Pricing Analysis
Long-term workplace-as-a-service contracts now anchor enterprise procurement, displacing transactional desk rentals as the dominant revenue structure. Three-tier pricing stratification across executive suite, serviced office, and coworking levels reflects certification grade under EU Green Deal mandates and volume scale commitments. Cost compression in the hot desk tier intensifies because price-sensitive freelancers and startups dominate transaction velocity. Large enterprises with distributed workforce policies exhibit lowest price sensitivity due to ESG compliance requirements and IT integration complexity.
Supply Chain Analysis
Upstream feedstock for modular furniture systems and IT infrastructure components draws from China, Germany, and the United States as primary manufacturing hubs. Specialized labor pools for rapid space reconfiguration, high-bandwidth network equipment, and hospitality-grade fit-out materials constitute critical input dependencies. Single-source vulnerability concentrates in German-engineered building automation systems required for EU Green Deal certification compliance. Distribution runs through operator-owned platforms aggregating enterprise contracts across multiple metropolitan markets rather than third-party channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible office incumbents face substitution pressure from remote-work technology platforms and enterprise-owned satellite offices that replicate distributed workforce functionality without third-party space commitments.
For Market Incumbents: Harden enterprise retention through multi-year workplace-as-a-service contracts embedding proprietary IT infrastructure and security compliance. Accelerate backward integration into modular furniture manufacturing to compress 24-hour reconfiguration timelines. Certification investment under EU Green Deal mandates filters subscale competitors from prime Berlin and Frankfurt locations. For New Entrants and Emerging Players: Secondary urban cores in India's Bangalore and Hyderabad represent the most penetrable entry point given price-sensitive startup density and uneven enforcement of national building efficiency codes. Tertiary German cities beyond Berlin, Frankfurt, Munich, and Hamburg offer white-space capture as hybrid work policies institutionalize across SME segments. Channel partnerships with technology sector vendors provide the most efficient go-to-market angle for rapid enterprise client acquisition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU Green Deal-certified executive suite configurations due to extended pre-opening timelines and specialized fit-out requirements. Acquisition targets should concentrate on operators with verified environmental credentials and existing enterprise master service agreements spanning multiple cities. The signal to watch as inflection indicator is municipal zoning reform velocity in major employment hubs, which reshapes permissible supply density and development pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Workplace-as-a-Service Contract Bundling | Multi-year agreements embedding IT infrastructure capture enterprise procurement departments consolidating vendor relationships. |
| EU Green Deal Certification Investment | Verified environmental credentials redirect contracts from subscale operators under ESG disclosure frameworks. |
| Secondary Urban Core Expansion | Premium build-outs outside oversupplied primary markets capture margin density in Germany's Hamburg and Munich. |
| Backward Integration into Modular Systems | In-house production of 24-hour reconfigurable furniture reduces labor pool dependency in tertiary markets. |
| Technology Platform Integration | AI-powered space utilization analytics render static floorplate designs obsolete for distributed workforce tenants. |
Research Methodology
Initial hypotheses were tested against primary input from flexible space operators, enterprise real estate directors, modular furniture manufacturers, and hospitality procurement specialists and refined through secondary validation. Bottom-up and top-down triangulation combined SEC filings from publicly traded operators, EU building certification databases, OSHA ventilation standard documentation, and metropolitan office absorption reports. Primary stakeholder interviews captured contract structure evolution and IT integration complexity requirements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user scale, pricing model duration, and service configuration complexity. CAGRs were derived from absorption velocity differentials between flexible and conventional leasing in Berlin, Frankfurt, Austin, and San Francisco. Forecast inputs incorporated hybrid work policy permanence rates and EU Green Deal enforcement timeline compression.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate capital availability and technology sector headcount growth would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and enterprise procurement consolidation velocity. Cross-checking against municipal zoning reform announcements and building permit issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market