
 Saudi Arabia Co-Working Office Spaces Market | 2026-2036
Saudi Arabia Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Co-Working Office Spaces Market Analytics
Saudi Arabia's freelance and tech talent pool is bifurcating between gig-economy independents and corporate-remote professionals, creating dual demand streams for flexible workspace. WeWork leverages its international brand architecture to attract multinational satellite teams entering the Kingdom. Kayanspace anchors its position through localized Arabic-language community programming and government partnership channels. AstroLabs specializes in venture-backed startup incubation, embedding mentorship and investor access into its physical workspace model.
Co-working office spaces constitute professionally managed, short-lease commercial environments providing shared infrastructure, enterprise-grade connectivity, and modular desk configurations for non-traditional occupiers. Facilities incorporating dedicated internet services and scalable conference room access command premium positioning against basic hot-desking alternatives. Private offices within co-working complexes capture the fastest expansion trajectory as enterprises pursue hybrid work footprints without conventional lease commitments. Monthly membership structures dominate revenue stability while flexible contracts attract project-based consulting teams seeking cancellation agility.
SAGIA licensing requirements and municipal commercial zoning enforcement shape market entry barriers for new facility operators in Riyadh, Jeddah, and Dammam. The Saudi Building Code and SFDA-adjacent workplace safety protocols mandate specific ventilation, egress, and ergonomic standards that differentiate compliant premium providers from informal competitors. Stakeholders must monitor how MOF-approved public-private partnership frameworks for SME districts redirect demand toward state-sanctioned innovation hubs versus independent co-working brands.
Market Dynamics
Saudi Vision 2030's SME enablement policies are restructuring commercial real estate demand, redirecting workspace procurement from traditional long-lease corporate contracts toward modular, short-term occupancy models that align with fluctuating headcount needs.
Growth Catalysts
- Remote Work Normalization:Corporate satellite teams from multinational enterprises are establishing Riyadh presences without committing to conventional five-year commercial leases. This demand stream favors operators offering enterprise-grade connectivity and scalable private office configurations.
- SAGIA Licensing Streamlining:The Saudi Arabian General Investment Authority's simplified foreign business establishment procedures reduce entry friction for international startups seeking physical presence. Co-working operators capture this inbound flow through turnkey licensing support bundled with workspace.
- Hybrid Work Infrastructure:Domestic enterprises are downsizing central headquarters while maintaining distributed collaboration nodes. Facilities incorporating dedicated internet services and on-demand conference room access address this bimodal occupancy requirement.
Market Restraints
- Municipal Z Enforcement:Commercial zoning restrictions in Riyadh, Jeddah, and Dammam limit facility locations to designated business districts. Operators face extended permitting timelines and site selection constraints that inflate pre-operational capital requirements.
- Saudi Building Code Compliance:Mandatory ventilation, egress, and ergonomic standards under national construction regulations impose fit-out costs that informal competitors circumvent. Premium providers absorb these compliance burdens while competing against non-compliant alternatives.
- Input Cost Volatility:Specialized furniture and modular partition systems rely on imported materials subject to freight rate fluctuations and currency exposure. Facility operators face margin compression when contract terms lock in membership pricing ahead of procurement cycles.
Strategic Opportunities
- Secondary City Penetration:Dammam's industrial corridor and emerging knowledge zones in Al Khobar exhibit underserved demand from petrochemical sector contractors and logistics technology ventures. First-mover operators can anchor positions before supply saturation.
- SFDA-Adjacent Workplace Protocols:Life sciences and health technology startups require laboratory-adjacent office configurations meeting Saudi Food and Drug Authority environmental controls. Specialized co-working formats addressing this compliance niche command substantial pricing premiums.
- Public-Private Partnership Alignment:Ministry of Finance-approved frameworks for state-sanctioned innovation hubs channel subsidized demand toward compliant operators. Partnership positioning with SME district developments secures preferential tenant pipelines and reduced competitive intensity.
Industry Challenges
- Arabic-Language Community Programming:International brand operators struggle to deploy localized engagement strategies that resonate with Saudi entrepreneurial culture. Talent acquisition for community management roles combining bilingual capability and regional network access remains constrained.
- Technology Integration Complexity:Legacy property management systems require substantial adaptation to support flexible billing, hot-desking reservation protocols, and member analytics. Operators face execution risk during platform migrations that disrupt daily operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Co-Working Office Spaces Market |
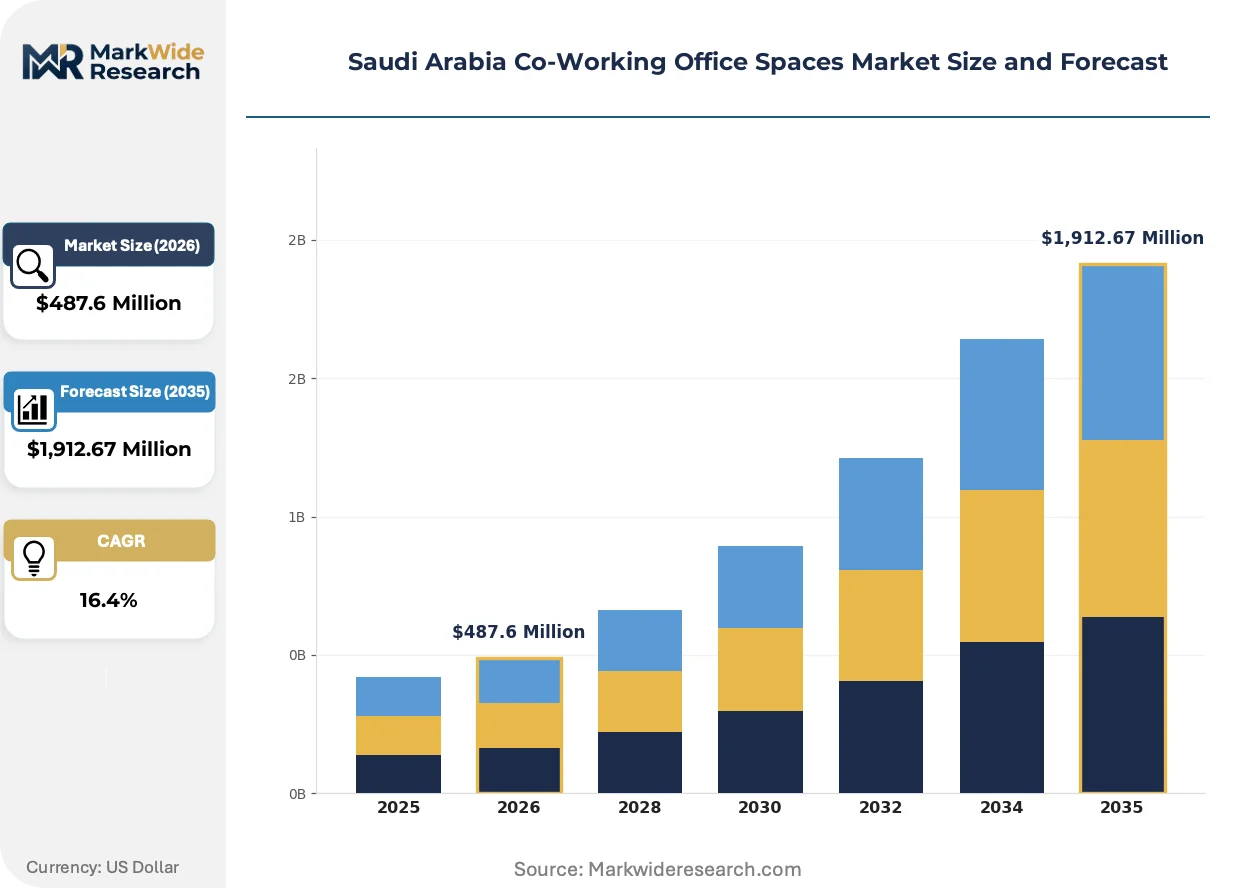
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,912.67 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hot Desking, Dedicated Desks, Private Offices, Meeting Rooms End User: Startups, Freelancers, Small Businesses, Enterprises Facilities: Internet Services, Conference Rooms, Pantry, Individual Workstations Pricing Model: Monthly Membership, Pay-As-You-Go, Hourly Rates, Flexible Contracts |
| Companies Covered | Spaces, Vibes Offices, WeWork, Kayanspace, Gravita, Regus, White Space, AstroLabs, Servcorp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Co-Working Office Spaces Market Evolving Landscape
Workspace technology and occupancy models are converging around intelligence-driven resource allocation, replacing static floor plans with responsive environments that adapt to real-time utilization patterns and hybrid collaboration requirements.
Smart building management systems integrating IoT sensors and predictive analytics are supplanting manual facilities oversight in premium Saudi facilities. Operators deploying these platforms achieve 15-25% energy efficiency improvements and reduced staffing ratios. The structural consequence compresses operating cost structures for technology-enabled competitors while straining margin positions at conventional managed properties.
SFDA workplace safety protocols and Saudi Building Code ventilation mandates are tightening environmental standards for commercial occupancies. Facilities must demonstrate compliance through documented air quality monitoring and ergonomic workstation assessments. Life sciences and health technology segments are most affected, driving demand toward purpose-built laboratory-adjacent office configurations that pre-empt regulatory scrutiny.
Enterprise procurement departments are unbundling real estate decisions from centralized headquarters planning, empowering regional managers to acquire satellite workspace through discretionary budgets. Traditional corporate lease brokers are losing intermediary positioning to direct operator relationships and digital booking platforms. This behavioral shift is most visible in Riyadh's King Abdullah Financial District, where multinational satellite teams now contract directly with co-working brands for sub-12-month engagements.
Saudi Arabia Co-Working Office Spaces Market Segmentation
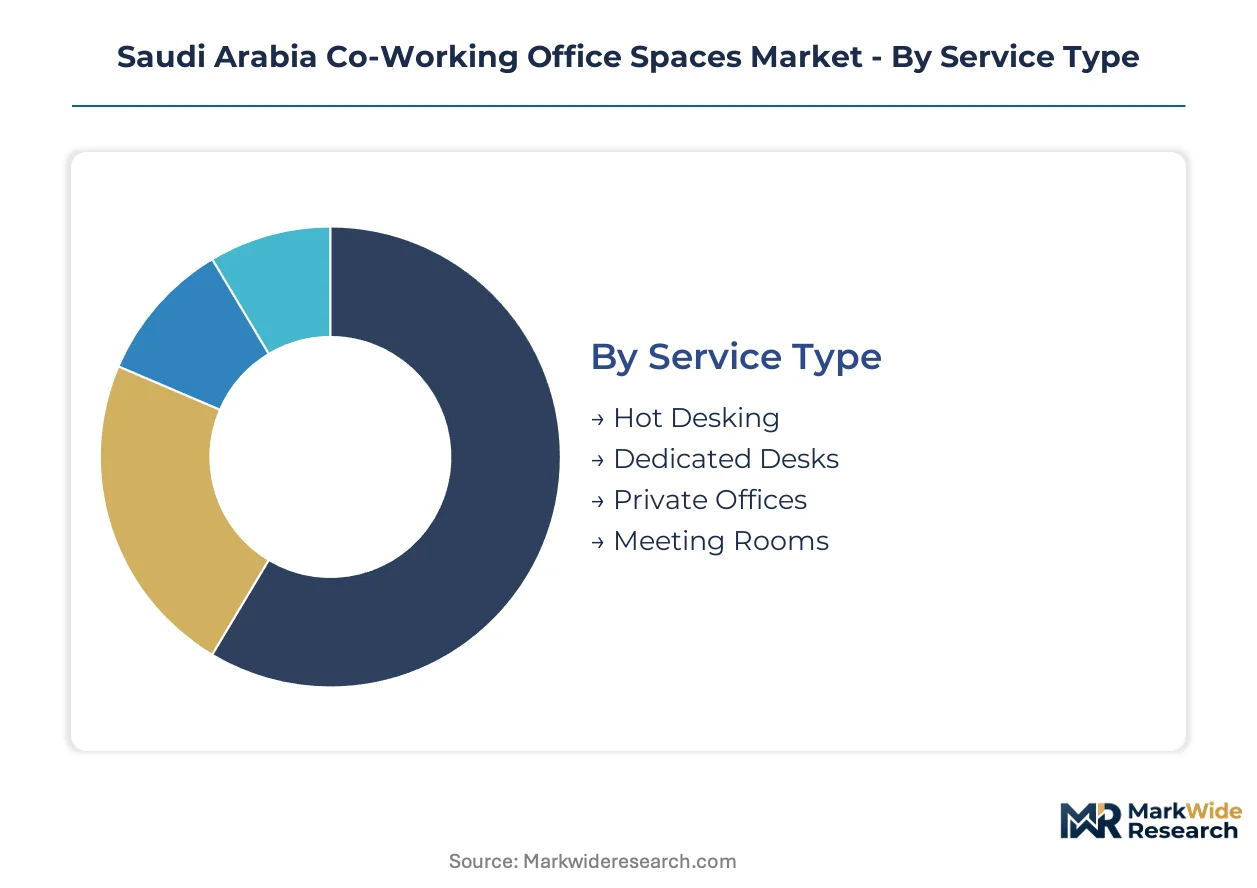
Workspace configuration and user economics fragment the Saudi co-working market into distinct procurement segments. Each dimension shapes operator revenue stability, facility design requirements, and competitive positioning against conventional commercial lease alternatives.
Service Type:
Riyadh and Jeddah operators report divergent demand profiles, with domestic enterprises favoring enclosed configurations while inbound satellite teams prioritize flexible desk access.
- Hot Desking:Unassigned seating in open floor configurations with shared power and network infrastructure. Freelancers in Jeddah's innovation corridors drive utilization, constrained by noise tolerance limits and personal storage absence.
- Dedicated Desks:Permanently reserved workstations within shared environments, combining flexibility with personalization. Small businesses in Riyadh's King Abdullah Financial District favor this tier for team continuity without private office overhead.
- Private Offices:Enclosed suites accommodating 4-20 personnel within co-working complexes. Enterprises downsizing central headquarters under Vision 2030 hybrid mandates anchor demand in this segment.
- Meeting Rooms:Bookable conference and presentation spaces available to members and external clients. Project-based consulting teams in Dammam's industrial corridor generate intermittent but high-margin utilization.
Private offices hold the largest share; momentum sits with dedicated desks as mid-size enterprises calibrate hybrid footprints.
End User:
Customer procurement authority varies sharply across segments, from individual discretionary spending to centralized corporate real estate budgets.
- Startups:Venture-backed and bootstrapped ventures requiring scalable occupancy without lease liability. SAGIA licensing support bundled with workspace accelerates onboarding for foreign-founded entities entering the Kingdom.
- Freelancers:Independent professionals spanning creative services, technology consulting, and professional advisory. Gig-economy participants in urban centers generate price-sensitive demand for basic hot-desking access.
- Small Businesses:Established SMEs with 10-50 employees seeking satellite locations or headquarters alternatives. Regional logistics and professional services firms in secondary cities exhibit underserved demand.
- Enterprises:Multinational corporations and large domestic conglomerates establishing project offices or departmental satellites. Procurement departments now authorize sub-12-month co-working contracts outside traditional lease processes.
Enterprises command premium pricing power; expanding most quickly are small businesses capitalizing on SME district subsidies.
Facilities:
Infrastructure differentiation separates premium providers from budget competitors, with compliance burdens concentrated in connectivity and environmental standards.
- Internet Services:Dedicated enterprise-grade bandwidth with redundancy and service-level agreements. SFDA-adjacent workplace protocols mandate documented connectivity reliability for health technology occupiers.
- Conference Rooms:Scalable meeting infrastructure ranging from 4-person huddle spaces to 50-person presentation suites. Hybrid collaboration requirements drive demand for video-integrated configurations.
- Pantry:Food preparation and casual meeting zones with beverage and light meal service. Saudi Building Code ventilation standards apply to these high-occupancy amenity areas.
- Individual Workstations:Ergonomically assessed desk configurations meeting national occupational health guidelines. Compliance documentation differentiates formal operators from informal competitors.
Internet services anchor competitive positioning; gaining share fastest are integrated conference room portfolios as hybrid meeting patterns normalize.
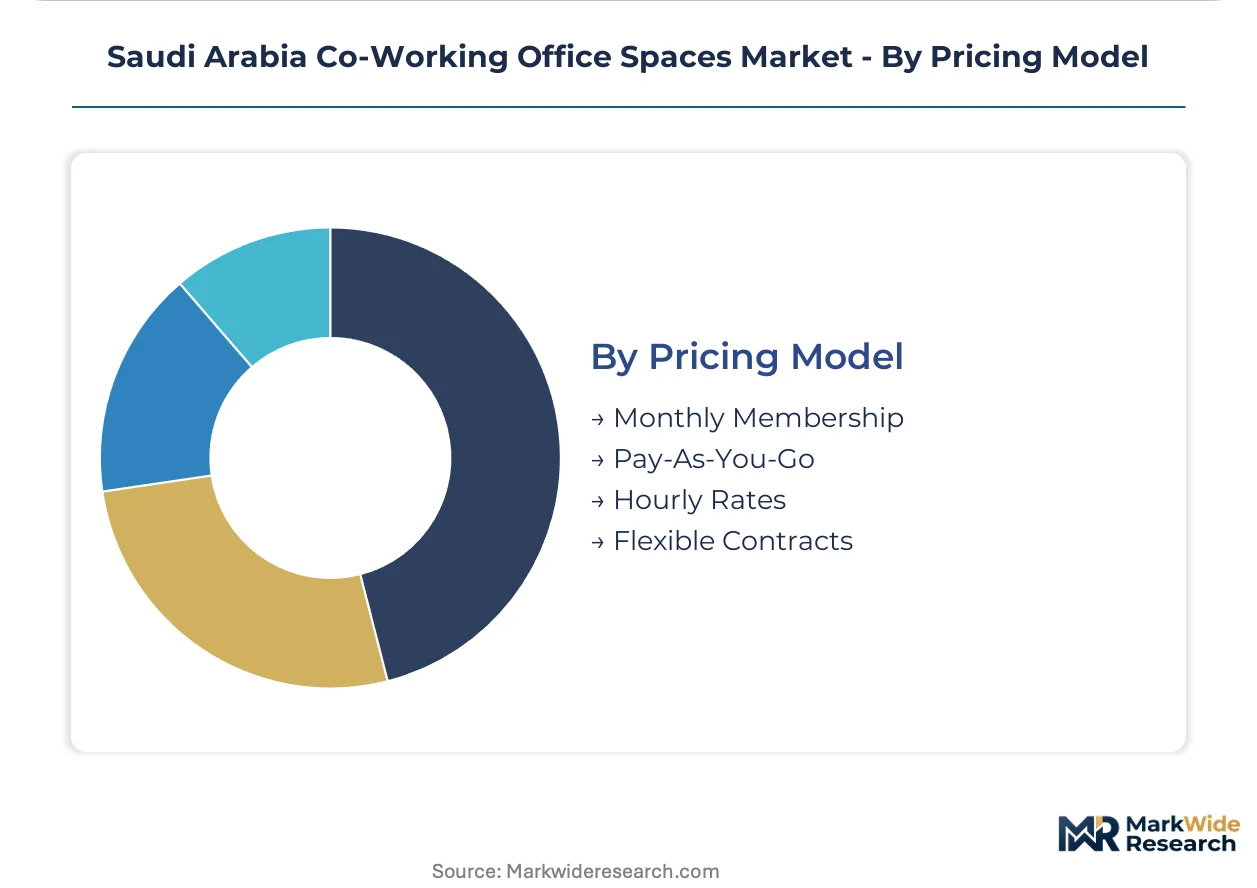
Pricing Model:
Revenue predictability and customer acquisition friction trade off across payment structures, shaping operator cash flow profiles.
- Monthly Membership:Recurring fixed fees for unlimited or tiered access to facilities and services. Domestic SMEs in Riyadh favor this structure for budget certainty and accounting simplicity.
- Pay-As-You-Go:Per-visit or per-service charges without ongoing commitment. International visitors and intermittent users generate sporadic but high-margin revenue.
- Hourly Rates:Time-bounded access to specific resources including desks, offices, or meeting rooms. Project-based contractors in Dammam's petrochemical corridor utilize this for site visit coordination.
- Flexible Contracts:Short-term agreements with cancellation provisions and scaling options. Corporate satellite teams mandate this structure for headcount volatility accommodation.
Monthly membership dominates revenue stability; steepest expansion trajectory belongs to flexible contracts as enterprise procurement autonomy increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workspace utilization patterns diverge sharply across Saudi Arabia's economic geography, with Riyadh prioritizing enterprise-grade private offices while Jeddah and secondary cities exhibit stronger freelancer and SME demand for flexible desk access.
Riyadh
Corporate headquarters relocations and Vision 2030 government agency consolidation drive demand for scalable private suites. SAGIA licensing streamlining accelerates foreign startup entry through co-working channels. King Abdullah Financial District anchors multinational satellite team procurement.
Eastern Province
Petrochemical sector contractors and logistics technology ventures generate intermittent but high-margin meeting room utilization. Municipal commercial zoning enforcement limits facility placement to designated business corridors. Dammam's industrial corridor exhibits underserved demand from project-based consulting teams.
Western Region
Jeddah's innovation corridors concentrate gig-economy independents seeking basic hot-desking arrangements. Saudi Building Code ventilation mandates impose fit-out costs that informal competitors circumvent. The city's port-adjacent knowledge zones attract creative services freelancers.
NEOM Northwest
Emerging knowledge economy zones under MOF-approved public-private partnership frameworks channel subsidized demand toward state-sanctioned innovation hubs. SFDA-adjacent workplace safety protocols shape specialized laboratory-adjacent office configurations. The region's regulatory greenfield status attracts first-mover operators.
Saudi Arabia Co-Working Office Spaces Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with international brands leveraging scale against localized community operators. The market exhibits moderate concentration, with foreign entrants capturing multinational satellite demand while domestic players anchor SME and government partnership channels. Two strategic archetypes dominate: global workspace networks deploying standardized service architectures, and regional specialists embedding Arabic-language programming and regulatory navigation support. Competitive intensity centers on M&A activity consolidating secondary city positions and technology licensing partnerships embedding smart building management systems.
Among international workspace networks, WeWork and Regus exemplify the scale-driven archetype, occupying positions that attract enterprise procurement departments seeking standardized global service level agreements. Within the regional specialist tier, Kayanspace and AstroLabs anchor localized positioning through government partnership channels and venture-backed startup incubation programming. These domestic operators sit within a competitive structure where Arabic-language community management and SAGIA licensing support differentiate against foreign competitors.
| Leading Market Players |
|---|
| Spaces |
| Vibes Offices |
| WeWork |
| Kayanspace |
| Gravita |
| Regus |
| White Space |
| AstroLabs |
| Servcorp |
| Others |
Value Network & Pricing Analysis
Modular furniture systems replacing conventional fixed build-outs are simultaneously redrawing procurement geography toward East Asian manufacturing clusters and compressing fit-out cost structures for Saudi operators competing against informal providers. This substitution dynamic transfers pricing leverage from domestic contractors to international suppliers while amplifying margin pressure on premium providers absorbing Saudi Building Code compliance burdens.
Pricing Analysis
Contract structures bifurcate between monthly membership commitments favored by Riyadh-based domestic SMEs and flexible short-term agreements demanded by multinational satellite teams. Three-tier pricing structure across premium, standard, and economy levels differentiates facilities by connectivity grade and compliance documentation depth. Cost compression in the hot-desking tier is intensifying because informal competitors circumvent Saudi Building Code ventilation and egress mandates. Freelancers in Jeddah's innovation corridors exhibit highest price sensitivity, while enterprise procurement departments in the King Abdullah Financial District prioritize service-level agreements over rate minimization.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability fluctuations on Asia-Middle East trade lanes are extending lead times for specialized workstation and modular partition imports. Supply concentrates in China, South Korea, and Germany for IoT-enabled building management systems, ergonomic furniture, and enterprise-grade networking equipment. Operators draw from these sources while managing currency exposure against SAR-denominated membership contracts. Single-source vulnerability concentrates in Chinese-manufactured smart sensor arrays. Distribution runs through Riyadh-based facility management integrators serving King Abdullah Financial District and Jeddah innovation corridor developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's co-working market is recovering from pandemic-era occupancy disruptions through Vision 2030's SME enablement cycle, with government procurement and foreign startup entry creating sustained demand tailwinds.
For Market Incumbents: Shield market position by deepening Arabic-language community programming capabilities and securing MOF-approved public-private partnership slots in emerging SME districts. Incumbent operators face margin pressure from informal competitors circumventing Saudi Building Code compliance; vertical integration into in-house SAGIA licensing advisory services creates switching costs and diversifies revenue beyond desk rentals. For New Entrants and Emerging Players: SFDA-adjacent laboratory-adjacent office configurations represent a service-layer gap where incumbents under-serve life sciences and health technology ventures. Dammam's industrial corridor and Al Khobar knowledge zones offer penetrable geography with limited premium supply. New entrants should anchor positioning through specialized compliance documentation and petrochemical sector contractor networks. For Investors and Strategic Acquirers: The market sits at an expansion phase that favors technology-enabled operators with smart building management deployment capabilities. Long-term viability rests on platforms achieving 15-25% operating cost advantages through IoT sensor integration and predictive analytics. Acquisition targets should demonstrate established SAGIA partnership channels and documented Saudi Building Code compliance infrastructure. The signal to watch is MOF innovation hub allocation announcements redirecting subsidized demand.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Management Deployment | IoT sensor integration reduces energy costs and staffing ratios for King Abdullah Financial District facilities. |
| SAGIA Licensing Support Bundling | Turnkey foreign business establishment accelerates inbound startup onboarding and retention. |
| SFDA-Adjacent Compliance Specialization | Laboratory-adjacent configurations capture health technology ventures requiring environmental controls. |
| Public-Private Partnership Alignment | MOF-approved SME district positioning secures preferential tenant pipelines and reduced competition. |
| Secondary City Geographic Expansion | First-mover anchoring in Dammam and Al Khobar captures petrochemical contractor demand. |
Research Methodology
Desk research of municipal zoning filings, SAGIA licensing statistics, and Saudi Building Code regulatory updates preceded structured interviews with facility operators, commercial real estate brokers, and SME procurement officers. Primary fieldwork encompassed workspace utilization assessments across Riyadh's King Abdullah Financial District, Jeddah innovation corridors, and Dammam industrial zones. Secondary validation drew from Vision 2030 policy documents, MOF public-private partnership frameworks, and SFDA workplace safety protocols. Bottom-up facility capacity modeling and top-down SME formation projections were triangulated against actual occupancy disclosures.
Variance decomposition across service type, end user category, and regional demand cluster informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include workspace configuration, customer procurement authority, infrastructure tier, and contract flexibility structure. CAGRs were derived from fitted growth curves anchored to Vision 2030 SME enablement policy trajectories and foreign direct investment licensing trends. Industry-specific forecast inputs encompass SAGIA application processing rates and municipal commercial zoning approval timelines.
Underlying assumptions cover sustained Vision 2030 implementation, stable SAGIA licensing streamlining, and consistent Saudi Building Code enforcement intensity, with deviation risk concentrated in municipal zoning enforcement variability and public-private partnership allocation shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
North America Flexible Office Market
Office Real Estate
Office Real Estate Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Global Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market