
 Fintech Technologies Market | 2026-2036
Fintech Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech Technologies Market Foresight
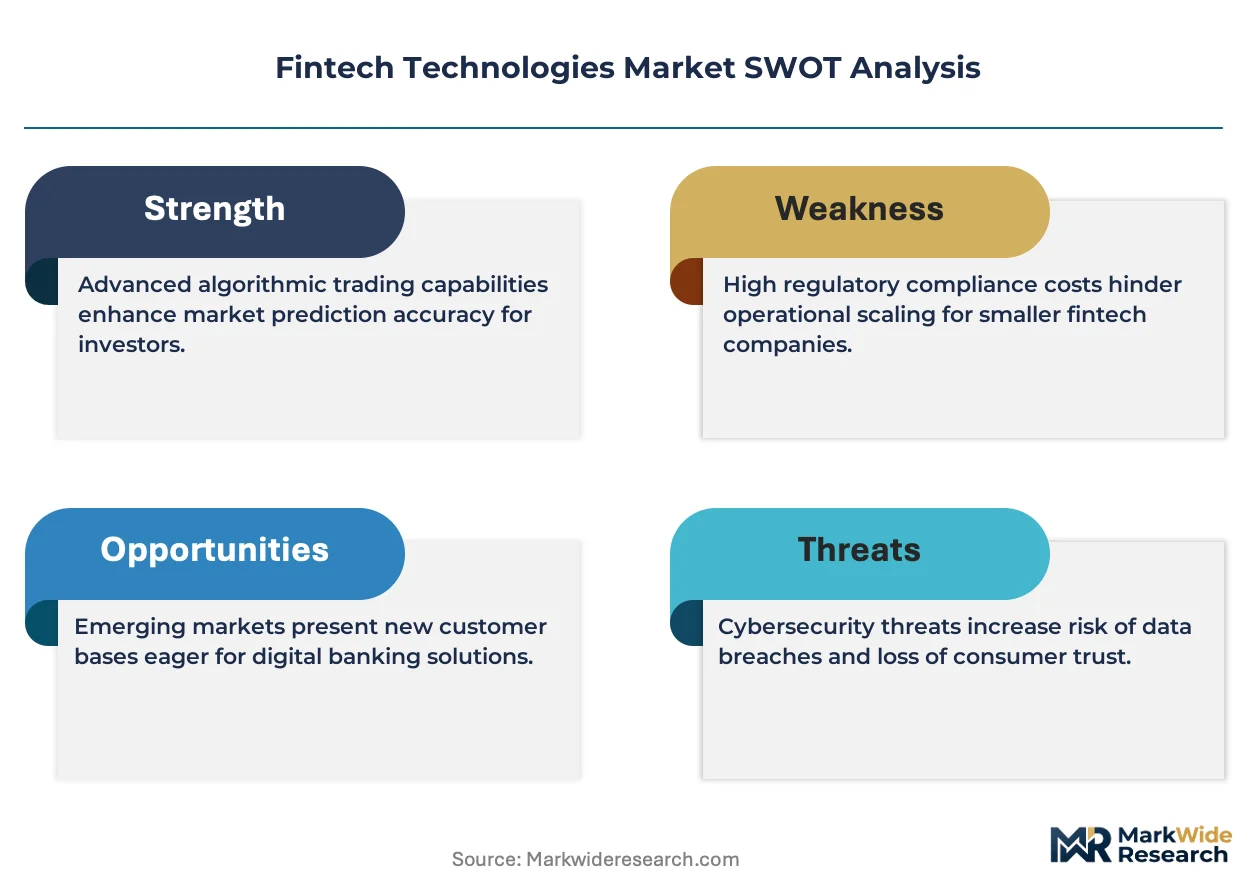
Embedded finance and banking-as-a-service licensing is reconfiguring capital requirements for new entrants, allowing technology firms to offer financial products without chartering full-service banks. Stripe leverages its payment infrastructure to anchor merchant-facing fintech stacks across North America and Europe. Ant Group dominates consumer finance interfaces through its super-app architecture in China. Adyen competes on unified commerce platforms that process online, in-store, and mobile transactions through single integrations.
Fintech technologies encompass software systems, digital platforms, and data-driven infrastructure that automate financial services, typically operating through API-based architectures with sub-second transaction processing and 99.99% uptime requirements. These systems execute payments, credit decisions, wealth allocation, and risk assessment with minimal human intervention. Payment Processing solutions sustain the largest revenue pools due to per-transaction fee structures, while Lending Platforms extend fastest as alternative credit scoring models expand addressable borrower bases. Artificial Intelligence and Machine Learning segments concentrate margin capture through fraud detection and algorithmic underwriting capabilities that reduce default rates.
The EU's PSD2 open banking framework and the UK's Financial Conduct Authority standards shape API interoperability mandates, forcing incumbent banks to share customer data with licensed third parties. In the United States, the CFPB's emerging open banking rules and state-level money transmission licensing create a fragmented compliance landscape that favors multi-jurisdiction operators. China's SAMR and PBOC oversee Ant Group and Tencent's financial activities through capital adequacy and data localization requirements. Stakeholders must monitor regulatory divergence between privacy-centric European frameworks and innovation-permissive Asian regimes when allocating platform development resources.
Market Dynamics
Embedded finance licensing frameworks are dismantling traditional capital barriers, allowing non-bank technology platforms to originate loans and process payments without maintaining full banking charters. This structural shift compresses time-to-market for new entrants while forcing incumbents to defend their deposit bases through API partnerships rather than proprietary infrastructure.
Growth Catalysts
- PSD2 Open Banking Mandates:The EU's revised Payment Services Directive compels incumbent banks to expose customer data through standardized APIs, creating entry points for third-party payment initiation services and account information providers.
- Real-Time Payment Rails:India's Unified Payments Interface processes peer-to-peer and merchant transactions instantaneously, demonstrating infrastructure scalability that other emerging economies are replicating through central bank digital currency pilots.
- Alternative Credit Scoring:Machine learning models analyzing cash-flow data from accounting software and e-commerce platforms extend credit access to thin-file borrowers excluded from traditional FICO-based underwriting.
Market Restraints
- State-Level Licensing Fragmentation:The United States maintains 50 distinct money transmission licensing regimes, forcing payment processors to secure separate approvals in each jurisdiction and maintain bonded capital reserves that scale with transaction volume.
- Cloud Concentration Risk:Critical fintech infrastructure depends on three dominant hyperscale providers, creating systemic vulnerability when regulators mandate data localization that conflicts with these providers' global architectures.
- Core Banking System Entrenchment:Tier-1 banks operate on COBOL-based legacy platforms that resist API integration, forcing fintech partnerships to route through expensive middleware layers that erode unit economics.
Strategic Opportunities
- Brazil's PIX Instant Payment Network:The Central Bank of Brazil's real-time payment system reached universal coverage within 18 months of launch, creating whitespace for embedded lending and merchant cash advance products built on transaction data visibility.
- Wealth Management Convergence:Robo-advisory platforms are integrating cryptocurrency custody and alternative asset tokenization, capturing millennial and Generation Z investors who reject traditional brokerage relationships.
- Regulatory Sandboxes:The UK Financial Conduct Authority and Singapore's Monetary Authority operate structured testing environments that reduce compliance costs for blockchain-based settlement and decentralized finance protocols.
Industry Challenges
- AI Model Explainability Requirements:Credit decisions automated through neural networks face scrutiny under fair lending laws, forcing engineering teams to retrofit interpretability tools that compromise predictive accuracy.
- Cross-Border Reconciliation Complexity:Multi-currency payment flows encounter fragmented settlement windows and correspondent banking relationships that delay fund availability and increase working capital requirements for treasury platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech Technologies Market |
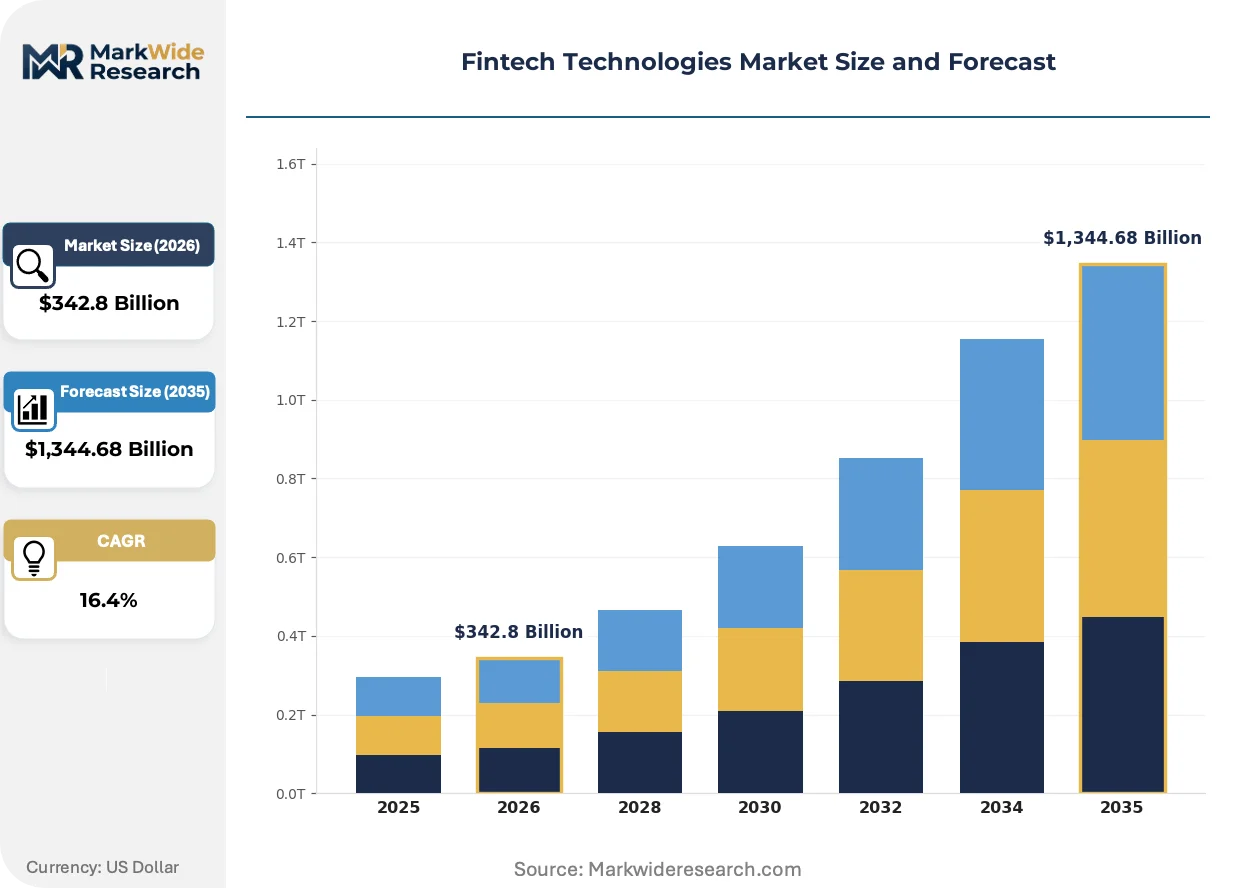
| Market Size in 2026 | $342.8 Billion |
| Market Size in 2035 | $1,344.68 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Payment Processing, Digital Wallets, Wealth Management, Lending Platforms End User Type: Consumers, SMEs, Large Enterprises, Financial Institutions Technology: Blockchain, Artificial Intelligence, Machine Learning, Cloud Computing Service Model: Software as a Service, Platform as a Service, Infrastructure as a Service, Others |
| Companies Covered | Visa, Mastercard, Tencent, Stripe, PayPal, Ant Group, Block, Adyen, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech Technologies Market Shifts & Advancements
Financial infrastructure is fragmenting into composable service layers that unbundle traditional banking functions. Technology vendors now compete to supply specialized components—identity verification, ledger management, compliance monitoring—that platform operators assemble into customer-facing products.
Core banking technology is migrating from monolithic on-premise installations to containerized microservices architectures. Neobanks and challenger institutions adopt cloud-native ledger systems that deploy feature updates within hours rather than quarters. This migration from legacy batch processing to event-driven streaming is compressing product development cycles and enabling real-time personalization of financial products.
Europe's Digital Operational Resilience Act imposes strict ICT risk management requirements on financial entities and their critical third-party providers. The regulation mandates incident reporting thresholds, penetration testing frequencies, and exit strategies for cloud-dependent operations. Payment service providers and cryptocurrency custodians face the heaviest compliance burdens, with many restructuring vendor contracts to satisfy concentration risk limits.
Corporate treasury departments are consolidating vendor relationships around platforms that unify payables, receivables, and liquidity management. This consolidation displaces point solutions for invoice financing and foreign exchange hedging. The shift is most visible among mid-market enterprises in Germany and the Netherlands, where CFOs prioritize working capital visibility over specialized functionality.
Fintech Technologies Market Segmentation
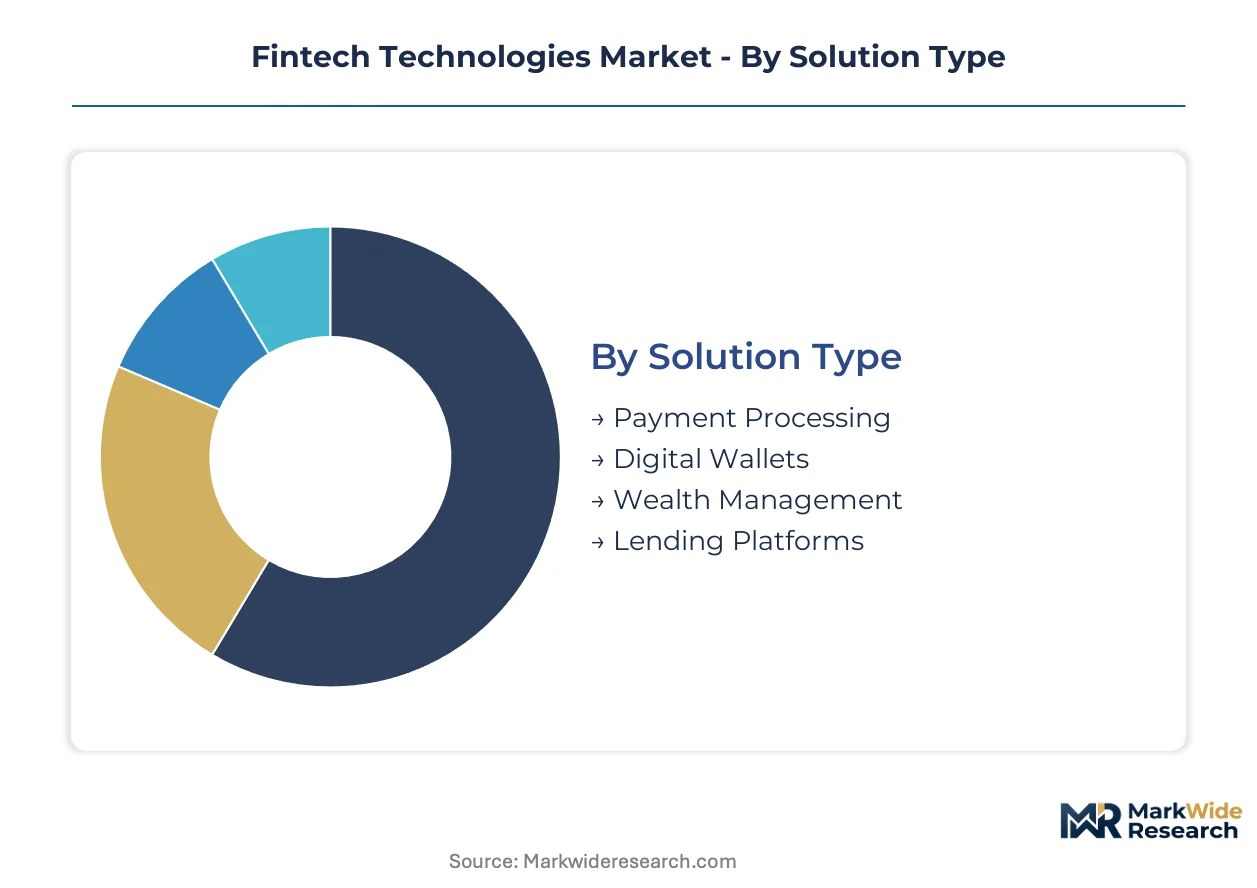
Fintech technologies fragment across multiple axes that determine deployment architecture and revenue capture. Solution type dictates capital intensity and regulatory exposure. Technology selection shapes fraud detection accuracy and underwriting speed. Service model choices determine margin structure and customer lock-in duration.
Solution Type:
Mature transaction infrastructure dominates established revenue pools while emerging credit and wealth interfaces expand addressable markets.
- Payment Processing:Real-time clearing systems and API-based merchant acquiring form the technical backbone. India's Unified Payments Interface and Brazil's PIX network concentrate demand as emerging economies leapfrog card-based rails. Per-transaction economics and regulatory fragmentation across state-level licensing regimes constrain margin expansion.
- Lending Platforms:Alternative credit scoring models analyze cash-flow data from accounting software and e-commerce platforms. SME borrowers in fragmented credit markets drive adoption as traditional FICO-based underwriting excludes thin-file applicants. Machine learning deployment faces scrutiny under fair lending explainability requirements.
- Digital Wallets:Super-app architectures consolidate payments, identity, and merchant discovery. Embedded finance licensing allows non-bank platforms to hold customer funds without full banking charters.
- Wealth Management:Robo-advisory interfaces integrate cryptocurrency custody and alternative asset tokenization. Millennial and Generation Z investors reject traditional brokerage relationships.
Payment Processing retains volume leadership; Lending Platforms hold the steepest expansion curve.
End User Type:
Customer scale determines integration complexity and customization requirements across the deployment spectrum.
- SMEs:Cash-flow visibility tools and working capital financing dominate procurement priorities. Mid-market enterprises in Germany and the Netherlands consolidate vendor relationships around unified payables and receivables platforms.
- Financial Institutions:Legacy core banking migration and API interoperability mandates consume technology budgets. COBOL-based platforms resist integration, forcing expensive middleware layers.
- Consumers:Peer-to-peer transfers and merchant payments concentrate demand in mobile-first emerging markets.
- Large Enterprises:Treasury management platforms unify multi-currency liquidity and foreign exchange hedging. Cross-border reconciliation complexity increases working capital requirements.
SMEs capture platform investment priority; Financial Institutions generate the longest contract durations.
Technology:
Algorithmic capabilities separate margin capture leaders from commodity infrastructure providers.
- Artificial Intelligence:Neural networks power fraud detection and algorithmic underwriting with sub-second decision latency. Credit decisions face regulatory scrutiny under fair lending laws, forcing engineering teams to retrofit interpretability tools.
- Machine Learning:Cash-flow prediction models and behavioral biometrics reduce default rates and authentication friction. Alternative data ingestion from accounting software and e-commerce platforms expands addressable borrower bases.
- Blockchain:Distributed ledger settlement reduces correspondent banking dependencies for cross-border flows. Central bank digital currency pilots replicate India's UPI scalability in other emerging economies.
- Cloud Computing:Containerized microservices architectures compress product development cycles from quarters to hours. Three-dominant-hyperscale concentration creates systemic vulnerability when data localization mandates conflict with global architectures.
Artificial Intelligence commands premium pricing; Machine Learning is expanding most quickly across underwriting applications.
Service Model:
Abstraction depth determines customer technical burden and vendor margin sustainability.
- Software as a Service:Pre-configured financial modules deploy through browser-based interfaces with minimal IT involvement. Neobanks and challenger institutions adopt cloud-native ledger systems for rapid feature iteration.
- Platform as a Service:Composable service layers unbundle banking functions into specialized components—identity verification, ledger management, compliance monitoring—that operators assemble into customer-facing products.
- Infrastructure as a Service:Bare-metal compute and storage resources support regulated workloads with strict data residency requirements. Europe's Digital Operational Resilience Act imposes incident reporting and penetration testing frequencies on critical third-party providers.
- Others:Hybrid deployments and managed services bridge legacy on-premise installations with cloud-native capabilities.
Software as a Service dominates customer acquisition economics; Platform as a Service is gaining share fastest among embedded finance providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fintech services remain lopsided, with the United States and United Kingdom generating surplus in payment infrastructure licensing while India and Brazil import embedded finance capabilities to modernize domestic banking rails.
United States
Real-time payment adoption through The Clearing House's RTP network and FedNow service drives infrastructure modernization. The CFPB's emerging open banking rules and state-level money transmission licensing create fragmented compliance requirements. New York and San Francisco financial technology clusters concentrate venture deployment for B2B payment orchestration platforms.
United Kingdom
PSD2-mandated API standardization and account information service provider licensing accelerate third-party payment initiation. The Financial Conduct Authority's regulatory sandbox reduces compliance costs for blockchain settlement pilots. London's Square Mile and Canary Wharf districts anchor European fintech headquarters concentration for banking-as-a-service providers.
India
Unified Payments Interface transaction volumes and merchant onboarding expansion concentrate demand in mobile-first payment infrastructure. The Reserve Bank of India's payment aggregator licensing and data localization mandates shape vendor compliance requirements. Mumbai and Bangalore technology corridors host domestic payment switch operators and neobank development centers.
Brazil
PIX instant payment network universal coverage within eighteen months creates whitespace for embedded lending products built on transaction data visibility. The Central Bank of Brazil's open finance regulations mandate standardized API exposure for account and credit data. São Paulo's financial district anchors Latin American fintech venture deployment and banking technology development.
Singapore
Cross-border payment corridor expansion and digital banking license issuance attract regional headquarters placement. The Monetary Authority of Singapore's regulatory sandbox and Project Guardian tokenization pilots shape institutional DeFi testing. The Marina Bay financial district concentrates wealth technology and treasury management platform development for Southeast Asian markets.
Fintech Technologies Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying identity verification, ledger management, and compliance monitoring modules. The vendor base concentrates around payment orchestration and embedded finance licensing, with three to five hyperscale operators capturing disproportionate transaction flow economics. Strategic archetypes include full-stack super-app operators, API-first infrastructure providers, and vertical-specialized lending platforms. Dominant competitive moves encompass banking-as-a-service partnership expansion and alternative data underwriting model deployment.
Among United States-based payment infrastructure providers, Stripe and Block occupy positions anchoring merchant-facing fintech stack assembly. Dutch-listed Adyen exemplifies the unified commerce platform archetype processing online, in-store, and mobile transactions through single integrations. Chinese technology conglomerates Tencent and Ant Group represent super-app operators dominating consumer finance interfaces through consolidated payment, credit, and wealth management functionality.
| Leading Market Players |
|---|
| Visa |
| Mastercard |
| Tencent |
| Stripe |
| PayPal |
| Ant Group |
| Block |
| Adyen |
| Fiserv |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud computing infrastructure across the United States and Western Europe is compressing margins for Infrastructure-as-a-Service providers while simultaneously lowering entry barriers for fintech platforms that depend on elastic compute resources. This utilization dynamic forces hyperscale providers to compete on price while embedding customers through long-term committed-use contracts that lock in favorable unit economics.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels in payment processing and core banking modules. Price differentiation hinges on API call volume thresholds and ISO 27001 certification tiers that separate regulated financial institutions from unlicensed technology vendors. Cost compression in standard-tier SaaS offerings is intensifying because containerized microservices architectures have commoditized ledger management functionality. Mid-market enterprises in Germany and the Netherlands exhibit the highest price sensitivity as they consolidate vendor relationships around unified treasury platforms.
Supply Chain Analysis
Upstream semiconductor fabrication capacity in Taiwan, South Korea, and the United States feeds critical hardware dependencies for payment terminal manufacturing and data center infrastructure. Specialized GPU clusters for AI-powered fraud detection and high-throughput networking equipment constitute concentrated input categories. Single-source vulnerability around Taiwan-based foundries creates systemic exposure when geopolitical tensions disrupt wafer supply. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels that bypass traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fintech technologies market is exiting a capital-constrained trough as central bank rate normalization restores venture deployment capacity and enterprise software procurement budgets expand. This cyclical recovery is underpinned by the resumption of real-time payment infrastructure buildouts that stalled during liquidity tightening.
For Market Incumbents: Pre-empt embedded finance licensing fragmentation by securing banking-as-a-service partnerships across multiple jurisdictions before regulatory harmonization closes arbitrage windows. Consolidate API gateway providers to reduce middleware costs that erode unit economics in legacy core banking integrations. Vertical integration into alternative data scoring models offers defensive positioning against neobanks leveraging cash-flow analytics from accounting software ecosystems.
For New Entrants and Emerging Players: Brazil's PIX network and India's UPI ecosystem present geographic underpenetration where instant payment rails have created transaction data visibility without mature embedded lending overlays. Target SME treasury management in fragmented European markets where mid-market enterprises seek unified payables-receivables platforms. A direct-to-CFO go-to-market angle leveraging working capital optimization narratives outperforms feature-comparison sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native core banking segments as containerized microservices reduce infrastructure deployment costs. Long-term viability favors platform operators with embedded finance licensing rather than point-solution vendors facing consolidation pressure. The signal to watch is central bank digital currency pilot announcements that validate real-time payment infrastructure scalability and signal regulatory appetite for innovation-permissive frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Banking-as-a-Service Licensing Expansion | Embedded finance partnerships with Stripe and Adyen enable non-bank platforms to originate loans without full charters. |
| Alternative Data Underwriting Deployment | Machine learning models analyzing e-commerce cash flows extend credit access to thin-file borrowers excluded from FICO-based systems. |
| Real-Time Payment Infrastructure Buildout | India's UPI and Brazil's PIX demonstrate scalable architectures that emerging economies replicate through central bank pilots. |
| Core Banking Microservices Migration | Containerized ledger systems compress product development cycles from quarters to hours for neobank challengers. |
| Regulatory Sandbox Participation | UK Financial Conduct Authority and Singapore MAS testing environments reduce compliance costs for blockchain settlement protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment infrastructure executives, regulatory compliance officers, neobank CTOs, and treasury platform procurement leads at mid-market enterprises. Secondary validation drew from SEC 10-K filings of listed payment processors, central bank annual reports on real-time payment volumes, and API documentation from open banking standard-setters. Bottom-up transaction volume modeling and top-down macroeconomic scenario analysis were triangulated to anchor market sizing.
Calibration against historical adoption curves for payment infrastructure and lending platform deployments informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed solution type, end-user scale, technology stack, and service model abstraction depth, with regional regulatory divergence treated as a cross-cutting variable. CAGRs were derived from installed base growth rates and average revenue per user trajectories, incorporating cloud infrastructure cost deflation and embedded finance penetration assumptions.
Practitioners should monitor central bank digital currency pilot announcements and open banking rulemaking timelines for early signals of infrastructure demand inflection. Forecasts reflect assumptions around regulatory harmonization pace and hyperscale cloud provider concentration limits. Cross-checking against disclosed payment volume data from national real-time clearing systems is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spend Management Platform Market
FinTech
Smart Finance Technologies Market
FinTech
Embedded Finance Market
FinTech
Financial App Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Financial Analytics Market
FinTech
US AI in Fintech Market
FinTech
Financial Services Cloud Market
FinTech
Smart Advisors Market
FinTech
Financial Audit Software Market
FinTech
Transaction Monitoring Software Market
FinTech
Robo-Advisory Services Market
FinTech
AI in Fintech Market
FinTech
Financial Fraud Detection Software Market
FinTech
Global Fintech Market
FinTech
United Kingdom AI in Fintech Market