
 Vietnam Fintech Market | 2026-2036
Vietnam Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Fintech Market Outlook
Asset-light platform models and revenue-based financing are rewriting competitive entry barriers for fintech operators in Vietnam. M_Service (MoMo) leverages its super-app distribution to sustain dominance in peer-to-peer transfers and merchant payments. VNPay anchors the public-sector digital payment stack through integration with government service portals. ZaloPay (VNG) competes by embedding financial services within Vietnam's largest social messaging platform.
Vietnam fintech encompasses technology-enabled financial services delivered through software platforms, mobile applications, and cloud infrastructure to process payments, extend credit, and manage investments without traditional branch networks. These systems rely on real-time transaction processing, API-based bank integrations, and localized compliance modules to serve users with limited legacy banking access. Payment gateway and digital wallet services lead transaction volume, while online lending platforms capture expanding margin pools among underbanked consumer segments. Blockchain and artificial intelligence segments are gaining structural importance as risk-scoring engines and cross-border settlement layers mature.
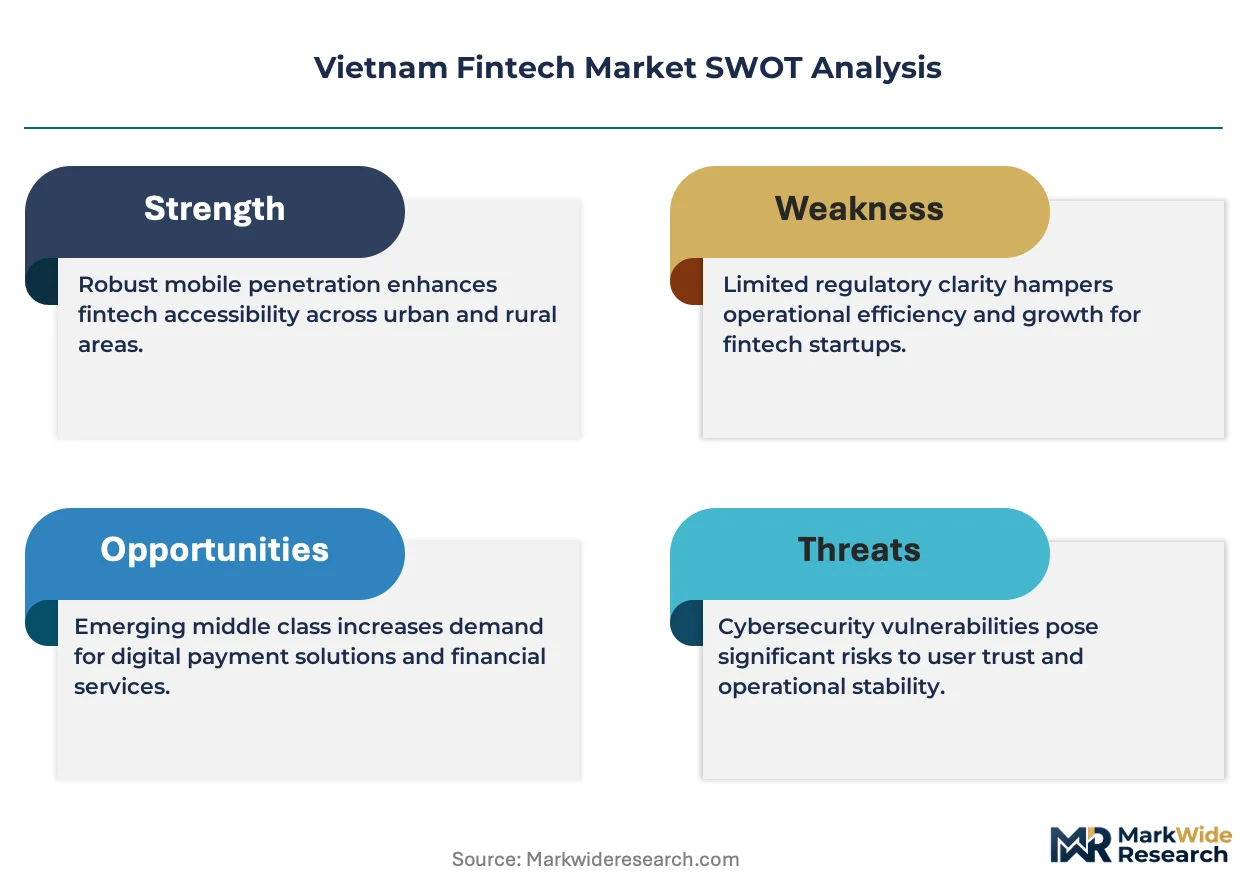
The State Bank of Vietnam governs licensing through Circular 23 and sandbox directives, while the Ministry of Public Security enforces cybersecurity standards under the Cybersecurity Law. These frameworks shape product architecture by mandating local data residency, multi-factor authentication protocols, and capital adequacy buffers for lending operators. Stakeholders must monitor how forthcoming e-KYC regulations and open-banking directives alter customer acquisition economics and partnership structures.
Market Dynamics
Asset-light platform models are compressing capital requirements for market entry while the State Bank of Vietnam's sandbox licensing framework accelerates product-to-market velocity for mobile-first financial services.
Growth Catalysts
- Circular 23 Licensing Framework:The State Bank of Vietnam's regulatory sandbox reduces compliance timelines for fintech startups testing peer-to-peer lending and digital wallet products.
- Ho Chi Minh City Merchant Concentration:Urban small businesses bypass traditional banking infrastructure through QR-code payment adoption at point-of-sale terminals.
- Super-App Distribution:Messaging platform ecosystems embed financial services within daily communication workflows, collapsing customer acquisition costs for underbanked segments.
Market Restraints
- Local Data Residency Mandates:The Cybersecurity Law requires server infrastructure placement within Vietnam, raising operational expenditure for foreign platform operators.
- Capital Adequacy Buffers:Lending-focused fintechs face minimum reserve requirements that constrain balance sheet expansion velocity relative to asset-light payment processors.
- Multi-Factor Authentication Protocols:Regulatory mandates for biometric verification increase friction in customer onboarding flows compared to simplified registration in neighboring markets.
Strategic Opportunities
- Open-Banking Directives:Forthcoming API standardization mandates will enable account aggregation services linking traditional bank deposits with third-party fintech interfaces.
- Blockchain Settlement Layers:Cross-border remittance corridors between Vietnam and labor-export destination markets present white space for distributed ledger-based transfer protocols.
- Artificial Intelligence Risk Scoring:Convergence of machine learning algorithms with alternative data sources enables credit extension to thin-file borrowers excluded from conventional bureau scoring.
Industry Challenges
- Embedded Finance Integration:Technical complexity increases when reconciling legacy core banking systems with real-time API architectures demanded by platform partners.
- E-KYC Compliance Timeline:Pending electronic know-your-customer regulations create uncertainty around identity verification workflows and partnership liability structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Fintech Market |
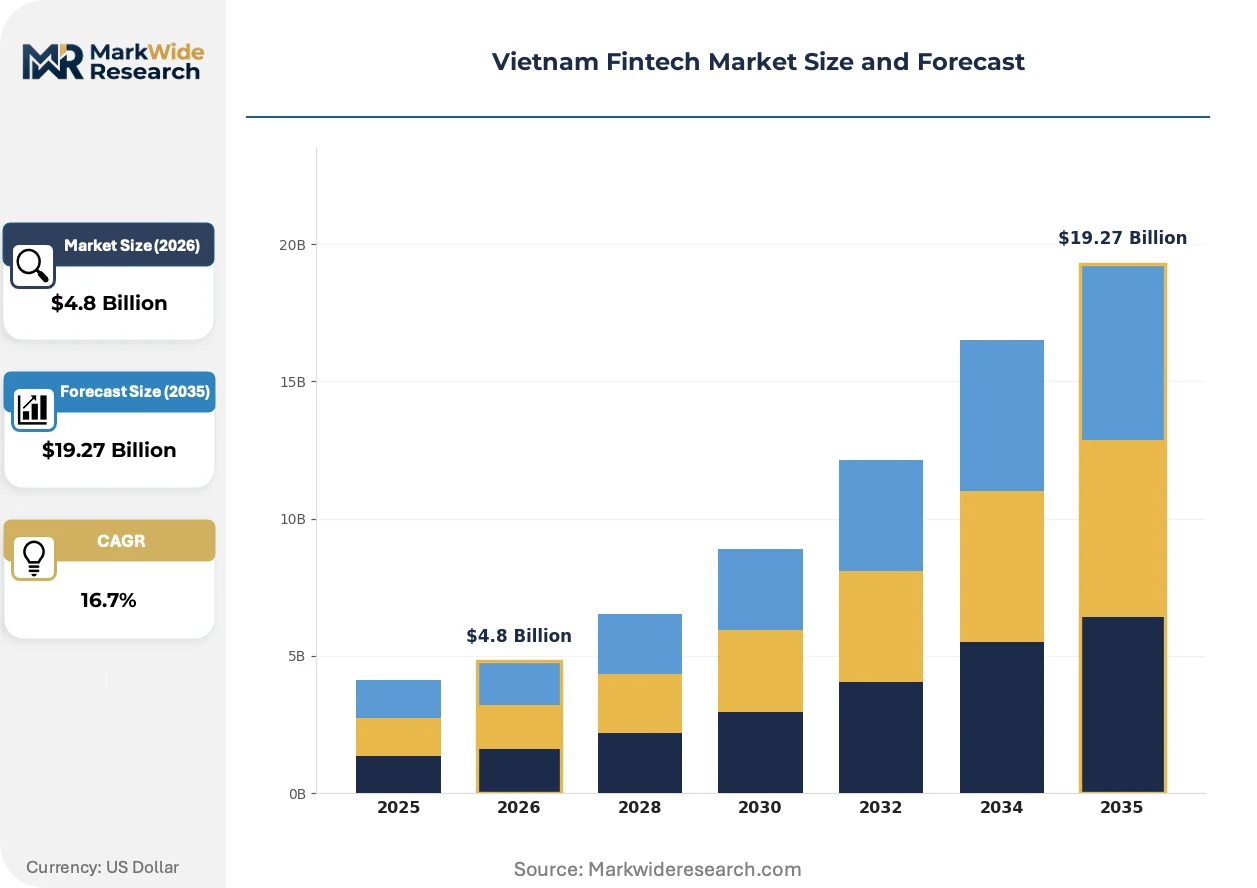
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Gateway, Digital Wallet, Online Lending, Investment Platform Customer Type: Small Businesses, Startups, Millennials, Large Enterprises Technology: Blockchain, Artificial Intelligence, Mobile Applications, Cloud Computing Regulatory Environment: Fintech Regulations, Licensing Requirements, Compliance Framework, Consumer Protection |
| Companies Covered | ShopeePay, Vietcombank Digital, M_Service (MoMo), Cake by VPBank, VPBank, VNPay, Grab Financial Group VN, Timo Digital Bank, ZaloPay (VNG), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Fintech Market Strategic Shifts
Real-time transaction processing architectures and API-based bank integrations are restructuring how financial services reach users without legacy branch access.
Cloud-native core banking infrastructure is rendering obsolete on-premise legacy systems that previously required multi-year deployment cycles. Tier-two fintech operators and neobank challengers adopt containerized microservices architectures within months rather than years. This compression is rendering obsolete the competitive moat that incumbent banks derived from sunk-cost infrastructure investments.
The State Bank of Vietnam's forthcoming e-KYC regulations will mandate biometric verification standards for digital account opening. This policy shift forces platform operators to rebuild onboarding flows around facial recognition and liveness detection protocols. Mobile wallet providers and online lenders in Hanoi and Ho Chi Minh City are pre-emptively integrating certified identity verification APIs to avoid compliance discontinuities.
Urban millennials concentrate transaction volumes within super-app ecosystems that bundle messaging, commerce, and financial services. Traditional standalone banking applications lose engagement frequency as users consolidate daily financial interactions within messaging-platform wallets. This behavioral consolidation is most visible in Ho Chi Minh City, where merchant payment acceptance now prioritizes QR-code compatibility with dominant social platforms over traditional card network terminals.
Vietnam Fintech Market Segmentation
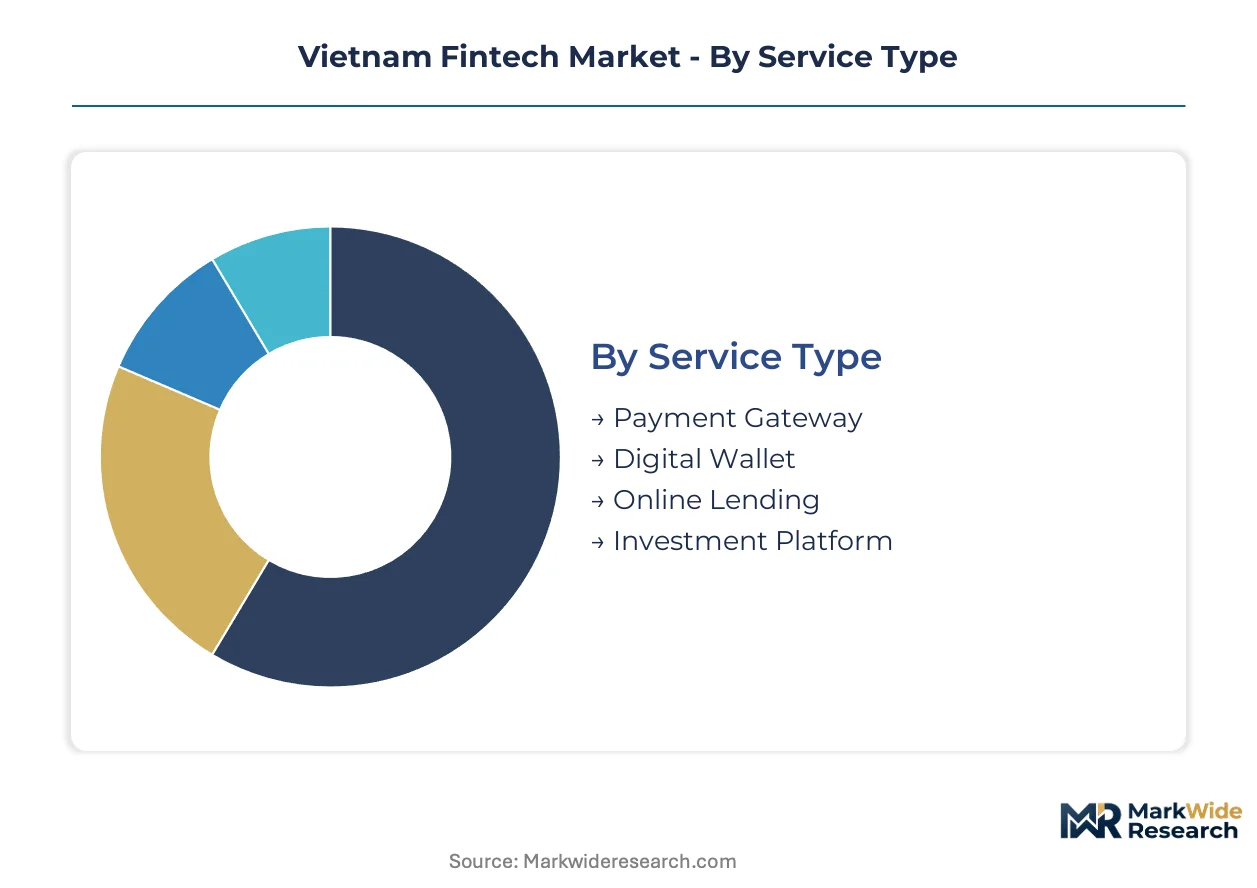
Vietnam fintech operators target distinct user cohorts with specialized service architectures. Payment processors optimize for merchant transaction density while lending platforms prioritize risk-scoring precision across thin-file borrowers.
Service Type:
Post-implementation support intensity varies sharply across service categories, with payment infrastructure demanding 24/7 uptime guarantees versus lending platforms requiring periodic portfolio monitoring.
- Payment Gateway:Real-time transaction routing systems process merchant settlements through API-integrated bank networks. Ho Chi Minh City retailers drive volume through QR-code point-of-sale terminals that bypass traditional card network fees.
- Digital Wallet:Mobile-first stored-value accounts enable peer-to-peer transfers and utility bill payments through super-app interfaces. Hanoi urban millennials concentrate daily transaction frequency within messaging-platform ecosystems rather than standalone banking applications.
- Online Lending:Algorithmic credit scoring extends unsecured consumer loans to underbanked segments with limited bureau history.
- Investment Platform:Retail wealth management tools democratize access to mutual funds and government bonds through fractional share structures.
By volume, Payment Gateway leads. By growth pace, Online Lending is ahead.
Customer Type:
Cost-to-serve economics stratify sharply across customer tiers, with small businesses generating thin margins at scale versus large enterprises demanding customized integration support.
- Small Businesses:Informal sector merchants adopt QR-code acceptance to eliminate cash-handling overhead. Street vendors in Ho Chi Minh City District 1 prioritize instant settlement velocity over interest-bearing deposit features.
- Startups:Venture-backed technology companies require multi-currency treasury management and automated payroll disbursement. These users concentrate in Hanoi startup clusters where regulatory sandbox access accelerates product testing.
- Millennials:Digitally native consumers aged 25-35 drive super-app wallet adoption through social payment splitting and ride-hailing integration.
- Large Enterprises:Corporate treasuries demand white-label payment infrastructure with dedicated API support and SLA guarantees.
Small Businesses dominate transaction count. Startups show the steepest expansion trajectory.
Technology:
Development maturity separates production-ready architectures from experimental deployments, with mobile applications achieving mass scale while blockchain remains in proof-of-concept phases.
- Blockchain:Distributed ledger protocols enable cross-border remittance settlement with reduced correspondent banking friction. Labor-export corridors linking Vietnam to Gulf state markets present primary deployment opportunities.
- Artificial Intelligence:Machine learning models score credit risk using alternative data from mobile usage patterns and e-commerce transaction history. Thin-file borrowers in rural provinces gain access previously blocked by conventional bureau reliance.
- Mobile Applications:Native iOS and Android interfaces deliver financial services through smartphone penetration exceeding 75% of working-age adults.
- Cloud Computing:Containerized microservices architectures reduce infrastructure deployment cycles from years to months for tier-two operators.
Mobile Applications capture the largest user base. Artificial Intelligence is climbing the fastest.
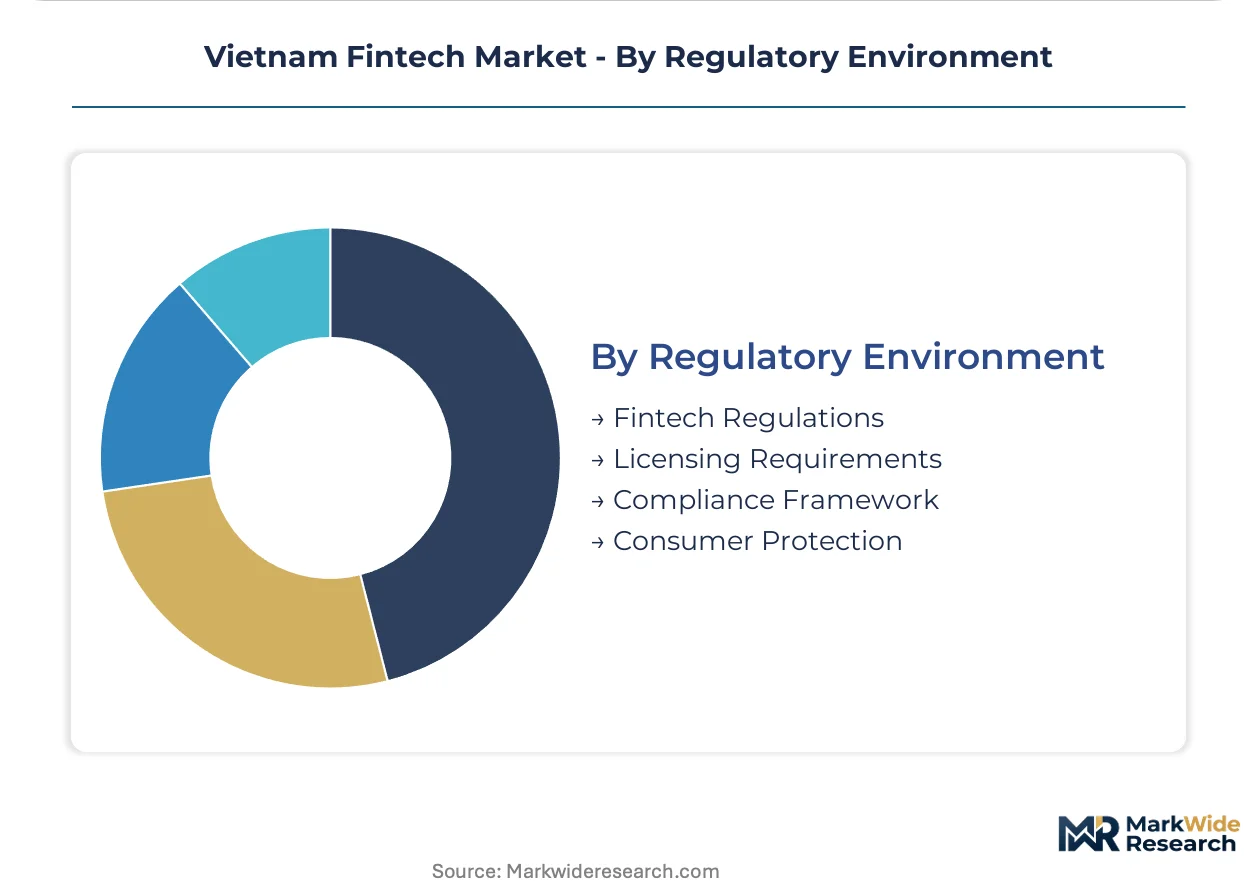
Regulatory Environment:
Compliance burden intensity correlates with licensing tier, with payment processors facing lighter ongoing obligations than lending operators subject to capital adequacy monitoring.
- Fintech Regulations:State Bank of Vietnam directives govern permissible activities through Circular 23 and sandbox licensing frameworks. These rules mandate local data residency and biometric verification standards.
- Licensing Requirements:Capital buffers and operational continuity plans constrain market entry velocity for credit-focused operators. Minimum reserve thresholds exceed requirements for pure payment processors.
- Compliance Framework:Cybersecurity Law mandates multi-factor authentication and incident reporting protocols to the Ministry of Public Security.
- Consumer Protection:Disclosure requirements and dispute resolution mechanisms govern marketing practices and fee transparency.
Fintech Regulations structure the broadest operational scope. Licensing Requirements impose the heaviest compliance concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State Bank of Vietnam's sandbox licensing framework accelerates fintech deployment across urban commercial corridors. Ho Chi Minh City and Hanoi concentrate transaction volumes as regulatory clarity attracts platform operators. Provincial expansion follows merchant payment density into secondary cities.
Ho Chi Minh City
District 1 street vendors drive QR-code payment adoption to eliminate cash-handling overhead. Circular 23 mandates local data residency and biometric verification standards for digital wallet operators. Bitexco Financial Tower anchors fintech co-working clusters where venture-backed startups test peer-to-peer lending products.
Hanoi
Government technology procurement channels channel public-sector digital payment contracts through integrated service portals. Cybersecurity Law enforcement by the Ministry of Public Security requires multi-factor authentication protocols for all financial applications. Cau Giay District startup incubators concentrate revenue-based financing platforms serving underbanked consumer segments.
Da Nang
Central region logistics hubs generate cross-border remittance demand from labor-export corridors. Sandbox directives enable testing of blockchain settlement protocols for Gulf state transfer corridors. Han River commercial districts host emerging merchant payment networks connecting tourism hospitality to digital infrastructure.
Can Tho
Mekong Delta agricultural cooperatives adopt mobile-first credit scoring for farm equipment financing. E-KYC regulations pending from the State Bank of Vietnam reshape identity verification workflows for rural borrowers. Ninh Kieu District banking agents extend super-app wallet penetration into previously unbanked communes.
Hai Phong
Port city manufacturing zones create payroll disbursement demand from foreign-invested enterprises. Capital adequacy buffers constrain lending-focused fintech expansion velocity relative to asset-light payment processors. Cat Bi economic zone hosts API-integrated treasury management pilots for export-oriented small businesses.
Vietnam Fintech Market Competitive Environment
On the supply side, the industry is consolidating around super-app ecosystems that embed financial services within daily communication and commerce workflows. Tier-one operators leverage existing user bases from e-commerce, ride-hailing, and social messaging to collapse customer acquisition costs. Three strategic archetypes dominate: platform-native wallets born from digital commerce, bank-spinoff digital challengers with legacy deposit bases, and independent fintech specialists with regulatory sandbox access. Competitive moves concentrate on merchant network expansion through QR-code infrastructure and strategic API partnerships with government service portals.
Within the super-app platform tier, M_Service (MoMo) and ZaloPay (VNG) exemplify distribution-first positioning that prioritizes transaction frequency over standalone banking features. VNPay anchors the public-sector vector through direct integration with state service portals. Among bank-affiliated challengers, Cake by VPBank and Timo Digital Bank occupy the neobank archetype with cloud-native core systems. These six entities represent the competitive core around which second-tier payment processors and lending specialists orbit.
| Leading Market Players |
|---|
| ShopeePay |
| Vietcombank Digital |
| M_Service (MoMo) |
| Cake by VPBank |
| VPBank |
| VNPay |
| Grab Financial Group VN |
| Timo Digital Bank |
| ZaloPay (VNG) |
| Others |
Value Chain & Pricing Dynamics
Cybersecurity Law data residency mandates create the dominant cost chokepoint, compressing margin structures for foreign platform operators while simultaneously forcing localization investments that reshape tiered service pricing across payment gateway and digital wallet segments.
Pricing Analysis
Certification level under State Bank of Vietnam Circular 23 creates the primary spread between sandbox-licensed operators and fully regulated entities. Three-tier pricing structure across premium API-integrated, standard merchant-acquiring, and economy peer-to-peer tiers reflects compliance investment recovery timelines. Pricing pressure stems from super-app ecosystems subsidizing transaction fees to capture user base. Small businesses in Ho Chi Minh City exhibit highest price sensitivity, while large enterprises absorb premium tiers for SLA guarantees.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers in Singapore, Hong Kong, and domestic Vietnamese facilities. Core banking software modules, biometric verification APIs, and QR-code payment terminals constitute critical component dependencies. Single-source vulnerability concentrates in foreign-owned cloud platforms subject to data localization enforcement. Distribution runs through API aggregator networks linking merchant acquirers to bank settlement rails.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam fintech represents early-cycle expansion as sandbox licensing collapses product-to-market timelines for mobile-first financial services.
For Market Incumbents: Entrench merchant network density through exclusive QR-code infrastructure partnerships in Ho Chi Minh City District 1 and Hanoi Cau Giay. Pre-empt e-KYC compliance investments to avoid onboarding friction discontinuities. Vertical integration into biometric verification APIs reduces third-party dependency as regulatory standards tighten. For New Entrants and Emerging Players: Provincial banking agent networks in Can Tho Mekong Delta communes present the most penetrable geography. Blockchain settlement pilots for Gulf state remittance corridors offer white-space positioning. Revenue-based financing models targeting agricultural cooperatives bypass capital adequacy buffers constraining pure lending operators. For Investors and Strategic Acquirers: Forthcoming open-banking directives reshape the acquisition landscape toward API-aggregation specialists with certified bank partnerships. Five-to-ten year viability centers on cloud-native core systems displacing legacy infrastructure. Monitor State Bank of Vietnam e-KYC implementation timelines as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Licensing | Circular 23 accelerates product testing velocity for peer-to-peer lending and wallet operators. |
| Super-App Platform Integration | Messaging ecosystem embedding collapses customer acquisition costs for underbanked segments. |
| Biometric Verification API Partnership | e-KYC pre-positioning avoids compliance discontinuities in Hanoi and Ho Chi Minh City. |
| Provincial Agent Network Expansion | Mekong Delta and Central Highlands penetration extends wallet access beyond urban millennials. |
| Blockchain Remittance Corridor Pilot | Gulf state labor-export settlement protocols reduce correspondent banking friction. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of State Bank of Vietnam regulatory circulars, Ministry of Public Security cybersecurity directives, and hyperscaler infrastructure disclosures. Primary interviews engaged fintech product managers, regulatory compliance officers at payment processors, merchant acquisition leads, and sandbox program administrators. Secondary sources encompassed Circular 23 licensing frameworks, Cybersecurity Law implementation guidelines, and API documentation from dominant super-app platforms. Bottom-up transaction volume modeling triangulates against top-down market sizing from banking sector disclosures.
Forecast inputs incorporate service type segmentation across payment gateway, digital wallet, online lending, and investment platform categories; customer tier stratification from street vendors to corporate treasuries; and technology deployment patterns spanning mobile applications, cloud infrastructure, and emerging blockchain protocols. CAGRs derive from regression analysis of historical transaction velocity against smartphone penetration curves and regulatory licensing velocity. Sandbox admission rates and e-KYC implementation timelines constitute Vietnam-specific forecast variables.
Macroeconomic conditions sit as an overlay; deviation in dong-dollar exchange volatility or labor-export remittance flows would shift the trajectory. Forecasts reflect documented assumptions around regulatory timeline adherence and infrastructure deployment schedules. Cross-checking against State Bank of Vietnam quarterly licensing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Fintech Credit Management Blockchain Market
FinTech
Automotive Fintech Market
FinTech
Fintech Crisis Management Market
FinTech
Australia Fintech Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Global Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Stock Trading App Market
FinTech
Smart Finance Technologies Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Financial Technology Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Embedded Finance Market
FinTech
Financial Management Software Market
FinTech
Smart Finance Connectivity Market