
 United Kingdom Data Analytics in Banking Market | 2026-2036
United Kingdom Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Analytics in Banking Market Insights
Market Dynamics
London is reconfiguring its position as Europe's dominant banking analytics hub despite post-Brexit regulatory divergence. IBM leverages its Watson platform and longstanding relationships with UK clearing banks to sustain enterprise-grade deployments across core banking systems. Microsoft Corporation anchors cloud-native analytics adoption through Azure Synapse and Power BI integrations with British retail banking networks. SAS Institute Inc. competes on specialized risk analytics and regulatory reporting modules tailored to Prudential Regulation Authority templates.
Segmentation Analysis
Data analytics in banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate actionable intelligence for credit decisions, risk calibration, and customer engagement. Cloud-based deployment is displacing legacy on-premises infrastructure as UK banks prioritize elastic compute for stress-testing and real-time fraud detection. Customer analytics and fraud detection solution types capture disproportionate investment flows, with retail banks and investment firms representing the most digitally mature end-user categories in application penetration.
Regulatory Environment
The Prudential Regulation Authority and Financial Conduct Authority jointly enforce capital adequacy and consumer protection standards that mandate auditable analytics pipelines and model explainability. GDPR and the UK Data Protection Act impose strict governance requirements on customer data usage, directly shaping vendor selection criteria and platform architecture decisions. Stakeholders must monitor evolving UK-EU regulatory equivalence negotiations and their implications for cross-border data analytics service provision.
Market Dynamics
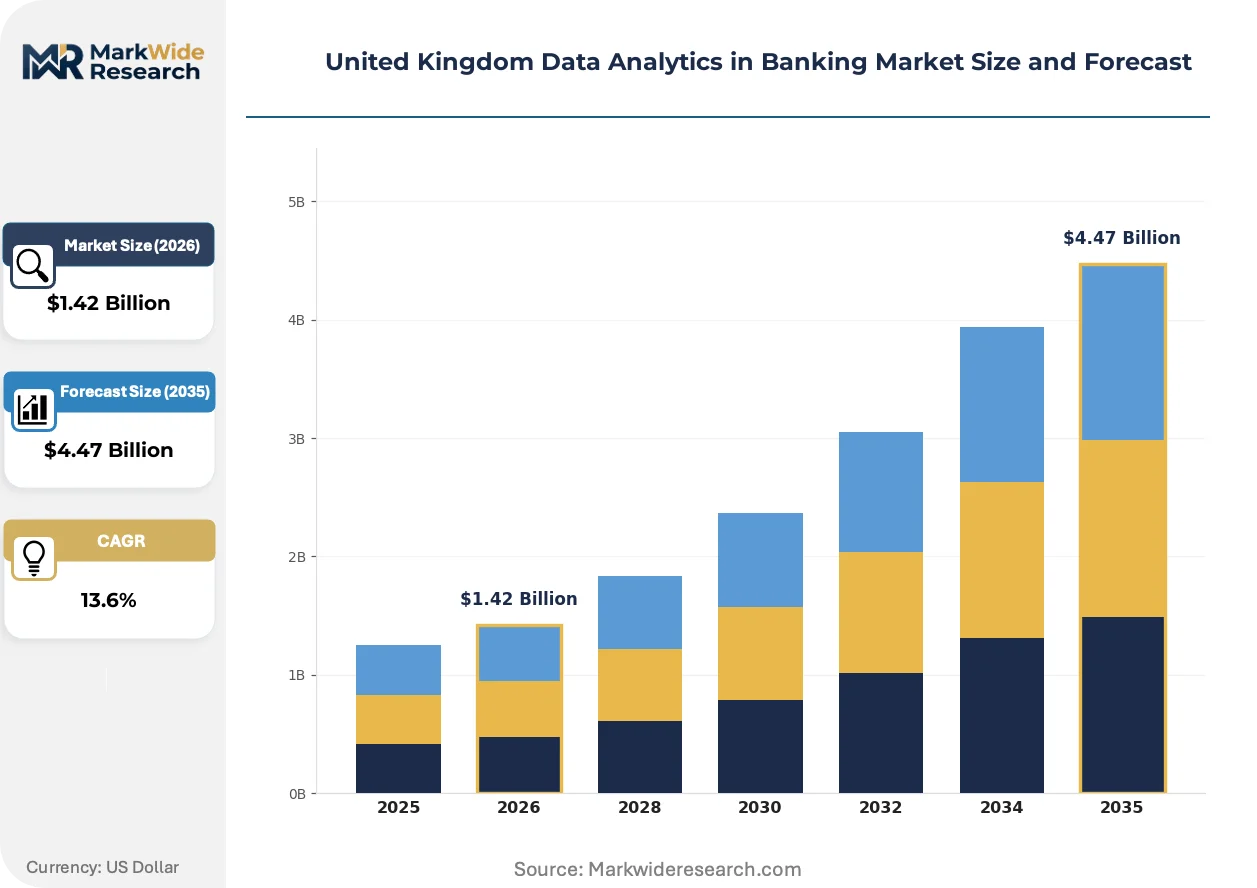
Cloud-native analytics infrastructure is compressing deployment timelines for UK banks while the Financial Conduct Authority's consumer duty mandates force architectural rewrites toward explainable AI pipelines.
Growth Catalysts
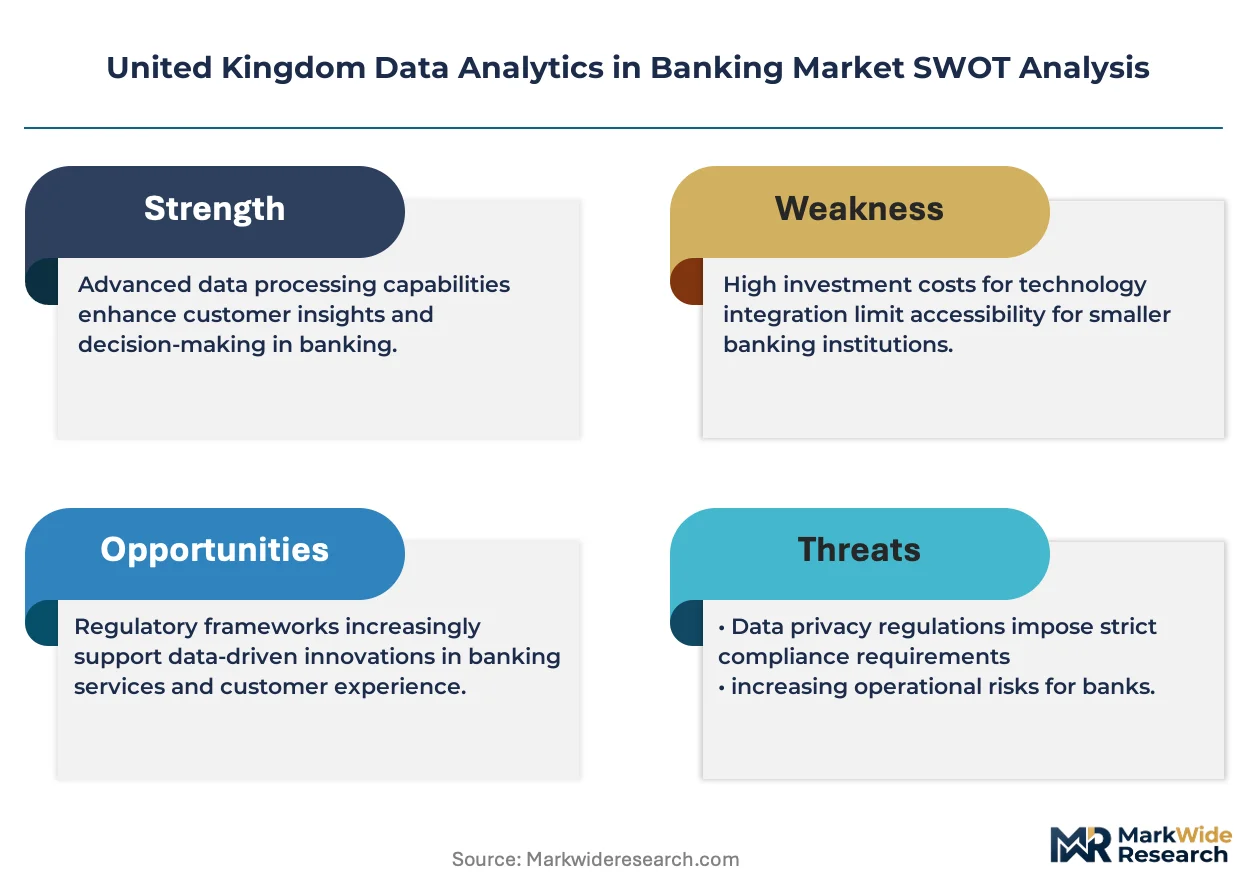
- Consumer Duty Rules:The Financial Conduct Authority's transparency mandates compel investment in auditable machine learning workflows for credit decisions and fraud detection.
- Elastic Compute:Cloud-based stress-testing platforms enable real-time scenario modeling that on-premises hardware cannot support, accelerating regulatory compliance cycles.
- London Cluster Density:Concentrated data science talent in the Square Mile and Canary Wharf reduces recruitment friction for specialized analytics roles.
Market Restraints
- GDPR Compliance Costs:Cross-border data transfer restrictions under UK-EU adequacy uncertainty inflate legal and technical overhead for multinational banks.
- Legacy Core Dependency:Mainframe-anchored transaction systems resist API-native analytics integration, trapping functionality in siloed batch processes.
- Talent Pipeline Constraints:The UK produces insufficient quantitative risk specialists relative to demand from investment banking and insurance sectors.
Strategic Opportunities
- Open Banking Expansion:The Competition and Markets Authority's data-sharing mandates create new revenue streams from consented customer data monetization.
- Scotland and Northern England:Lower operational costs in Edinburgh and Manchester attract secondary analytics centers away from London's premium real estate.
- AI-RegTech Convergence:Automated Prudential Regulation Authority reporting templates reduce manual compliance burden while improving submission accuracy.
Industry Challenges
- Model Risk Management:The Bank of England's SR 11-7 equivalent guidelines demand independent validation teams that most mid-tier banks lack.
- Skills Mismatch:Traditional credit analysts require retraining in Python and cloud tooling, creating productivity gaps during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Analytics in Banking Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Analytics Solution Type: Customer Analytics, Risk Analytics, Fraud Detection, Compliance Analytics, Operational Analytics Application: Credit Scoring, Customer Segmentation, Investment Analysis, Loan Default Prediction, Market Trend Forecasting End User: Retail Banks, Corporate Banks, Credit Unions, Investment Firms, Mortgage Providers |
| Companies Covered | IBM, Microsoft Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Finastra International Limited, Amazon Web Services, Inc., Google, TIBCO Software Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Analytics in Banking Market Trends and Innovations
Real-time streaming analytics is replacing batch processing as the default architecture for customer-facing banking applications, compressing decision latency from hours to milliseconds.
Explainable AI frameworks are migrating from research prototypes to production deployments as UK retail banks face audit requirements for algorithmic credit decisions. Major clearing institutions are embedding SHAP and LIME interpretability layers into existing Python workflows. This shift is compressing vendor selection cycles toward platforms with native transparency features rather than black-box performance optimization.
The Financial Conduct Authority's consumer duty rules are mandating documentation standards that force analytics vendors to rearchitect product roadmaps around audit trails. Banks must now demonstrate how models reach individual customer outcomes. Investment firms with discretionary portfolio management face the steepest compliance burden, driving demand for regulatory technology modules that automate explanation generation.
Scottish and Northern English financial centers are capturing analytics investment that previously concentrated exclusively in London. Edinburgh's established fund management ecosystem and Manchester's lower cost base attract satellite data science operations. This geographic diversification reduces single-point-of-failure risk while accessing talent pools outside the capital's overheated labor market.
United Kingdom Data Analytics in Banking Market Segmentation
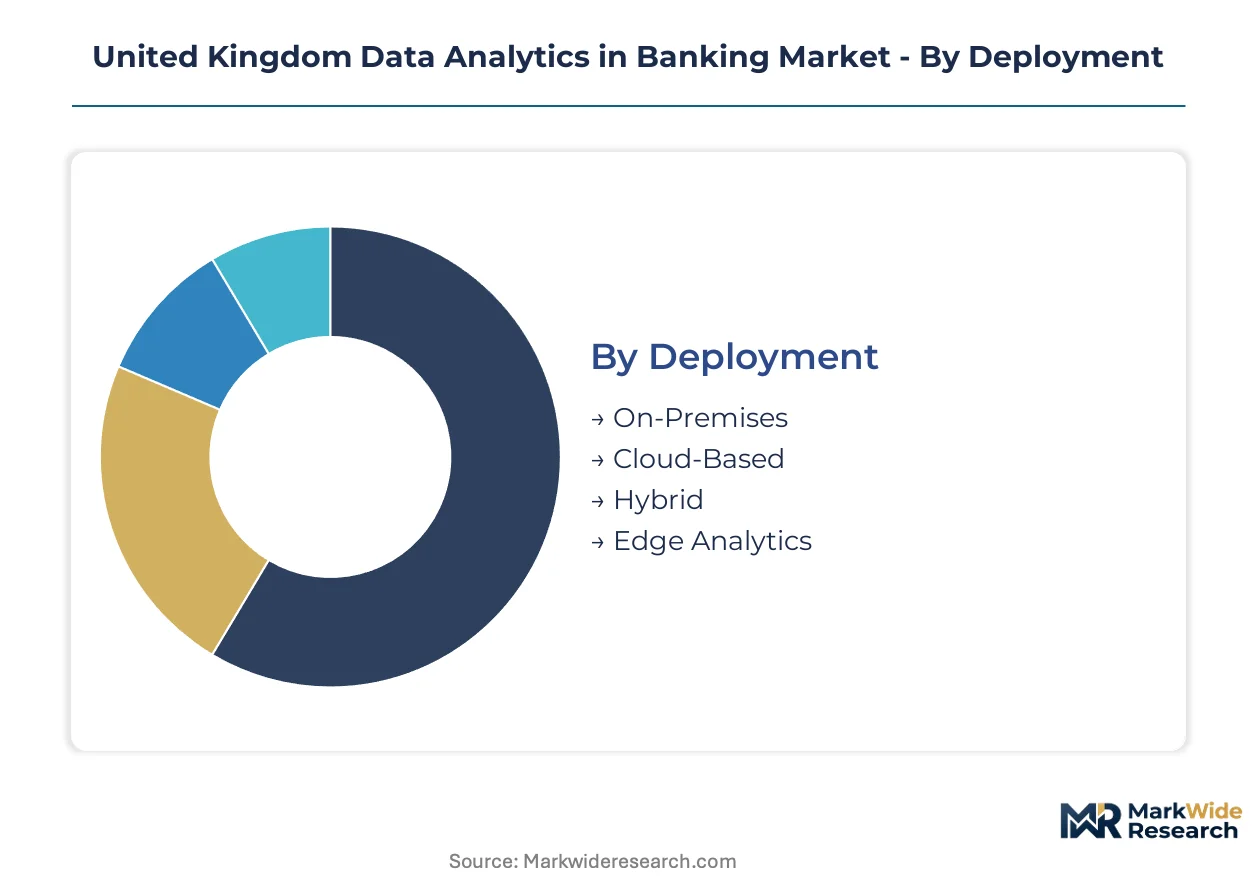
UK banks segment analytics investments by deployment architecture, solution capability, and institutional use case. Each dimension reflects divergent regulatory pressures, legacy constraints, and competitive priorities shaping procurement decisions across the Square Mile and regional financial centers.
Deployment:
Mature on-premises estates coexist with emerging cloud-native architectures as banks navigate Prudential Regulation Authority audit requirements and elastic compute demands.
- On-Premises:Hardware-resident analytics infrastructure persists where transaction data sovereignty concerns dominate. Tier-one clearing banks in London maintain mainframe-anchored deployments for core ledger analytics despite migration costs.
- Cloud-Based:Elastic compute environments enable real-time stress-testing and fraud detection pipelines that static infrastructure cannot support. Azure and AWS regions in London and Manchester attract retail banking workloads seeking regulatory-compliant data residency.
- Hybrid:Split architectures partition sensitive customer data on-premises while pushing model training to cloud environments. This configuration dominates mid-tier banks balancing GDPR compliance with AI development velocity.
- Edge Analytics:Distributed processing nodes at branch locations support low-latency customer-facing decisions. Manchester-based building societies pilot edge deployments for in-branch credit pre-qualification.
On-Premises handles the majority of throughput; Cloud-Based is the fastest mover on share.
Solution Type:
Application breadth spans customer-facing intelligence through back-office regulatory automation, with investment intensity mapping directly to Financial Conduct Authority enforcement priorities.
- Customer Analytics:Behavioral segmentation and lifetime value modeling drive personalization engines across digital banking channels. Open Banking data feeds from the Competition and Markets Authority regime accelerate consented data monetization strategies.
- Risk Analytics:Capital adequacy modeling and counterparty exposure measurement anchor prudential compliance workflows. The Bank of England's stress-testing calendar demands continuous model refinement that consumes disproportionate data science resources.
- Fraud Detection:Real-time transaction scoring identifies anomalous patterns in payment flows. Machine learning pipelines integrate with Faster Payments infrastructure to compress detection latency below settlement windows.
- Compliance Analytics:Automated regulatory reporting extracts structured submissions from raw transaction records. Consumer Duty audit trails now mandate explainable documentation for algorithmic decision pathways.
- Operational Analytics:Process mining and workforce optimization target cost-to-income ratios in branch networks. Scottish banks deploy operational intelligence to rationalize physical footprints across Highlands and Islands communities.
Risk Analytics commands the largest dedicated budgets; Customer Analytics is expanding most quickly as retail differentiation intensifies.
Application:
Use case maturity varies from established credit decisioning to emerging predictive capabilities in investment management and macro forecasting.
- Credit Scoring:Traditional logistic regression models yield to gradient-boosted ensembles incorporating alternative data streams. The Financial Conduct Authority's fair lending scrutiny demands bias audits that reshape feature engineering practices.
- Customer Segmentation:Clustering algorithms partition retail depositors by behavioral propensity rather than demographic proxies. Wealth managers in Edinburgh apply segmentation to tailor discretionary portfolio services.
- Investment Analysis:Alternative data ingestion and natural language processing extract signals from unstructured sources. Canary Wharf hedge funds compete on proprietary analytics pipelines for equity and fixed-income positioning.
- Loan Default Prediction:Early warning systems flag deteriorating credit quality across commercial and residential portfolios. Challenger banks leverage open banking transaction histories to refine probability estimates beyond credit bureau files.
- Market Trend Forecasting:Macroeconomic scenario modeling supports treasury and trading desk decisions. Brexit-related volatility sustained investment in nowcasting capabilities for interest rate and currency movements.
Credit Scoring absorbs the deepest institutional expertise; Investment Analysis is gaining share fastest as asset managers compete on data differentiation.
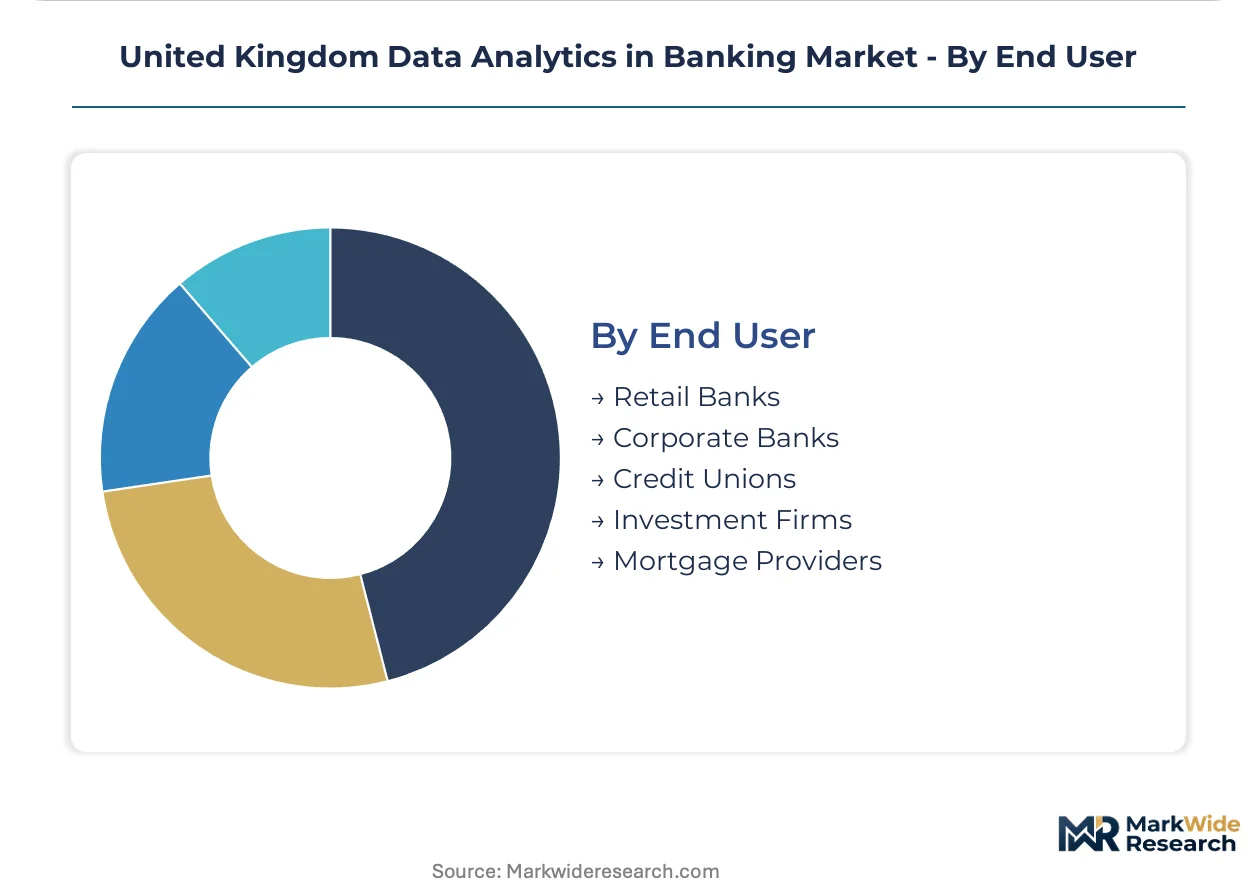
End User:
Institutional type determines analytics sophistication, procurement scale, and regulatory exposure across the UK banking hierarchy.
- Retail Banks:Mass-market deposit and lending institutions deploy customer analytics at scale across millions of accounts. High street networks prioritize fraud detection and digital channel optimization over complex risk modeling.
- Corporate Banks:Transaction banking and working capital providers apply analytics to supply chain finance and trade credit decisions. Relationship managers in London leverage predictive tools for cross-selling treasury services.
- Credit Unions:Member-owned cooperatives adopt cloud-native solutions to circumvent capital constraints on infrastructure investment. Community-focused institutions emphasize member retention analytics over acquisition targeting.
- Investment Firms:Asset managers and broker-dealers demand real-time analytics for execution and research functions. FCA consumer duty rules impose steepest explanation requirements on discretionary portfolio management.
- Mortgage Providers:Specialized lenders concentrate analytics on property valuation automation and affordability stress-testing. Building societies apply regional housing market models to geographic concentration risk.
Retail Banks deploy the broadest analytics portfolios; Investment Firms are climbing the fastest on AI intensity per employee.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data science talent and regulatory infrastructure concentrate in London and the Southeast, with secondary clusters emerging in Edinburgh and Manchester as cost pressures reshape investment geography.
London and the Southeast
Clearing banks and investment firms drive demand for real-time fraud detection and stress-testing platforms. The Financial Conduct Authority's consumer duty rules mandate explainable AI documentation for algorithmic credit decisions. Canary Wharf and the Square Mile host centralized data science centers where major institutions deploy cloud-native analytics pipelines.
Scotland
Edinburgh's fund management ecosystem generates specialized demand for investment analysis and portfolio risk modeling. The Prudential Regulation Authority's model risk guidelines apply uniformly across UK jurisdictions, shaping vendor selection. Scottish financial centers attract satellite analytics operations seeking talent outside London's premium labor market.
North England
Manchester and Leeds offer lower operational costs for mid-tier banks building secondary data science capabilities. The UK Data Protection Act governs customer data usage across all English regions, influencing hybrid cloud architectures. Building societies in Manchester pilot edge analytics for in-branch credit pre-qualification.
Midlands
Birmingham's corporate banking presence supports analytics investment in supply chain finance and trade credit decisions. GDPR compliance requirements shape cross-border data transfer protocols for multinational banks with Midlands operations. The region's manufacturing heritage informs operational analytics targeting cost-to-income optimization.
Wales and Northern Ireland
Cardiff and Belfast develop specialized compliance analytics capabilities serving UK-wide regulatory reporting needs. The Competition and Markets Authority's open banking mandates create opportunities for consented data monetization across these smaller markets. Regional universities supply quantitative talent to distributed analytics teams.
United Kingdom Data Analytics in Banking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk modeling and regulatory reporting niches. The vendor landscape organizes around three archetypes: hyperscale cloud providers with financial services certifications, established enterprise software vendors with legacy banking relationships, and emerging fintech specialists in open banking and real-time analytics. Consolidation pressures favor platform breadth over point solutions, while regulatory complexity sustains demand for specialized compliance modules.
Among US-based technology conglomerates, IBM and Microsoft Corporation occupy positions anchoring enterprise-grade deployments, while SAS Institute Inc. exemplifies the specialized risk analytics tier. These three entities represent distinct competitive vectors: IBM leverages longstanding clearing bank relationships, Microsoft accelerates cloud-native adoption through Azure integrations, and SAS competes on regulatory templates aligned with Prudential Regulation Authority requirements. Their collective presence shapes procurement criteria across UK retail and investment banking segments.
| Leading Market Players |
|---|
| IBM |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| Finastra International Limited |
| Amazon Web Services, Inc. |
| TIBCO Software Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in London's cloud-native analytics talent pool drives both wage inflation for specialized data scientists and vendor pricing power for platforms with Financial Conduct Authority certification. This utilization squeeze forces UK banks toward longer contract terms and bundled service agreements that lock in scarce implementation capacity.
Pricing Analysis
The Financial Conduct Authority's consumer duty rules dictate the pricing tier structure across explainable AI modules, with premium tiers commanding spreads for built-in audit trails and automated documentation. Pricing stratifies across enterprise-grade, mid-market, and challenger-bank tiers based on model complexity and regulatory validation depth. Cost compression in the mid-market tier is intensifying because open-source Python frameworks reduce proprietary platform dependency. Challenger banks exhibit highest price sensitivity due to capital constraints, while tier-one clearing institutions prioritize compliance assurance over unit cost.
Supply Chain Analysis
Accenture, Deloitte, and specialized fintech systems integrators hold dominant implementation capacity for UK banking analytics deployments. Geographic supply concentration centers on the United Kingdom for regulatory domain expertise, Ireland for EU-facing data residency compliance, and India for model development and testing scale. Raw material dependencies include cloud compute credits from hyperscalers, open-source machine learning libraries, and proprietary risk data feeds from credit bureaus. Single-source vulnerability runs through the concentrated pool of Prudential Regulation Authority-accredited model validators. Distribution runs through direct vendor relationships with tier-one banks and partner-channel resale to mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK banking analytics market sits at a platform-economics inflection where Open Banking API interoperability is collapsing data silos and redistributing value toward real-time analytics orchestrators.
For Market Incumbents: Pre-empt challenger-bank encroachment by acquiring specialist explainable AI boutiques before regulatory validation requirements harden. Defensive consolidation around cloud-native core systems reduces legacy mainframe drag that traps functionality in batch processes. Vertical integration into proprietary risk data assets creates switching costs that offset price pressure from open-source alternatives. For New Entrants and Emerging Players: Establish a beachhead in Edinburgh's fund management ecosystem where investment analysis tooling lags retail banking sophistication. White-space targets include automated Prudential Regulation Authority reporting templates and Scottish regulatory technology modules. A regulatory-co-design go-to-market angle accelerates credibility with compliance-constrained asset managers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with embedded model risk management workflows. Long-term viability over a five-to-ten-year window favors vendors with Financial Conduct Authority pre-certification and existing tier-one bank reference architectures. The signal to watch as inflection indicator is mid-tier bank consolidation velocity, which concentrates procurement power and favors platform breadth over point solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS financial services certifications accelerate cloud-native deployment timelines for UK retail banks. |
| Acquisition of Specialist Firm | Explainable AI boutiques with SHAP and LIME production expertise fill regulatory documentation gaps in incumbent portfolios. |
| Strategic Partnership | Open Banking API consortia create data-sharing revenue streams under Competition and Markets Authority mandates. |
| Geographic Expansion | Manchester and Edinburgh satellite centers capture cost-advantaged talent outside London's premium labor market. |
| Product Launch | Real-time fraud detection pipelines integrating with Faster Payments infrastructure compress detection latency below settlement windows. |
Research Methodology
A standing panel of chief data officers, model risk managers, regulatory technology leads, and cloud platform procurement officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against Prudential Regulation Authority policy statements, Financial Conduct Authority enforcement notices, Bank of England stress-testing documentation, and hyperscaler financial services certification disclosures. Bottom-up deployment estimates triangulated against top-down market sizing derived from UK banking IT expenditure benchmarks.
Scenario bracketing anchored the analytical framework across the projection horizon, with growth trajectories stress-tested against regulatory timeline acceleration and cloud adoption inflection points. Segmentation dimensions modeled include deployment architecture, solution capability, institutional use case, and geographic adoption pattern. CAGRs were derived from fitted growth curves calibrated to historical technology adoption cycles in UK financial services. Forecast inputs incorporated Open Banking transaction volume growth and consumer duty compliance deadline effects.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and UK-EU regulatory equivalence negotiations would shift the trajectory. Forecasts reflect documented assumptions about cloud migration velocity and talent supply elasticity. Quarterly review of Prudential Regulation Authority consultation papers and Financial Conduct Authority enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Neo and Challenger Bank Market
Banking
Machine Learning in Banking Market
Banking
Germany Neobanking Market
Banking
Retail Banking Market
Banking
Core Banking Solutions Market
Banking
US Commercial Banking Market
Banking
US Investment Banking Market
Banking
Armenia Banking Market
Banking
North America Machine Learning in Banking Market
Banking
API Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Global Big Data Analytics in Banking Market
Banking
ATM Market
Banking
China Data Analytics in Banking Market
Banking
Embedded Banking Market
Banking
Video Banking Service Market