
 Financial Analytics Market | 2026-2036
Financial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Analytics Market Analysis
Data science talent scarcity is reorganizing vendor competitive dynamics across the Financial Analytics Market. SAS Institute leverages decades of statistical computing heritage to anchor its position in risk modeling workflows. Microsoft Corporation competes through Azure-native integration that extends analytics into enterprise productivity stacks. IBM Corporation differentiates via Watson-powered natural language interfaces that reduce technical barriers for front-office users.
Financial analytics encompasses the systematic extraction, transformation, and modeling of structured and unstructured financial data to generate actionable intelligence for decision-making, valuation, and risk quantification, typically operating across sub-second latency thresholds for real-time trading applications and batch cycles for regulatory reporting. Cloud-based deployment is capturing the fastest expansion as institutions retire legacy mainframe infrastructure, while compliance analytics commands premium pricing due to mandatory SEC, FCA, and MAS reporting obligations that require audit-grade data lineage. Risk management solutions maintain the largest installed base among asset managers facing Basel III and FRTB capital adequacy mandates.
SEC disclosure rules in the United States, FCA conduct standards in the United Kingdom, and MAS technology risk management guidelines in Singapore collectively elevate data governance requirements that directly shape product roadmaps and procurement criteria. GDPR data residency provisions in Europe and equivalent privacy frameworks elsewhere fragment cloud architecture strategies, forcing multi-region deployment investments. Stakeholders must evaluate whether their analytics infrastructure can absorb forthcoming climate risk disclosure mandates without parallel system duplication.
Market Dynamics
Cloud migration is compressing infrastructure refresh cycles across financial institutions, forcing vendors to rearchitect around API-first delivery models that displace monolithic on-premise deployments.
Growth Catalysts
- Basel III and FRTB capital adequacy mandates:Asset managers in the United States, United Kingdom, and Singapore face binding regulatory deadlines that necessitate real-time risk quantification infrastructure.
- Investment banking adoption of real-time risk dashboards:Trading desks require sub-second latency analytics to monitor counterparty exposures and market volatility during execution windows.
- SEC, FCA, and MAS reporting obligations:Mandatory audit-grade data lineage requirements create captive demand for compliance analytics modules with embedded governance controls.
Market Restraints
- Data science talent scarcity:Specialized expertise in statistical computing and quantitative modeling commands premium compensation that inflates total cost of ownership for analytics programs.
- GDPR data residency fragmentation:European privacy provisions force multi-region cloud deployments that duplicate infrastructure investments and complicate vendor consolidation strategies.
- Legacy mainframe dependency:Core banking systems running COBOL-based batch processes resist API integration, creating middleware complexity that extends implementation timelines.
Strategic Opportunities
- Climate risk disclosure mandates:Emerging TCFD-aligned reporting requirements in the European Union and United Kingdom create white space for scenario modeling and stress testing modules.
- Natural language interface convergence:Front-office adoption of conversational analytics that bridge Watson-style query interfaces with Excel-native workflows reduces training barriers for non-technical users.
- Singapore's MAS technology risk management guidelines:The city-state's regulatory clarity on cloud governance creates a testbed environment for vendor proof-of-concept deployments before global rollout.
Industry Challenges
- Quantitative model validation bottlenecks:Independent model risk management teams face backlog pressures as algorithmic trading strategies proliferate across asset classes.
- Cross-border data transfer friction:Divergent national privacy frameworks complicate centralized analytics architectures for multinational banks operating across United States, European, and Asia-Pacific jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Analytics Market |
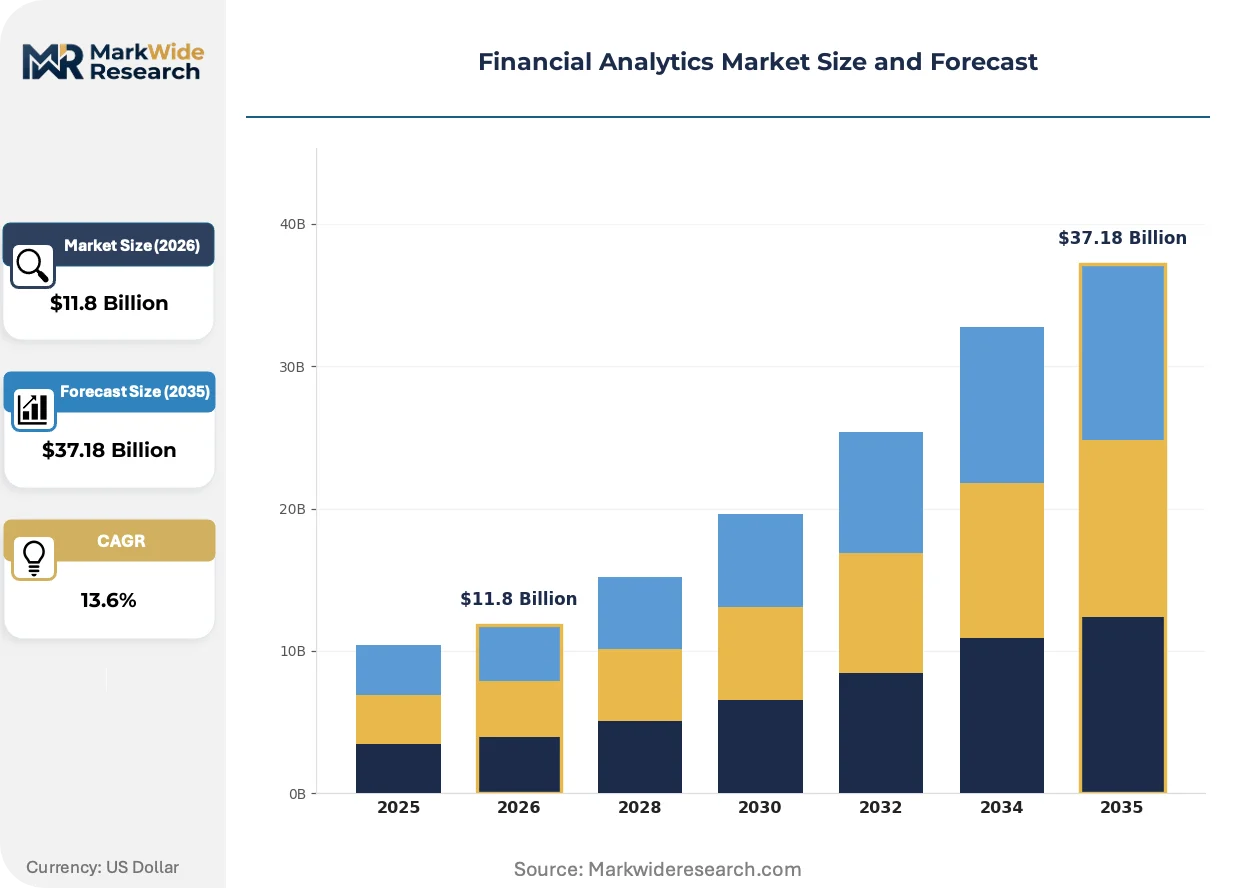
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $37.18 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Investment Banks, Asset Managers, Hedge Funds, Insurance Companies Solution: Data Visualization, Risk Management, Credit Scoring, Compliance Analytics Feature: Predictive Analytics, Real-Time Reporting, Risk Assessment, Budgeting Tools |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Microsoft Corporation, SAS Institute, Tableau Software, QlikTech International AB, Alteryx, S&P Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Analytics Market Emerging Trajectories
API-first architectures are mainstreaming modular analytics consumption that fragments traditional suite-based procurement, while embedded artificial intelligence compresses the technical barrier between data engineers and business users.
Real-time stream processing infrastructure is displacing batch-oriented data warehouses in trading applications. Hedge funds and market makers are adopting Apache Kafka and Flink-based pipelines to ingest tick-level market data with millisecond latency. This architecture is displacing overnight ETL workflows that previously governed intraday risk calculations.
The European Union's CSRD sustainability reporting standards mandate granular emissions disclosure across portfolio holdings. Asset managers must now source Scope 3 supply chain data and model transition risk scenarios. European-domiciled funds are responding by embedding climate analytics directly into portfolio construction workflows rather than treating disclosure as a downstream compliance exercise.
Front-office users are bypassing centralized IT procurement to acquire departmental analytics subscriptions. Business unit leaders in United States investment banks are expensing cloud-native visualization tools through operational budgets, circumventing enterprise vendor negotiations. This shadow procurement pattern concentrates in equity research and corporate finance divisions where analytical autonomy carries revenue attribution.
Financial Analytics Market Segmentation
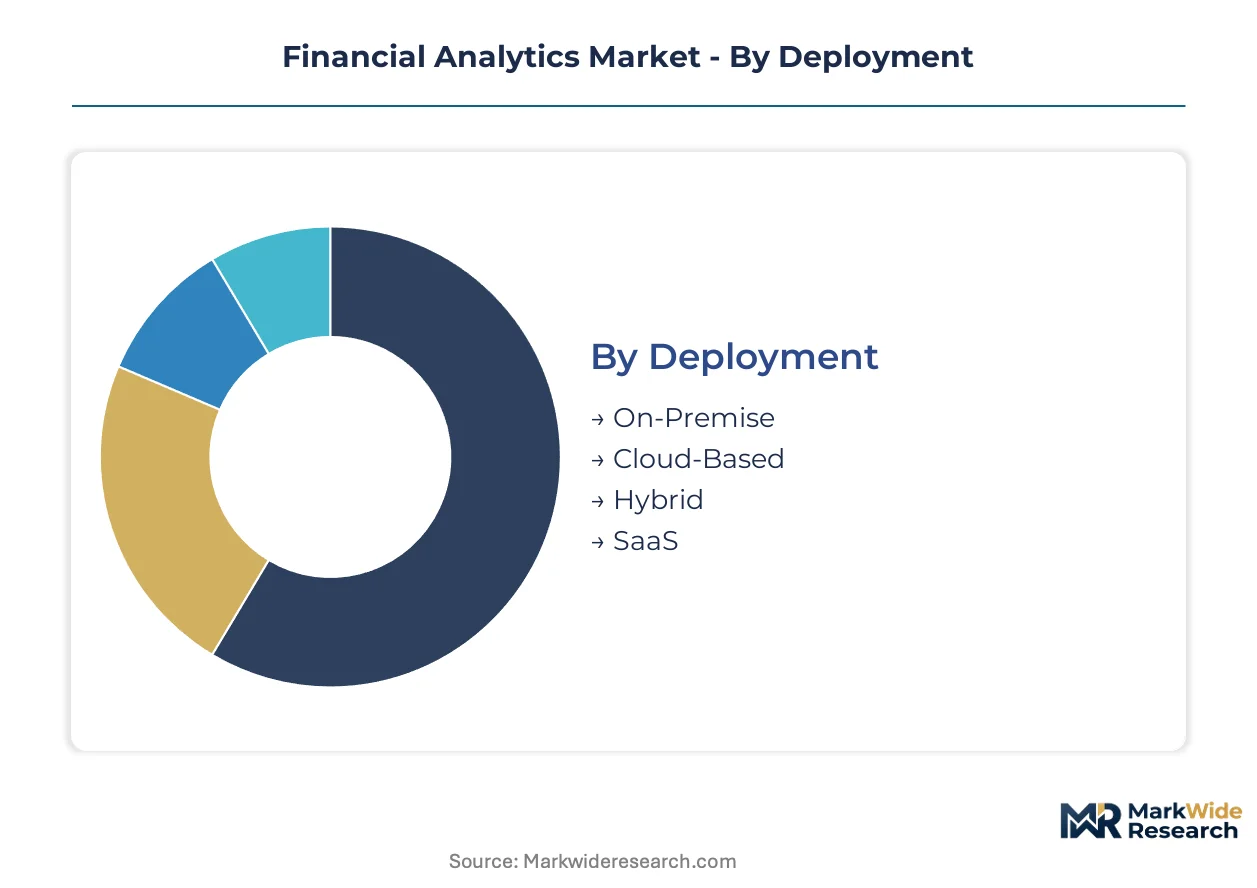
Financial analytics procurement splits across infrastructure topology, institutional user type, functional capability, and analytical depth. These dimensions determine integration complexity, regulatory compliance scope, and total cost of ownership for deployment decisions.
Deployment:
Cloud-based configurations dominate new procurement in Singapore and the United Kingdom, while United States institutions maintain substantial on-premise footprints due to legacy system entrenchment.
- On-Premise:Hardware-resident installations within institutional data centers provide direct control over latency-sensitive trading infrastructure. Investment banks in the United States retain these deployments for co-located algorithmic execution systems where physical proximity to exchanges minimizes round-trip delay.
- Cloud-Based:Scalable compute resources delivered via public or private cloud environments eliminate capital expenditure cycles. Asset managers facing FRTB reporting deadlines in the United Kingdom are migrating risk calculation workloads to cloud-native architectures to compress implementation timelines.
- Hybrid:Split architectures maintain sensitive data on-premise while bursting computational loads to cloud infrastructure.
- SaaS:Subscription-delivered analytics accessed through web browsers reduce internal IT maintenance burdens.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
End User:
Regulatory intensity varies sharply across user categories, with Basel III and Solvency II mandates creating divergent compliance analytics requirements.
- Investment Banks:Full-service institutions requiring integrated trading, risk, and regulatory reporting capabilities across multiple asset classes. Trading desks at United States bulge-bracket firms are deploying real-time risk dashboards to monitor counterparty exposures during execution windows.
- Asset Managers:Institutional portfolio managers focused on long-only and alternative strategies with heavy regulatory reporting obligations. United Kingdom fund managers are embedding climate risk analytics into portfolio construction workflows ahead of TCFD-aligned disclosure mandates.
- Hedge Funds:Alternative investment vehicles prioritizing alpha generation through quantitative strategies.
- Insurance Companies:Risk-bearing entities with actuarial modeling and solvency monitoring requirements.
Investment Banks command the established base. The steepest expansion runs through Asset Managers.
Solution:
Pricing power concentrates in modules with embedded regulatory logic, where mandatory reporting obligations create captive demand.
- Data Visualization:Interactive dashboard and reporting interfaces translating complex datasets into interpretable formats. Front-office users in Singapore are adopting natural language query interfaces that reduce technical barriers for non-quantitative staff.
- Risk Management:Quantitative infrastructure for market, credit, and operational risk measurement. Basel III and FRTB capital adequacy mandates in the United States are forcing asset managers to upgrade from overnight batch calculations to intraday risk monitoring.
- Credit Scoring:Statistical models assessing borrower default probability and loss given default.
- Compliance Analytics:Audit-grade data lineage and reporting modules satisfying SEC, FCA, and MAS obligations.
Risk Management commands the established base. Compliance Analytics shows the steepest expansion trajectory.
Feature:
Latency requirements separate front-office trading applications from middle-office regulatory functions.
- Predictive Analytics:Machine learning models forecasting price movements, default probabilities, and portfolio outcomes. Hedge funds in the United States are deploying these capabilities for alternative data integration and signal extraction from unstructured sources.
- Real-Time Reporting:Sub-second latency dashboards streaming live position and risk metrics. Market makers in Singapore require millisecond-level updates to monitor counterparty exposures during volatile trading sessions.
- Risk Assessment:Quantitative evaluation of portfolio vulnerabilities across market regimes.
- Budgeting Tools:Financial planning and forecasting modules for corporate treasury functions.
Risk Assessment commands the established base. Real-Time Reporting gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial analytics consumption patterns diverge sharply across major economies. United States institutions prioritize real-time trading infrastructure, while European and Asia-Pacific markets emphasize regulatory compliance and cloud-native architectures respectively.
United States
Investment banks and hedge funds drive demand for sub-second latency risk dashboards and alternative data integration. SEC disclosure rules and Basel III capital adequacy mandates force continuous infrastructure upgrades. New York's financial district hosts concentrated deployments of co-located algorithmic execution systems alongside cloud migration initiatives.
United Kingdom
Asset managers dominate procurement as FRTB reporting deadlines approach, accelerating cloud-based risk calculation workloads. FCA conduct standards and emerging TCFD-aligned climate disclosure requirements reshape product roadmaps. London's City and Canary Wharf clusters witness embedded climate analytics integration into portfolio construction workflows.
Singapore
The city-state serves as Asia-Pacific's testbed for vendor proof-of-concept deployments before global rollout. MAS technology risk management guidelines provide regulatory clarity on cloud governance that attracts multinational banking operations. Marina Bay's financial district concentrates real-time reporting infrastructure serving cross-border trading activities.
Germany
Universal banks and insurance conglomerates sustain demand for integrated risk and compliance analytics. GDPR data residency provisions force multi-region cloud architectures that complicate vendor consolidation. Frankfurt's banking quarter anchors continental Europe's largest concentration of Basel III-compliant risk infrastructure.
Japan
Securities houses and regional banks modernize legacy mainframe-dependent systems through phased API-first migrations. METI industrial policy and domestic data sovereignty requirements influence procurement criteria. Tokyo's Otemachi financial district hosts hybrid deployments balancing on-premise latency sensitivity with cloud scalability.
Financial Analytics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Financial Analytics Market. The upper tier combines cloud infrastructure, productivity software, and embedded artificial intelligence capabilities. The specialist tier concentrates in statistical computing heritage, data visualization, and regulatory compliance modules. Competitive dynamics center on API-first architecture transitions and vertical integration into upstream data provision.
Within the integrated platform tier, Microsoft Corporation and IBM Corporation exemplify contrasting strategic approaches to enterprise analytics embedding. Microsoft leverages Azure-native integration extending analytics into productivity stacks, while IBM anchors its position through Watson-powered natural language interfaces. SAS Institute occupies a distinctive position representing decades of statistical computing heritage in risk modeling workflows. These three players collectively illustrate how vendor competitive dynamics reorganize around data science talent scarcity and cloud migration imperatives.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| SAS Institute |
| Tableau Software |
| QlikTech International AB |
| Alteryx |
| S&P Global |
| Others |
Supply Flow & Price Mechanics
Cloud-native API architectures displacing legacy on-premise installations simultaneously redistribute vendor pricing power toward subscription-based SaaS tiers and compress procurement cycles across financial institutions migrating from capital-intensive hardware refresh programs.
Pricing Analysis
Contract structures in financial analytics split between multi-year enterprise licensing agreements and consumption-based SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by compliance certification depth and latency performance guarantees. Pricing pressure stems from open-source alternatives commoditizing basic visualization capabilities. Asset managers exhibit highest price sensitivity due to fee compression in passive investment products, while investment banks absorb premium tiers for sub-second risk infrastructure.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for financial analytics workloads, while India and Poland concentrate software engineering talent for platform development. Proprietary risk calculation engines draw from open-source statistical libraries and commercial data feeds from exchanges. Single-source vulnerability concentrates in specialized quantitative model validation services. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Financial analytics sits in early-cycle expansion as Basel III and FRTB implementation deadlines force replacement of overnight batch risk systems with real-time streaming architectures.
For Market Incumbents: Shield installed base relationships by embedding climate risk modules ahead of TCFD mandates and deepening API integration with core banking platforms. Cloud-native entrants threaten traditional licensing revenue through consumption-based pricing. Vertical integration into upstream data provision defends margin position. For New Entrants: Differentiate on natural language interfaces that collapse technical barriers for front-office users without quantitative training. White space concentrates in Singapore's MAS-regulated cloud governance testbed and European CSRD-aligned sustainability disclosure tools. Partner with regional system integrators for proof-of-concept deployment velocity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed statistical computing specialists possessing decades of risk modeling heritage but lagging cloud migration roadmaps. Five-to-ten year viability hinges on successful API-first rearchitecture. Watch for inflection in hedge fund adoption of alternative data integration capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Displaces monolithic deployments at United States investment banks facing latency requirements. |
| Climate Risk Module Development | Captures TCFD-aligned disclosure demand from United Kingdom asset managers. |
| Natural Language Interface Integration | Reduces training barriers for Singapore front-office users without statistical computing backgrounds. |
| Hyperscaler Marketplace Listing | Accelerates procurement velocity through operational budget channels bypassing IT negotiations. |
| Quantitative Model Validation Service | Addresses backlog pressures at independent model risk management teams in algorithmic trading. |
Methodological Framework
The analysis maps risk management solutions, compliance analytics modules, data visualization platforms, and real-time reporting infrastructure, each validated through chief risk officers, quantitative analysts, regulatory technology leads, and cloud procurement officers. Primary fieldwork combined structured interviews with secondary validation against SEC disclosure filings, MAS technology risk guidelines, FCA conduct standards, and Basel Committee regulatory texts. Bottom-up deployment estimates triangulated against top-down vendor revenue analysis.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler financial services vertical disclosures and regulatory technology spending surveys. Segmentation modeling spanned deployment topology, end-user institution type, functional solution capability, and analytical depth across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and regulatory deadline impacts. Forecast inputs incorporated FRTB implementation timelines and cloud migration velocity indices.
Material uncertainties — regulatory delay, data sovereignty fragmentation, and talent scarcity escalation — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance mandate adherence and infrastructure refresh cycles. Recalibration cycles align with material shifts in central bank capital requirement announcements and major data breach disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
France AI in Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
Japan AI in Fintech Market
FinTech
Global Fundraising Software Market
FinTech
Micro-Investing Platform Market
FinTech
Vietnam Fintech Market
FinTech
Germany Fintech Market
FinTech
Financial Audit Software Market
FinTech
Singapore Fintech Market
FinTech
MENA Fintech Market
FinTech
Europe Embedded Finance Market
FinTech
United States Fintech Market
FinTech
Stock Trading App Market
FinTech
Financial Fraud Detection Software Market
FinTech
Smart Advisors Market
FinTech
Fintech Cloud Market